
 Nanotubes Market | 2026-2036
Nanotubes Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotubes Market Outlook
The capital-intensity divergence between plasma-enhanced chemical vapor deposition specialists and bulk chemical producers is collapsing as reactor throughput improvements compress unit economics. OCSiAl leverages proprietary synthesis technology to sustain kiloton-scale single-wall nanotube output from European facilities. Jiangsu Cnano Technology Co., Ltd anchors China's domestic supply chain through integrated purification and dispersion capabilities. Cabot Corporation competes in conductive additive formulations for lithium-ion battery electrodes.
Nanotubes are hollow cylindrical nanostructures composed of rolled graphene sheets or analogous layered materials, typically measuring one to several nanometers in diameter and up to millimeters in length, with aspect ratios exceeding 1000:1 enabling exceptional tensile strength and electrical conductivity. Carbon nanotubes dominate commercial volume due to established catalyst-feedstock optimization, while boron nitride nanotubes command premium positioning in thermal management applications where electrical insulation remains mandatory. The energy storage application segment attracts the fastest capacity expansion as battery manufacturers specify conductive slurries, whereas biomedical applications face elongated regulatory validation timelines despite promising drug-delivery vectors.
The EPA regulates nanotube manufacturing under the Toxic Substances Control Act, while REACH mandates registration dossiers for imported carbon nanotubes into the European Union, and China's SAMR enforces GB standards for occupational exposure limits in nanomaterial production facilities. These frameworks elevate compliance costs for smaller producers while accelerating consolidation around certified manufacturing bases. Stakeholders must monitor evolving toxicity classifications and alignment between regional purity standards to preserve cross-border market access.
Market Dynamics
Plasma-enhanced chemical vapor deposition throughput gains are compressing unit economics and collapsing the historical capital-intensity gap between specialty nanotube producers and bulk chemical manufacturers.
Growth Catalysts
- REACH dossier mandates:European Union registration requirements for imported multi-walled carbon nanotubes are consolidating certified supply bases and rewarding producers with pre-validated purity documentation.
- Lithium-ion battery conductive slurry demand:Energy storage manufacturers are specifying nanotube-enhanced electrode formulations to reduce internal resistance and extend cycle life.
- Jiangsu-Sichuan cluster expansion:China's government-backed nanomaterial production hubs are scaling domestic purification and dispersion capabilities to reduce import dependency.
Market Restraints
- Iron-molybdenum catalyst cost volatility:Feedstock price swings for transition metal catalysts directly impact single-wall nanotube production economics at commercial scale.
- Biomedical validation timelines:FDA and EMA toxicity classification delays for drug-delivery vector applications extend commercialization horizons beyond typical investor patience.
- Graphene conductive ink substitution:Two-dimensional carbon alternatives are capturing share in flexible electronics applications where sheet resistance requirements are less stringent.
Strategic Opportunities
- Boron nitride thermal interface materials:Electrical insulation mandates in aerospace power electronics are opening premium positioning for non-conductive nanotube variants.
- Direct-to-battery-manufacturer supply contracts:Bypassing traditional chemical distributor networks captures margin and locks in volume commitments from CATL and LG Energy Solution.
- EU Green Deal sustainable production incentives:Carbon footprint reduction mandates favor producers with renewable-powered synthesis facilities and closed-loop catalyst recovery.
Industry Challenges
- Reactor engineering talent scarcity:Plasma physics and high-temperature process control expertise concentrates at a handful of academic centers and incumbent producers.
- Multi-jurisdictional purity standard misalignment:Divergent EPA, REACH, and SAMR toxicity thresholds force redundant testing protocols for cross-border shipments.
- Legacy petrochemical equipment retrofit complexity:Converting fluid catalytic cracking infrastructure to nanotube synthesis requires fundamental reactor redesign rather than modular upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotubes Market |
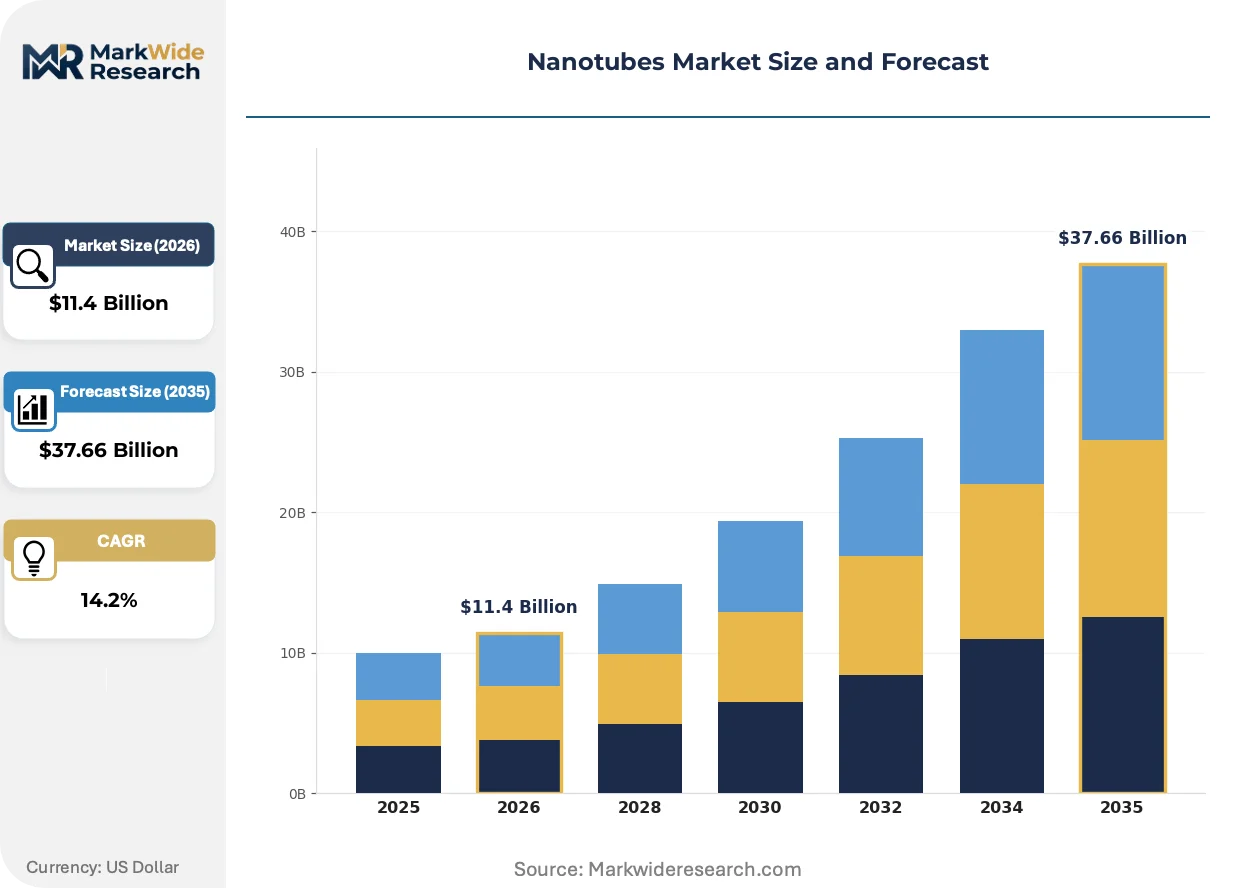
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $37.66 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Nanotubes, Boron Nitride Nanotubes, Metallic Nanotubes, Semiconductor Nanotubes Application: Energy Storage, Composite Materials, Electronics, Biomedical End User: Aerospace, Automotive Components, Electronics Manufacturing, Healthcare Devices Distribution Channel: Direct Sales, Online Retail, Distributors, OEM Partners |
| Companies Covered | LG Chem, Cabot Corporation, Showa Denko K.K., Arkema, Nanocyl SA, OCSiAl, Jiangsu Cnano Technology Co., Ltd, Chengdu Organic Chemicals Co. Ltd., Resonac Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotubes Market Strategic Shifts
Continuous-flow reactor architectures are displacing batch synthesis across commercial nanotube production, enabling real-time quality control and reducing solvent waste volumes. Three developments are restructuring competitive positioning.
Plasma-enhanced floating catalyst synthesis is decomposing the historical throughput ceiling for single-wall nanotube manufacturing. Aerospace composite suppliers in Germany and Japan are qualifying these materials for primary structural applications. The technology is decomposing price premiums that previously separated laboratory-grade from industrial-grade supply tiers.
ECHA's 2023 update to nanomaterial registration guidance is tightening purity disclosure thresholds for multi-walled carbon nanotubes entering European customs territories. Importers must now submit transmission electron microscopy batch records and surface area characterization data. Biomedical device manufacturers with pre-validated supply chains are accelerating procurement to avoid third-quarter clearance bottlenecks.
Battery cell producers are consolidating supplier panels and demanding captive dispersion capability from nanotube vendors. Korean and Chinese cathode manufacturers now specify ready-to-use conductive slurries rather than dry powder deliveries. This specification shift is visible most acutely in Ningbo and Suzhou, where integrated purification-dispersion facilities are securing five-year offtake agreements.
Nanotubes Market Segmentation
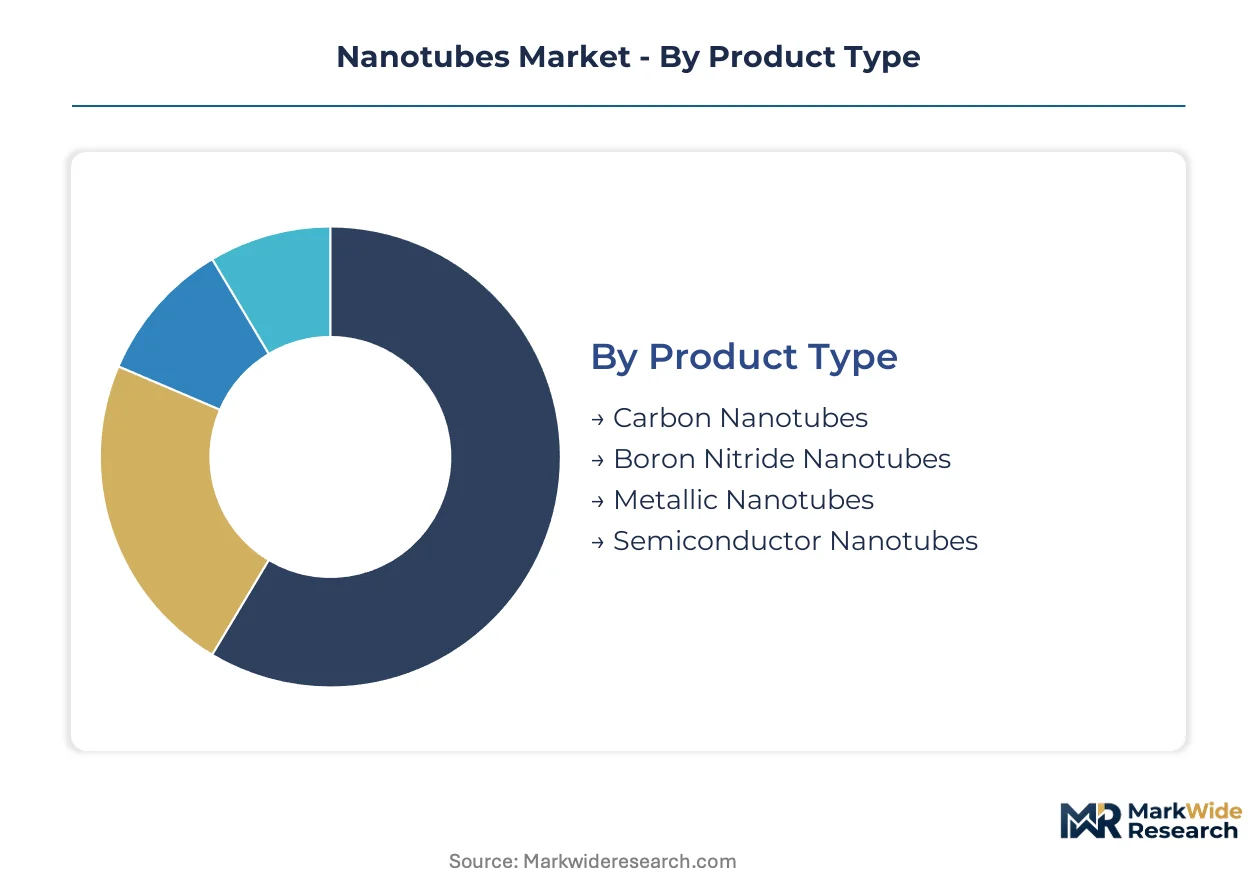
Nanotube procurement patterns diverge sharply across purity grades and synthesis methods, with regulatory thresholds in the European Union, United States, and China fragmenting supplier qualification pathways. Segmentation clarity enables buyers to align specification requirements with validated manufacturing bases and accelerate time-to-qualification for critical applications.
Product Type:
REACH dossier mandates and EPA Toxic Substances Control Act oversight create divergent compliance burdens across nanotube chemistries, concentrating procurement around producers with pre-validated registration documentation.
- Carbon Nanotubes:Rolled graphene cylinders with diameters of one to several nanometers and aspect ratios exceeding 1000:1 deliver exceptional tensile strength and electrical conductivity. Aerospace manufacturers in Germany and Japan are qualifying these materials for primary structural composites as plasma-enhanced floating catalyst synthesis decomposes historical throughput ceilings. Established volume favors carbon nanotubes; emerging adoption favors boron nitride variants.
- Boron Nitride Nanotubes:Hexagonal boron nitride layers arranged in cylindrical geometry provide thermal conductivity comparable to carbon analogs with mandatory electrical insulation. Aerospace power electronics suppliers specify these materials for thermal interface applications where conductivity would short-circuit sensitive components.
- Metallic Nanotubes:Transition metal chalcogenide structures serve niche catalytic and sensing applications with limited commercial scale.
- Semiconductor Nanotubes:Bandgap-engineered variants enable field-effect transistor channels in experimental flexible electronics prototypes.
Cost tier separation widens as single-wall carbon nanotube synthesis commands premium positioning against multi-wall alternatives.
Application:
Specification shifts from dry powder to ready-to-use conductive slurries are restructuring procurement relationships between nanotube vendors and downstream manufacturers.
- Energy Storage:Conductive additive formulations for lithium-ion battery electrodes reduce internal resistance and extend cycle life through percolation network optimization. Korean and Chinese cathode manufacturers in Ningbo and Suzhou now mandate captive dispersion capability from suppliers, securing five-year offtake agreements with integrated purification-dispersion facilities. Battery-grade specifications are climbing the fastest.
- Composite Materials:Structural reinforcement in polymer matrices enables weight reduction for aerospace and automotive components without sacrificing mechanical load-bearing capacity. German aerospace composite suppliers are qualifying plasma-enhanced materials for primary structural applications previously reserved for laboratory-grade supply tiers.
- Electronics:Transparent conductive films and interconnect materials face substitution pressure from graphene conductive inks in flexible applications with less stringent sheet resistance requirements.
- Biomedical:Drug-delivery vectors and biosensing substrates face elongated FDA and EMA toxicity classification timelines despite promising pharmacokinetic profiles.
Volume concentration favors energy storage; margin expansion favors biomedical applications contingent on regulatory clearance.
End User:
Customer technical sophistication determines specification granularity, with tier-one aerospace and battery manufacturers demanding batch-level characterization data unavailable to general industrial buyers.
- Aerospace:Primary structural applications require transmission electron microscopy batch records and surface area characterization data meeting ECHA's tightened purity disclosure thresholds. Pre-validated supply chains are accelerating procurement to avoid customs clearance bottlenecks.
- Automotive Components:Lightweight structural parts and thermal management systems specify nanotube-reinforced polymers for electric vehicle battery enclosures and powertrain components.
- Electronics Manufacturing:Flexible display and semiconductor packaging applications drive demand for controlled chirality distributions in single-wall variants.
- Healthcare Devices:Implantable and diagnostic applications face SAMR occupational exposure limit enforcement in Chinese manufacturing facilities and redundant testing protocols for cross-border shipments.
Procurement scale favors automotive; technical barrier height favors aerospace qualification pathways.
Distribution Channel:
Margin capture incentives are compressing traditional chemical distributor networks as battery cell producers consolidate supplier panels and demand direct contractual relationships.
- Direct Sales:Long-term offtake agreements with CATL and LG Energy Solution bypass distributor markups and lock in volume commitments for qualified producers with integrated dispersion capabilities.
- Distributors:Regional chemical distributors serve fragmented industrial and research laboratory demand with smaller lot sizes and higher per-kilogram service premiums.
- Online Retail:E-commerce platforms facilitate research-grade sample procurement and small-volume pilot testing for early-stage product development.
- OEM Partners:Equipment manufacturers embed nanotube-enhanced components in subsystem deliveries to downstream integrators.
Relationship stickiness favors direct sales; geographic reach favors distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Japan commands premium positioning for aerospace-grade single-wall nanotubes, while Chinese producers in Jiangsu and Sichuan compete on scale and integrated dispersion capability. This asymmetry shapes procurement patterns across battery, electronics, and composite applications.
United States
Aerospace manufacturers in California and Washington specify carbon nanotube composites for lightweight structural components in next-generation aircraft programs. EPA oversight under the Toxic Substances Control Act tightens purity standards for biomedical and electronics applications, elevating compliance costs for smaller importers. Texas-based energy storage operations are scaling conductive slurry procurement as domestic battery cell production expands.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg integrate nanotube-reinforced polymers for electric vehicle battery enclosures and powertrain thermal management. ECHA's 2023 nanomaterial registration guidance mandates transmission electron microscopy batch records and surface area characterization data for multi-walled carbon nanotube imports. The Stuttgart aerospace cluster qualifies plasma-enhanced materials for primary structural applications previously reserved for laboratory-grade supply tiers.
China
Cathode manufacturers in Ningbo and Suzhou consolidate supplier panels and demand captive dispersion capability from nanotube vendors, securing five-year offtake agreements. SAMR enforces GB standards for occupational exposure limits in nanomaterial production facilities across Jiangsu and Sichuan provinces. Government-backed nanomaterial clusters in these provinces scale domestic purification and dispersion capabilities to reduce import dependency for battery-grade supply.
Japan
Electronics manufacturers in Tokyo and Osaka drive demand for controlled chirality distributions in single-wall variants for flexible display and semiconductor packaging applications. METI industrial policy supports domestic synthesis technology development to preserve supply chain autonomy. The Nagoya aerospace corridor evaluates boron nitride nanotubes for thermal interface materials in power electronics where electrical insulation remains mandatory.
South Korea
Battery cell producers at CATL and LG Energy Solution operations specify ready-to-use conductive slurries rather than dry powder deliveries, compressing traditional chemical distributor networks. MFDS alignment with international toxicity classification frameworks streamlines cross-border shipment protocols for biomedical device applications. The Gyeonggi-do battery materials cluster anchors integrated purification-dispersion facilities serving Korean and Chinese cathode manufacturers.
Nanotubes Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Plasma-enhanced chemical vapor deposition specialists command premium positioning in aerospace and biomedical segments, while bulk chemical producers compete on volume in battery conductive additives. The market consolidates around three strategic archetypes: synthesis technology owners, integrated purification-dispersion operators, and conductive formulation specialists. Dominant competitive moves include reactor throughput expansion and direct-to-battery-manufacturer supply contract negotiations.
Within the synthesis technology tier, OCSiAl and Showa Denko K.K. represent European and Japanese technology leadership archetypes respectively. Among China-based integrated operators, Jiangsu Cnano Technology Co., Ltd. and Chengdu Organic Chemicals Co. Ltd. exemplify the domestic supply chain consolidation pattern. Cabot Corporation occupies a position bridging specialty chemicals and conductive additive formulations. These players anchor the competitive landscape without exhaustive enumeration of strategic actions or financial positions.
| Leading Market Players |
|---|
| LG Chem |
| Cabot Corporation |
| Showa Denko K.K. |
| Arkema |
| Nanocyl SA |
| OCSiAl |
| Jiangsu Cnano Technology Co., Ltd |
| Chengdu Organic Chemicals Co. Ltd. |
| Resonac Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day purification qualification windows for battery-grade nanotubes concentrate procurement leverage with Jiangsu and Sichuan producers who maintain strategic metal catalyst stockpiles. This inventory posture lets integrated operators command premium positioning against spot-market buyers facing iron-molybdenum price volatility.
Pricing Analysis
Configured-to-order dispersion slurries for Korean battery manufacturers command spreads exceeding standard dry-powder deliveries by substantial margins. Contract-based long-term offtake agreements dominate volume transactions, with price differentiation resting on REACH certification tier and captive dispersion capability. Cost compression in multi-wall commodity grades is intensifying because Chinese cluster expansion adds purification capacity faster than demand absorption. Tier-one aerospace buyers show least price sensitivity due to ECHA-mandated batch documentation requirements.
Supply Chain Analysis
Strategic stockpiling of transition metal catalysts prevails among single-wall specialists, while battery-grade producers favor just-in-time ferrocene deliveries from domestic Chinese refiners. Geographic supply concentration centers on China, Germany, and Japan, with raw material dependencies spanning iron-molybdenum catalysts, acetylene feedstock, and high-purity solvents. Single-source vulnerability concentrates in European plasma-enhanced reactor engineering talent pools. Distribution runs through direct sales channels for qualified battery manufacturers and regional chemical distributors for research-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nanotube procurement platforms are consolidating around battery-manufacturer specification standards, creating interoperability lock-in effects similar to semiconductor process node transitions. This platform dynamic favors early movers who establish qualified dispersion formats before industry-wide standardization.
For Market Incumbents: Consolidate reactor throughput gains through backward integration into catalyst recovery systems, locking in cost advantage against emerging Chinese cluster competitors. Secure ECHA pre-registration dossiers before purity disclosure thresholds tighten further, defending margin position against importers facing redundant testing protocols. Prioritize captive dispersion capability investments in Ningbo and Suzhou to match Korean cathode manufacturer specifications.
For New Entrants and Emerging Players: Differentiate on boron nitride thermal interface materials for aerospace power electronics, where electrical insulation mandates create protected premium positioning unavailable to carbon nanotube competitors. Target German automotive OEM thermal management programs with nanotube-reinforced polymer formulations for electric vehicle battery enclosures. Pursue qualification partnerships with Stuttgart-area aerospace composite suppliers as secondary entry path.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-platform play because battery conductive additive specifications are consolidating toward slurry-format interoperability standards that will persist across cell chemistry generations. Acquisition focus should center on integrated purification-dispersion operators with SAMR-compliant Chinese manufacturing bases and pre-validated REACH documentation. Monitor ECHA toxicity classification updates for biomedical applications as signal for margin expansion timing in drug-delivery vector segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Throughput Expansion | Plasma-enhanced floating catalyst advances decompose single-wall production cost premiums for aerospace qualification. |
| Backward Integration into Catalyst Recovery | Closed-loop iron-molybdenum recovery reduces feedstock exposure and locks in unit economics against volatility. |
| Captive Dispersion Capability Investment | Ready-to-use slurry specifications from CATL and LG Energy Solution bypass distributor markups and secure offtake. |
| REACH Pre-Registration Dossier Completion | ECHA's tightened purity disclosure thresholds reward pre-validated producers with customs clearance speed advantage. |
| Boron Nitride Thermal Interface Development | Aerospace power electronics insulation mandates open premium positioning unavailable to conductive carbon variants. |
Study Parameters
Initial hypotheses were tested against primary input from nanotube plant managers, battery cathode procurement leads, aerospace composite engineers, and REACH regulatory consultants, then refined through secondary validation against customs trade data, SEC chemical company filings, ECHA registration databases, and Jiangsu provincial industrial cluster reports. Bottom-up capacity and demand modeling triangulated against top-down market sizing from synthesis technology throughput assumptions.
Variance decomposition across purity grade, application segment, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating reactor utilization rates, qualification timelines, and substitution elasticity parameters. Forecast inputs included battery cell production ramp schedules from Korean and Chinese manufacturers and aerospace composite adoption curves from German and Japanese qualification programs.
Forecasts assume regulatory continuity in EPA TSCA oversight, REACH dossier mandates, and SAMR GB standard enforcement; material policy shifts would require re-modeling around revised toxicity thresholds or import restriction protocols. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Global Carbon Nanomaterials Market