
 Aluminium Oxide Nanoparticles Market | 2026-2036
Aluminium Oxide Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Oxide Nanoparticles Market Intelligence
High-purity alpha-phase specifications above 99.99% is reorganizing the aluminium oxide nanoparticles competitive landscape as buyers in semiconductor and LED substrate applications reject lower-grade material. Evonik Industries AG leverages its precipitation expertise to sustain European supply of electronics-grade powder. Cabot Corporation anchors North American catalyst demand through controlled pore-volume formulations. American Elements competes on catalog breadth, offering both nanopowder and dispersion forms for research institutions and industrial buyers.
Aluminium oxide nanoparticles are crystalline or amorphous aluminium oxide particles with diameters typically between 1 and 100 nanometers, produced via sol-gel synthesis, flame spray pyrolysis, or plasma vaporization, valued for exceptional hardness, thermal stability, and dielectric properties that enable precision polishing, thermal barrier coatings, and ceramic membrane filtration. The amorphous product type dominates volume shipments into catalyst support applications where surface area trumps crystalline perfection, while the single crystalline segment commands premium pricing from sapphire substrate manufacturers seeking minimal defect density. Electronics applications absorb the fastest-growing share of high-purity output as advanced packaging architectures multiply thermal interface material layers per device.
EPA emission standards and OSHA permissible exposure limits govern US manufacturing facility design and worker protection protocols for nanoscale alumina handling, while REACH registration requirements in Europe mandate extensive toxicity dossiers that filter out smaller producers lacking analytical infrastructure. ISO/TS 80004 nanotechnology terminology standards and IEC nanotechnology measurement protocols provide the metrological backbone for cross-border trade and quality arbitration. Stakeholders must monitor evolving regulatory thresholds for nanomaterial classification, as reclassification under stricter substance regimes would force reformulation investments across coating and abrasive product lines.
Market Dynamics
High-purity alpha-phase specifications above 99.99% are compressing margins for commodity-grade producers while concentrating procurement power among semiconductor substrate manufacturers in Germany, Japan, and South Korea. Electronics-grade material now commands pricing multiples that reflect defect-density thresholds rather than tonnage.
Growth Catalysts
- REACH Registration Tiering:ECHA's escalating data requirements for nanomaterial dossiers are filtering out undercapitalized competitors, concentrating supply among analytical-capable producers serving European catalyst and coating sectors.
- Advanced Packaging Architectures:Thermal interface material layer multiplication in 3D chip stacking is accelerating consumption of sub-50nm alumina dispersions for heat dissipation in high-performance computing.
- East Asian Electronics Clusters:Concentrated demand from South Korean and Japanese LED sapphire substrate foundries is pulling premium single-crystalline nanoparticle volumes away from commodity abrasive applications.
Market Restraints
- Aluminum Precursor Volatility:Spikes in aluminum chloride and aluminum nitrate feedstock costs transmit directly to sol-gel production economics, compressing margins for dispersion-grade manufacturers.
- ISO/TS 80004 Metrology Gaps:Inconsistent particle-size measurement protocols across national laboratories create quality arbitration friction that delays cross-border shipments and extends certification timelines.
- Silica Nanoparticle Substitution:Lower-cost fumed silica alternatives are capturing share in polishing slurry applications where absolute hardness requirements permit compositional flexibility.
Strategic Opportunities
- Indian Pharmaceutical Filtration:CDSCO's tightening purity mandates for parenteral drug manufacturing are opening specification windows for high-surface-area amorphous alumina membrane substrates in sterile filtration.
- EU Green Deal Catalyst Mandates:Automotive emissions-control retrofit programs are expanding addressable demand for high-surface-area gamma-phase nanoparticles in diesel oxidation catalyst washcoats.
- Plasma Vaporization-Convergent Synthesis:Integration of plasma torch technology with continuous flow reactors is enabling tailorable particle-size distributions that bridge electronics-grade and catalyst-grade specifications.
Industry Challenges
- Cleanroom Nanohandling Expertise:OSHA-permissible exposure limit compliance requires specialized ventilation engineering and personal protective equipment protocols that strain workforce availability and training bandwidth.
- Multi-Jurisdictional Registration Synchronization:Divergent nanomaterial classification thresholds between EPA, ECHA, and METI regimes force parallel toxicity testing programs that extend product launch timelines by 18-36 months.
- Legacy Coating Formulation Integration:Substituting nanoparticle-enhanced binders into established automotive and aerospace coating lines requires solvent system reformulation and spray equipment recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Oxide Nanoparticles Market |
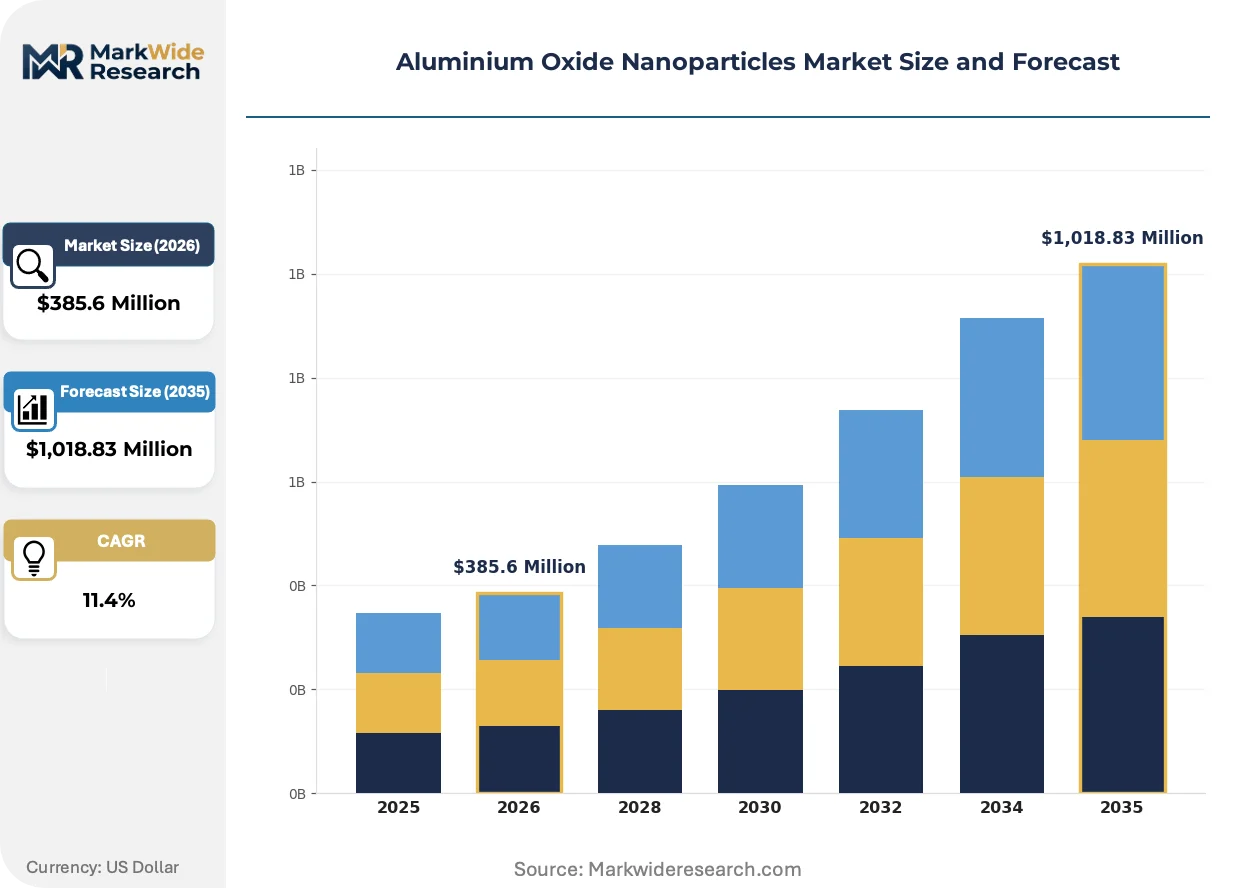
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystalline, Polycrystalline, Amorphous, Sintered Application: Catalysts, Abrasives, Electronics, Coatings, Ceramic Materials End User: Electronics Manufacturers, Chemical Producers, Ceramics Fabricators, Coating Companies Form: Powder, Suspension, Dispersion, Granular |
| Companies Covered | Evonik Industries AG, Cabot Corporation, American Elements, Sasol Limited, US Research Nanomaterials, Inc., Inframat Advanced Materials, NaBond Technologies Co., Ltd., SkySpring Nanomaterials, Inc., Strem Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Oxide Nanoparticles Market Strategic Shifts & Innovations
Plasma vaporization and flame spray pyrolysis are displacing legacy sol-gel methods for high-purity electronics-grade output, while regulatory data requirements are reshaping competitive entry barriers across all major production geographies.
Flame spray pyrolysis is decomposing the traditional sol-gel dominance in sub-100nm high-purity alpha-alumina production. German and Japanese semiconductor substrate manufacturers are adopting flame-synthesized material at accelerating rates for thermal interface applications. This technology is decomposing the historical correlation between batch size and particle-size uniformity, enabling continuous production economics at electronics-grade purity thresholds.
EPA's nanomaterial reporting rule under TSCA Section 8(a) is imposing systematic exposure and release documentation requirements on US-based alumina nanoparticle manufacturers. Industrial consequence includes mandatory workplace monitoring infrastructure investments and supply chain transparency obligations extending to downstream formulators. Catalyst-grade producers serving automotive emissions-control customers face the most acute compliance timeline pressure, with several facilities accelerating third-party verification programs.
Specification-driven vendor consolidation is compressing qualified supplier lists among LED substrate and advanced packaging buyers in East Asia. Tier-one electronics manufacturers are replacing spot-market purchasing with multi-year offtake agreements tied to defect-density guarantees and lot-to-lot consistency metrics. South Korean semiconductor foundries exhibit the most pronounced procurement pattern shift, with thermal interface material suppliers now required to demonstrate ISO/TS 80004-compliant characterization capabilities as a condition of vendor qualification.
Aluminium Oxide Nanoparticles Market Segmentation
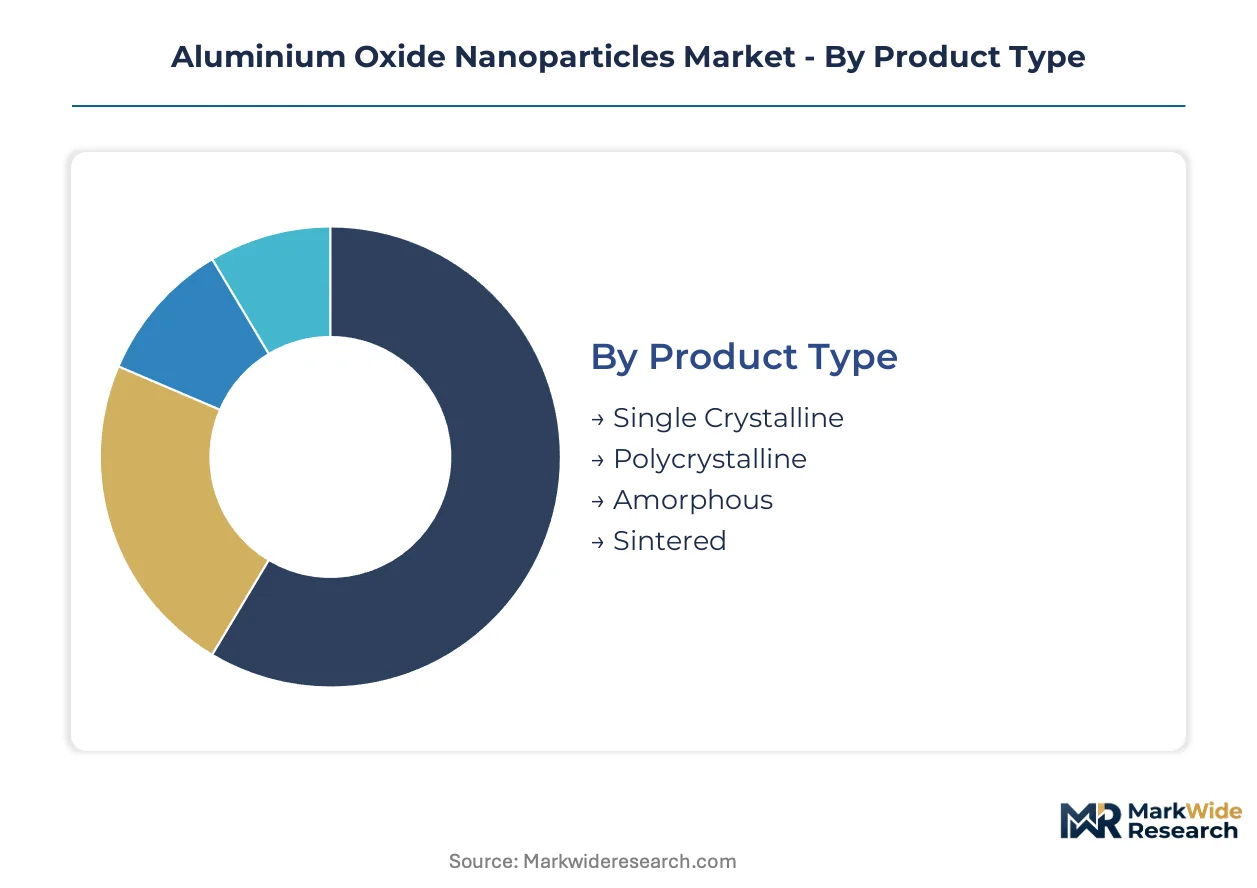
Aluminium oxide nanoparticles exhibit sharply divergent margin profiles across structural variants, with crystalline perfection and surface-area-to-volume ratios determining pricing power in semiconductor, catalyst, and abrasive end-uses. Specification granularity within each category dictates vendor qualification timelines and procurement contract structures.
Product Type:
Premium margin pools concentrate in segments where defect-density thresholds and phase purity command semiconductor substrate qualification, while commodity-grade volumes flow toward catalyst support applications prioritizing surface area over crystalline order.
- Single Crystalline:Alpha-phase particles with minimal grain boundaries and controlled orientation enable sapphire substrate epitaxy for LED and RF device manufacturing. South Korean and Japanese LED foundries now mandate sub-50nm single-crystalline material with defect densities below 10^4 per square centimeter, locking in multi-year offtake agreements at pricing multiples above standard grades.
- Amorphous:Disordered atomic structure maximizes specific surface area above 200 square meters per gram, making this variant indispensable for automotive catalytic converter washcoats where platinum group metal dispersion determines conversion efficiency. EU Green Deal retrofit programs are pulling volumes away from legacy gamma-phase supply.
- Polycrystalline:Aggregated nanocrystalline domains balance hardness with cost in precision polishing slurries for silicon wafer planarization.
- Sintered:Pre-consolidated agglomerates reduce dust exposure during ceramic matrix composite fabrication for aerospace thermal protection systems.
The dominant share belongs to Amorphous material by volume, while Single Crystalline is closing the gap fastest through sapphire substrate procurement acceleration.
Application:
Application-level profitability splits between specification-heavy electronics integration and high-throughput industrial processes where tonnage scale compensates for thinner margins.
- Electronics:Thermal interface materials, dielectric layers, and chemical-mechanical planarization slurries require sub-100nm particle size distributions with tight polydispersity indices. Advanced packaging architectures in German and South Korean semiconductor fabs are multiplying material layers per device, concentrating procurement among qualified dispersion suppliers.
- Catalysts:Gamma-phase and amorphous nanoparticles serve as washcoat substrates for diesel oxidation and selective catalytic reduction systems. REACH registration tiering is filtering European supply toward analytical-capable producers capable of documenting nanomaterial release profiles.
- Abrasives:Precision polishing of optical glass and semiconductor wafers exploits Mohs hardness above 9, though silica substitution pressure is intensifying in less demanding finishing applications.
- Coatings:Hard, wear-resistant surface treatments for cutting tools and biomedical implants leverage plasma-sprayed alumina nanoparticle feedstock.
- Ceramic Materials:Sintering aids and matrix reinforcements in structural ceramics for aerospace and defense applications.
Electronics commands the steepest expansion trajectory, while Catalysts retains the largest installed base by annual consumption.
End User:
Customer-type segmentation reveals divergent purchasing behaviors between specification-driven electronics OEMs and cost-optimized industrial processors.
- Electronics Manufacturers:Tier-one semiconductor and LED substrate producers enforce ISO/TS 80004-compliant characterization capabilities as mandatory vendor qualification criteria. Multi-year supply agreements with defect-density guarantees are displacing spot-market purchasing in South Korean and Japanese supply chains.
- Chemical Producers:Catalyst formulators prioritize surface area consistency and lot-to-lot reproducibility over absolute purity, enabling qualified supply from mid-scale precipitation specialists.
- Ceramics Fabricators:Structural ceramic manufacturers consume sintered and granular forms for high-temperature insulation and wear components.
- Coating Companies:Thermal spray and sol-gel coating operations require dispersion stability and solvent compatibility for automated application equipment.
Electronics Manufacturers concentrate the fastest-growing procurement spend, while Chemical Producers maintain the broadest supplier base.
Form:
Physical presentation determines logistics economics, handling safety protocols, and downstream formulation integration complexity.
- Dispersion:Pre-stabilized colloidal suspensions in organic or aqueous media eliminate dust exposure and enable direct integration into thermal interface pastes and polishing slurries. Electronics-grade dispersions command substantial premia over powder equivalents due to cleanroom packaging and particle-size certification.
- Powder:Dry nanopowder remains the default for catalyst washcoat impregnation and ceramic powder metallurgy, though OSHA-permissible exposure limit compliance necessitates specialized ventilation infrastructure.
- Suspension:Intermediate stability formulations serve research institutions and pilot-scale coating trials requiring adjustable solids loading.
- Granular:Millimeter-scale agglomerates of nanoparticles facilitate controlled feeding into plasma spray torches and sintering furnaces.
Dispersion formats are gaining share fastest in qualified electronics supply chains, while Powder retains volume leadership in catalyst and ceramic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized alumina nanoparticle fabrication clusters in Germany, Japan, and South Korea concentrate electronics-grade supply, while REACH registration requirements in Europe and EPA emission standards in the United States reshape production economics.
Germany
Semiconductor substrate manufacturers in Saxony and Bavaria drive procurement of high-purity alpha-phase material. ECHA's escalating REACH data requirements for nanomaterial dossiers filter supply toward analytical-capable producers. The Dresden-Leipzig electronics corridor anchors European demand for thermal interface dispersions.
United States
EPA's TSCA Section 8(a) nanomaterial reporting rule imposes systematic exposure documentation on domestic manufacturers. OSHA permissible exposure limits govern cleanroom handling protocols and ventilation infrastructure investments. The Southwest and Northeast corridor host catalyst-grade production facilities serving automotive emissions-control customers.
Japan
LED sapphire substrate foundries in Kyushu and Kansai mandate sub-50nm single-crystalline material with defect-density guarantees. METI nanomaterial classification frameworks guide industrial handling standards. The Nagoya-Osaka manufacturing belt concentrates premium nanoparticle qualification programs.
South Korea
Advanced packaging architectures in Seoul Capital Area fabs multiply thermal interface material layers per device. MFDS pharmaceutical purity mandates open specification windows for high-surface-area membrane substrates. The Suwon-Pyeongtaek semiconductor cluster enforces ISO/TS 80004-compliant characterization as a vendor qualification condition.
China
Domestic electronics OEMs expand procurement of dispersion-grade alumina for dielectric and polishing applications. MIIT industrial standards and GB nanotechnology measurement protocols provide metrological infrastructure. The Yangtze River Delta and Pearl River Delta absorb volume shipments for ceramic membrane and catalyst support manufacturing.
Aluminium Oxide Nanoparticles Market Key Industry Players
Concentration sits with diversified chemical conglomerates and specialized nanomaterial producers serving distinct specification tiers. The vendor base stratifies across analytical-capable REACH registrants, catalog-breadth suppliers, and precipitation-technology specialists. Three archetypes dominate: European chemical majors with precipitation expertise, North American catalyst-grade formulators, and Asian dispersion specialists. Competitive moves center on multi-year offtake agreements with defect-density guarantees and plasma vaporization technology licensing.
Within the diversified chemical tier, Evonik Industries AG and Cabot Corporation exemplify scale-driven positioning across electronics and catalyst segments. American Elements occupies a catalog-breadth position spanning nanopowder and dispersion forms for research and industrial buyers. These three entities represent the analytical-capable tier capable of navigating multi-jurisdictional registration requirements.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Cabot Corporation |
| American Elements |
| Sasol Limited |
| US Research Nanomaterials, Inc. |
| Inframat Advanced Materials |
| NaBond Technologies Co., Ltd. |
| SkySpring Nanomaterials, Inc. |
| Strem Chemicals, Inc. |
| Others |
Cost & Logistics Intelligence
Thirty-to-forty-five day certification timelines for ISO/TS 80004-compliant characterization separate qualified electronics-grade suppliers from commodity producers, concentrating pricing power among REACH-registered German and Japanese manufacturers while forcing spot-market buyers into premium dispersion contracts.
Pricing Analysis
REACH registration tiering dictates the pricing tier structure across European catalyst and coating sectors, with ECHA-compliant producers commanding substantial premia over non-registered competitors. Three-tier pricing structure across premium electronics-grade, standard catalyst-grade, and economy abrasive-grade levels reflects defect-density thresholds and analytical capability investments. Pricing pressure stems from aluminum chloride precursor volatility transmitting directly to sol-gel production economics. Chemical producers exhibit highest price sensitivity due to surface-area-driven specification flexibility, while semiconductor substrate manufacturers demonstrate lowest sensitivity given defect-density guarantees.
Supply Chain Analysis
Rotterdam-Antwerp chemical corridor transit underwrites European catalyst-grade distribution, with customs clearance friction for nanomaterial dossiers creating inventory buffers at major ports. Supply concentrates in Germany, Japan, and South Korea for electronics-grade material, while China and the United States anchor catalyst and abrasive volumes. Production draws from aluminum chloride, aluminum nitrate, and plasma torch feedstock streams. Single-source vulnerability concentrates in high-purity alpha-phase precipitation capacity. Distribution runs through qualified dispersion formulators serving tier-one electronics OEMs and direct powder shipments to catalyst washcoat impregnators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH dossier capabilities and ISO/TS 80004 metrology standards creates durable defensive moats for analytical-capable incumbents, with switching costs locking semiconductor substrate manufacturers into multi-year offtake agreements.
For Market Incumbents: Shield qualified supplier status by accelerating third-party verification programs ahead of EPA TSCA Section 8(a) enforcement timelines. Deepen backward integration into aluminum precursor refining to offset feedstock volatility compressing sol-gel margins. Secure capacity expansion slots in the Dresden-Leipzig corridor to capture thermal interface material layer multiplication in German advanced packaging fabs. For New Entrants and Emerging Players: ISO/TS 80004 certification fast-tracks offer the most penetrable entry path into South Korean semiconductor foundry supply chains, where vendor qualification gaps persist among dispersion specialists. Target Indian pharmaceutical filtration membrane substrates as white-space demand, where CDSCO tightening creates specification windows without incumbent lock-in. Pursue plasma vaporization technology licensing to bridge electronics-grade and catalyst-grade particle-size distributions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized precipitation assets and dormant REACH registrations. Long-term viability centers on analytical infrastructure ownership as regulatory thresholds escalate across EPA, ECHA, and METI regimes. Watch for inflection in South Korean multi-year offtake agreement announcements as signal of vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Precursor Refining | Captive supply of aluminum chloride insulates sol-gel producers from feedstock volatility transmitted by commodity metal markets. |
| ISO/TS 80004 Certification Investment | Metrology compliance unlocks vendor qualification at Samsung and SK Hynix thermal interface material suppliers. |
| Plasma Vaporization Technology Licensing | Continuous synthesis economics bridge electronics-grade purity with catalyst-grade surface area specifications. |
| Long-term Supply Agreement with Defect-Density Guarantees | Multi-year offtakes displace spot purchasing in LED sapphire substrate procurement patterns. |
| REACH Dossier Tier Escalation | ECHA data requirements filter European catalyst supply toward analytical-capable producers with toxicity documentation infrastructure. |
Research Approach
Cross-validation between primary interviews with plant managers at German precipitation facilities and secondary trade data anchors the qualitative findings on supply concentration and procurement pattern shifts. Conversations with procurement leads at South Korean semiconductor foundries, technical R&D directors at catalyst formulators, and distribution channel partners in the Rotterdam-Antwerp corridor informed vendor qualification dynamics. Bottom-up triangulation against SEC filings from Cabot Corporation and Evonik Industries AG, customs records for aluminum oxide nanoparticle trade flows, and Cefic chemical industry reports validated capacity and pricing observations.
Sensitivity analysis around aluminum precursor cost trajectories and REACH registration timeline scenarios shapes the projection framework across the analysis window. Segmentation modeling spans crystalline phase purity tiers, end-use applications from thermal interface materials to catalytic washcoats, physical presentation formats, and regional production hub clusters. CAGRs derive from demand elasticity coefficients calibrated to advanced packaging layer multiplication rates and automotive emissions retrofit program announcements. Forecast inputs incorporate semiconductor fab capacity expansion schedules and EU Green Deal catalyst mandate implementation pacing.
Decision-makers should treat outputs as directional under stable regulatory classification assumptions for nanomaterials; material deviation through EPA, ECHA, or METI reclassification would warrant model refresh. Practitioners should keep alternative scenarios live as aluminum precursor volatility and multi-jurisdictional registration synchronization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Europe Gold Nanoparticle Market