
 Nano Copper Oxide Market | 2026-2036
Nano Copper Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Copper Oxide Market Intelligence
Buyer concentration among electronics manufacturers is recalibrating procurement dynamics across the nano copper oxide value chain. Nanophase Technologies Corporation leverages its specialized manufacturing infrastructure to serve high-specification electronics clients. American Elements anchors North American supply through vertically integrated rare earth and advanced material production. Hongwu International Group Ltd dominates Asia-Pacific distribution channels with extensive nanoparticle portfolios.
Nano copper oxide denotes copper(II) oxide engineered at particle dimensions typically below 100 nanometers, synthesized through precipitation, sol-gel, or thermal decomposition routes to achieve elevated surface area and catalytic reactivity for antimicrobial coatings, semiconductor fabrication, and agrichemical formulations. Powder formulations command the largest volume share due to established handling protocols and compatibility with bulk catalytic processes, while aqueous suspensions represent the fastest-expanding category as paint producers and agricultural firms adopt liquid-delivery systems for uniform dispersion. Electronics applications concentrate the highest margin pools, driven by stringent purity requirements in conductive ink and printed circuit board manufacturing.
EPA nanomaterial reporting rules under the Toxic Substances Control Act and REACH registration mandates in Europe impose escalating compliance burdens on importers and formulators, effectively filtering smaller traders from premium supply tiers. China's GB standards for nanomaterial characterization and Japan's METI-guided nano-safety protocols further fragment regulatory landscapes across major consumption centers. Stakeholders must monitor evolving registration thresholds and testing protocols to sustain market access across jurisdictions.
Market Dynamics
Electronics manufacturers are consolidating procurement power around high-purity nano copper oxide specifications, forcing suppliers to absorb compliance costs from REACH documentation and EPA nanomaterial reporting while maintaining price discipline across fragmented regional regulatory regimes.
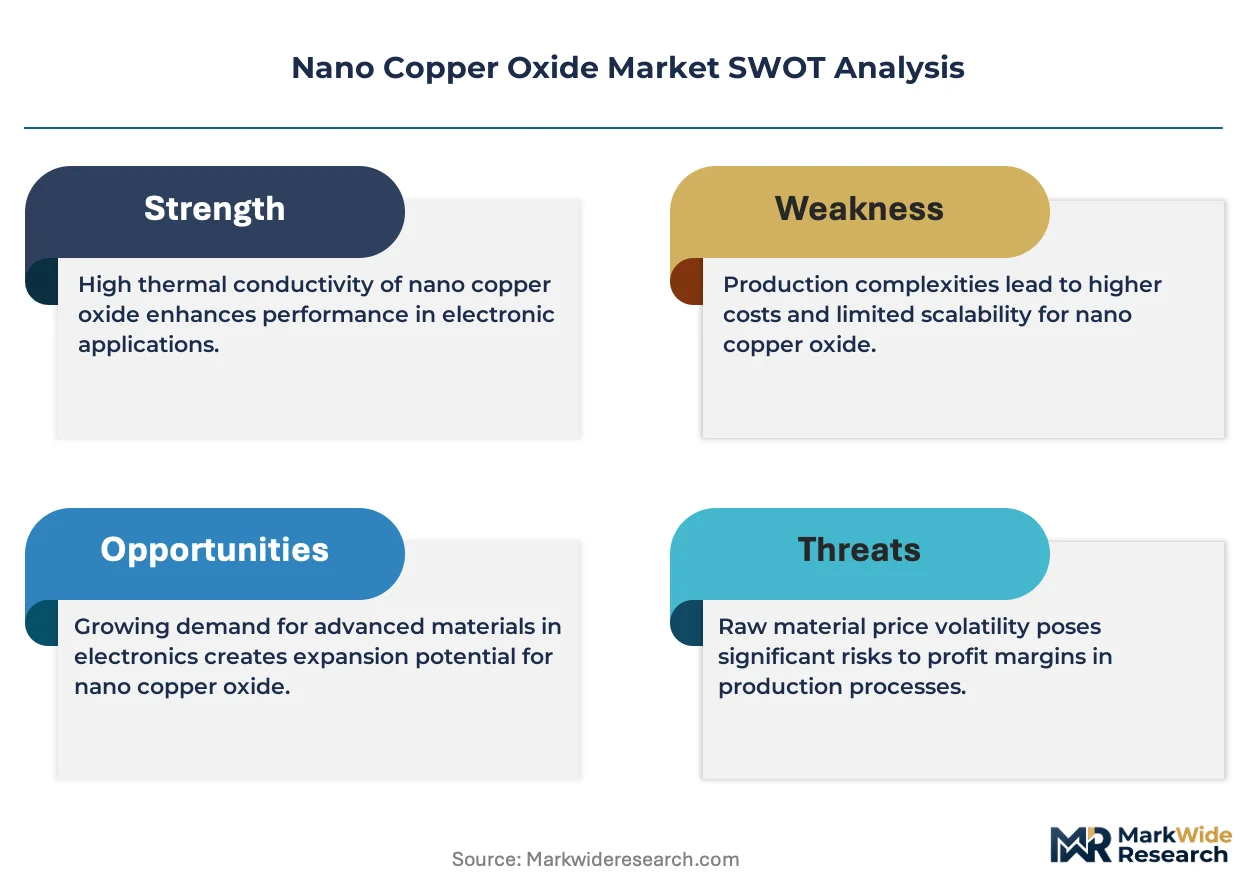
Growth Catalysts
- Printed circuit board miniaturization:Semiconductor fabs in Taiwan and South Korea are specifying sub-50nm copper oxide for advanced interconnect layers, creating specification-locked demand pools.
- REACH registration thresholds:European formulators face mandatory tonnage-band registration that filters out commodity traders, concentrating volume with certified producers.
- Antimicrobial coating mandates:Healthcare infrastructure codes in Japan and South Korea now recognize copper oxide nanoparticles for high-touch surface applications, opening institutional specification channels.
Market Restraints
- Copper price volatility:LME copper futures swings above 15% annually compress formulator margins and destabilize long-term supply agreements.
- Chinese supply concentration:Over 60% of global nano copper oxide precursor capacity sits in Jiangsu and Shandong provinces, creating geographic single-point vulnerability.
- Silver nanowire substitution:Flexible electronics producers are pivoting to silver nanowire transparent conductors for foldable display applications, displacing copper oxide in select high-value segments.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for semiconductor and component production are attracting nano copper oxide suppliers to establish local blending facilities near Bengaluru and Hyderabad clusters.
- Agricultural nanofertilizer convergence:Controlled-release formulations combining nano copper oxide with nitrogen carriers are penetrating precision agriculture trials in Australia and Brazil.
- EU Green Deal procurement rules:Public tender environmental criteria are favoring nanomaterial suppliers with verified lifecycle assessments, creating preferential access for documented producers.
Industry Challenges
- Characterization technician scarcity:DLS and BET surface area analysis expertise is concentrated among a handful of analytical service providers, creating bottlenecks for batch release testing.
- EPA pre-manufacture notification timelines:TSCA Section 5 review periods stretching 180+ days are delaying new formulation introductions and freezing R&D pipeline decisions.
- Legacy powder handling infrastructure:Agricultural and coatings customers lack explosion-proof nanomaterial dosing equipment, forcing suppliers to absorb capital expenditure for liquid suspension conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Copper Oxide Market |
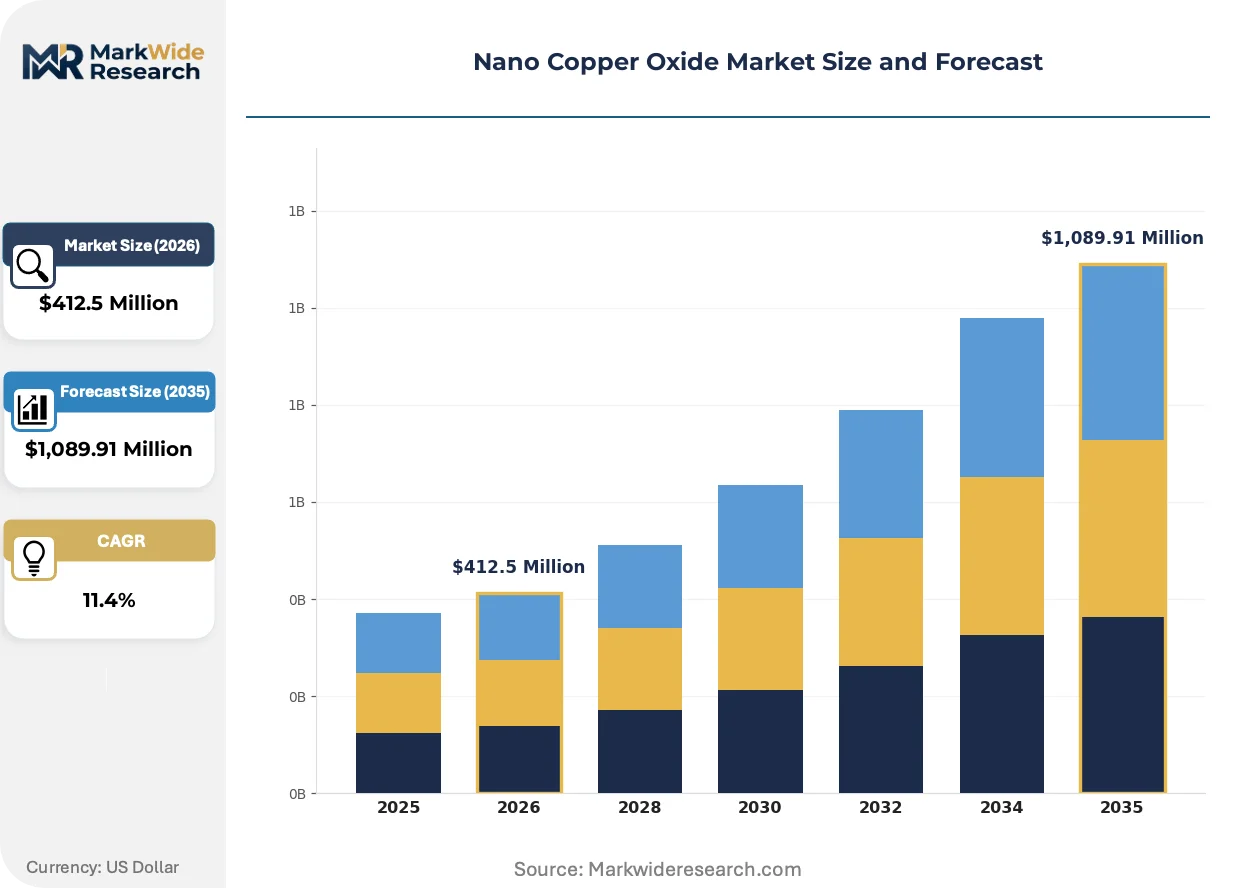
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,089.91 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Nanoparticles, Aqueous Suspension, Coated Application: Catalysis, Electronics, Coatings, Agriculture End User: Electronics Manufacturers, Agricultural Firms, Research Institutions, Paint Producers Form: Dry, Liquid, Gel, Composite |
| Companies Covered | Alfa Aesar, Nanophase Technologies Corporation, Merck KGaA, US Research Nanomaterials, Inc., Hongwu International Group Ltd, American Elements, Nanoshel LLC, NanoComposix, Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Copper Oxide Market Strategic Shifts & Innovations
Synthesis route optimization and regulatory documentation automation are compressing time-to-market for qualified nano copper oxide grades, while end-users are consolidating supplier panels around vertically integrated producers with captive analytical capabilities.
Green synthesis protocols using plant-derived reducing agents are unifying environmental compliance with cost reduction objectives. European coatings manufacturers are adopting these routes to preempt REACH authorization restrictions on traditional chemical precursors. The structural consequence is unifying sustainability certification with supply security, locking out traders lacking in-house green chemistry capabilities.
ECHA's 2023 updated nanoform guidance is forcing registrants to submit enhanced characterization data sets including dissolution kinetics and protein corona formation. Formulators importing into Europe must now secure full substance identity profiles from upstream manufacturers. Electronics applications face the steepest compliance cost escalation, as purity specifications already demand extensive analytical documentation.
Buyer consortiums in Taiwan and South Korea are consolidating annual nano copper oxide tenders into multi-year framework agreements with embedded price adjustment clauses. Direct procurement from synthesis houses is displacing distributor intermediaries for volume electronics accounts. This channel compression is most visible in semiconductor materials procurement, where fabs are qualifying single-source relationships with integrated producers holding ISO 17025 accredited laboratories.
Nano Copper Oxide Market Segmentation
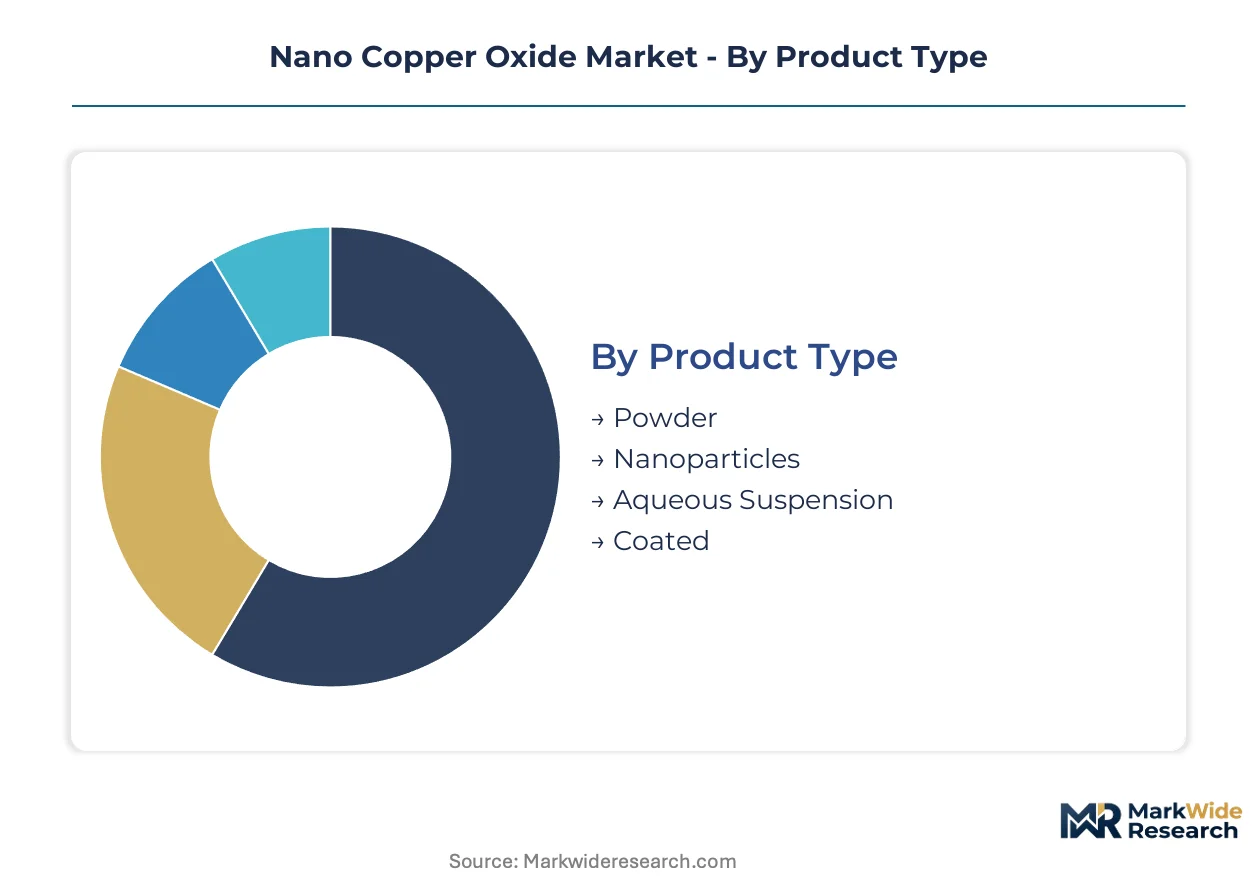
Nano copper oxide procurement patterns diverge sharply across formulation types and end-use specifications, with electronics manufacturers imposing purity thresholds that agricultural buyers rarely match. Understanding these segment boundaries clarifies where suppliers can standardize production versus where customization commands premium positioning.
Product Type:
Buyers differentiate primarily by handling infrastructure and dispersion requirements, with powder-capable facilities facing lower capital barriers than liquid-delivery systems.
- Powder:Dry particulate formulations with established bulk-handling protocols dominate catalytic process integration. Semiconductor fabs in Taiwan and South Korea specify sub-50nm grades for interconnect layers, locking volume with certified producers.
- Aqueous Suspension:Liquid-delivery systems enable uniform dispersion in agricultural spray applications and architectural coatings. Paint producers in Germany and Japan are converting dosing equipment to accommodate this format, climbing the fastest as regulatory pressure favors closed-system handling.
- Nanoparticles:Discrete sub-100nm units requiring specialized stabilization for research and high-specification electronics.
- Coated:Surface-modified variants with polymer or silica shells for controlled-release agrichemical and antimicrobial applications.
Volume sits with powder; growth tilts toward aqueous suspension.
Application:
Margin structures separate commodity catalytic consumption from specification-locked electronics demand, with coatings and agriculture occupying intermediate positions.
- Electronics:Conductive ink and printed circuit board manufacturing impose the steepest purity requirements, with REACH registration and EPA nanomaterial documentation filtering supplier pools. Taiwan-based semiconductor fabs consolidate procurement through multi-year framework agreements.
- Agriculture:Controlled-release nanofertilizer formulations combine copper oxide with nitrogen carriers for precision agriculture trials in Australia and Brazil. METI-guided nano-safety protocols in Japan recognize copper oxide for high-touch surface applications, expanding institutional specification channels.
- Catalysis:Bulk chemical process integration favors standardized powder grades with established supplier relationships.
- Coatings:Antimicrobial and functional surface treatments bridging industrial and consumer applications.
Electronics commands margin concentration; agriculture shows steepest expansion trajectory.
End User:
Procurement sophistication varies from institutional research tenders to integrated manufacturing demand, with documentation requirements scaling accordingly.
- Electronics Manufacturers:Vertically integrated producers with captive analytical capabilities dominate supplier panels, displacing distributor intermediaries through direct synthesis house relationships.
- Paint Producers:European coatings manufacturers adopting green synthesis protocols to preempt REACH authorization restrictions on traditional chemical precursors.
- Agricultural Firms:Precision agriculture operators in Australia and Brazil testing controlled-release formulations with limited legacy nanomaterial handling infrastructure.
- Research Institutions:Academic and government laboratories with flexible specification tolerance and fragmented purchasing volumes.
Electronics manufacturers anchor volume commitment; paint producers drive format conversion.
Form:
Physical state determines compatibility with existing customer equipment and regulatory exposure pathways across jurisdictions.
- Dry:Powder and granular formats compatible with established bulk material handling systems in catalytic and agricultural applications.
- Liquid:Suspensions and solutions enabling closed-system delivery for coatings and precision agriculture, favored under EU Green Deal procurement criteria.
- Gel:Thickened formulations for controlled-release and topical antimicrobial applications.
- Composite:Embedded matrices combining copper oxide with polymer, ceramic, or metal substrates for structural functionalization.
Dry forms retain installed base dominance; liquid gains share fastest under tightening workplace exposure regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Shandong provinces in China host over 60% of global nano copper oxide precursor capacity, creating geographic concentration that shapes trade flows and regulatory arbitrage across consumer markets.
China
Domestic electronics fabrication clusters in Shenzhen and government-backed nanotechnology initiatives in Suzhou accelerate volume uptake. GB standards for nanomaterial characterization impose testing protocols that filter smaller traders from premium supply tiers. Jiangsu province hosts concentrated precursor production serving both domestic semiconductor fabs and export formulators.
United States
EPA nanomaterial reporting requirements under the Toxic Substances Control Act tighten purity and safety documentation obligations for importers. American Elements anchors North American supply through vertically integrated rare earth and advanced material production. California-based semiconductor research centers drive specification-locked demand for sub-50nm grades.
Germany
REACH compliance mandates and ECHA's 2023 updated nanoform guidance force registrants to submit enhanced characterization data sets including dissolution kinetics. European coatings manufacturers in the Ruhr region adopt green synthesis protocols to preempt REACH authorization restrictions. Paint producers convert dosing equipment to accommodate aqueous suspension formats.
Japan
METI-guided nano-safety protocols recognize copper oxide nanoparticles for high-touch surface applications, expanding institutional specification channels. Healthcare infrastructure codes in Tokyo and Osaka now mandate antimicrobial coatings in public facilities. Kyushu-based electronics materials suppliers consolidate procurement through multi-year framework agreements.
South Korea
Semiconductor fabs in Gyeonggi Province specify sub-50nm copper oxide for advanced interconnect layers, creating specification-locked demand pools. Buyer consortiums consolidate annual tenders into framework agreements with embedded price adjustment clauses. Busan-Ulsan materials clusters serve as distribution hubs for Taiwan and Southeast Asian electronics manufacturers.
Nano Copper Oxide Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue green synthesis routes and regional compliance specialization. The vendor base stratifies across three tiers: integrated materials conglomerates with captive analytical capabilities, mid-scale specialists serving specification-locked electronics accounts, and commodity traders facing filtration from REACH tonnage-band registration. Competitive moves center on backward integration into precursor supply and geographic expansion toward India PLI scheme clusters.
Among US-based fabricators, Nanophase Technologies Corporation exemplifies the specialist archetype serving high-specification electronics clients. Hongwu International Group Ltd anchors Asia-Pacific distribution channels. American Elements represents vertically integrated production with rare earth and advanced material capabilities. Merck KGaA and Sigma-Aldrich occupy positions within the analytical-grade supply tier serving research institutions and semiconductor fabs.
| Leading Market Players |
|---|
| Alfa Aesar |
| Nanophase Technologies Corporation |
| Merck KGaA |
| US Research Nanomaterials, Inc. |
| Hongwu International Group Ltd |
| American Elements |
| Nanoshel LLC |
| NanoComposix |
| Sigma-Aldrich |
| Others |
Cost & Logistics Intelligence
Green synthesis protocols using plant-derived reducing agents are compressing production cost curves while simultaneously filtering supplier pools toward integrated producers with captive green chemistry capabilities. This dual effect concentrates pricing power among certified manufacturers as REACH authorization restrictions eliminate commodity traders lacking in-house environmental compliance infrastructure.
Pricing Analysis
Certificate-of-analysis bundling separates specification-locked electronics grades from commodity catalytic tiers, with ISO 17025 accredited testing included in premium quotations while agricultural buyers absorb third-party analytical costs. Electronics manufacturers in Taiwan and South Korea face steep REACH documentation fees passed through from European suppliers, intensifying cost compression in that tier. Agricultural formulators in Brazil and Australia exhibit highest price sensitivity due to thin margins on bulk nanofertilizer applications, whereas semiconductor fabs accept premium positioning for sub-50nm purity guarantees.
Supply Chain Analysis
Regional distribution centers in Busan, Rotterdam, and Los Angeles anchor hub-and-spoke patterns serving electronics clusters in Gyeonggi Province, the Ruhr region, and California. Precursor supply draws from Jiangsu and Shandong provinces in China, with copper concentrate feedstock sourced from Chilean and Peruvian mining operations. Single-source vulnerability concentrates in Chinese precursor capacity, exposing formulators to export licensing disruptions. Distribution runs through qualified producer-direct channels for volume electronics accounts, with distributor intermediaries retaining agricultural and coatings segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aqueous suspension formats are displacing legacy powder handling systems across European coatings and Japanese agricultural applications, compressing the transition window for suppliers dependent on dry-form infrastructure.
For Market Incumbents: To counter silver nanowire substitution in flexible display interconnects, deepen captive analytical capabilities through ISO 17025 laboratory accreditation and secure multi-year framework agreements with Taiwan semiconductor fabs. Backward integration into Jiangsu precursor supply hedges geographic concentration risk while absorbing margin compression from REACH compliance cost pass-through. For New Entrants and Emerging Players: Agricultural cooperatives in Australia's wheat belt represent an underserved buyer archetype seeking controlled-release nanofertilizer formulations without legacy nanomaterial handling infrastructure. Local blending facilities near Bengaluru PLI scheme clusters offer penetrable white-space for electronics-grade qualification. Green synthesis certification unlocks EU Green Deal procurement preference without competing on incumbent scale economics. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale specialists holding captive green synthesis capabilities given ECHA's escalating nanoform characterization requirements. Five-to-ten year viability favors producers with demonstrated dissolution kinetics and protein corona data sets. The inflection signal to watch is EPA TSCA Section 5 review timeline compression, which would freeze R&D pipelines at undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Jiangsu province capacity control mitigates single-source vulnerability for qualified producers. |
| Green Synthesis Certification | Plant-derived reducing agent protocols preempt REACH authorization restrictions on traditional precursors. |
| ISO 17025 Laboratory Accreditation | Captive analytical capabilities satisfy ECHA dissolution kinetics documentation for electronics clients. |
| Multi-Year Framework Agreements | Taiwan and South Korea fab procurement consolidation locks volume through embedded price adjustment clauses. |
| Regional Blending Facility Expansion | India PLI scheme proximity reduces logistics exposure for Bengaluru and Hyderabad electronics clusters. |
Research Approach
Trade databases, ECHA registration filings, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews involving nanomaterial plant managers, electronics procurement leads at Taiwan semiconductor fabs, coatings R&D directors in Germany, and agricultural extension officers in Australia. Bottom-up volume estimates from application-level consumption patterns were reconciled with top-down producer capacity assessments across Jiangsu and Shandong provinces.
Historical trendline analysis of nano copper oxide pricing and volume trajectories informed projection modeling across the analysis window. Segmentation dimensions included formulation type, application tier, end-user sophistication, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating copper price volatility and substitution threat parameters from silver nanowire transparent conductor development.
Revisions become necessary when EPA TSCA Section 5 review timelines extend beyond standard periods, when Chinese export licensing disrupts precursor flows, or when ECHA nanoform guidance thresholds shift. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Nanotools Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Global Graphene Based Supercapacitors Market
Nanomaterials
Global Nanoemulsion Market