
 Nanopesticides Market | 2026-2036
Nanopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Nanopesticides Market Foresight
Agricultural cooperative procurement networks are reshaping how nanoformulated crop protection reaches row-crop farmers. Bayer CropScience leverages its seed-treatment infrastructure to bundle nanopesticide coatings with hybrid genetics. Syngenta anchors its position through integrated field-station trials that validate nanoemulsion stability across variable climates. UPL Limited competes via broad geographic manufacturing that reduces freight costs to cooperative buyers in emerging agricultural zones.
Nanopesticides are active ingredients or biological agents engineered at 1-100 nanometer scale, typically encapsulated in lipid or polymer carriers to enhance foliar adhesion and controlled release against target pests. Nanoemulsion formulations dominate current commercial volume due to simpler manufacturing and established compatibility with ground sprayers, while nanoparticle carriers capture expanding margin pools through patent-protected delivery precision. The agricultural crops application segment leads absolute consumption as broad-acre growers seek dose reduction compliance, though horticultural crops generate premium pricing from residue-sensitive export markets.
The EPA regulates nanopesticides under FIFRA with supplemental data requirements for particle characterization and environmental fate, while the EU REACH framework mandates nano-specific registration dossiers that extend market access timelines. India's Central Insecticides Board evaluates nanoformulations under amended pesticide rules that distinguish carrier toxicity from active ingredient profiles. Stakeholders must track how evolving particle-size definitions in regulatory guidance documents affect existing product registrations and new submission pathways.
Market Dynamics
Regulatory divergence between EPA nano-specific data requirements and EFSA's evolving particle characterization standards is fragmenting registration pathways and forcing dual-track development investments for multinational suppliers.
Growth Catalysts
- REACH nano-annex dossier mandates:European formulators accelerating pre-registration toxicity studies to secure five-year exclusivity windows before generic nanoemulsion competitors enter.
- Soybean belt precision spraying infrastructure:Brazil's Cerrado region retrofitting ground rigs for nanoemulsion compatibility, creating captive demand for encapsulated active ingredients with drift-reduction properties.
- Lipid carrier technology maturation:University-industry partnerships in India advancing solvent-free nanoencapsulation methods that cut manufacturing energy intensity by half relative to polymer alternatives.
Market Restraints
- Active ingredient supply concentration:Three Chinese manufacturers control over 80% of technical-grade pyrethroid feedstock for nanoencapsulation, exposing formulators to export quota volatility.
- FIFRA supplemental data costs:EPA particle fate studies add 18-24 months to registration timelines, compressing commercialization windows before patent expiry.
- Conventional microencapsulation substitution:Established 1-10 micron polymer coatings from agricultural chemical majors retain cost advantages for broad-acre commodity crops.
Strategic Opportunities
- Uttar Pradesh horticultural export corridors:Residue-sensitive grape and mango shippers in India seeking sub-ppm detection limit solutions that nanoformulations uniquely provide.
- Biological-nanocarrier convergence:RNA interference payloads delivered via chitosan nanoparticles opening new mode-of-action categories against herbicide-resistant weed populations.
- Agricultural cooperative direct contracting:Bypassing traditional distribution tiers through state-level procurement consortia in Punjab and Haryana wheat belts.
Industry Challenges
- Environmental fate modeling expertise scarcity:Toxicologists capable of interpreting nano-specific OECD test guidelines command premium compensation, constraining mid-tier formulator expansion.
- Legacy sprayer incompatibility:Existing farmer equipment requires nozzle and filtration retrofits to prevent nanoparticle aggregation and line clogging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanopesticides Market |
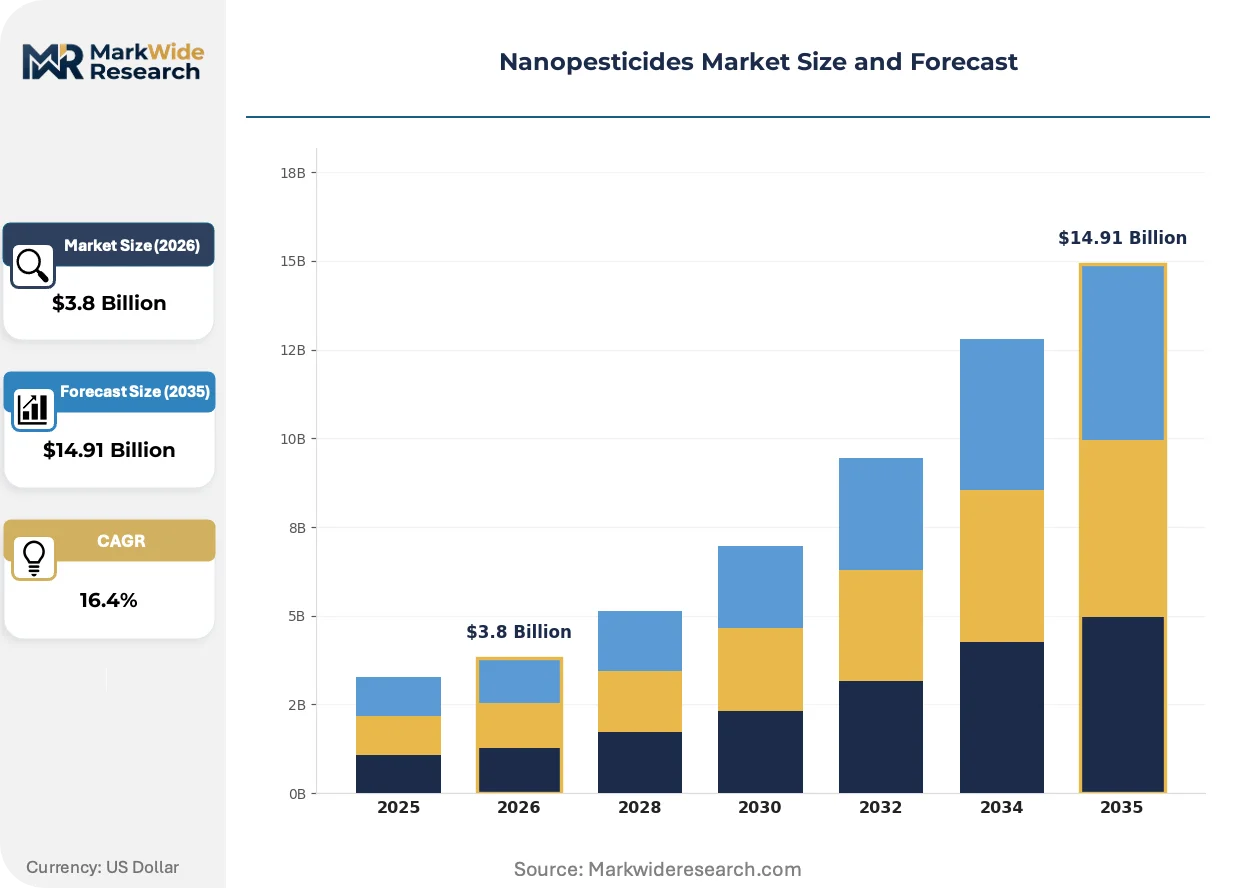
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopesticides, Chemical Pesticides, Conventional Pesticides, Microbial Pesticides Composition: Nanoparticles, Nanocarriers, Micelles, Nanoemulsions Application: Agricultural Crops, Horticultural Crops, Turf & Ornamentals, Forestry Distribution Channel: Online Retail, Specialty Stores, Agricultural Cooperatives, Direct Sales |
| Companies Covered | Corteva Agriscience, UPL Limited, Syngenta, Sumitomo Chemical Co., Ltd., Nufarm Limited, Bayer CropScience, FMC Corporation, Marrone Bio Innovations, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanopesticides Market Shifts & Advancements
Formulation science is converging with digital agriculture platforms, creating integrated systems where nanopesticide release kinetics synchronize with sensor-triggered application timing.
Chitosan-lignin composite carriers are hybridizing biological origin with synthetic polymer stability. Specialty crop producers in California's Central Valley are piloting these materials for pH-responsive release against piercing-sucking insects. The technology is hybridizing conventional crop protection with precision agriculture data layers, compressing the distinction between input supplier and farm management service provider.
EPA's 2024 updated guidance on conditional registration for nanopesticides now mandates chronic aquatic toxicity endpoints for particles below 50 nanometers. Formulators must rerun existing studies under revised protocols, delaying market entry for three pipeline products. Agricultural biotechnology firms with in-house ecotoxicology capacity are absorbing smaller competitors unable to fund duplicate testing.
Cooperative procurement aggregators in India's wheat belt now specify nanoformulation compatibility as mandatory in tender documents, displacing traditional distributor relationships. State-level agricultural departments in Punjab and Haryana are consolidating purchase volumes through digital platforms that bypass legacy commission-based networks. This concentration is most visible in northwestern India, where farmer producer organizations now contract directly with nanopesticide manufacturers for pre-season supply commitments.
Nanopesticides Market Segmentation
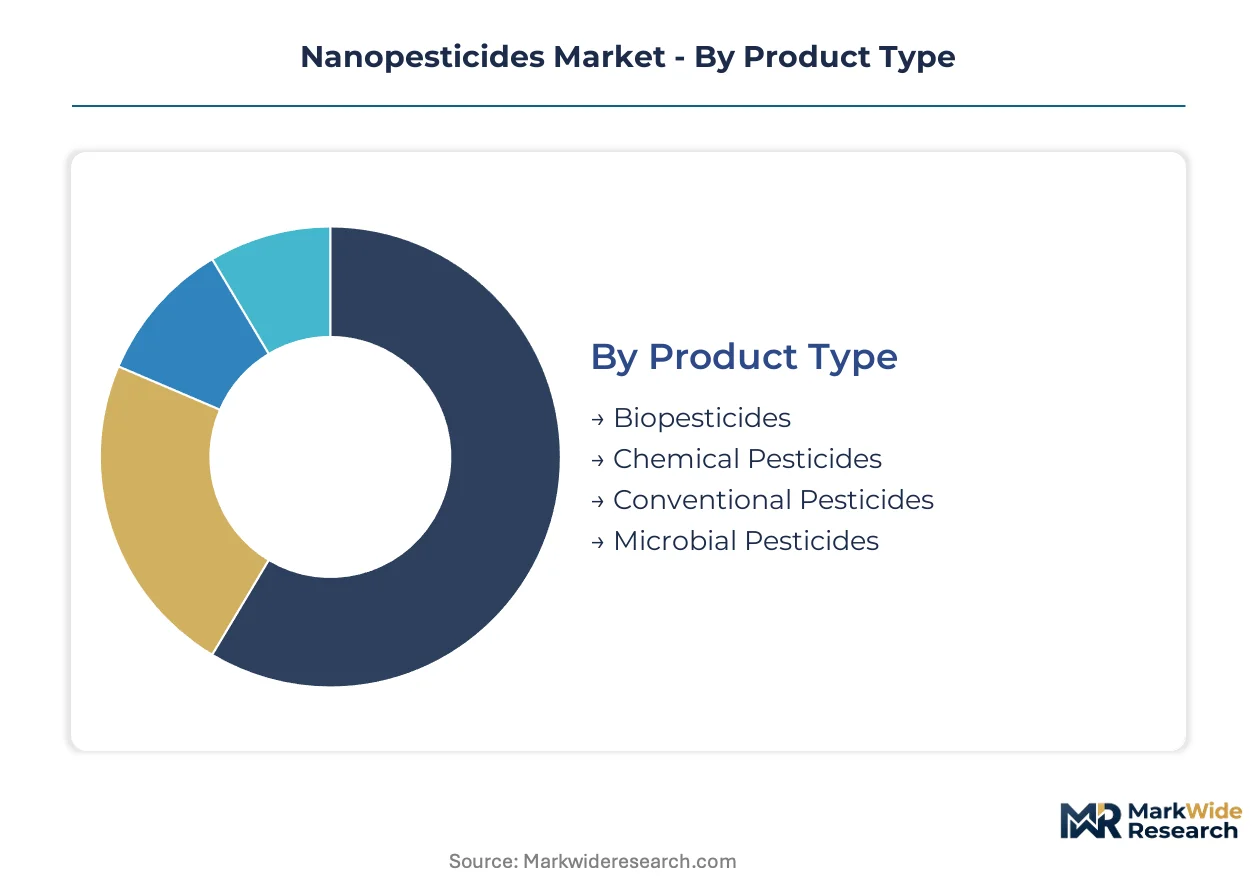
Segmentation in nanopesticides reveals how formulation chemistry, delivery mechanisms, and procurement pathways create distinct margin pools and regulatory exposure profiles across the value chain.
Product Type:
Cost tier determines regulatory burden and manufacturing complexity across active ingredient categories.
- Chemical Pesticides:Synthetic active ingredients engineered at nanoscale dominate current commercial volume. Brazil's Cerrado soybean belt and India's Punjab wheat corridor concentrate procurement of encapsulated pyrethroids and neonicotinoids for broad-acre row crops.
- Biopesticides:Microbial and botanical actives in nanoformulation capture premium pricing from residue-sensitive export markets. California's Central Valley specialty crop producers and Uttar Pradesh grape shippers drive formulation partnerships with chitosan-lignin composite carriers.
- Conventional Pesticides:Legacy active ingredients reformulated with nano-enhanced delivery systems extend patent life and differentiate against generic competition.
- Microbial Pesticides:Bacterial and fungal biocontrol agents stabilized in lipid nanoparticles improve field persistence against UV degradation and desiccation stress.
Chemical Pesticides holds installed capacity. Biopesticides is rotating up the share rankings.
Composition:
Application characteristics and equipment compatibility separate the four carrier technologies.
- Nanoemulsions:Oil-in-water dispersions below 200 nanometers integrate with existing ground sprayer infrastructure. Brazil's precision spraying retrofit programs and cooperative procurement networks in India's wheat belt standardize on nanoemulsion compatibility specifications.
- Nanoparticles:Solid-core carriers ranging 1-100 nanometers enable controlled release kinetics and pH-responsive payload delivery. University-industry partnerships in India advance solvent-free manufacturing methods that reduce energy intensity relative to polymer alternatives.
- Nanocarriers:Engineered delivery vehicles including polymeric shells and lipid vesicles protect sensitive actives from environmental degradation.
- Micelles:Self-assembling surfactant structures enhance solubility of hydrophobic actives in aqueous spray solutions.
Nanoemulsions holds installed capacity. Nanoparticles is rotating up the share rankings.
Application:
Customer type and residue tolerance thresholds define the four end-use segments.
- Agricultural Crops:Broad-acre grain and oilseed production generates absolute volume consumption. Large-scale farming operations in Brazil and India adopt nanoformulations for dose reduction compliance and drift mitigation in precision agriculture systems.
- Horticultural Crops:Fruit and vegetable production commands premium pricing from export markets with sub-ppm residue limits. Uttar Pradesh mango and grape shippers specify nanoformulation compatibility in procurement tenders to access European and Middle Eastern retail channels.
- Turf & Ornamentals:Golf course and landscape maintenance applications value reduced application frequency and aesthetic safety profiles.
- Forestry:Plantation timber and nursery operations utilize nanopesticides for targeted pest management in remote access terrain.
Agricultural Crops holds installed capacity. Horticultural Crops is rotating up the share rankings.
Distribution Channel:
Supply concentration and procurement consolidation reshape how nanoformulations reach end-users.
- Agricultural Cooperatives:State-level procurement consortia in Punjab and Haryana consolidate purchase volumes through digital platforms that bypass legacy commission-based distributor networks. Cooperative tender documents now specify nanoformulation compatibility as mandatory.
- Direct Sales:Manufacturers contract pre-season supply commitments with farmer producer organizations, compressing margin capture from traditional distribution tiers. Bayer CropScience leverages seed-treatment infrastructure to bundle nanopesticide coatings with hybrid genetics.
- Online Retail:E-commerce platforms aggregate smallholder demand in fragmented agricultural zones with limited cooperative penetration.
- Specialty Stores:Independent agricultural input retailers serve horticultural producers with technical advisory and customized formulation blending.
Agricultural Cooperatives holds installed capacity. Direct Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA nano-specific data requirements anchor United States regulatory frameworks, while EFSA particle characterization standards in Europe and India's Central Insecticides Board amendments create divergent compliance pathways that fragment multinational development strategies.
United States
Precision agriculture adoption among large-scale farming operations in the Corn Belt drives nanoemulsion demand for drift-reduction compliance. EPA's FIFRA supplemental data mandates for particle fate studies extend registration timelines by 18-24 months, compressing commercialization windows. California's Central Valley specialty crop producers pilot chitosan-lignin composite carriers for pH-responsive release against piercing-sucking insects.
Brazil
Soybean belt precision spraying infrastructure in the Cerrado region retrofits ground rigs for nanoemulsion compatibility, creating captive demand for encapsulated active ingredients. ANVISA evaluates nanoformulations under amended agrochemical rules that distinguish carrier toxicity from active ingredient profiles. Mato Grosso's large-scale farming operations consolidate procurement through agricultural cooperative networks that specify nanoformulation compatibility in tender documents.
India
Punjab and Haryana wheat corridors concentrate demand for dose reduction compliance through state-level procurement consortia. The Central Insecticides Board distinguishes carrier toxicity from active ingredient profiles under amended pesticide rules. University-industry partnerships in Gujarat advance solvent-free nanoencapsulation methods that cut manufacturing energy intensity relative to polymer alternatives.
Germany
REACH nano-annex dossier mandates accelerate pre-registration toxicity studies among European formulators seeking five-year exclusivity windows. ECHA's evolving particle characterization standards extend market access timelines compared to EPA pathways. Bavaria's agricultural biotechnology firms absorb smaller competitors unable to fund duplicate ecotoxicology testing under revised OECD protocols.
China
Three domestic manufacturers control over 80% of technical-grade pyrethroid feedstock for nanoencapsulation, exposing global formulators to export quota volatility. MEE environmental fate modeling requirements for particles below 50 nanometers align with tightening international standards. Shandong Peninsula's chemical clusters supply raw material concentration that shapes downstream pricing dynamics for encapsulated formulations.
Nanopesticides Market Competitive Landscape
Integrated agricultural conglomerates and specialized formulation houses split the market between seed-treatment bundling capabilities and standalone nanoemulsion manufacturing expertise. The vendor base concentrates around patent-protected delivery precision versus cost-optimized compatibility with existing ground sprayer infrastructure. Two dominant competitive moves define current positioning: agricultural cooperative direct contracting that bypasses traditional distribution tiers, and university-industry partnerships that advance solvent-free manufacturing methods.
Within the integrated conglomerate tier, Bayer CropScience, Syngenta, and BASF SE exemplify archetypes that leverage seed-treatment infrastructure and field-station trial networks to validate nanoemulsion stability across variable climates. Bayer CropScience occupies a position bundling nanopesticide coatings with hybrid genetics through established distribution channels. Syngenta anchors integrated field-station validation capabilities that compress development cycles for climate-adaptive formulations. BASF SE sits within the polymer carrier patent portfolio segment that captures expanding margin pools through delivery precision differentiation. UPL Limited represents geographic manufacturing diversification that reduces freight costs to cooperative buyers in emerging agricultural zones.
| Leading Market Players |
|---|
| Corteva Agriscience |
| UPL Limited |
| Syngenta |
| Sumitomo Chemical Co., Ltd. |
| Nufarm Limited |
| Bayer CropScience |
| FMC Corporation |
| Marrone Bio Innovations |
| BASF SE |
| Others |
Supply & Pricing Matrix
Overcapacity in Shandong Peninsula pyrethroid feedstock facilities is pressuring technical-grade input pricing while simultaneously eroding margin capture for nanoencapsulation formulators lacking captive supply agreements. This utilization dynamic forces mid-tier manufacturers toward cooperative procurement consortia that aggregate volume leverage against concentrated Chinese suppliers.
Pricing Analysis
Price spreads between nanoemulsion formulations in Brazil's Cerrado and polymer-carrier alternatives in Germany's Bavaria reach three-to-one multiples. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected nanoparticle carriers from commodity nanoemulsions and legacy microencapsulation. Cost compression in standard-tier nanoemulsions is intensifying because Brazilian cooperative buyers consolidate tender volumes. Smallholder farmers in fragmented Indian districts exhibit highest price sensitivity; California Central Valley specialty crop producers show lowest.
Supply Chain Analysis
Contract manufacturing for lipid nanoparticle carriers concentrates among Gujarat-based university-industry partnerships and Bavarian agricultural biotechnology clusters. Technical-grade pyrethroid feedstock draws from Shandong Peninsula, Jiangsu Province, and Zhejiang chemical parks. Chitosan raw material sources from coastal India and Southeast Asian shrimp processing byproduct streams. Single-source vulnerability in Chinese technical-grade active ingredient supply exposes formulators to export quota volatility. Distribution runs through agricultural cooperative procurement consortia in Punjab, Haryana, and Mato Grosso that displace legacy distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nanopesticides represent a high-growth disruption as EPA chronic aquatic toxicity mandates for sub-50 nanometer particles force duplicate ecotoxicology investment that only integrated conglomerates can fund.
For Market Incumbents: Pre-empt cooperative procurement consolidation by seed-treatment bundling that locks in pre-season supply commitments before tender windows open. Acquire solvent-free nanoencapsulation capabilities from Gujarat university partnerships to reduce manufacturing energy intensity. Patent-protected delivery precision remains the priority lever against generic nanoemulsion competitors.
For New Entrants and Emerging Players: Build out biological-nanocarrier convergence offerings targeting Uttar Pradesh horticultural export corridors where residue-sensitive grape and mango shippers seek sub-ppm detection solutions. Chitosan-lignin composite carriers for pH-responsive release present the most penetrable white-space. Direct contracting with farmer producer organizations bypasses entrenched distribution tiers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ecotoxicology testing infrastructure as EPA and EFSA particle characterization standards diverge. Five-to-ten year viability favors agricultural biotechnology firms with in-house OECD guideline interpretation capacity. The signal to watch is acquisition activity among Bavarian firms absorbing smaller competitors unable to fund duplicate chronic aquatic toxicity studies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Feedstock | Captive pyrethroid supply from Shandong Peninsula insulates against Chinese export quota volatility. |
| Solvent-Free Nanoencapsulation Scale-Up | Gujarat university partnerships cut manufacturing energy intensity relative to polymer alternatives. |
| Cooperative Procurement Platform Integration | Direct digital contracting with Punjab and Haryana consortia displaces legacy commission-based distribution. |
| Biological-Nanocarrier R&D Partnership | Chitosan-lignin composites for RNA interference payloads open mode-of-action categories against herbicide-resistant weeds. |
| Dual-Track Regulatory Dossier Development | Parallel EPA FIFRA and ECHA REACH submissions compress time-to-market across Atlantic markets. |
Research Methodology
Cross-validation between regulatory filing analysis and field-station trial documentation anchors the qualitative findings in this study. Primary interviews with formulation scientists at integrated agricultural conglomerates, regulatory affairs leads at specialty chemical firms, procurement managers at Indian agricultural cooperatives, and technical directors at contract research organizations combined with secondary validation from EPA FIFRA registration databases, ECHA REACH dossier submissions, OECD test guideline publications, and customs trade data for technical-grade pyrethroid feedstock. Bottom-up segmentation modeling and top-down macroeconomic calibration triangulate volume estimates.
Calibration against historical nanoemulsion adoption curves in Brazil's Cerrado and polymer-carrier penetration in Germany's Bavaria validates projection assumptions across the analysis window. Segmentation dimensions modeled include formulation chemistry, carrier technology, crop application type, and distribution channel structure. CAGRs derive from logistic diffusion curves fitted to precision agriculture infrastructure deployment rates and regulatory approval timeline distributions. Industry-specific forecast inputs incorporate cooperative procurement tender volume data and university-industry partnership pipeline disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed chemical conglomerates into downstream nanoencapsulation would shift outcomes. Regulatory divergence between EPA and EFSA particle characterization standards presents revision risk to market access timeline assumptions. Quarterly review of ECHA guidance document updates and Indian Central Insecticides Board amendment notices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Nanomaterial Supercapacitors Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Nano Copper Oxide Market