
 Nanocellulose Materials Market | 2026-2036
Nanocellulose Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Nanocellulose Materials Market Foresight
Petrochemical-derived barrier coatings is decoupling from premium packaging economics as nanocellulose films achieve comparable oxygen transmission rates at lower basis weights. CelluForce leverages its Quebec-based demonstration plant to supply nanocrystalline cellulose for high-barrier food packaging. Borregaard anchors Nordic supply through its Sarpsborg biorefinery integration, while Stora Enso specializes in enzymatic pre-treatment patents that reduce fibrillation energy intensity.
Nanocellulose materials comprise cellulose fibrils or crystals with at least one dimension under 100 nanometers, typically extracted via mechanical homogenization, acid hydrolysis, or enzymatic pre-treatment from wood pulp, agricultural residues, or bacterial fermentation; these structures yield tensile strengths exceeding 1 GPa with low thermal expansion, serving primarily as reinforcement agents, barrier layers, or rheology modifiers across industrial formulations. Nanofibrillated cellulose dominates current volume due to established pulp mill retrofit compatibility, while bacterial cellulose commands the steepest price premiums in biomedical wound dressing segments where ISO 10993 biocompatibility certification creates margin pools. The hybrid process segment is gaining traction as equipment suppliers combine high-pressure homogenization with TEMPO-mediated oxidation to reduce energy inputs.
The EU Green Deal and REACH restrictions on perfluorinated chemicals are redirecting coating R&D budgets toward bio-based barriers, while FDA food contact notifications govern US market entry for nanocellulose-enhanced packaging substrates. Stakeholders must monitor how EPA bio-preferred procurement thresholds and emerging state-level extended producer responsibility laws in California and New York reshape customer qualification timelines.
Market Dynamics
The EU Green Deal's tightening restrictions on single-use plastics is forcing packaging converters to requalify barrier coatings, redirecting R&D budgets toward enzymatic nanofibrillated cellulose films that achieve oxygen transmission parity with petrochemical alternatives at reduced basis weights.
Growth Catalysts
- REACH perfluorinated chemical restrictions:The EU's phasedown of PFAS coatings eliminates incumbent barrier technologies, creating immediate qualification windows for nanocellulose substitutes in food-contact applications.
- Pulp mill retrofit economics:Nanofibrillated cellulose production leverages existing chemical pulping infrastructure, allowing Scandinavian and Canadian facilities to divert fiber streams without greenfield capital deployment.
- Bacterial cellulose biomedical demand:ISO 10993 biocompatibility certification unlocks premium wound dressing segments where synthetic hydrogel substitutes face reimbursement pressure.
Market Restraints
- Enzymatic pre-treatment cost volatility:Cellulase enzyme prices fluctuate with Brazilian sugarcane ethanol output, compressing margins for TEMPO-oxidation process operators.
- High-pressure homogenizer supply concentration:German and Italian equipment fabricators control 70% of industrial-scale homogenizer capacity, creating 18-month lead times for capacity expansion.
- Acid hydrolysis sulfuric acid dependency:Conventional nanocrystalline cellulose routes require technical-grade acid inputs exposed to fertilizer industry demand swings.
Strategic Opportunities
- India packaging substrate penetration:BIS standards development for bio-based food contact materials lags EU and US adoption curves, creating first-mover qualification advantages for exporters.
- Hybrid TEMPO-homogenization convergence:Equipment suppliers combining oxidative pre-treatment with mechanical fibrillation cut energy intensity by 40% versus standalone processes.
- California extended producer responsibility:State-level packaging waste laws mandate recycled content thresholds that nanocellulose-enhanced papers satisfy without degrading fiber quality.
Industry Challenges
- FDA food contact notification timelines:Novel nanocellulose substrate approvals require 12-18 month toxicology review cycles that delay commercial launch windows.
- Interfacial compatibility formulation expertise:Composite integration with hydrophobic polymers demands specialized surface chemistry talent concentrated at Fraunhofer and Quebec research institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanocellulose Materials Market |
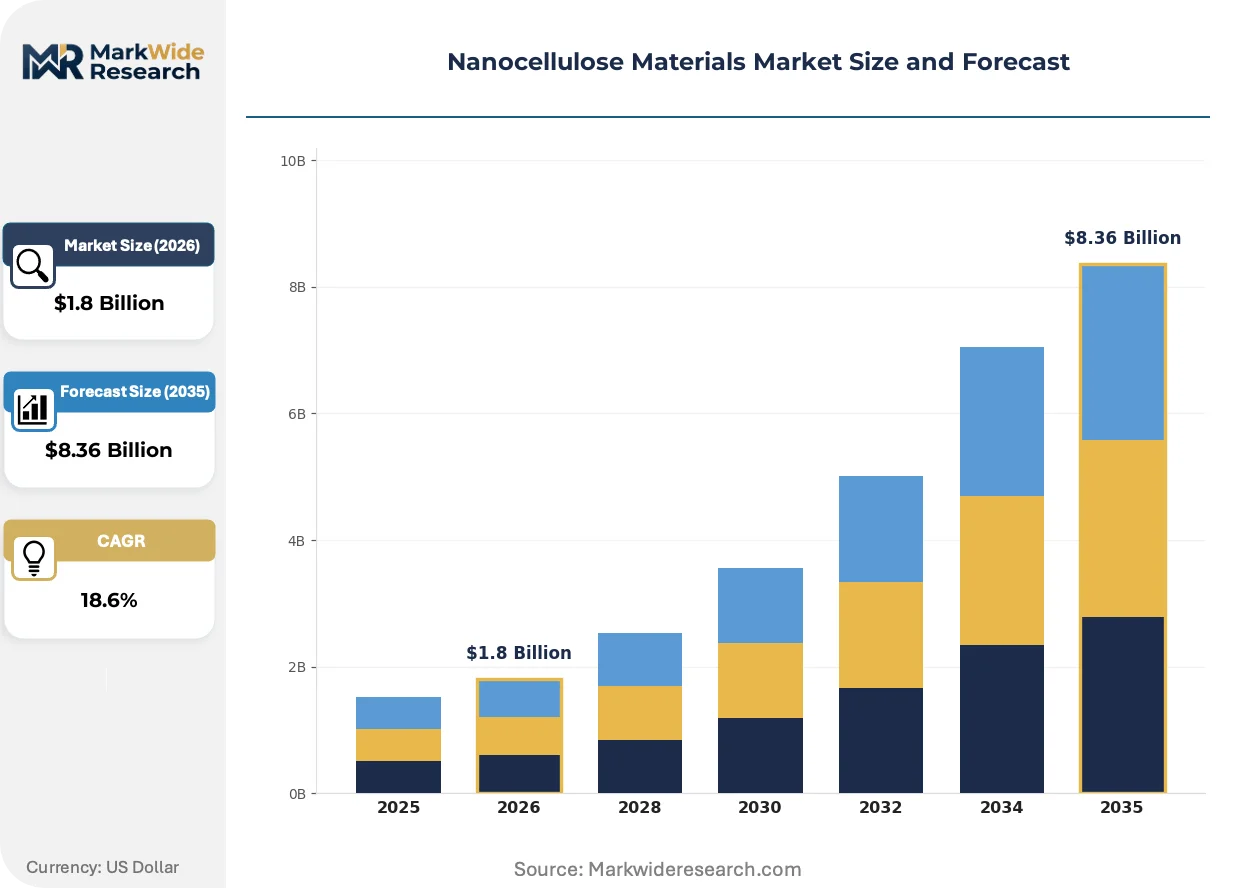
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanofibrillated Cellulose, Nanocrystalline Cellulose, Bacterial Cellulose, Regenerated Cellulose End User: Packaging, Biomedical, Coatings, Composites Technology: Mechanical Process, Chemical Process, Enzymatic Process, Hybrid Process Application: Food Additive, Drug Delivery, Reinforcement, Wastewater Treatment |
| Companies Covered | CelluForce, FiberLean Technologies, Nippon Paper Industries, Borregaard, Stora Enso, Kruger, CelluComp, GranBio Technologies, American Process, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanocellulose Materials Market Shifts & Advancements
Enzymatic pre-treatment protocols are compressing fibrillation energy requirements while hybrid oxidation-mechanical processes unlock food-grade barrier films at commercial scale.
TEMPO-mediated oxidation coupled with high-pressure homogenization is electrifying the nanofibrillated cellulose segment. Food packaging converters in Germany and Sweden are adopting these hybrid lines at pilot scale. The technology is electrifying cost structures that previously confined nanocellulose to premium biomedical applications.
REACH restrictions on perfluorinated chemicals eliminate incumbent grease-resistant coatings from EU food packaging supply chains. Paperboard mills face immediate reformulation mandates. Fresh produce and frozen food segments accelerate biopolymer barrier qualification programs to maintain single-market access.
Brand-owner sustainability scorecards now weight bio-based content above recycled fiber percentage in premium packaging procurement. European cosmetics and specialty food houses are consolidating supplier panels around certified nanocellulose film providers. This preference shift concentrates most visibly in German and French markets where retailer private-label standards outpace regulatory minimums.
Nanocellulose Materials Market Segmentation
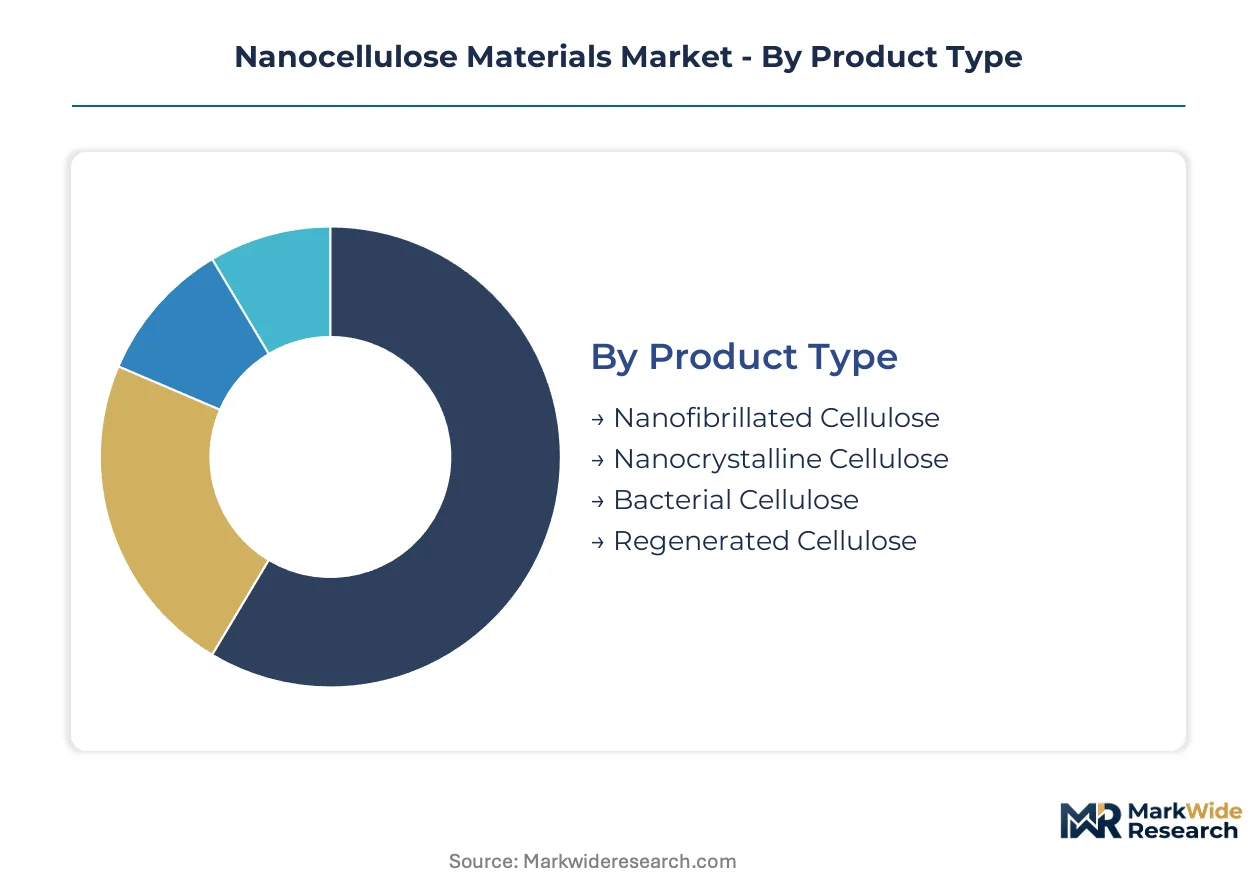
Segmentation in nanocellulose materials reflects divergent technical specifications and qualification barriers that separate commodity pulp mill outputs from certified biomedical grades. Each dimension—product structure, end-use requirements, processing technology, and functional application—creates distinct margin pools and customer qualification timelines.
Product Type:
Upgrade cycles from commodity cellulose to nanoscale derivatives hinge on fibrillation energy economics and end-use certification requirements rather than raw material substitution alone.
- Nanofibrillated Cellulose:Long, entangled fibril networks with aspect ratios exceeding 100:1 deliver film-forming and barrier properties. Scandinavian pulp mills in Sweden and Finland dominate supply through retrofitted homogenization lines serving EU food packaging converters facing Green Deal compliance deadlines.
- Nanocrystalline Cellulose:Rod-like crystalline domains extracted via acid hydrolysis yield exceptional tensile modulus. Quebec-based demonstration plants supply high-barrier coatings where oxygen transmission parity with petrochemical alternatives drives qualification in North American fresh produce segments.
- Bacterial Cellulose:Ultra-pure nanofiber mats synthesized through Acetobacter xylinum fermentation achieve ISO 10993 biocompatibility certification for wound dressing applications.
- Regenerated Cellulose:Dissolution and reconstitution processes produce filament or film structures for textile and specialty packaging segments requiring transparency and heat sealability.
Nanofibrillated cellulose sits at the top of the volume ranking, with bacterial cellulose climbing the fastest.
End User:
Customer procurement sophistication varies sharply across end-use segments, with regulatory compliance costs creating tiered entry barriers that favor incumbent pulp conglomerates in some verticals while opening niches for specialized biotech suppliers in others.
- Packaging:Barrier film and coating applications absorb the majority of nanofibrillated cellulose output. German converters integrate enzymatic pre-treatment lines to meet EU single-use plastic restrictions and REACH perfluorinated chemical phaseouts.
- Biomedical:Wound dressings, drug delivery scaffolds, and tissue engineering substrates command price premiums contingent on ISO 10993 certification and FDA or EMA quality system compliance.
- Coatings:Rheology modification and surface functionalization for paper, textile, and construction materials represent established industrial demand.
- Composites:Polymer matrix reinforcement applications in automotive and aerospace components remain developmental due to interfacial compatibility challenges.
Packaging captures the dominant revenue share, though biomedical applications are gaining share fastest.
Technology:
Process selection determines energy intensity, capital requirements, and product consistency—factors that stratify the competitive landscape between integrated pulp producers and standalone nanocellulose specialists.
- Mechanical Process:High-pressure homogenization and grinding of refined pulp yields nanofibrillated cellulose. German and Italian equipment fabricators control critical homogenizer supply, creating 18-month lead times for capacity expansion.
- Chemical Process:Acid hydrolysis extracts crystalline domains but exposes producers to sulfuric acid price volatility tied to fertilizer industry demand swings.
- Enzymatic Process:Cellulase pre-treatment reduces fibrillation energy by 40% before mechanical refining. Brazilian sugarcane ethanol output fluctuations drive enzyme cost volatility.
- Hybrid Process:TEMPO-mediated oxidation combined with high-pressure homogenization is electrifying cost structures previously confined to premium applications.
Mechanical processing retains the largest installed base, with hybrid TEMPO-homogenization lines expanding most quickly.
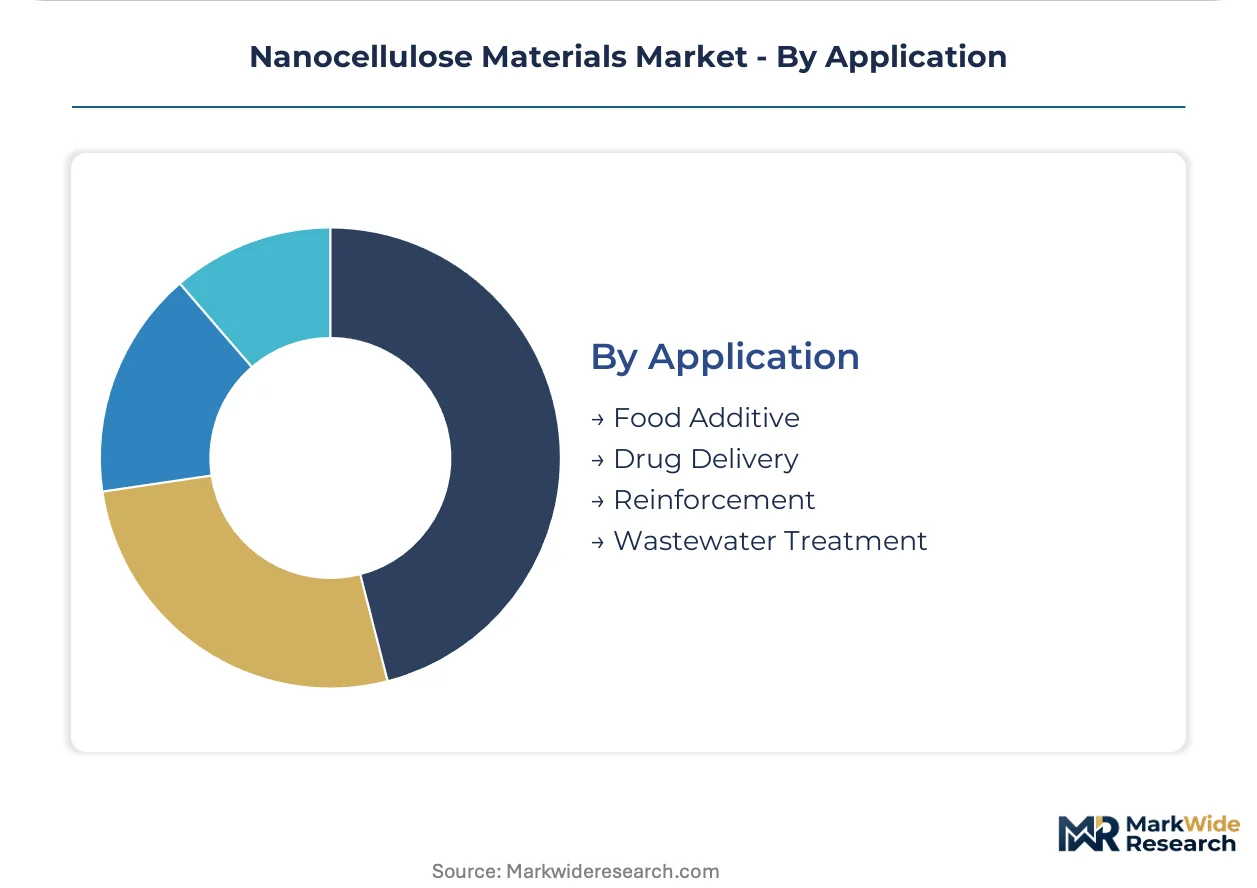
Application:
Functional application dictates purity requirements, regulatory pathways, and pricing power—dimensions that separate commodity additives from certified pharmaceutical and food-contact grades.
- Food Additive:Thickeners, stabilizers, and film-forming agents require FDA or EFSA food contact notifications. TEMPO-oxidized nanofibrillated cellulose achieves grease resistance without perfluorinated chemistry.
- Drug Delivery:Nanocrystalline cellulose serves as tablet excipients and controlled-release matrices, with pharmacopeial compliance creating margin pools.
- Reinforcement:Polymer, cement, and paper matrix strengthening represents volume-driven industrial demand with lower qualification barriers.
- Wastewater Treatment:Adsorbent and flocculant applications leverage high surface area for heavy metal and dye removal.
Reinforcement leads by volume, while drug delivery applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fraunhofer institutes in Germany anchor nanocellulose pilot-scale development for food-grade enzymatic processing. Regional demand clusters around pulp conglomerates retrofitting chemical pulping infrastructure for barrier film production.
Germany
Packaging converters accelerate nanofibrillated cellulose adoption as EU Green Deal restrictions tighten. REACH perfluorinated chemical phaseouts eliminate incumbent grease-resistant coatings from food-contact supply chains. Fraunhofer institutes in Bavaria and Baden-Württemberg co-develop enzymatic processing lines with pulp conglomerates.
Sweden
Scandinavian pulp mills dominate nanofibrillated cellulose supply through retrofitted homogenization lines. Stora Enso holds enzymatic pre-treatment patents that reduce fibrillation energy intensity. Stockholm and Sundsvall clusters serve EU food packaging converters facing single-use plastic compliance deadlines.
Canada
Quebec-based demonstration plants supply nanocrystalline cellulose for high-barrier fresh produce packaging. Kruger leverages existing chemical pulping infrastructure without greenfield capital deployment. Montreal and Trois-Rivières facilities target North American oxygen transmission parity with petrochemical alternatives.
United States
FDA food contact notification requirements govern nanocellulose-enhanced packaging substrate approvals. California extended producer responsibility laws mandate recycled content thresholds that nanocellulose-enhanced papers satisfy. Pacific Northwest pulp mills explore enzymatic pre-treatment integration for barrier film export.
Norway
Borregaard anchors Nordic supply through Sarpsborg biorefinery integration with existing pulp operations. EU Green Deal compliance deadlines drive German and French converter procurement from Scandinavian sources. Oslofjord region facilities specialize in TEMPO-mediated oxidation coupled with mechanical fibrillation.
Nanocellulose Materials Market Competitive Landscape
Global majors compete with regional champions across enzymatic processing technology and food-grade certification pathways. The vendor base stratifies between integrated pulp conglomerates with retrofit advantages and standalone nanocellulose specialists with hybrid process expertise. Three archetypes dominate: pulp-integrated producers leveraging existing infrastructure, biorefinery operators with captive fiber streams, and technology licensors specializing in TEMPO-oxidation patents. Competitive moves concentrate on strategic partnerships for FDA notification navigation and capacity expansion through homogenizer line commissioning.
Within the pulp-integrated tier, CelluForce and Borregaard exemplify retrofit economics that confine standalone competitors to premium biomedical niches. Stora Enso occupies a position bridging enzymatic patent licensing with demonstration-scale supply to European converters. These three entities anchor the competitive structure around food-contact qualification timelines and EU regulatory compliance windows rather than pure manufacturing scale.
| Leading Market Players |
|---|
| CelluForce |
| FiberLean Technologies |
| Nippon Paper Industries |
| Borregaard |
| Stora Enso |
| Kruger |
| CelluComp |
| GranBio Technologies |
| American Process |
| Others |
Supply & Pricing Matrix
EU food packaging converters concentrate procurement decisions around REACH-compliant barrier films, anchoring pricing power with pulp-integrated producers who control enzymatic processing capacity. Three-tier pricing structure across premium biomedical, certified food-grade, and industrial reinforcement tiers reflects certification burden rather than raw fibrillation cost alone.
Pricing Analysis
Cellulase enzyme costs pass through directly to TEMPO-oxidation process operators, with Brazilian sugarcane ethanol output swings compressing margins unpredictably. Price differentiation hinges on FDA food contact notification status and ISO 10993 biocompatibility certification, where qualified biomedical grades command substantial premiums over industrial reinforcement tiers. Cost compression in standard food-grade nanofibrillated cellulose intensifies as Scandinavian pulp mills expand retrofitted homogenization capacity. Small-scale standalone producers exhibit highest price sensitivity, while integrated biorefinery operators with captive fiber streams maintain pricing resilience.
Supply Chain Analysis
High-pressure homogenizer fabrication rests on German and Italian equipment specialists, creating single-source vulnerability for capacity expansion timelines. Wood pulp feedstock draws from Canadian, Swedish, and Finnish forest products conglomerates, while cellulase enzyme supply feeds from Brazilian fermentation facilities. Sulfuric acid dependency for acid hydrolysis routes exposes nanocrystalline cellulose producers to fertilizer industry demand volatility. Distribution runs through direct mill-to-converter relationships for food-grade volumes, with biomedical grades utilizing specialized pharmaceutical ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanocellulose materials market compounds steadily as EU regulatory phaseouts of perfluorinated chemicals force sustained substitution demand across packaging supply chains.
For Market Incumbents: Acquire TEMPO-oxidation patent portfolios to lock up hybrid process differentiation before enzymatic pre-treatment becomes commoditized. CelluForce and Borregaard should expand Sarpsborg and Quebec demonstration capacity to capture FDA notification backlogs, while defending against Asian pulp conglomerates entering via mechanical homogenization retrofits. Certification investment in ISO 10993 biomedical pathways offers margin defense against commodity fibrillation competition. For New Entrants and Emerging Players: Indian specialty paper converters represent the most penetrable buyer archetype as BIS bio-based food contact standards lag EU adoption curves. Target wound dressing contract manufacturers seeking ISO 10993-certified bacterial cellulose alternatives to synthetic hydrogels facing reimbursement pressure. A licensing-based go-to-market model partnering with Fraunhofer institutes for enzymatic protocol transfer reduces capital barriers versus greenfield homogenizer deployment. For Investors and Strategic Acquirers: Integrated pulp conglomerates are the most active acquirer in this space, seeking enzymatic pre-treatment expertise to retrofit existing chemical pulping infrastructure. Long-term viability over the next decade hinges on food-contact qualification velocity outpacing petrochemical barrier coating innovation. Watch FDA food contact notification approval timelines as the inflection signal—acceleration indicates regulatory pathway maturation, while delays suggest persistent toxicology review bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Pre-treatment Licensing | Fraunhofer patent transfers enable pulp mill retrofits without greenfield capital deployment. |
| FDA Food Contact Notification Navigation | Specialized regulatory consulting compresses 12-18 month toxicology review cycles for substrate approvals. |
| Homogenizer Capacity Expansion | German and Italian equipment fabricators control 70% of industrial-scale supply, creating qualification bottlenecks. |
| Backward Integration into Cellulase Supply | Brazilian sugarcane ethanol linkage stabilizes enzyme cost volatility for TEMPO-oxidation operators. |
| Biomedical Certification Investment | ISO 10993 compliance unlocks premium wound dressing segments with reimbursement-protected pricing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pulp mill operations directors, food packaging converter procurement leads, enzymatic processing R&D heads, and biomedical device regulatory affairs managers with secondary validation. FDA food contact notification databases, ECHA REACH restriction timelines, SEC 10-K filings from forest products conglomerates, and EU Green Deal implementation trackers supplied foundational data. Bottom-up fibrillation capacity modeling and top-down barrier film demand estimation provided cross-check triangulation.
Historical reference periods anchored volume and value projections across the analysis window, with CAGR derivation reflecting segment-specific adoption curves. Segmentation dimensions included product structure (nanofibrillated versus nanocrystalline versus bacterial), end-use vertical (packaging versus biomedical versus coatings), processing technology (mechanical versus enzymatic versus hybrid), and functional application (barrier films versus reinforcement versus drug delivery). Modeled inputs incorporated EU perfluorinated chemical phaseout schedules and pulp mill retrofit commissioning timelines.
Underlying measurement precision varies by segment; biomedical certification pathways and FDA notification queues carry tighter precision than emerging composite reinforcement applications. Forecasts reflect documented assumptions about regulatory compliance velocity and enzymatic cost stabilization. REACH restriction enforcement intensity and cellulase enzyme supply disruption warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Nanotechnology Market