
 Molybdenum Trioxide Nanopowder Market | 2026-2036
Molybdenum Trioxide Nanopowder Market Size, Share, and Industry Trends Forecast 2026-2036
Molybdenum Trioxide Nanopowder Market Outlook
China's expanding rare earth refining corridor is reconfiguring regional supply dynamics for molybdenum trioxide nanopowder. Nanografi Nano Technology leverages its Ankara-based synthesis facilities to serve European catalyst producers with ISO-certified batches. US Research Nanomaterials Inc. sustains a dominant position in North American research-grade distribution through direct university contracts. Merck KGaA anchors its portfolio with pharmaceutical-grade specifications that meet EMA impurity thresholds.
Molybdenum trioxide nanopowder consists of nanoscale MoO3 particles typically ranging from 10 to 100 nanometers in primary crystallite size, produced via sol-gel precipitation or flame spray pyrolysis, and functions primarily as a catalytic active phase, electrochromic layer, and photovoltaic buffer material. High purity powder commands premium positioning due to semiconductor-grade trace metal constraints below 10 ppm total impurities. The catalysts application segment leads current volume offtake, while photovoltaics represents the fastest structural expansion as perovskite cell architectures commercialize. Electronics manufacturers as an end-user category concentrate margin pools through long-term qualification contracts and customized particle morphology requirements.
EPA nanomaterial reporting rules under TSCA Section 8(a) mandate production volume and exposure data from U.S. manufacturers and importers, while REACH registration in Europe enforces full toxicological dossiers for nanoform substances above one tonne annual volume. China's GB standards for nanomaterials, administered by SAMR, impose mandatory labeling and safety data sheet provisions that affect export market access. South Korea's MFDS maintains separate cosmetic and pharmaceutical nano-ingredient guidelines that filter cross-border trade eligibility. Stakeholders must monitor evolving purity certification reciprocity between these jurisdictions to avoid qualification gaps in qualified supplier programs.
Market Dynamics
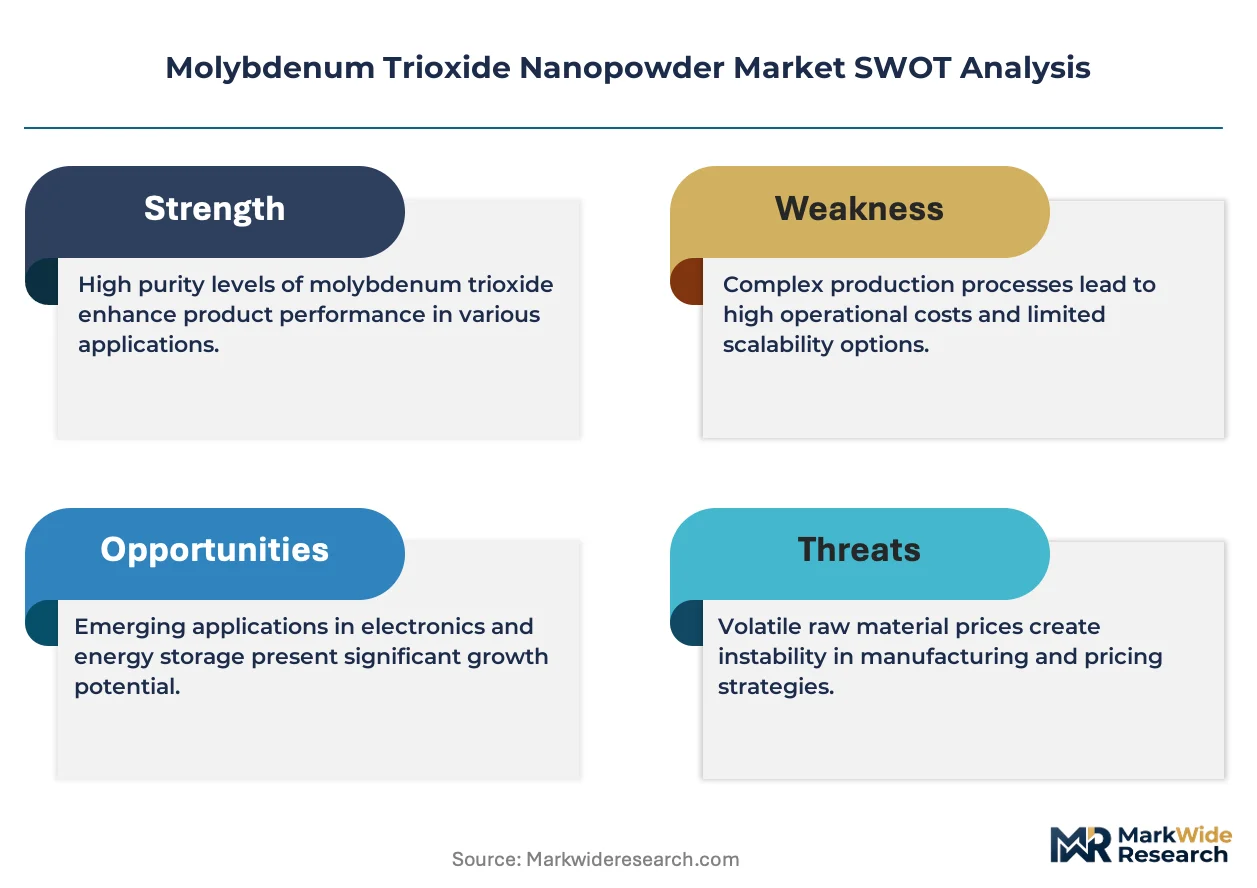
Perovskite solar cell commercialization is concentrating semiconductor-grade molybdenum trioxide nanopowder procurement into long-term qualification contracts with East Asian electronics supply chains, compressing spot market liquidity and elevating purity documentation requirements.
Growth Catalysts
- Perovskite buffer layers:Photovoltaic manufacturers in South Korea are locking multi-year supply agreements for sub-50 nm particle specifications to secure qualification slots for next-generation tandem cell architectures.
- REACH nanoform registration:European catalyst producers are advancing toxicological dossiers for MoO3 nanoforms above one tonne annual volume, creating first-mover certification premiums for compliant suppliers.
- Flame spray pyrolysis scale-up:Synthesis equipment makers are delivering modular production units that reduce batch-to-batch particle size variance below 5% coefficient of variation.
Market Restraints
- Ammonium molybdate feedstock volatility:Rare earth refining corridor expansions in China are tightening technical-grade molybdenum concentrate availability, transmitting cost pressure to nanopowder conversion margins.
- Single-source synthesis equipment:Flame spray pyrolysis reactor fabrication concentrates among German and Swiss precision engineering suppliers, creating 14-18 month order backlogs for capacity expansion.
- Tungsten oxide substitution:Electrochromic device developers are qualifying tungsten oxide nanopowder for smart window applications where optical modulation speed requirements are less stringent.
Strategic Opportunities
- Indian pharmaceutical nano-ingredients:CDSCO is finalizing guidelines for nanomaterial-containing drug formulations, opening qualification pathways for MoO3 catalytic intermediates in active pharmaceutical ingredient synthesis.
- Solid-state battery cathode coatings:Sulfide electrolyte interface engineering is hybridizing MoO3 nanopowder with lithium thiophosphate composites to suppress dendrite propagation.
- US IRA clean energy manufacturing credits:Domestic content bonuses for solar module assembly are incentivizing perovskite supply chain localization and qualified supplier program development.
Industry Challenges
- ISO 17025 analytical talent scarcity:Inductively coupled plasma mass spectrometry operators capable of sub-10 ppm trace metal validation are commanding 40% wage premiums above general materials testing personnel.
- Multi-jurisdiction certification reciprocity gaps:EPA TSCA Section 8(a) nanomaterial reporting data packages lack automatic acceptance under REACH registration requirements, forcing redundant toxicological study commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molybdenum Trioxide Nanopowder Market |
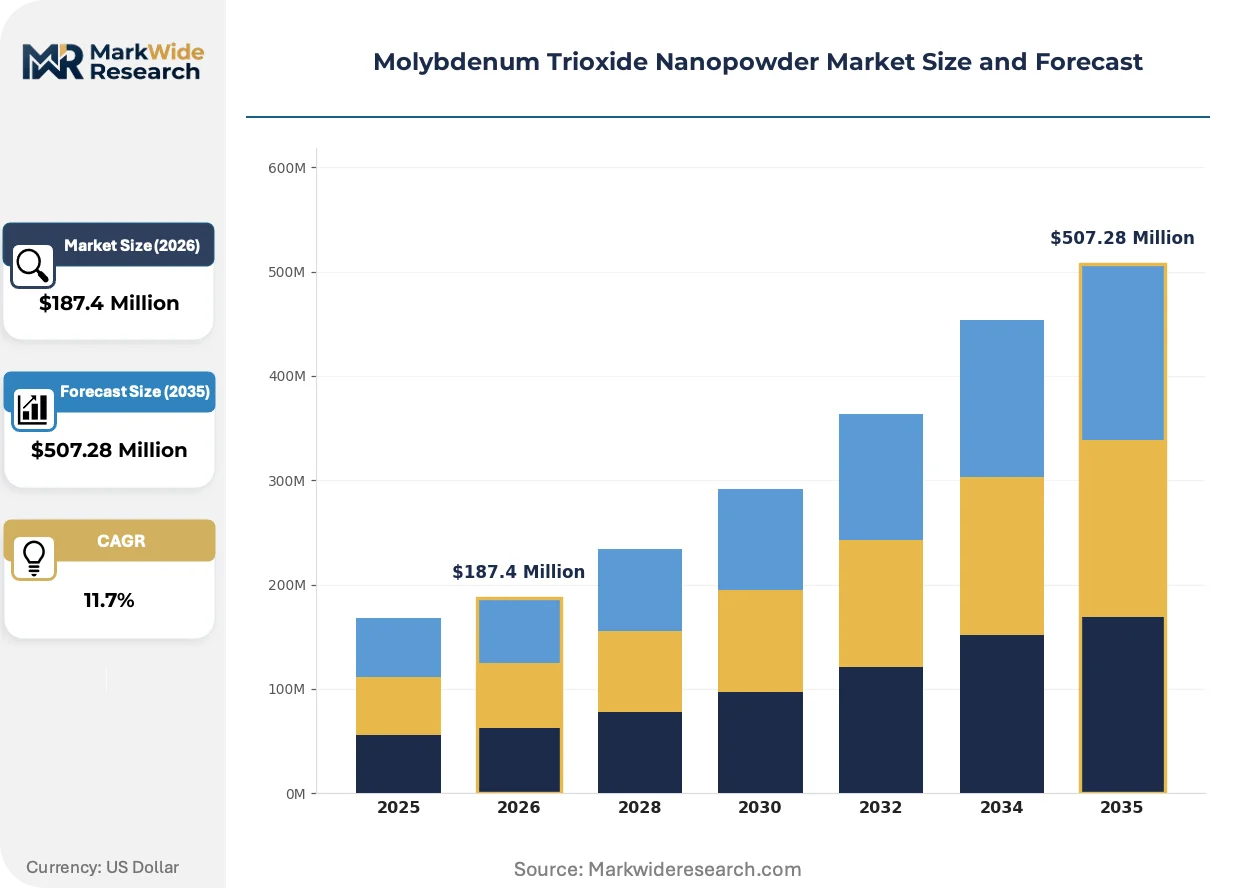
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Powder, Coated Powder, Customized Powder, High Purity Powder Application: Catalysts, Electronics, Photovoltaics, Coatings End User: Aerospace, Medical Devices, Electronics Manufacturers, Research Institutions Distribution Channel: Direct Sales, Online Sales, Third-Party Distributors, Specialty Stores |
| Companies Covered | Nanografi Nano Technology, US Research Nanomaterials Inc., Nanoshel LLC, Merck KGaA, Novarials Corporation, SkySpring Nanomaterials Inc., SAT Nano Technology Material Co. Ltd., Edgetech Industries LLC, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molybdenum Trioxide Nanopowder Market Strategic Shifts
MoO3 nanopowder synthesis and application engineering are converging around precision particle morphology control, regulatory data package standardization, and demand-side qualification contract structures that favor integrated supply relationships over transactional procurement.
Sol-gel precipitation with supercritical drying is hybridizing flame spray pyrolysis outputs to produce hierarchical pore structures for catalytic applications. Petrochemical crackers in the US Gulf Coast are adopting these bimodal pore distributions for heavy oil upgrading catalysts. The structural consequence is compressing conventional precipitation-calcination equipment demand while elevating supercritical fluid processing unit orders.
EPA nanomaterial reporting rules under TSCA Section 8(a) are mandating production volume and exposure data submissions from US manufacturers and importers. Industrial consequence includes forced disclosure of proprietary particle size distribution methodologies to competitors through public chemical data reporting. Small-volume specialty chemical distributors are responding by consolidating import volumes through qualified third-party representatives to minimize direct reporting obligations.
Electronics manufacturers are consolidating qualified supplier programs around semiconductor-grade trace metal specifications below 10 ppm total impurities. Long-term contracts with 36-48 month duration are displacing spot procurement for high-purity grades. South Korean display panel producers are most visible in this shift, leveraging parent company chemical subsidiary relationships to secure captive nanopowder supply.
Molybdenum Trioxide Nanopowder Market Segmentation
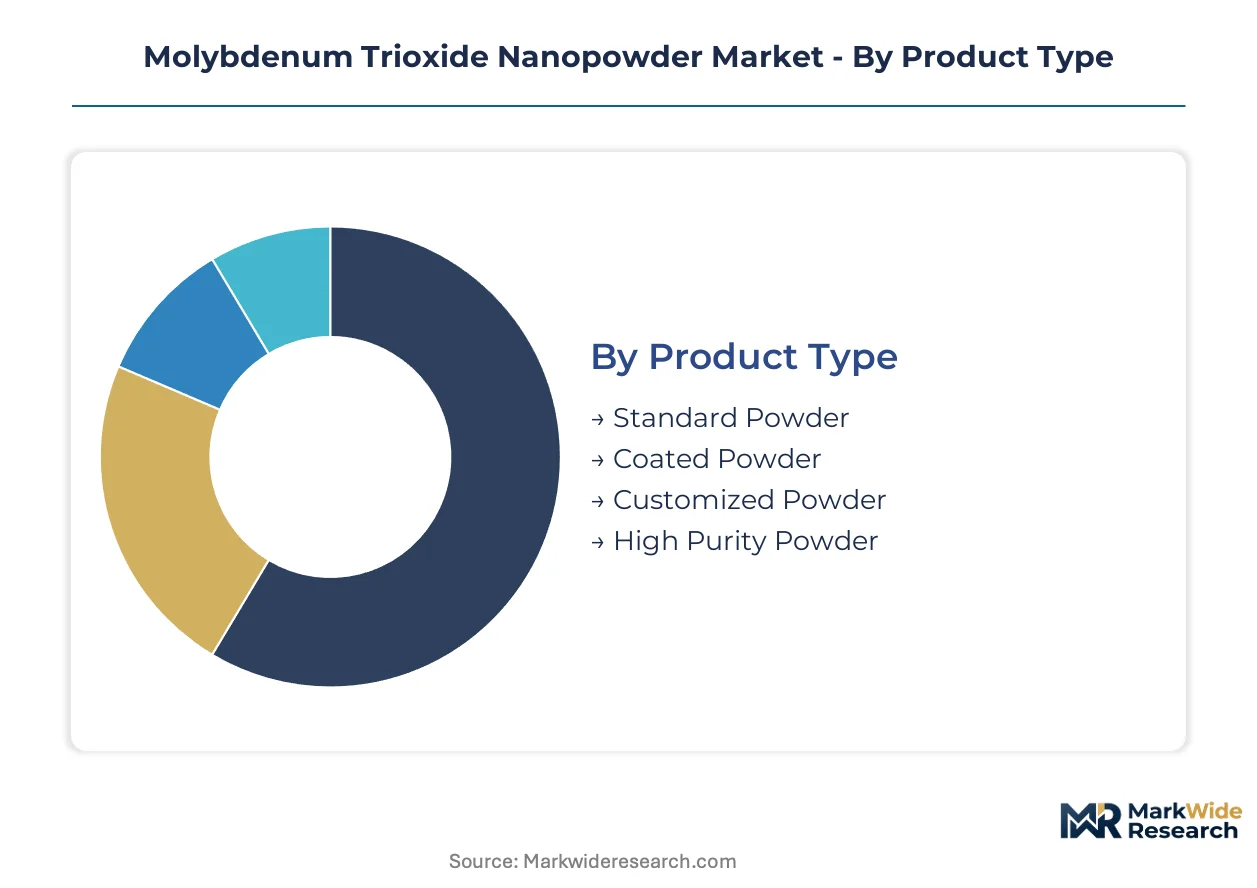
Molybdenum trioxide nanopowder procurement splits across purity grades, synthesis customization, and end-use qualification requirements. Each dimension carries distinct margin structures and regulatory documentation burdens that reshape supplier-customer contracting patterns.
Product Type:
Purity tier and particle morphology control define cost positioning and application eligibility across semiconductor, catalytic, and research markets.
- High Purity Powder:Semiconductor-grade specifications enforce total trace metal impurities below 10 ppm through inductively coupled plasma mass spectrometry validation. South Korean electronics supply chains are locking 36-48 month qualification contracts for sub-50 nm crystallite sizes to secure perovskite tandem cell buffer layer slots.
- Customized Powder:Tailored particle size distributions and surface functionalizations serve proprietary catalyst formulations and electrochromic device architectures. Flame spray pyrolysis reactors with modular configuration enable batch-to-batch variance below 5% coefficient of variation for these specifications.
- Standard Powder:Technical-grade material serves industrial catalyst precursors and ceramic pigment applications where trace metal constraints exceed 100 ppm.
- Coated Powder:Surface-passivated variants with organic or inorganic shells enhance dispersion stability in polar and non-polar solvent systems for coating formulations.
High Purity Powder commands the established base. The steepest expansion runs through Customized Powder.
Application:
Functional end-use determines particle specification stringency, volume scale, and regulatory data package requirements.
- Catalysts:Petrochemical crackers and refinery operators deploy MoO3 nanopowder as hydrodesulfurization active phases. Bimodal pore structures from supercritical drying hybridization are displacing conventional precipitation-calcination equipment across US Gulf Coast facilities.
- Photovoltaics:Perovskite solar cell manufacturers specify sub-50 nm primary crystallites for electron transport layer deposition. East Asian electronics supply chains are compressing spot market liquidity through multi-year procurement agreements.
- Electronics:Electrochromic displays and thin-film transistors utilize MoO3 for optical modulation and hole injection layers.
- Coatings:Anti-corrosion and smart window applications integrate nanopowder into polymer matrices and ceramic overlays.
Catalysts anchor current volume offtake. Photovoltaics is climbing the fastest as perovskite commercialization accelerates.
End User:
Customer category shapes contract duration, technical service intensity, and purity documentation depth.
- Electronics Manufacturers:Display panel and semiconductor producers enforce qualified supplier programs with captive chemical subsidiary relationships. Long-term agreements displace spot procurement for high-purity grades.
- Research Institutions:Universities and national laboratories procure research-grade material through direct distributor contracts with flexible batch sizing.
- Aerospace:Thermal barrier coating and sensor applications require aerospace-grade trace metal certification.
- Medical Devices:Diagnostic and implantable device manufacturers navigate MFDS cosmetic and pharmaceutical nano-ingredient guidelines in South Korea.
Electronics Manufacturers concentrate margin pools through qualification barriers. Research Institutions deliver volume elasticity for emerging specifications.
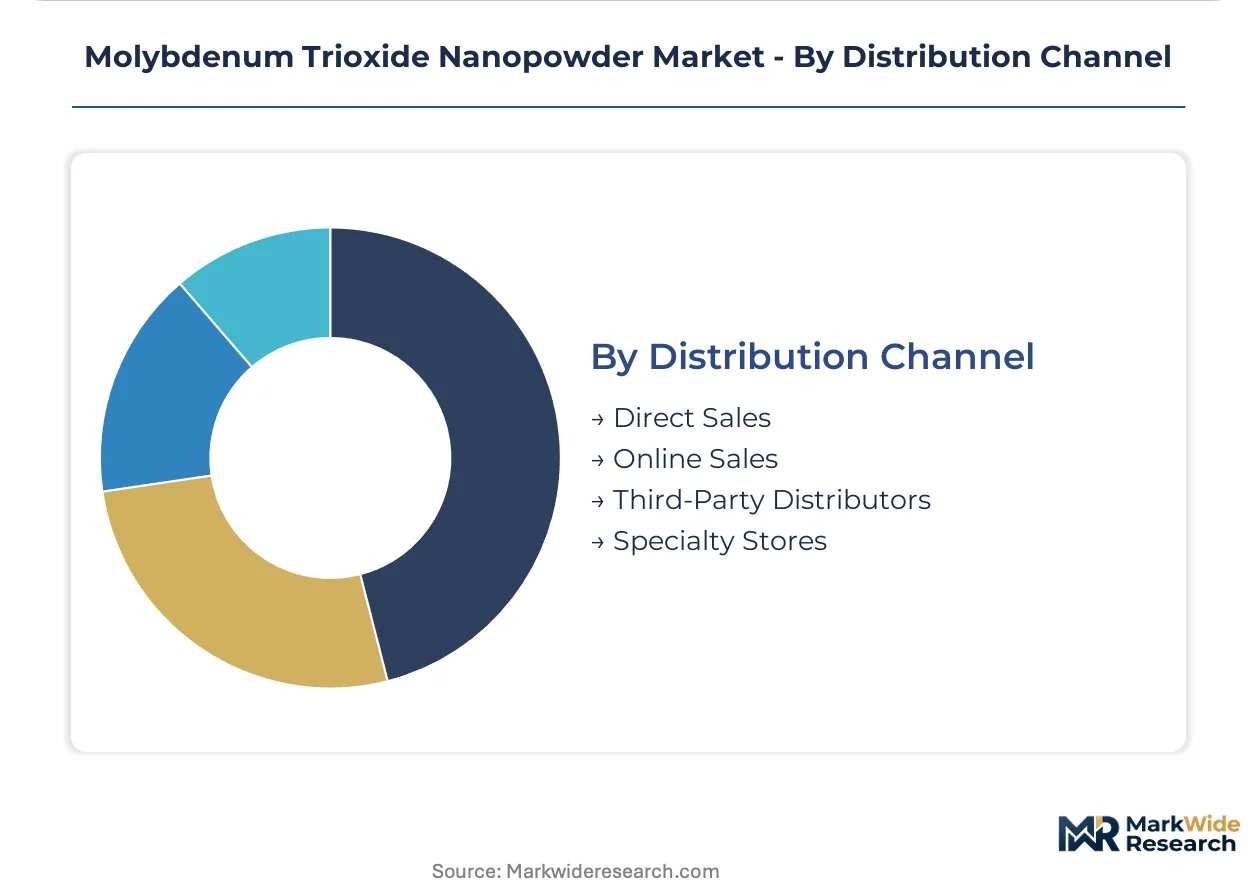
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and regulatory reporting obligations.
- Direct Sales:High-volume electronics and catalyst producers negotiate directly with synthesis facilities for customized specifications and multi-year supply security.
- Third-Party Distributors:Specialty chemical distributors consolidate import volumes to minimize EPA TSCA Section 8(a) nanomaterial reporting exposure for small-volume end users.
- Online Sales:Research-grade and standard powder move through digital procurement platforms for rapid quotation and sample fulfillment.
- Specialty Stores:Regional chemical supply houses serve local industrial users with technical consultation and inventory proximity.
Direct Sales captures the premium tier. Third-Party Distributors are gaining share fastest as regulatory complexity fragments import compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthesis capacity clusters in China, South Korea, Germany, and the United States, with each jurisdiction imposing distinct nanomaterial reporting obligations that reshape export market access. Qualified supplier programs in semiconductor supply chains concentrate procurement decisions within specific metropolitan chemical corridors.
China
Rare earth refining corridor expansions in Jiangxi and Inner Mongolia are tightening technical-grade molybdenum concentrate flows toward nanopowder conversion facilities. SAMR-administered GB standards mandate nanomaterial labeling and safety data sheet provisions that filter cross-border trade eligibility. Zhengzhou and Shanghai specialty chemical clusters are absorbing captive supply from integrated rare earth processors.
South Korea
Display panel producers in the Seoul Capital Area are locking 36-48 month qualification contracts for sub-50 nm crystallite specifications to secure perovskite tandem cell buffer layer slots. MFDS maintains separate cosmetic and pharmaceutical nano-ingredient guidelines that constrain dual-use material pathways. Busan-Ulsan petrochemical complexes are adopting bimodal pore structure catalysts for heavy oil upgrading.
Germany
REACH nanoform registration requirements above one tonne annual volume are forcing European catalyst producers to advance toxicological dossiers for MoO3 nanoforms. ECHA compliance timelines are creating first-mover certification premiums for suppliers with pre-submitted data packages. Leverkusen and Ludwigshafen chemical parks are consolidating flame spray pyrolysis capacity expansion orders amid 14-18 month equipment backlogs.
United States
EPA TSCA Section 8(a) nanomaterial reporting rules mandate production volume and exposure data submissions that force disclosure of proprietary particle size distribution methodologies. IRA clean energy manufacturing credits are incentivizing perovskite supply chain localization and domestic content bonus qualification. Texas Gulf Coast petrochemical crackers are deploying supercritical drying hybridization for bimodal pore catalyst structures.
Japan
Electronics material suppliers in the Kanto region are qualifying MoO3 nanopowder for electrochromic display and thin-film transistor hole injection layers. METI industrial nanomaterial guidelines coordinate with JIS standards for trace metal validation protocols. Osaka-based specialty chemical distributors are consolidating import volumes to minimize direct EPA reporting exposure for research-grade end users.
Molybdenum Trioxide Nanopowder Market Competitive Environment
Integrated chemical conglomerates and specialized nanomaterial synthesis houses split the market along purity-tier and qualification-depth vectors. The vendor base organizes around three strategic archetypes: captive electronics chemical subsidiaries with multi-year contract structures, independent flame spray pyrolysis operators serving research and catalyst markets, and diversified materials distributors consolidating regulatory compliance burdens. Dominant competitive moves include backward integration into ammonium molybdate feedstock security and technology licensing partnerships for modular synthesis equipment deployment.
Among Turkey-based synthesis specialists, Nanografi Nano Technology occupies a position exemplifying the independent operator archetype serving European catalyst producers with ISO-certified batch structures. US Research Nanomaterials Inc. and Merck KGaA represent contrasting scale tiers within the research-grade and pharmaceutical-grade distribution channels respectively. These three anchors illustrate how geographic origin and corporate structure suffixes map onto divergent purity documentation and end-market qualification strategies.
| Leading Market Players |
|---|
| Nanografi Nano Technology |
| US Research Nanomaterials Inc. |
| Nanoshel LLC |
| Merck KGaA |
| Novarials Corporation |
| SkySpring Nanomaterials Inc. |
| SAT Nano Technology Material Co. Ltd. |
| Edgetech Industries LLC |
| American Elements |
| Others |
Value Chain & Pricing Dynamics
Flame spray pyrolysis reactor order backlogs stretching 14-18 months signal acute undercapacity in precision synthesis equipment, compressing supplier margins on ammonium molybdate conversion while amplifying pricing power for qualified batch producers with secured equipment slots. REACH nanoform registration deadlines and EPA TSCA Section 8(a) reporting burdens layer compliance premiums onto high-purity grades, widening spreads between certified and technical-tier quotations.
Pricing Analysis
REACH nanoform registration dictates the pricing tier structure across European catalyst procurement, with ECHA-compliant suppliers commanding 15-20% premiums over uncertified competitors. Three-tier pricing structure across semiconductor-grade, customized catalyst, and technical pigment levels segments buyers by trace metal tolerance and particle morphology stringency. Cost compression in technical-grade material intensifies because Chinese rare earth refining corridors are tightening molybdenum concentrate flows. Research institutions exhibit highest price sensitivity due to fragmented order volumes, while South Korean electronics manufacturers absorb premium positioning through captive chemical subsidiary relationships.
Supply Chain Analysis
Export control regimes on precision thermal spray equipment limit flame spray pyrolysis reactor flows from German and Swiss engineering houses to Asian synthesis facilities, constraining capacity expansion timelines. Supply concentrates in China, South Korea, and Germany, with Jiangxi rare earth corridors and Seoul Capital Area display clusters anchoring regional output. Raw material flows draw from ammonium molybdate feedstock, technical-grade molybdenum concentrate, and supercritical fluid processing solvents. Single-source vulnerability runs through flame spray pyrolysis reactor fabrication, where two precision engineering suppliers control global equipment availability. Distribution runs through direct sales for high-volume electronics contracts and third-party distributors consolidating regulatory compliance for smaller research-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite solar cell commercialization cycles are lifting molybdenum trioxide nanopowder demand from trough conditions, with South Korean tandem cell qualification timelines providing visible recovery confirmation. Equipment order backlogs and regulatory certification premiums suggest margin expansion ahead for positioned suppliers.
For Market Incumbents: Entrench qualified supplier program relationships through 36-48 month contract extensions before South Korean perovskite capacity scales. Secure backward integration into ammonium molybdate feedstock to defend against Chinese rare earth corridor tightening. Invest in ISO 17025 analytical talent retention as ICP-MS operator scarcity threatens batch release timelines. For New Entrants and Emerging Players: Pursue Indian pharmaceutical nano-ingredient qualification ahead of CDSCO guideline finalization, where incumbent presence remains thin. Target research-grade distribution through university direct contracts as the most penetrable entry vector. Differentiate through modular flame spray pyrolysis equipment licensing rather than capital-intensive reactor ownership. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent synthesis operators with captive electronics qualification slots and multi-year offtake structures. Five-to-ten-year viability favors specialists with REACH pre-submitted dossiers and established South Korean supply relationships. Watch perovskite tandem cell mass production announcements as the inflection signal for semiconductor-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive ammonium molybdate supply insulates margins from Chinese rare earth corridor volatility. |
| REACH Nanoform Pre-Registration | ECHA-compliant toxicological dossiers unlock first-mover certification premiums in European catalyst procurement. |
| Modular Synthesis Equipment Licensing | Technology partnerships reduce capital barriers for entrants targeting research-grade and customized powder segments. |
| Long-Term Qualification Contracts | 36-48 month agreements with South Korean electronics manufacturers compress spot market exposure and stabilize revenue. |
| Analytical Talent Acquisition | ICP-MS operators capable of sub-10 ppm validation command wage premiums and constrain competitor batch release capacity. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with synthesis plant managers, catalyst procurement leads at petrochemical operators, electronics manufacturer supply chain directors, and specialty chemical distributors; alongside secondary validation through customs trade data, ECHA registration databases, EPA TSCA Section 8(a) filings, and SEC disclosures from integrated chemical conglomerates. Bottom-up volume estimates from individual synthesis facility capacities were triangulated against top-down demand projections from end-use application models.
Forecast inputs span purity grade tier, synthesis methodology, end-use industry, and regional regulatory cluster segmentation across the projection horizon. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking capacity expansion schedules. Perovskite solar cell commercialization timelines and REACH registration compliance trajectories provided industry-specific demand and supply-side anchors.
Sensitivities concentrate around perovskite tandem cell mass production delays, Chinese rare earth export policy shifts, and flame spray pyrolysis equipment delivery timeline extensions. Forecasts reflect assumptions on qualification contract durations and regulatory reciprocity evolution between EPA and ECHA jurisdictions. Material shifts in semiconductor-grade purity documentation standards or ammonium molybdate feedstock availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Nanocatalysts Market