
 Global Nanoclay Market | 2026-2036
Global Nanoclay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanoclay Market Foresight
Multi-source procurement for refined smectite feedstock is shifting toward captive mining agreements as suppliers seek layer-charge consistency. Elementis plc leverages its Wyoming bentonite deposits to anchor North American supply security. Clariant AG competes through surface-modification chemistry leadership in polymer-grade organoclays. Kunimine Industries dominates Asian sourcing with integrated hectorite extraction and processing in Japan.
Nanoclay denotes layered silicate minerals, typically one nanometer in thickness and hundreds of nanometers in lateral dimension, whose intergallery cations can be exchanged with organic surfactants to render the platelets compatible with thermoplastic matrices. These materials function primarily as barrier enhancers, mechanical reinforcements, and flame retardancy synergists across industrial formulations. Montmorillonite grades occupy the largest share of commercial volume due to abundant deposits and established intercalation chemistry, while hectorite variants command premium positioning in personal care and pharmaceutical rheology applications where electrolyte tolerance and transparency requirements are stringent. The plastics application segment leads in tonnage as automotive and packaging converters substitute nanoclay masterbatches for conventional mineral fillers to achieve weight reduction and oxygen barrier improvement.
REACH registration requirements in Europe and EPA toxic substance control reviews in the United States impose exfoliation efficiency and migratable surfactant testing that filter out low-grade imports. China's GB standards for nanomaterial classification and Japan's METI chemical substance reporting obligations add further compliance layers for cross-border suppliers. Stakeholders must monitor evolving polymer nanocomposite recycling protocols, as secondary processing of organoclay-loaded resins introduces separation and re-dispersion challenges that will reshape end-of-life value recovery strategies.
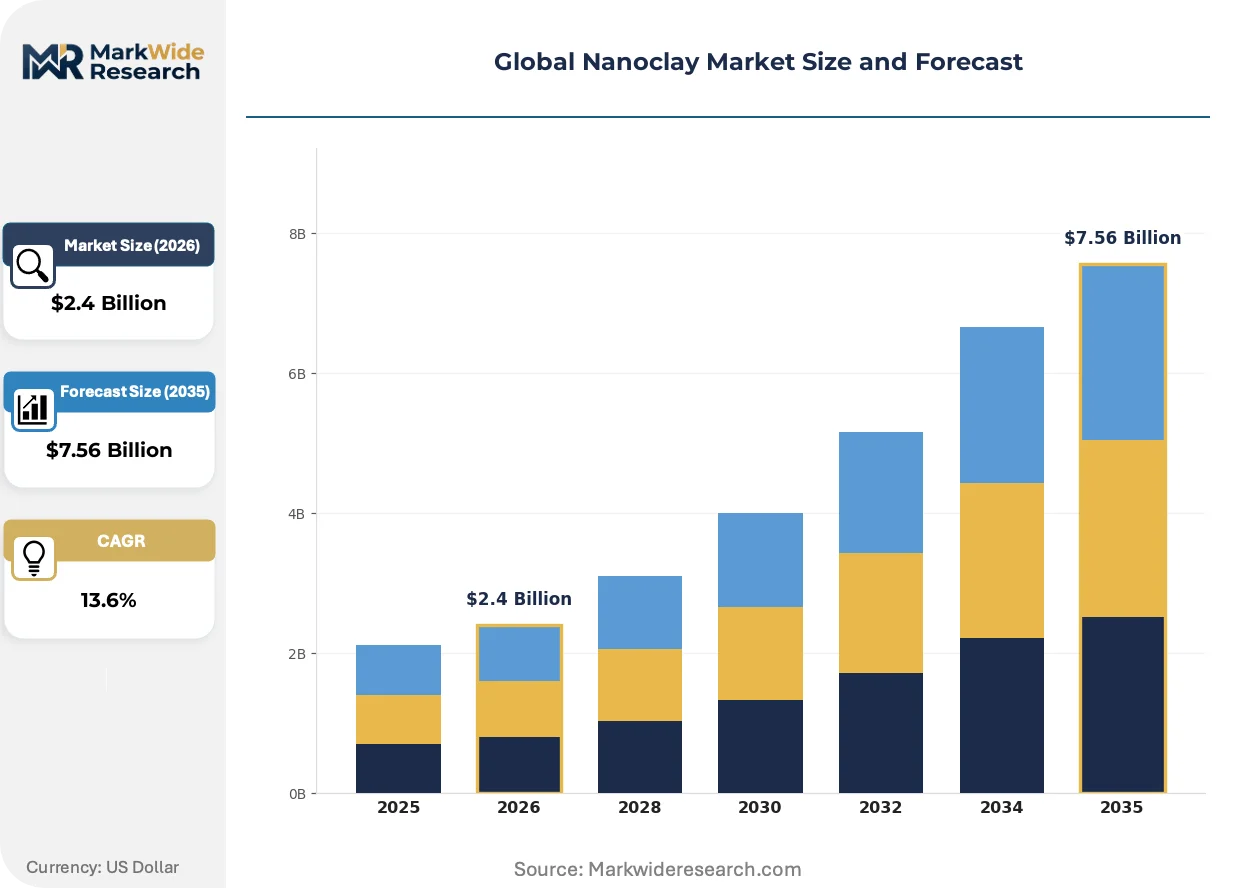
Market Dynamics
Automotive lightweighting mandates and battery enclosure thermal management requirements are compressing qualification cycles for polymer-grade organoclays, forcing suppliers to synchronize surface-modification R&D with OEM platform timelines.
Growth Catalysts
- EV battery enclosure contracts:Chinese OEMs specify nanoclay-reinforced thermoplastics for module housings to meet flame-retardancy standards without metal weight penalties.
- REACH registration thresholds:ECHA purity requirements filter low-grade imports, creating pricing power for compliant European processors of refined smectite feedstock.
- Intercalation chemistry advances:Alkylammonium surfactant innovations expand montmorillonite compatibility with polyamide and polypropylene matrices.
Market Restraints
- Wyoming bentonite concentration:Elementis plc and limited alternative deposit holders control layer-charge consistent feedstock, exposing converters to single-source risk.
- Organoclay recycling incompatibility:Secondary processing of surfactant-modified platelets creates re-dispersion failures that block circular economy certification.
- Precipitated calcium carbonate substitution:Packaging converters in cost-sensitive segments switch to conventional mineral fillers when oxygen barrier specifications allow.
Strategic Opportunities
- India packaging conversion:FSSAI food-contact material reviews create first-mover advantage for GB-standard-compliant Chinese exporters seeking alternative markets.
- Pharmaceutical rheology applications:Hectorite grades with electrolyte tolerance penetrate ophthalmic and injectable suspension formulations.
- Dual carbon alignment:China's MEE carbon intensity benchmarks favor domestic bentonite processors with integrated mining and low-transport surface modification.
Industry Challenges
- Exfoliation efficiency certification:EPA toxic substance control reviews demand standardized XRD interlayer spacing documentation that small-scale processors cannot generate.
- Masterbatch dispersion engineering:Compounding facilities lack shear-rate calibrated twin-screw configurations required for platelet alignment in thin-wall automotive components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanoclay Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.56 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Montmorillonite, Hectorite, Saponite, Illite Application: Plastics, Coatings, Composites, Pharmaceuticals End User: Construction, Automotive, Electronics, Packaging Distribution Channel: Direct Sales, E-commerce, Distributors, Retail |
| Companies Covered | Elementis plc, BYK-Chemie (ALTANA), Laviosa Chimica Mineraria, Clariant AG, BASF SE, Kunimine Industries, Merck Group, Cabot Corporation, Nanocor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanoclay Market Shifts & Advancements
Surface-modification chemistry and regulatory compliance protocols are converging to redefine supplier qualification criteria, with end-users now auditing intercalation efficiency rather than accepting generic mineral filler specifications.
In-situ polymerization techniques are integrating organoclay platelets directly into polymerization reactors rather than post-reactor compounding, enabling automotive Tier-1 suppliers to achieve sub-5% weight reduction targets in underhood components. BMW and Volkswagen procurement teams now mandate this integration pathway for 2026 platform nominations. The approach compresses masterbatch supplier margins while rewarding chemical companies with reactor-scale capabilities.
ECHA REACH authorization requirements for quaternary ammonium surfactants used in organoclay production are tightening migratable residue thresholds for food-contact applications. German and French converters face reformulation costs or supplier switches. The personal care segment absorbs compliance premiums more readily than commodity packaging, reshaping Clariant AG and Kunimine Industries portfolio prioritization.
Automotive OEMs are consolidating approved supplier lists to three nanoclay masterbatch qualifications per polymer type, down from historical seven-to-nine vendor rosters. Tier-2 compounders in Michigan, Stuttgart, and Shanghai report compressed switching timelines as platform engineers demand locked formulations eighteen months before SOP. This concentration rewards processors with captive smectite supply and in-house surface modification laboratories.
Global Nanoclay Market Segmentation
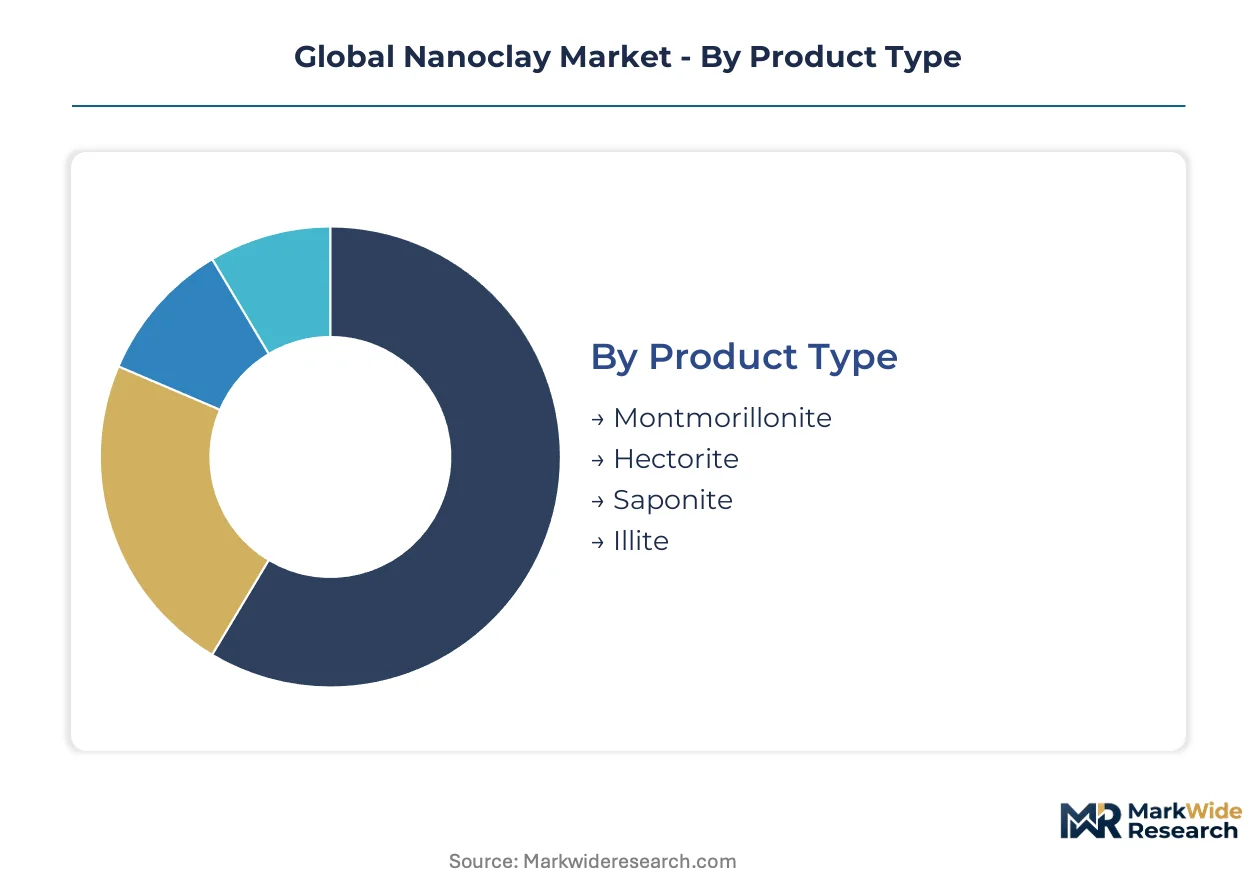
Nanoclay procurement patterns diverge sharply across mineral grades and end-use specifications. Surface chemistry compatibility and regulatory clearance thresholds determine which segments command premium positioning versus commodity volume.
Product Type:
Layer-charge density and cation exchange capacity separate industrial-grade feedstock from specialty rheology modifiers.
- Montmorillonite:Aluminum-rich 2:1 phyllosilicate with moderate layer charge enables cost-effective intercalation with alkylammonium surfactants. Chinese EV battery enclosure contracts and European automotive lightweighting programs concentrate demand here, though Wyoming deposit concentration creates feedstock security exposure.
- Hectorite:Magnesium lithium silicate with low layer charge and high electrolyte tolerance delivers transparent gel structures for personal care and ophthalmic suspensions. Japanese pharmaceutical formulators and French cosmetics manufacturers absorb compliance premiums for METI- and ANSM-cleared grades.
- Saponite:Iron-bearing trioctahedral smectite with larger interlayer spacing suits high-temperature polymer processing. German automotive Tier-1 suppliers specify saponite masterbatches for underhood components.
- Illite:Non-expanding mica-like structure with potassium-fixed interlayers provides thermal stability in ceramic and drilling applications. Russian and Ukrainian deposits supply European refractory manufacturers.
Mature deployment sits with montmorillonite in automotive and packaging. Newer deployment is concentrated in hectorite for pharmaceutical rheology.
Application:
Processing method and performance threshold dictate whether converters specify masterbatch compounds or direct mineral addition.
- Plastics:Thermoplastic nanocomposites leverage platelet alignment for oxygen barrier and flame retardancy in thin-wall automotive components. BMW and Volkswagen procurement teams mandate in-situ polymerization integration for platform nominations.
- Coatings:Exfoliated organoclay suspensions improve sag resistance and corrosion protection in marine and industrial formulations. Korean shipbuilders specify Clariant AG surface-modified grades for IMO-compliant protective systems.
- Composites:Fiber-reinforced thermoset matrices incorporate nanoclay for interlaminar fracture toughness in wind turbine blades and aerospace structures.
- Pharmaceuticals:Electrolyte-tolerant hectorite gels stabilize injectable suspensions and topical delivery systems. FDA and EMA reviews on migratable surfactant residues filter supplier qualification.
Volume leadership belongs to plastics compounding. Steepest expansion trajectory runs through pharmaceuticals as regulatory clearance barriers concentrate margin with qualified suppliers.
End User:
Certification requirements and formulation complexity separate specification-driven sectors from price-sensitive commodity buyers.
- Construction:Cementitious nanocomposites improve compressive strength and chloride ion resistance in marine concrete. Dubai and Singapore infrastructure projects specify GB-standard-compliant Chinese bentonite.
- Automotive:Module housings and underhood components demand flame-retardant thermoplastics without metal weight penalties. Chinese OEMs compress qualification cycles to synchronize with platform timelines.
- Electronics:Printed circuit board laminates and battery separator coatings require ultra-low ionic content. Japanese and South Korean battery manufacturers enforce exfoliation efficiency documentation.
- Packaging:Oxygen barrier films for food-contact applications face REACH and FDA migratable residue thresholds. Indian converters absorb FSSAI review timelines for first-mover positioning.
Automotive specifications drive masterbatch innovation. Packaging converters represent the most price-elastic demand segment.
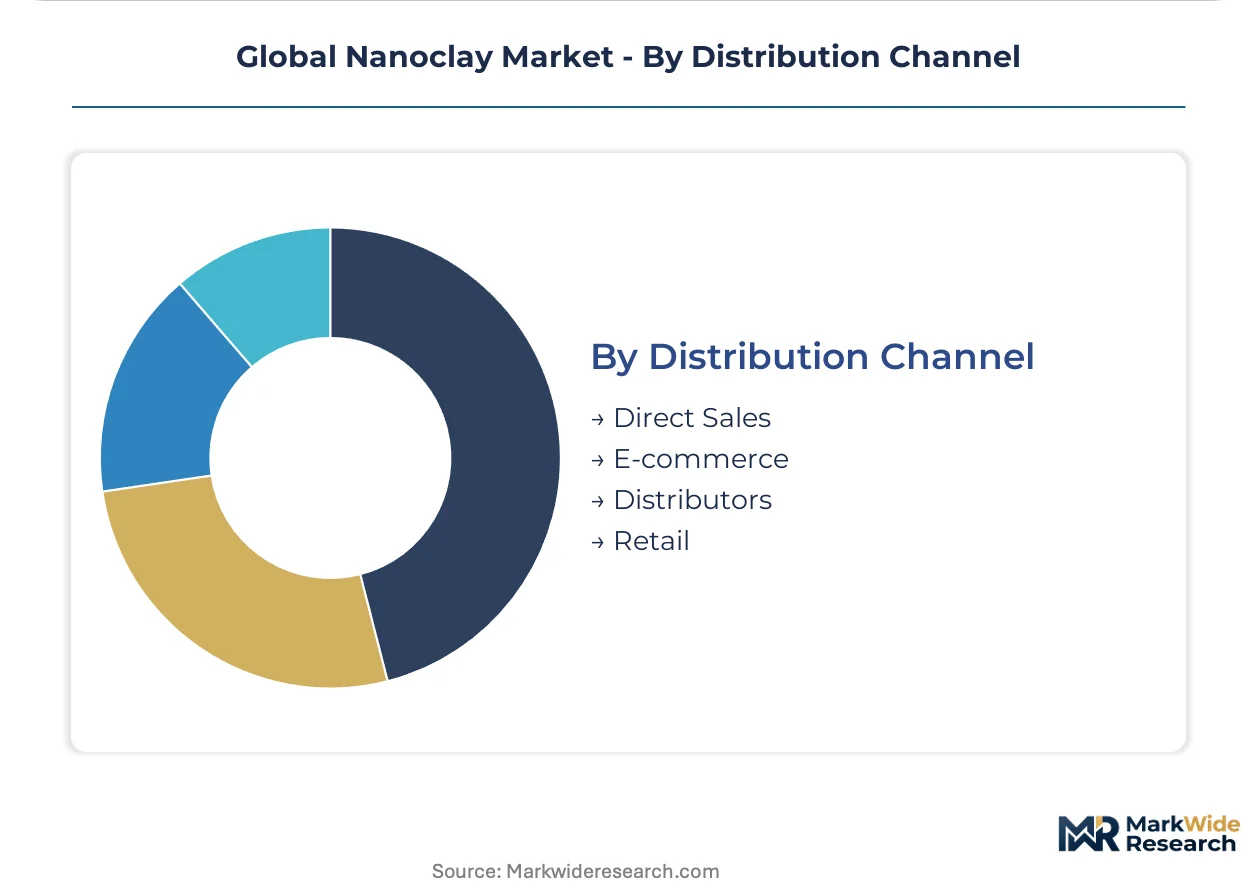
Distribution Channel:
Technical service intensity and order scale determine whether suppliers deploy direct technical sales or rely on distributor inventory.
- Direct Sales:Captive technical service teams support automotive and pharmaceutical accounts with formulation development and regulatory documentation. Elementis plc and Kunimine Industries maintain direct relationships with Tier-1 compounders.
- E-commerce:Standardized organoclay grades and technical data sheets serve research institutions and small-batch processors. Alibaba and specialty chemical platforms aggregate Chinese domestic supply.
- Distributors:Regional inventory positioning reduces lead times for construction and coatings formulators. Brenntag and Univar Solutions stock REACH-registered grades in European hubs.
- Retail:Small-package bentonite and cosmetic-grade hectorite reach hobbyist cosmetics and educational laboratories through specialty chemical retailers.
Direct relationships dominate high-specification automotive and pharmaceutical procurement. Distributor and e-commerce channels expand most quickly in construction and research segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wyoming bentonite deposits anchor North American feedstock security, while Chinese domestic processing capacity and Japanese hectorite extraction define Asia-Pacific supply architecture. European REACH compliance filters create pricing power for refined smectite processors.
United States
Automotive lightweighting programs and EV battery enclosure contracts pull volume through Michigan and Stuttgart-adjacent Tier-1 supply chains. EPA toxic substance control reviews demand standardized XRD interlayer spacing documentation that filters small-scale processors. Wyoming bentonite concentration exposes converters to single-source risk as Elementis plc controls layer-charge consistent feedstock.
Germany
BMW and Volkswagen procurement teams mandate in-situ polymerization integration for 2026 platform nominations, compressing masterbatch supplier margins. ECHA REACH authorization requirements for quaternary ammonium surfactants tighten migratable residue thresholds for food-contact applications. Stuttgart-based Tier-2 compounders report compressed switching timelines as platform engineers demand locked formulations eighteen months before SOP.
China
Domestic bentonite processing capacity and EV battery enclosure contracts expand fastest here, with OEMs specifying nanoclay-reinforced thermoplastics for module housings. GB standards for nanomaterial classification and MEE carbon intensity benchmarks favor domestic processors with integrated mining and low-transport surface modification. Yangtze River Delta clusters concentrate qualified masterbatch production.
Japan
Pharmaceutical rheology applications command premium positioning as METI chemical substance reporting obligations add compliance layers for cross-border suppliers. Kunimine Industries dominates Asian sourcing with integrated hectorite extraction and processing. Kanto-based pharmaceutical formulators absorb compliance premiums for electrolyte-tolerant grades in ophthalmic and injectable suspension formulations.
India
FSSAI food-contact material reviews create first-mover advantage for GB-standard-compliant Chinese exporters seeking alternative markets. Packaging converters absorb review timelines for positioning ahead of regulatory finalization. Maharashtra and Gujarat industrial corridors concentrate construction nanocomposite demand from infrastructure projects.
Global Nanoclay Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers synchronize surface-modification R&D with OEM platform timelines. The vendor base organizes around three tiers: integrated miners with captive bentonite deposits, specialty chemical houses with reactor-scale capabilities, and regional masterbatch compounders. Two competitive moves define positioning: backward integration into Wyoming and Asian bentonite mining, and technology licensing for in-situ polymerization reactor integration.
Among integrated mining specialists, Elementis plc anchors North American supply security through Wyoming deposit control, while Kunimine Industries exemplifies the Asian model with Japanese hectorite extraction. Specialty chemical representation sits with Clariant AG, whose surface-modification chemistry leadership occupies premium positioning in polymer-grade organoclays. These three occupy distinct archetype positions: captive resource control, integrated extraction-processing, and formulation chemistry leadership.
| Leading Market Players |
|---|
| Elementis plc |
| BYK-Chemie (ALTANA) |
| Laviosa Chimica Mineraria |
| Clariant AG |
| BASF SE |
| Kunimine Industries |
| Merck Group |
| Cabot Corporation |
| Nanocor Inc. |
| Others |
Supply & Pricing Matrix
Family-owned bentonite processors in Wyoming and Japan anchor supply discipline through generational deposit control, translating geological scarcity into pricing power that resists commodity cycling. Their refusal to dilute equity through private-equity rollup preserves long-term contracting behavior against spot-market volatility.
Pricing Analysis
Technical service bundling separates premium organoclay quotations from unbundled mineral filler transactions. Three-tier pricing structure across pharmaceutical-grade, automotive-certified, and industrial-standard levels tracks REACH registration status and exfoliation efficiency documentation. Cost compression in industrial-grade montmorillonite intensifies as Chinese domestic processors absorb margin to secure EV battery enclosure contracts. Packaging converters represent the most price-sensitive demand segment, while pharmaceutical formulators absorb compliance premiums for electrolyte-tolerant hectorite.
Supply Chain Analysis
Ocean freight cost differentials between Wyoming-to-Europe and China-to-India routes reshape regional sourcing decisions for polymer compounders. Supply concentrates in the United States, China, and Japan, with Wyoming bentonite, Yangtze River Delta processing clusters, and Kanto hectorite extraction feeding global conversion. Raw material flows draw from alkylammonium surfactant producers, refined smectite feedstock processors, and intercalation chemical specialists. Single-source vulnerability in Wyoming deposit control exposes North American converters to disruption. Distribution runs through direct technical sales for automotive and pharmaceutical accounts, with regional distributors serving construction and coatings segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanoclay market sits in a technology-transition phase as in-situ polymerization displaces conventional masterbatch compounding in automotive qualification cycles.
For Market Incumbents: Extend surface-modification R&D capabilities to capture in-situ polymerization reactor integration contracts before platform engineers lock formulations. Secure captive smectite supply through upstream mining partnerships or long-term offtake agreements to defend against Wyoming deposit concentration risk. Clariant AG and Elementis plc demonstrate how integrated extraction-processing buffers margin compression from Chinese domestic processors. For New Entrants and Emerging Players: FSSAI food-contact material reviews in India open a window for GB-standard-compliant Chinese exporters to establish first-mover positioning before regulatory finalization. Target pharmaceutical rheology applications where electrolyte tolerance requirements filter competition to qualified suppliers. Pursue white-label masterbatch partnerships with Yangtze River Delta compounders lacking international certification capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Japanese hectorite specialists with METI-cleared grades and ophthalmic formulation relationships. Long-term viability centers on regulatory clearance moats rather than commodity volume exposure. Watch EPA toxic substance control review timelines as inflection indicators for US market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wyoming Bentonite Mining | Elementis plc secures layer-charge consistent feedstock against single-source risk exposure. |
| In-Situ Polymerization Reactor Licensing | BMW and Volkswagen procurement teams mandate this integration pathway for platform nominations. |
| REACH-Compliant Surface Modification Expansion | Clariant AG captures pricing power as ECHA authorization filters low-grade imports. |
| Pharmaceutical Hectorite Grade Development | Kunimine Industries penetrates ophthalmic suspensions with electrolyte-tolerant formulations. |
| GB-Standard Export Capacity Buildout | Chinese processors align with MEE carbon intensity benchmarks for dual carbon compliance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with polymer compounding plant managers, OEM platform engineers, pharmaceutical formulation scientists, and REACH registration consultants. ECHA substance dossiers, EPA toxic substance control submissions, and Chinese customs export statistics provided validation triangulation against bottom-up segment sizing and top-down macroeconomic cross-checks.
Segment-level modeling tracked montmorillonite, hectorite, saponite, and illite grades across plastics, coatings, composites, and pharmaceutical applications, with end-use splits for automotive, packaging, construction, and electronics procurement. CAGRs derived from elasticity-adjusted volume projections incorporating OEM platform nomination timelines and regulatory clearance lag structures. Carbon intensity benchmarks and recycling protocol development shaped scenario weighting across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for in-situ polymerization reactor integration would alter the outlook for masterbatch compounder margins. Forecasts reflect assumptions on REACH authorization timelines, Wyoming deposit depletion curves, and Chinese domestic absorption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
1,8-Dinitroanthraquinone Market