
 Global Nanosilica Market | 2026-2036
Global Nanosilica Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanosilica Market Foresight
The EU Green Deal is rebalancing procurement priorities across European tire and coatings supply chains. Evonik Industries AG leverages its integrated precipitated silica network to sustain formulation partnerships with premium tire manufacturers. Cabot Corporation anchors North American supply through controlled distribution channels for rubber reinforcement grades.
Nanosilica consists of amorphous silicon dioxide particles with diameters typically ranging from 1 to 100 nanometers, produced via sol-gel, flame pyrolysis, or chemical precipitation methods to deliver high surface area, controlled porosity, and enhanced mechanical or barrier properties in composite matrices. Colloidal nanosilica dominates volume in coatings additive applications where optical clarity and suspension stability command premium positioning. Pyrogenic grades lead margin pools in electronics packaging, where ultra-high purity and low moisture content justify differentiated pricing against precipitated alternatives.
REACH registration requirements in Europe, EPA Toxic Substances Control Act provisions in the United States, and China's GB standards under SAMR oversight collectively tighten purity thresholds and occupational exposure limits for nanomaterial handlers. These frameworks elevate compliance costs for smaller producers while advantaging scaled manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving nanomaterial classification debates at OECD and ISO levels, as downstream liability rules will determine which product forms retain market access across major economies.
Market Dynamics
Tire manufacturers are consolidating nanosilica procurement around low-rolling-resistance compound specifications, compressing supplier qualification timelines and reshaping formulation partnerships across the value chain.
Growth Catalysts
- REACH Registration Thresholds:ECHA purity mandates are filtering out sub-scale producers and concentrating volume with integrated manufacturers capable of sustained compliance investment.
- China Sol-Gel Capacity Expansion:Domestic chemical companies are scaling continuous production lines, reducing import dependency for coatings and electronics packaging grades.
- Low-Rolling-Resistance Tire Mandates:EPA emissions standards and EU CO2 regulations for passenger vehicles are embedding nanosilica as a required performance additive in tread compounds.
Market Restraints
- Sodium Silicate Price Volatility:Energy-intensive production of this feedstock creates margin compression for precipitated silica manufacturers during natural gas price spikes.
- Pyrogenic Grade Supply Concentration:Ultra-high-purity production clusters in Germany and Japan expose electronics packaging customers to single-source risk during logistics disruptions.
- Carbon Black Substitution Economics:Reinforcement-grade precipitated silica faces price-performance competition from surface-modified carbon blacks in commodity tire segments.
Strategic Opportunities
- India BIS Certification Gap:Domestic nanosilica production remains below technical-grade thresholds, creating import substitution potential for coatings and adhesives applications.
- Battery Electrolyte Additives:Colloidal nanosilica is penetrating lithium-ion cell manufacturing as a viscosity modifier and thermal stabilizer in separator coatings.
- EU Green Deal Procurement Rules:Public infrastructure coatings tenders are mandating lifecycle carbon assessments, favoring sol-gel producers with verified renewable energy inputs.
Industry Challenges
- ISO/TC 229 Classification Delays:Uncertainty over nanomaterial definition boundaries is extending product registration timelines and freezing investment decisions in emerging applications.
- Sol-Gel Scale-Up Capital Requirements:Continuous reactor construction demands specialized engineering expertise that equipment vendors cannot deliver within compressed project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanosilica Market |
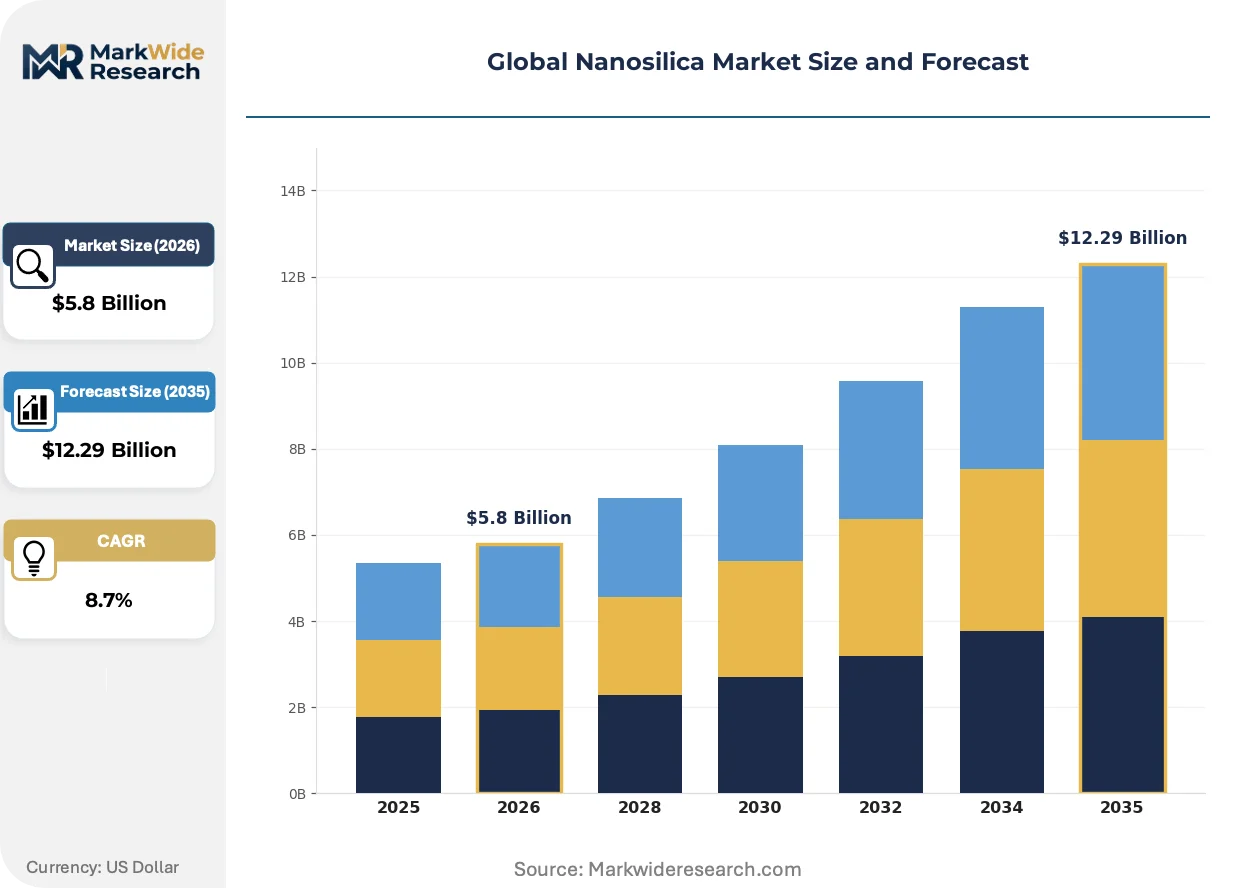
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Colloidal, Precipitated, Pyrogenic, Wet Process Technology: Sol-Gel, Vapor Phase, Chemical Precipitation, Flame Pyrolysis, Microemulsion Application: Rubber Reinforcement, Coatings Additive, Cosmetics Enhancer, Catalyst Support, Electronics Packaging End User Industry: Tire Manufacturers, Paint Producers, Personal Care, Chemical Companies, Electronics Fabricators |
| Companies Covered | Evonik Industries AG, Cabot Corporation, Fuso Chemical Co. Ltd., Wacker Chemie AG, NanoPore Incorporated, DuPont, AkzoNobel N.V., nanoComposix, Bee Chems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanosilica Market Shifts & Advancements
Process intensification and regulatory precision are converging to redefine how nanosilica grades are specified, produced, and validated across tire, coatings, and electronics supply chains.
Hybrid sol-gel synthesis is modularizing production architecture by separating particle nucleation from surface functionalization into discrete, optimized reactor stages. Coatings formulators in Germany and Japan are adopting this approach to reduce batch-to-batch variability in optical clarity grades. The technology is compressing qualification cycles from 18 months to under 8 months for premium automotive clearcoat applications.
REACH nanomaterial registration requirements are tightening occupational exposure documentation for handlers of unbound particles above 1 nanometer. Industrial consequence includes mandatory workplace monitoring systems and respirator fit-testing protocols that smaller compounders cannot implement. Tire manufacturing facilities in Belgium and the Netherlands are responding by consolidating nanosilica handling into sealed, automated weighing stations.
Specification-driven procurement is displacing relationship-based supplier selection in North American tire compound development. Compounders now require ISO 17025-certified particle size distributions and surface area measurements with every delivery lot. This shift is most visible in South Carolina and Ohio, where domestic tire plants are reducing approved supplier lists from twelve to four qualified vendors.
Global Nanosilica Market Segmentation
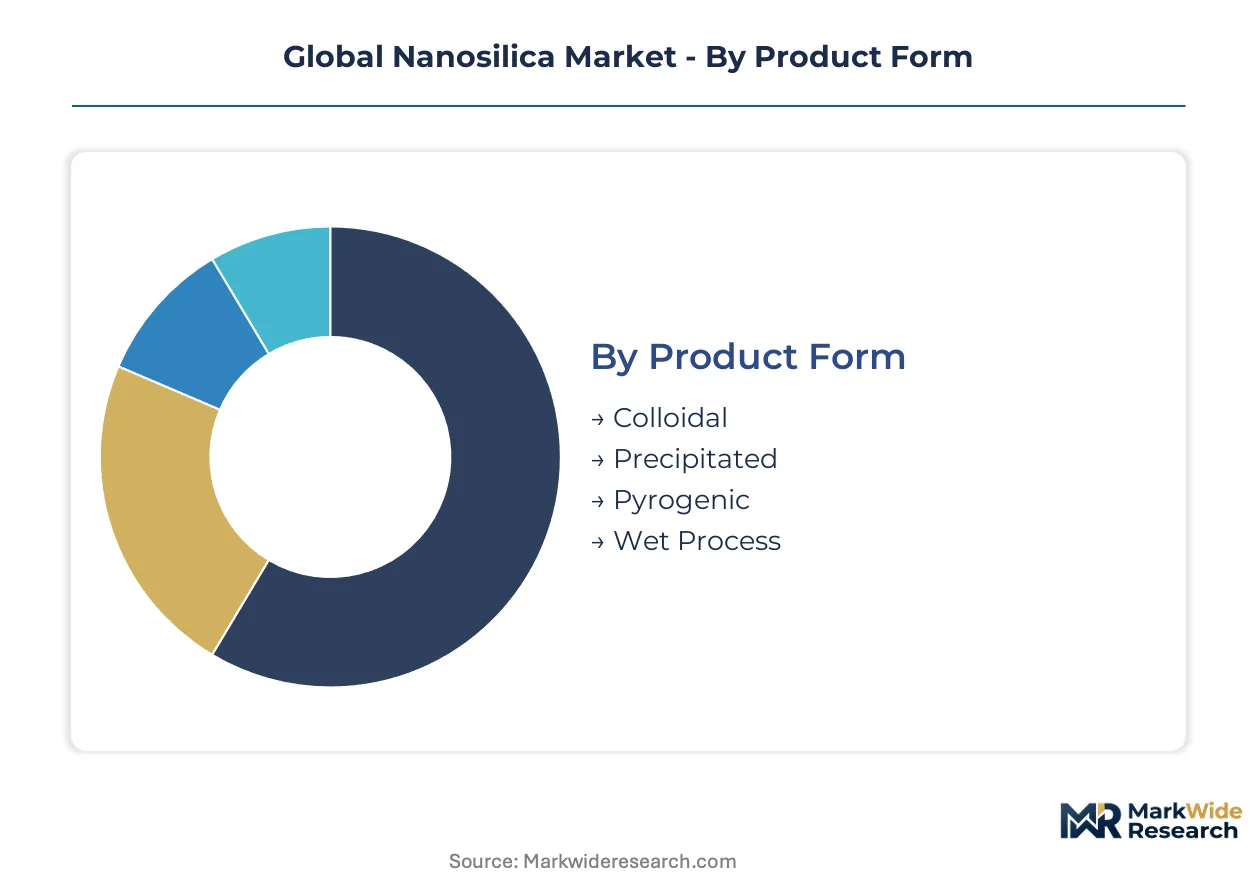
Segmentation in nanosilica markets determines specification pathways, as tire compounders, coatings formulators, and electronics packagers each impose distinct purity thresholds and surface chemistry requirements. Buyers in premium automotive and semiconductor applications enforce lot-level certification that commodity segments rarely demand.
Product Form:
Cost tier differentiation separates specification-grade buyers from volume purchasers in this category.
- Colloidal:Stable aqueous suspensions with particle sizes below 100 nanometers deliver optical clarity and suspension stability. Coatings additive demand concentrates in Germany and Japan, where automotive clearcoat formulators require batch-to-batch consistency for premium finishes.
- Pyrogenic:Flame-hydrolyzed particles with ultra-high surface area and low moisture content serve electronics packaging applications. Semiconductor mold compound manufacturers in Japan and South Korea specify pyrogenic grades for thermal management in high-density chip encapsulation.
- Precipitated:Acid-neutralized sodium silicate solutions yield controlled porosity for rubber reinforcement at moderate cost.
- Wet Process:Aqueous precipitation variants optimize for coatings viscosity modification with reduced dust handling concerns.
Volume sits with precipitated grades; growth tilts toward colloidal dispersions.
Technology:
Application requirements dictate process selection, with surface area targets and impurity ceilings driving reactor configuration choices.
- Sol-Gel:Alkoxide hydrolysis in alcohol media produces monodisperse particles with tunable porosity. Chinese chemical companies are scaling continuous sol-gel lines to reduce coatings industry import dependency.
- Flame Pyrolysis:Silicon tetrachloride combustion generates ultra-pure fumed silica with surface areas exceeding 300 square meters per gram. Electronics packaging demand in Germany and Japan sustains premium positioning despite energy-intensive production.
- Vapor Phase:High-temperature oxidation of silane precursors yields controlled aggregate structures for specialty coatings.
- Chemical Precipitation:Acid-base neutralization of sodium silicate dominates rubber reinforcement volume through cost efficiency.
- Microemulsion:Surfactant-templated synthesis enables precise particle size distribution for cosmetic applications.
Output concentrates in chemical precipitation; capability investment flows toward sol-gel modularization.
Application:
Customer type maturity shapes procurement sophistication, with automotive and semiconductor buyers imposing the most stringent qualification protocols.
- Rubber Reinforcement:Precipitated silica replaces carbon black in tire tread compounds to reduce rolling resistance. EPA emissions standards and EU CO2 regulations for passenger vehicles are embedding this application as mandatory for low-resistance formulations.
- Electronics Packaging:Pyrogenic grades provide thermal conductivity and mechanical protection in semiconductor encapsulation. Japanese and South Korean fabricators specify ultra-low ionic content for high-reliability chip packaging.
- Coatings Additive:Colloidal dispersions modify rheology and scratch resistance in automotive and industrial finishes.
- Cosmetics Enhancer:Microemulsion-derived particles deliver texture and optical properties in personal care formulations.
- Catalyst Support:High-surface-area grades anchor active metals in petrochemical and environmental catalysis.
Revenue weight rests with rubber reinforcement; margin expansion clusters in electronics packaging.
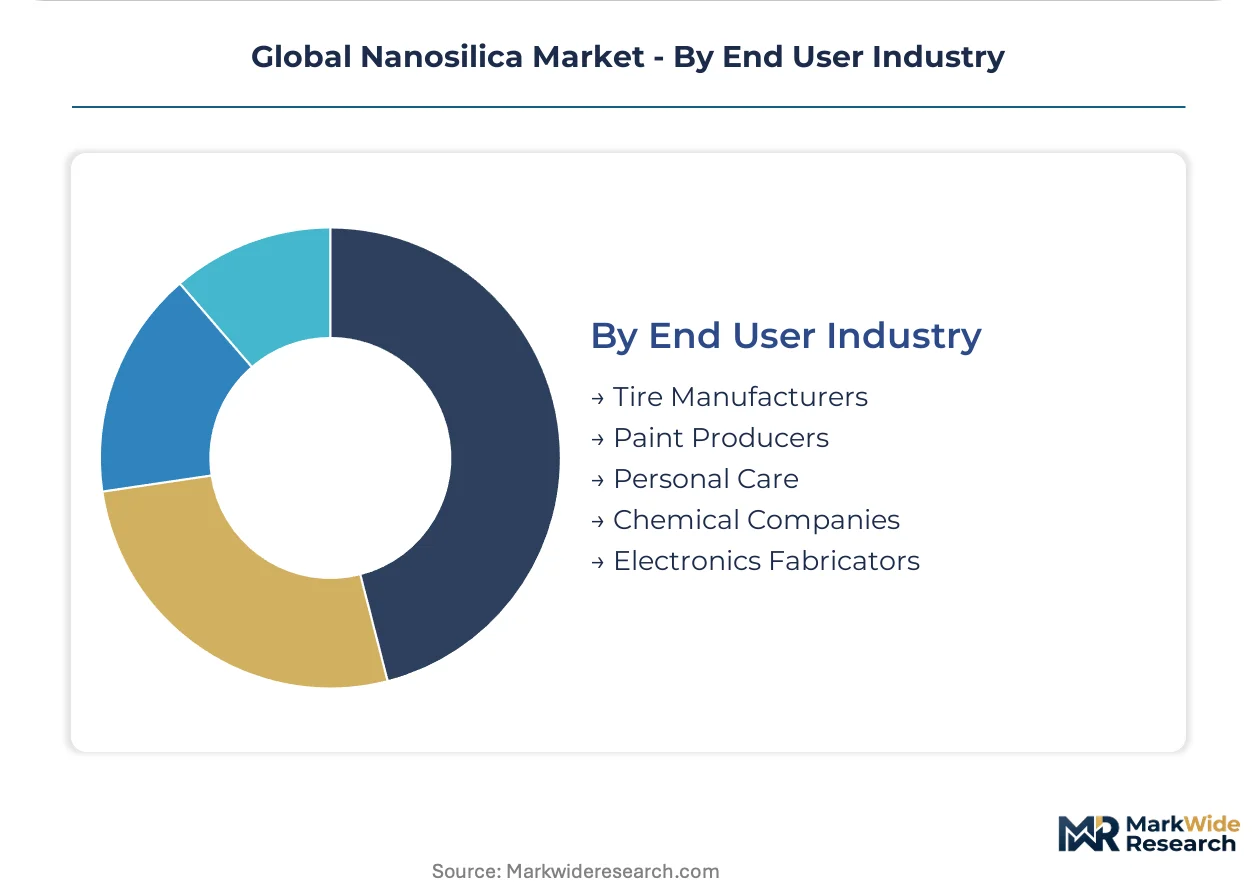
End User Industry:
Supply concentration varies sharply across this dimension, with tire manufacturing consolidating procurement while personal care remains fragmented.
- Tire Manufacturers:Compounders in Belgium, the Netherlands, South Carolina, and Ohio are consolidating approved supplier lists from twelve vendors to four qualified sources. REACH registration requirements and ISO 17025-certified lot testing are filtering out sub-scale producers.
- Electronics Fabricators:Semiconductor packaging houses in Japan and South Korea enforce single-digit parts-per-billion metal contamination limits. Pyrogenic grade supply concentration in Germany and Japan creates single-source exposure during logistics disruptions.
- Paint Producers:Automotive OEM clearcoat specifications drive colloidal silica demand in Germany and Japan.
- Chemical Companies:Catalyst and intermediate producers purchase bulk precipitated grades for process applications.
- Personal Care:Cosmetics formulators specify microemulsion grades for sensory and optical performance.
Procurement scale aggregates with tire manufacturers; specification intensity peaks at electronics fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in China and Germany while consumption spreads across tire manufacturing clusters in Belgium, South Carolina, and Japan. This geographic split creates trade flows that expose buyers to logistics bottlenecks and currency volatility.
China
Domestic chemical companies are scaling continuous sol-gel production lines to serve coatings and electronics packaging demand. SAMR oversight through GB standards tightens purity thresholds for nanomaterial handlers. The Yangtze River Delta hosts the fastest capacity additions, with Jiangsu and Zhejiang provinces attracting state-backed investment in modular reactor construction.
Germany
Evonik Industries AG anchors European supply through integrated precipitated silica networks serving premium tire manufacturers. REACH registration requirements under ECHA filter out sub-scale producers and concentrate volume with compliant manufacturers. The North Rhine-Westphalia chemical corridor maintains pyrogenic grade production for semiconductor packaging applications.
United States
Cabot Corporation controls North American distribution channels for rubber reinforcement grades serving South Carolina and Ohio tire plants. EPA Toxic Substances Control Act provisions elevate compliance costs for occupational exposure documentation. The Southeast manufacturing belt is consolidating approved supplier lists from twelve vendors to four qualified sources.
Japan
Fuso Chemical Co. Ltd. and Wacker Chemie AG operations supply ultra-high-purity pyrogenic grades for semiconductor mold compounds. METI standards enforce single-digit parts-per-billion metal contamination limits for electronics fabricators. The Kansai region around Osaka remains the dominant cluster for thermal management grade production.
India
Domestic nanosilica production sits below technical-grade thresholds for coatings and adhesives applications, sustaining import dependency. BIS certification gaps create substitution potential for qualified foreign suppliers. Maharashtra and Gujarat chemical corridors are attracting joint venture proposals to localize sol-gel capacity.
Global Nanosilica Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with dedicated regulatory affairs capabilities. Tiered positioning separates specification-grade specialists from volume producers of rubber reinforcement grades. Two archetypes dominate: integrated silica networks with tire manufacturer partnerships, and technology licensors with modular sol-gel platforms. Capacity expansion and strategic qualification partnerships represent the dominant competitive moves as compounders compress supplier approval timelines.
Among German-based chemical conglomerates, Evonik Industries AG and Wacker Chemie AG occupy positions within the integrated silica network archetype, exemplifying the regulatory scale and formulation partnerships that filter out sub-scale competitors. Cabot Corporation represents the North American volume anchor, while Fuso Chemical Co. Ltd. sits within the premium-grade specialist tier serving electronics packaging demand in Japan and South Korea.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Cabot Corporation |
| Fuso Chemical Co. Ltd. |
| Wacker Chemie AG |
| NanoPore Incorporated |
| DuPont |
| AkzoNobel N.V. |
| nanoComposix |
| Bee Chems |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China's Yangtze River Delta and family-owned mid-caps in Germany's North Rhine-Westphalia chemical corridor anchor supply discipline through controlled capacity release, translating feedstock volatility into tiered pricing power across tire and electronics grades.
Pricing Analysis
Margin tightening in precipitated grades traces to sodium silicate feedstock volatility and energy cost spikes at German and Chinese production nodes. Contract-based long-term offtake dominates volume transactions for rubber reinforcement, while spot-adjacent premiums attach to pyrogenic electronics grades. Price differentiation hinges on REACH registration status and ISO 17025-certified lot testing, with commodity tire compounders exhibiting acute price sensitivity against semiconductor packagers absorbing purity premiums.
Supply Chain Analysis
Specialized reactor engineering talent shortages in Jiangsu and Zhejiang provinces constrain continuous sol-gel scale-up timelines. Supply concentrates in China, Germany, and Japan, with pyrogenic grade production drawing from silicon tetrachloride and high-purity silane precursors. Single-source vulnerability persists for ultra-high-purity electronics grades clustered around Osaka and Leverkusen. Distribution runs through qualified distributor networks for rubber reinforcement and direct technical service relationships for coatings and semiconductor applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous reactor construction bottlenecks and specialized engineering scarcity prop pricing power for incumbent sol-gel and pyrogenic producers across the analysis window.
For Market Incumbents: Deepen backward integration into sodium silicate feedstock to buffer margin compression from natural gas volatility. Expand modular sol-gel capacity in Jiangsu province to capture coatings demand migration. Consolidate formulation partnerships as tire compounders compress supplier lists from twelve to four qualified sources. For New Entrants and Emerging Players: The premium-to-economy pricing gap in Indian coatings and adhesives applications offers white-space entry before BIS certification requirements tighten. Target Maharashtra and Gujarat chemical corridors with joint-venture structures leveraging foreign sol-gel technology licensing. Lead with battery electrolyte additive qualification to bypass entrenched tire supply relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale precipitated silica producers in South Korea and Taiwan facing REACH compliance cost escalation. Long-term viability centers on regulatory affairs capabilities and automotive qualification pipelines. Watch for ECHA nanomaterial classification decisions as inflection triggers for downstream liability exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive sodium silicate supply insulates German and Chinese producers from energy cost volatility. |
| Capacity Expansion | Modular sol-gel reactor additions in Jiangsu reduce coatings industry import dependency. |
| Green Manufacturing Transition | Verified renewable energy inputs qualify sol-gel producers for EU Green Deal infrastructure tenders. |
| Long-term Supply Agreement | Compressed tire compounder qualification timelines favor locked relationships with REACH-registered suppliers. |
| Joint Venture | Technology-licensing partnerships enable foreign entry into India's BIS-constrained coatings market. |
Research Methodology
Document review covered ECHA registration databases, SAMR GB standard filings, and tire industry trade publications, complemented by interviews with plant managers at precipitated silica facilities, procurement leads at South Carolina and Ohio tire plants, coatings formulators in Germany and Japan, and semiconductor packaging engineers in Osaka and Seoul. Secondary validation drew from customs trade data, SEC chemical company filings, and ACC industry reports. Bottom-up capacity modeling and top-down demand segmentation were triangulated against primary fieldwork.
Output projections span volume and value across product form, technology route, application, and end-user industry dimensions over the projection horizon. CAGRs were derived from regression analysis of historical capacity additions, regulatory timeline impacts, and substitution elasticity between nanosilica and carbon black in tire formulations. Forecast inputs incorporated sol-gel reactor construction lead times and REACH registration cost trajectories.
Underlying measurement precision varies by segment; electronics packaging and premium automotive coatings carry tighter precision than commodity rubber reinforcement. Forecasts reflect assumptions around ECHA classification stability, Chinese dual carbon policy implementation pace, and tire OEM low-rolling-resistance mandate adoption curves. Material deviation in sodium silicate pricing or ISO/TC 229 classification timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Nanoparticle Contract Manufacturing Market
Nanomaterials
Nanocellulose Materials Market