
 Nanocellulose Market | 2026-2036
Nanocellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Nanocellulose Market Analysis
The gap between pharmaceutical-grade bacterial cellulose and commodity paper additives is realigning procurement strategies across the value chain. Borregaard AS leverages its Norwegian biorefinery complex to sustain high-purity nanocellulose output for biomedical clients. CelluForce anchors North American supply through its Quebec demonstration plant, while Sappi Ltd. competes via integrated pulp-to-nanofibril pathways in South Africa and Europe.
Nanocellulose comprises cellulose fibrils or crystals with at least one dimension below 100 nanometers, typically extracted through mechanical fibrillation, acid hydrolysis, or bacterial synthesis to yield reinforcing agents with tensile strength exceeding 1 GPa. Nanofibrils dominate volume due to established pulp-mill retrofit compatibility, whereas bacterial cellulose commands premium positioning in biomedical and electronics applications where ultrahigh purity matters. Composites and packaging absorb the bulk of current output, though coatings for flexible electronics represent the fastest-expanding margin pool as film-form specifications tighten.
EU REACH registration requirements and the F-Gas Regulation indirectly bolster nanocellulose substitution in thermal insulation and barrier films, while FDA guidance on bio-based food contact materials shapes North American adoption timelines. Japan's METI promotes nanocellulose through national biomass strategies tied to carbon neutrality targets. Stakeholders must track how evolving compostability certifications in the EU and food-contact approvals in the US determine which product forms capture scalable commercial slots.
Market Dynamics
Pulp-mill retrofit economics are compressing nanocellulose production costs while EU Green Deal enforcement accelerates substitution mandates across barrier film applications. This dual pressure is redrawing competitive boundaries between Nordic integrated producers and standalone technology licensors.
Growth Catalysts
- EU F-Gas Regulation:Thermal insulation manufacturers in Germany and France are substituting fluorinated gases with nanocellulose aerogels to meet phasedown targets, creating pull-through demand for high-aspect-ratio fibrils.
- Food contact material approvals:FDA guidance on bio-based packaging is unlocking commercial slots for bacterial cellulose films in fresh produce applications across California and Florida processing corridors.
- Pulp-mill integration:Mechanical fibrillation equipment retrofits at Scandinavian kraft mills are collapsing unit costs below standalone production thresholds.
Market Restraints
- Energy input volatility:High-pressure homogenization and TEMPO-oxidation processes consume 8-15 MWh per tonne, exposing margins to Nordic electricity price swings.
- Purification bottlenecks:Pharmaceutical-grade bacterial cellulose requires 72-hour fermentation cycles and aseptic handling, constraining output to a handful of certified bioreactors in Norway and Japan.
- Cellulose ether substitution:Carboxymethyl cellulose and hydroxyethyl cellulose maintain cost advantages in commodity paper reinforcement, limiting nanocellulose penetration below food-contact thresholds.
Strategic Opportunities
- India BIS standards development:Draft national biomass utilization codes are creating first-mover positioning for barrier film suppliers in Maharashtra and Gujarat packaging clusters.
- Flexible electronics substrates:Convergence of roll-to-roll coating equipment with nanocellulose film casting is enabling transparent conductive layers for foldable display prototypes.
- EU CSRD disclosure mandates:Scope 3 emissions reporting requirements are pushing cosmetics brands toward verified bio-based rheology modifiers with full supply chain traceability.
Industry Challenges
- Compostability certification lag:Industrial composting standards for nanocellulose-polymer blends remain unsettled across EN 13432 and ASTM D6400 frameworks, delaying customer qualification timelines.
- Process analytical technology gaps:Real-time fibril dimension monitoring during continuous production lacks robust inline sensors, forcing batch release testing that extends lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanocellulose Market |
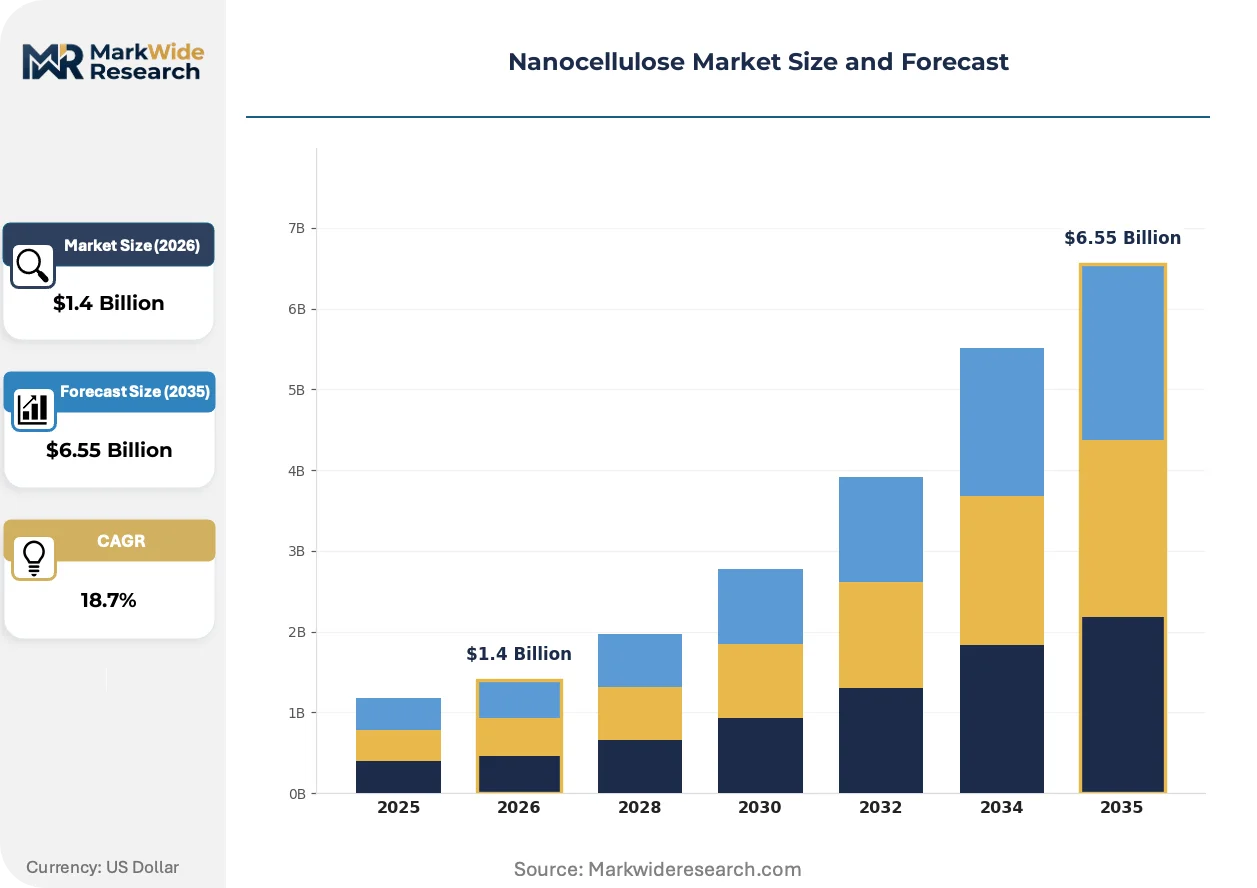
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanofibrils, Nanocrystals, Bacterial Cellulose, Whiskers Application: Composites, Packaging, Coatings, Biomedical End User: Food Industry, Electronics, Automotive, Pharmaceuticals Form: Dry Powder, Suspension, Gel, Film |
| Companies Covered | Borregaard AS, CelluForce, FiberLean Technologies, Nippon Paper Industries Co. Ltd., Kruger Inc., Sappi Ltd., Stora Enso, GranBio Technologies, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanocellulose Market Emerging Trajectories
Surface functionalization chemistry is unlocking nanocellulose compatibility with hydrophobic polymer matrices previously resistant to cellulosic reinforcement. These advances are expanding addressable markets beyond paper and packaging into engineered composites and biomedical devices.
TEMPO-mediated oxidation is integrating carboxylate groups onto fibril surfaces to enable stable aqueous dispersions in high-salinity coating baths. Marine coating formulators in Rotterdam and Singapore are adopting these dispersions for anti-corrosion primers, displacing solvent-borne epoxy systems in shipyard maintenance cycles. The technology is integrating waterborne performance standards into regulatory compliance frameworks previously dominated by petrochemical binders.
Japan's METI national biomass strategy is channeling R&D subsidies toward carbon-neutral material certification pathways. Pulp processors in Hokkaido and Kyushu are leveraging these incentives to construct demonstration plants linking forestry residues to nanofibril output. Electronics manufacturers in Osaka and Nagoya are responding with pilot orders for biodegradable substrate films in disposable sensor applications.
Brand-led sustainability scorecards are compressing supplier qualification cycles for bio-based packaging inputs. Major food retailers in France and the Netherlands are unbundling traditional resin supply agreements to incorporate nanocellulose barrier layers as standalone specification tiers. This pattern is most visible in chilled ready-meal segments where modified atmosphere packaging requirements intersect with single-use plastic reduction commitments.
Nanocellulose Market Segmentation
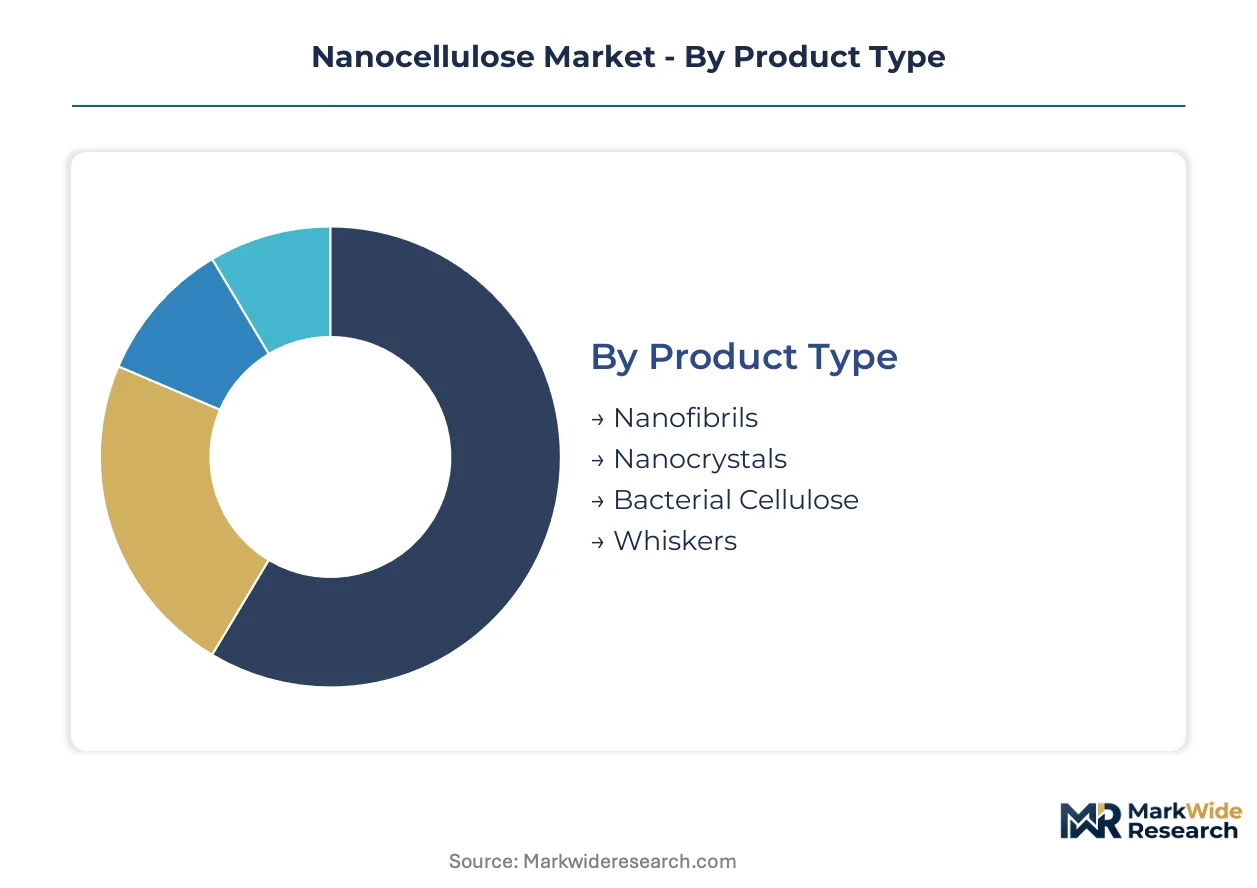
Nanocellulose procurement patterns diverge sharply across purity grades, physical forms, and end-use specifications. Buyers in biomedical and electronics segments prioritize bacterial cellulose purity and film-form consistency, while packaging converters optimize for fibril aspect ratio and aqueous dispersion stability at scale.
Product Type:
Cost tier differentiation separates commodity pulp-mill retrofits from precision fermentation systems requiring aseptic infrastructure.
- Nanofibrils:Mechanical fibrillation of kraft pulp yields high-aspect-ratio fibrils with surface area exceeding 200 m²/g. Nordic kraft mills in Sweden and Finland dominate volume output through retrofitted homogenization lines, driven by EU Green Deal single-use plastic substitution mandates in barrier film applications.
- Bacterial Cellulose:Acetobacter xylinum fermentation produces ultrahigh-purity pellicles with crystallinity above 90% and zero lignin content. Norwegian bioreactors supply biomedical device manufacturers in Germany and Japan where FDA and PMDA implant-grade certifications command 15-20x commodity pricing multiples.
- Nanocrystals:Acid hydrolysis of cellulose fibers isolates rod-like crystalline domains 3-10 nm in diameter. Quebec demonstration plants serve North American coating formulators seeking rheology modification in waterborne marine primers.
- Whiskers:Rigid cellulose microcrystals extracted from tunicate and algae sources provide exceptional modulus for specialty composites. Limited commercial output concentrates in French and Japanese research consortia.
Nanofibrils lead volumes today; bacterial cellulose is gaining share fastest.
Application:
Application selection tracks end-use performance thresholds and regulatory compliance burdens rather than raw material cost alone.
- Composites:Surface-functionalized fibrils reinforce hydrophobic polymer matrices in automotive interior panels and construction materials. German Tier 1 suppliers integrate TEMPO-oxidized nanofibrils into polypropylene compounds for lightweight structural components under EU end-of-life vehicle directives.
- Packaging:Barrier films with oxygen transmission rates below 1 cm³/m²/day replace metallized layers in modified atmosphere packaging. French and Dutch retailers specify nanocellulose-coated substrates for chilled ready-meal segments to meet single-use plastic reduction commitments.
- Coatings:Aqueous dispersions displace solvent-borne epoxy primers in marine maintenance cycles. Rotterdam and Singapore shipyards adopt carboxylated fibril formulations to comply with waterborne performance standards in port authority environmental codes.
- Biomedical:Wound dressings, drug delivery scaffolds, and cardiovascular patches require endotoxin levels below 0.25 EU/mL. Norwegian and Japanese certified bioreactors supply this segment under FDA and PMDA quality management systems.
Packaging absorbs the largest share of current output; biomedical applications show the steepest margin expansion trajectory.
End User:
End-user concentration reflects divergent certification requirements and supply chain proximity to pulp-processing infrastructure.
- Food Industry:Fresh produce processors in California and Florida specify bacterial cellulose films under FDA bio-based food contact material guidance. Barrier performance against moisture and oxygen drives specification in premium organic segments.
- Electronics:Osaka and Nagoya manufacturers pilot biodegradable substrate films for disposable sensors under METI carbon-neutral certification pathways. Transparent conductive layers for foldable displays require film-form nanocellulose with surface roughness below 5 nm.
- Automotive:Interior panel producers in Germany and France substitute glass fiber with nanofibril-reinforced compounds to reduce weight and improve recyclability scores under EU CSRD disclosure mandates.
- Pharmaceuticals:Excipient and drug delivery applications demand pharmaceutical-grade bacterial cellulose with documented supply chain traceability. Norwegian biorefineries anchor European supply through EMA-certified quality systems.
Food industry procurement dominates current volumes; electronics represents the fastest-climbing demand category.
Form:
Physical form selection determines logistics economics and downstream processing compatibility with existing capital equipment.
- Suspension:Aqueous dispersions at 2-10% solids content ship in bulk tankers to paper mills and coating operations. Scandinavian producers leverage short distribution distances to Nordic and German converters.
- Film:Cast or extruded sheets serve flexible electronics and biomedical applications requiring precise thickness control. Japanese and South Korean roll-to-roll coating lines integrate nanocellulose film casting for transparent substrate production.
- Dry Powder:Spray-dried or lyophilized products enable long-haul shipping to regions lacking local fibrillation infrastructure. Powder reconstitution requires high-shear mixing equipment standard in polymer compounding facilities.
- Gel:High-consistency hydrogels at 15-25% solids suit biomedical wound dressing applications where moisture retention and conformability matter. Aseptic packaging extends shelf life for hospital supply chains.
Suspension leads volume shipments today; film formats are expanding most quickly in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biorefinery engineers and pulp-process technologists cluster in Nordic forestry corridors, anchoring high-purity nanocellulose supply chains for biomedical and barrier film applications.
United States
Fresh produce processors in California and Florida drive bacterial cellulose film procurement under FDA bio-based food contact material guidance. The EPA's sustainable packaging initiatives accelerate substitution mandates in modified atmosphere packaging. Research consortia in the Boston-Cambridge corridor pilot nanocellulose substrates for flexible electronics prototypes.
Germany
Thermal insulation manufacturers in Bavaria and North Rhine-Westphalia substitute fluorinated gases with nanocellulose aerogels to meet EU F-Gas Regulation phasedown targets. The EU Green Deal enforcement compresses qualification timelines for barrier film converters. Automotive Tier 1 suppliers around Stuttgart integrate TEMPO-oxidized nanofibrils into lightweight interior compounds.
Japan
Electronics manufacturers in Osaka and Nagoya pilot biodegradable substrate films for disposable sensors under METI carbon-neutral certification pathways. The PMDA's implant-grade quality frameworks shape bacterial cellulose specifications for wound dressing applications. Pulp processors in Hokkaido leverage national biomass R&D subsidies to construct forestry-to-nanofibril demonstration plants.
Norway
Biomedical device manufacturers in Germany and Japan source pharmaceutical-grade bacterial cellulose from Norwegian certified bioreactors under EMA and PMDA quality systems. Borregaard AS leverages its Sarpsborg biorefinery complex to sustain high-purity output for endotoxin-sensitive applications. The country's hydropower infrastructure stabilizes energy inputs for mechanical fibrillation processes.
India
Packaging converters in Maharashtra and Gujarat anticipate BIS national biomass utilization codes to unlock barrier film commercialization. Draft standards create first-mover positioning for suppliers targeting food industry qualification cycles. Pulp-processing infrastructure in Kerala and Karnataka supplies feedstock for emerging nanofibril demonstration capacity.
Nanocellulose Market Vendor Landscape
Top-tier vendors anchor integrated pulp-to-nanofibril production, while standalone technology licensors occupy mid-tier licensing positions. The competitive landscape splits between Nordic kraft mill retrofits with captive cellulose supply and fermentation-based specialists serving premium biomedical segments. Three archetypes dominate: forestry-integrated biorefiners, bacterial cellulose fermentation specialists, and coating technology licensors. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure downstream offtake agreements.
Within the forestry-integrated tier, Borregaard AS and Stora Enso exemplify Nordic biorefinery operators with pulp-mill retrofit capabilities. CelluForce occupies a distinct position as a North American demonstration plant operator bridging scale-up gaps. Sappi Ltd. anchors the Southern Hemisphere vector through integrated pulp processing in South Africa and European operations.
| Leading Market Players |
|---|
| Borregaard AS |
| CelluForce |
| FiberLean Technologies |
| Nippon Paper Industries Co. Ltd. |
| Kruger Inc. |
| Sappi Ltd. |
| Stora Enso |
| GranBio Technologies |
| Oji Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
EU Green Deal single-use plastic reduction mandates gate qualified supply access and premium-tier pricing power for barrier film converters. Nordic pulp-mill retrofits command contract premiums while standalone producers face margin compression from energy cost volatility and qualification bottlenecks.
Pricing Analysis
Bundled pulp-to-nanofibril supply contracts dominate Nordic corridors while unbundled spot purchases concentrate among Asian packaging converters. Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial-grade certification levels separates bacterial cellulose pellicles from commodity fibril suspensions. Cost compression in nanofibril tiers is intensifying because mechanical fibrillation equipment retrofits at Scandinavian kraft mills collapse unit costs below standalone thresholds. Food industry buyers in California and Florida exhibit highest price sensitivity; biomedical device manufacturers in Germany and Japan demonstrate lowest sensitivity due to implant-grade certification requirements.
Supply Chain Analysis
EU domestic-content mandates under the Green Deal and CSRD disclosure frameworks are reshaping sourcing patterns for European packaging converters. Supply concentrates in Sweden, Norway, and Finland for nanofibril output; Norway and Japan anchor bacterial cellulose production. Raw material dependencies rest on kraft pulp feedstock, fermentation substrates for Acetobacter xylinum, and TEMPO oxidation chemicals. Single-source vulnerability from certified bioreactor concentration in Norwegian Sarpsborg and Japanese Hokkaido corridors creates qualification risk for biomedical-grade supply. Distribution runs through bulk tanker networks for aqueous suspensions to Nordic and German converters, with lyophilized powders enabling long-haul reach to Asian and North American markets lacking local fibrillation infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers sustained margin expansion as pulp-mill integration collapses production costs and biomedical-grade bacterial cellulose captures 15-20x commodity pricing multiples.
For Market Incumbents: Deepen backward integration into forestry residue supply chains in Nordic corridors to defend against emerging Asian pulp-mill retrofit competitors. Secure EMA and PMDA certification renewals for Norwegian bioreactor capacity to maintain implant-grade pricing power against Japanese fermentation specialists expanding output.
For New Entrants and Emerging Players: Coating formulators in Rotterdam and Singapore represent the most penetrable channel partner type for TEMPO-oxidized nanofibril aqueous dispersions displacing solvent-borne marine primers. Target Indian packaging clusters in Maharashtra and Gujarat ahead of finalized BIS biomass utilization codes to capture first-mover qualification slots for barrier film commercialization.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale fermentation specialists because pharmaceutical-grade bacterial cellulose certification scarcity creates durable moats against commodity competition. Acquire targets with FDA or PMDA quality management systems already operational. Watch EU compostability certification finalization under EN 13432 frameworks as the inflection signal determining which product forms capture scalable commercial slots.
| Strategic Initiative | Industry Significance |
|---|---|
| Pulp-Mill Retrofit Capacity Expansion | Mechanical fibrillation equipment at Swedish and Finnish kraft mills collapses nanofibril unit costs below standalone production thresholds. |
| Pharmaceutical-Grade Certification Investment | FDA and PMDA quality management systems for Norwegian bioreactors sustain 15-20x pricing multiples in biomedical applications. |
| Long-term Supply Agreement with Food Retailers | French and Dutch chilled ready-meal specifications under EU Green Deal create committed offtake for barrier film converters. |
| Joint Venture with Electronics Manufacturers | Osaka and Nagoya pilot programs for biodegradable sensor substrates under METI carbon-neutral pathways secure premium positioning. |
| Backward Integration into Forestry Residue Supply | Hokkaido and Kyushu demonstration plants linking forestry residues to nanofibril output reduce feedstock cost volatility. |
Methodological Framework
Direct dialogue with pulp mill operations managers, biomedical device procurement leads, barrier film converter technical directors, and marine coating formulators grounded qualitative findings. Secondary validation drew from EU REACH registration databases, FDA food contact material guidance documents, METI biomass strategy white papers, and Scandinavian kraft industry production statistics. Bottom-up volume estimates from individual facility capacities triangulated against top-down demand projections from end-use sector consumption patterns.
Segment-level value outputs across the analysis window reflect disaggregated modeling by product type, application, physical form, and end-user industry. CAGRs were derived from fitted growth curves incorporating EU F-Gas Regulation phasedown timelines, FDA approval velocity for bio-based packaging, and pulp-mill retrofit deployment schedules. Industry-specific inputs included electricity price volatility indices for Nordic mechanical fibrillation energy costs and fermentation cycle duration data for pharmaceutical-grade bacterial cellulose yield forecasting.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU compostability certification finalization, BIS standard promulgation in India, and METI subsidy continuity for Japanese demonstration plants. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and technology scale-up success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Mesoporous Carbons Market