
 Polymeric Nanoparticles Market | 2026-2036
Polymeric Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Polymeric Nanoparticles Market Intelligence
China is tilting toward domestic polymer nanoparticle capacity through state-backed advanced materials parks. BASF leverages its Ludwigshafen polymer science infrastructure to sustain European supply of nanosphere precursors. Evonik Industries AG anchors German output with specialized resorbable polymers for parenteral delivery. Cabot Corporation competes in North American colloidal silica-polymer hybrid systems for imaging contrast agents.
Polymeric nanoparticles are synthetic or natural polymer-based particulate systems ranging from 1 to 1000 nanometers, fabricated through emulsion polymerization or nanoprecipitation to encapsulate hydrophobic actives within amphiphilic block copolymer micelles or crosslinked nanosphere matrices. These carriers enhance bioavailability of poorly soluble therapeutics, enable sustained release kinetics, and permit surface functionalization for active targeting to tumor microenvironments or immune cell subsets. Nanospheres and nanocapsules dominate current pharmaceutical procurement due to established manufacturing scalability and regulatory familiarity, while polymersomes represent the fastest-expanding category as bilayer-structured vesicles gain traction for co-delivery of hydrophilic and hydrophobic payloads in combination therapy protocols. Targeted drug delivery applications command the largest value pool among clinical end-uses, though vaccine delivery formulations are accelerating fastest following mRNA platform validation.
The FDA's nanotechnology guidance framework and EMA's quality guideline on chemically synthesized peptides and oligonucleotides both impose characterization standards that filter out under-equipped manufacturers. REACH registration requirements in Europe and China's NMPA technical review standards for nanomedicines further raise barriers to market entry. Stakeholders must monitor evolving pharmacopeial monographs for polymer nanoparticle critical quality attributes and position manufacturing investments ahead of anticipated bioequivalence guidance revisions for complex generic nanomedicines.
Market Dynamics
Accelerated FDA nanomedicine approval pathways are compressing development timelines and forcing contract manufacturers to pre-validate polymer nanoparticle critical quality attributes ahead of commercial scale-up.
Growth Catalysts
- Oncology portfolio expansion:Pharmaceutical pipelines for targeted therapeutics are pulling nanosphere procurement volumes upward as sponsors prioritize tumor microenvironment penetration.
- EMA reflection papers:Europe's quality guidelines for nanotechnology-based medicines are standardizing characterization protocols that reduce regulatory uncertainty for cross-border filings.
- mRNA platform validation:Vaccine delivery applications are expanding polymer nanoparticle addressable demand beyond traditional small-molecule encapsulation.
Market Restraints
- Specialized polymer feedstock concentration:Resorbable polymer precursor supply clusters in German chemical parks, creating geographic single-source vulnerability.
- REACH registration burden:ECHA chemical safety dossier requirements impose six-figure compliance costs that filter out mid-scale entrants.
- Lipid nanoparticle substitution:Competing lipid-based delivery systems are capturing share in nucleic acid applications where polymeric alternatives show lower transfection efficiency.
Strategic Opportunities
- India's PLI scheme for pharmaceuticals:Domestic formulation incentives are drawing polymer nanoparticle technology transfer to CDMOs in Hyderabad and Ahmedabad clusters.
- Polymersome co-delivery protocols:Bilayer vesicle architectures enable simultaneous hydrophilic-hydrophobic payload carriage for combination oncology regimens.
- China's NMPA nanomedicine standards:Technical review guidelines are creating first-mover advantage for manufacturers with established Chinese pharmacopeial dossiers.
Industry Challenges
- Process analytical technology integration:Real-time release testing for particle size distribution and zeta potential demands capital-intensive PAT infrastructure.
- Pharmacopeial monograph lag:Absence of harmonized polymer nanoparticle critical quality attribute standards forces redundant characterization across FDA, EMA, and NMPA submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymeric Nanoparticles Market |
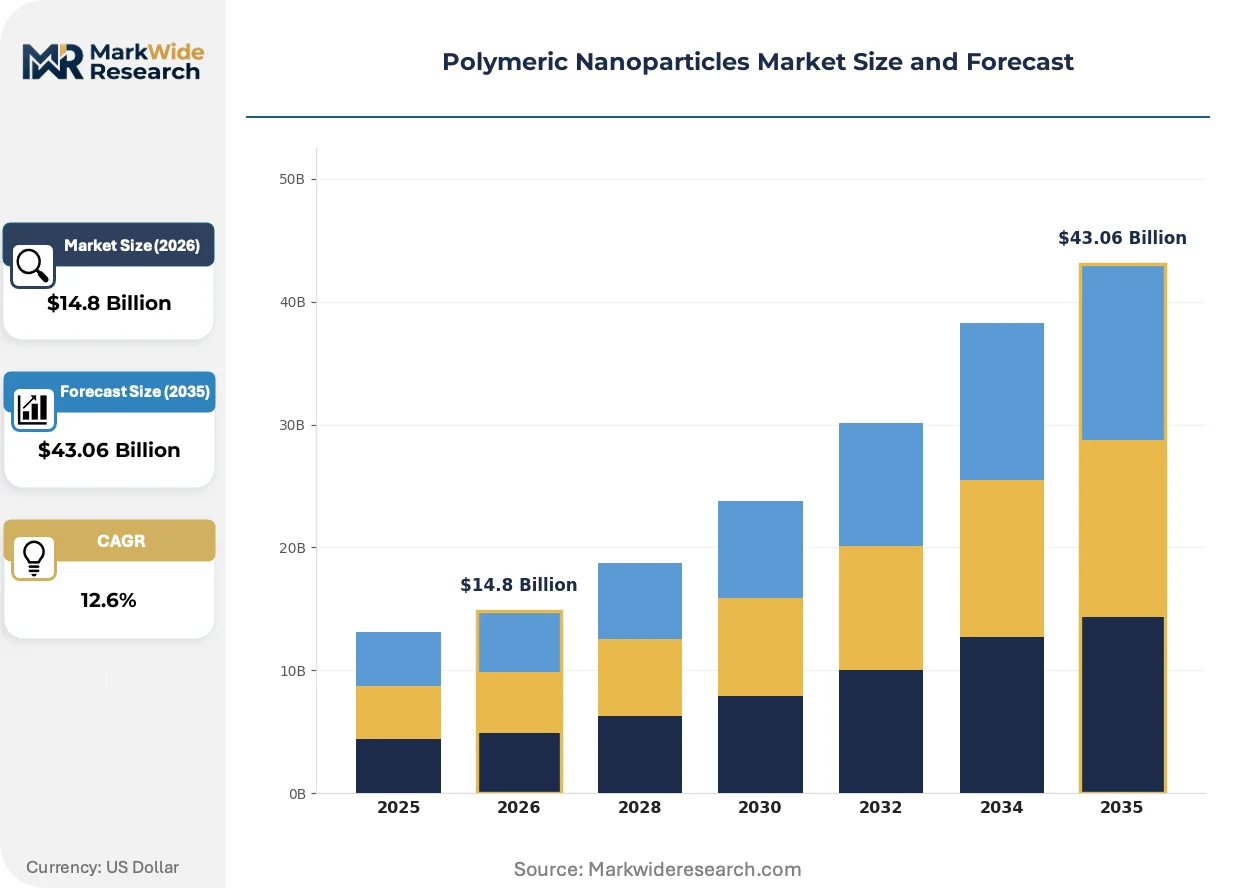
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micelles, Dendrimers, Nanocapsules, Nanospheres, Polymersomes Application: Targeted Drug Delivery, Gene Therapy, Imaging, Vaccine Delivery, Diagnostic Agents End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Contract Manufacturing Organizations Fabrication Method: Emulsion Polymerization, Nanoprecipitation, Solvent Evaporation, Dialysis, Microfluidics |
| Companies Covered | Cabot Corporation, Precision NanoSystems, Arkema, Aphios Corporation, Hybrid Plastics Inc, BASF, CD Bioparticles, Nanorh, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymeric Nanoparticles Market Strategic Shifts & Innovations
Digital integration of manufacturing execution systems with quality control analytics is compressing batch release cycles and enabling continuous processing for polymer nanoparticle production.
Process analytical technology is digitizing polymer nanoparticle manufacturing by embedding in-line spectroscopic probes for real-time particle size monitoring. Contract manufacturers in the United States are retrofitting legacy batch reactors with PAT-enabled feedback loops to reduce offline testing burden. This shift is digitizing quality assurance workflows and collapsing the traditional 14-day batch release window to 72-hour turnaround.
EMA's quality guideline on chemically synthesized peptides and oligonucleotides is extending characterization requirements to polymer nanoparticle excipient components. European manufacturers must now submit forced degradation studies and impurity profiling for block copolymer starting materials. Oncology-focused CDMOs in Germany and Switzerland are responding by qualifying second-source polymer suppliers ahead of anticipated guideline enforcement.
Formulation sponsors are consolidating procurement under single-source CDMO relationships that bundle polymer synthesis, nanoparticle fabrication, and sterile fill-finish. This bundling is displacing the historical three-vendor model where sponsors separately sourced polymers, manufactured nanoparticles, and contracted aseptic processing. The shift is most visible among mid-cap biotechnology firms in the Boston-Cambridge cluster seeking to compress CMC timeline risk.
Polymeric Nanoparticles Market Segmentation
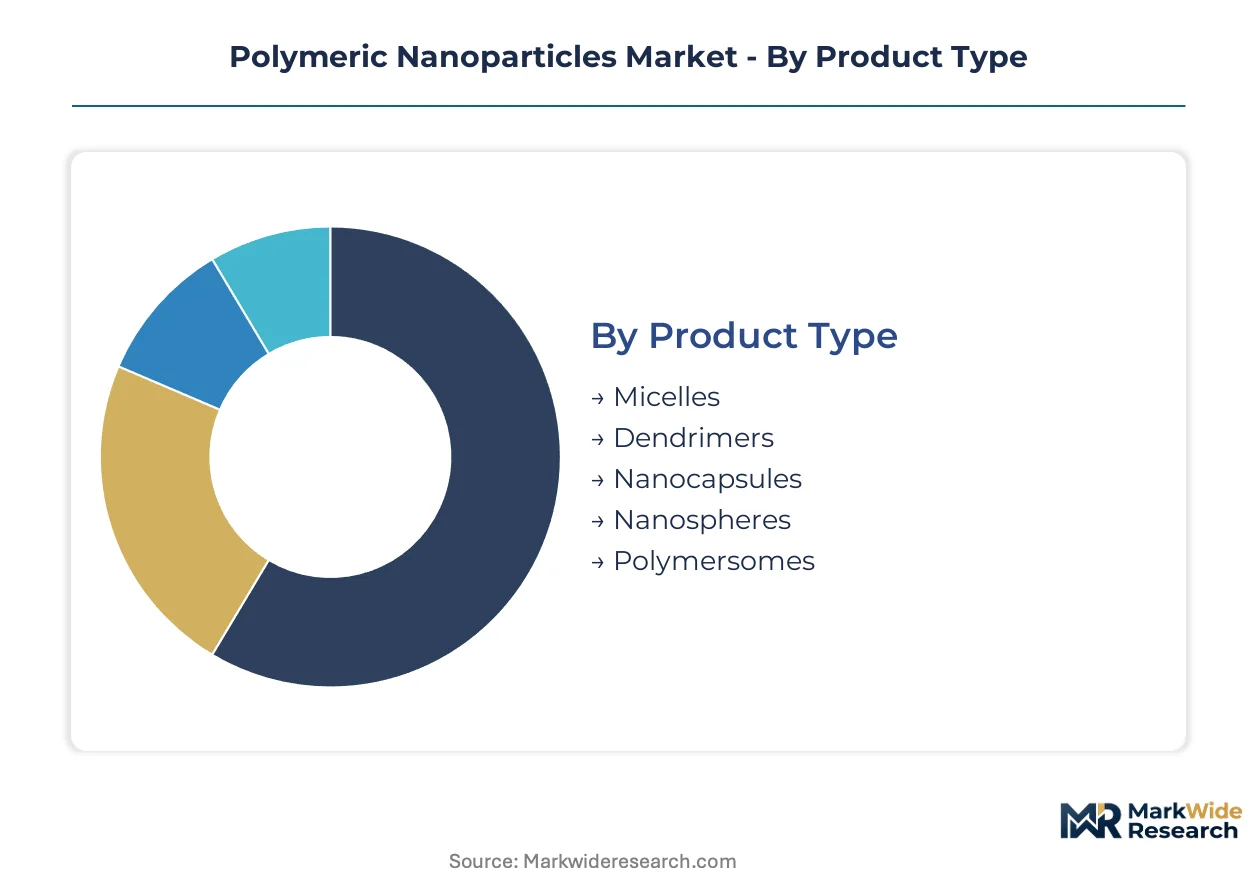
Polymeric nanoparticle procurement patterns diverge sharply across therapeutic modality, fabrication scale, and regulatory pathway maturity. Pharmaceutical sponsors select carrier architectures based on payload physicochemistry, manufacturing reproducibility requirements, and target tissue penetration profiles.
Product Type:
Carrier architecture determines encapsulation efficiency, release kinetics, and surface functionalization capacity across the therapeutic use-case spectrum.
- Nanospheres:Solid matrix structures fabricated through emulsion polymerization or nanoprecipitation enable sustained release of hydrophobic actives. Oncology pipelines in the United States and Germany dominate procurement volumes as sponsors prioritize tumor microenvironment penetration with PEGylated surface modifications.
- Polymersomes:Bilayer vesicle architectures assembled from amphiphilic block copolymers accommodate simultaneous carriage of hydrophilic and hydrophobic payloads. Combination therapy protocols in Swiss and Japanese research institutes are pulling adoption upward for co-delivery applications requiring precise stoichiometric control.
- Micelles:Self-assembled core-shell structures from amphiphilic polymers.
- Dendrimers:Highly branched synthetic macromolecules with defined molecular weight.
- Nanocapsules:Core-shell systems with liquid or oil-filled cavities for hydrophobic drug reservoirs.
Established volume favors nanospheres; emerging adoption favors polymersomes.
Application:
Clinical end-use segments map directly to reimbursement pathways, regulatory precedent density, and manufacturing complexity tiers.
- Targeted Drug Delivery:Surface-functionalized carriers directed to tumor antigens or immune cell subsets command premium procurement pricing. FDA's accelerated approval pathways for nanomedicines have compressed development timelines, concentrating sponsor investment in active targeting programs for oncology and inflammatory disease.
- Vaccine Delivery:mRNA platform validation has expanded addressable demand beyond traditional small-molecule encapsulation. CDMOs in the United States and Germany are scaling lipid-polymer hybrid capacity to serve infectious disease and personalized neoantigen programs.
- Gene Therapy:Nucleic acid carriage for CRISPR and mRNA therapeutics.
- Imaging:Contrast agent delivery for MRI and optical modalities.
- Diagnostic Agents:Biosensing and in vitro diagnostic applications.
Revenue concentration sits with targeted drug delivery; steepest expansion trajectory belongs to vaccine delivery.
End User:
Customer organizational structure dictates procurement bundling preferences, quality agreement complexity, and technology transfer requirements.
- Pharmaceutical Companies:Large-cap sponsors with internal nanomedicine capabilities are consolidating procurement under single-source CDMO relationships. This bundling displaces the historical three-vendor model across Boston-Cambridge and Basel clusters as firms compress CMC timeline risk.
- Contract Manufacturing Organizations:Specialized CDMOs with integrated polymer synthesis and aseptic processing capabilities are capturing share from fragmented vendor bases. Hyderabad and Ahmedabad clusters in India are drawing technology transfer through PLI scheme incentives for domestic formulation.
- Biotechnology Firms:Venture-backed developers lacking internal manufacturing infrastructure.
- Research Institutes:Academic and government laboratories with exploratory programs.
Procurement volume concentrates in pharmaceutical companies; fastest capability buildup is occurring at contract manufacturing organizations.
Fabrication Method:
Process technology selection balances particle size distribution control, scalability economics, and regulatory familiarity.
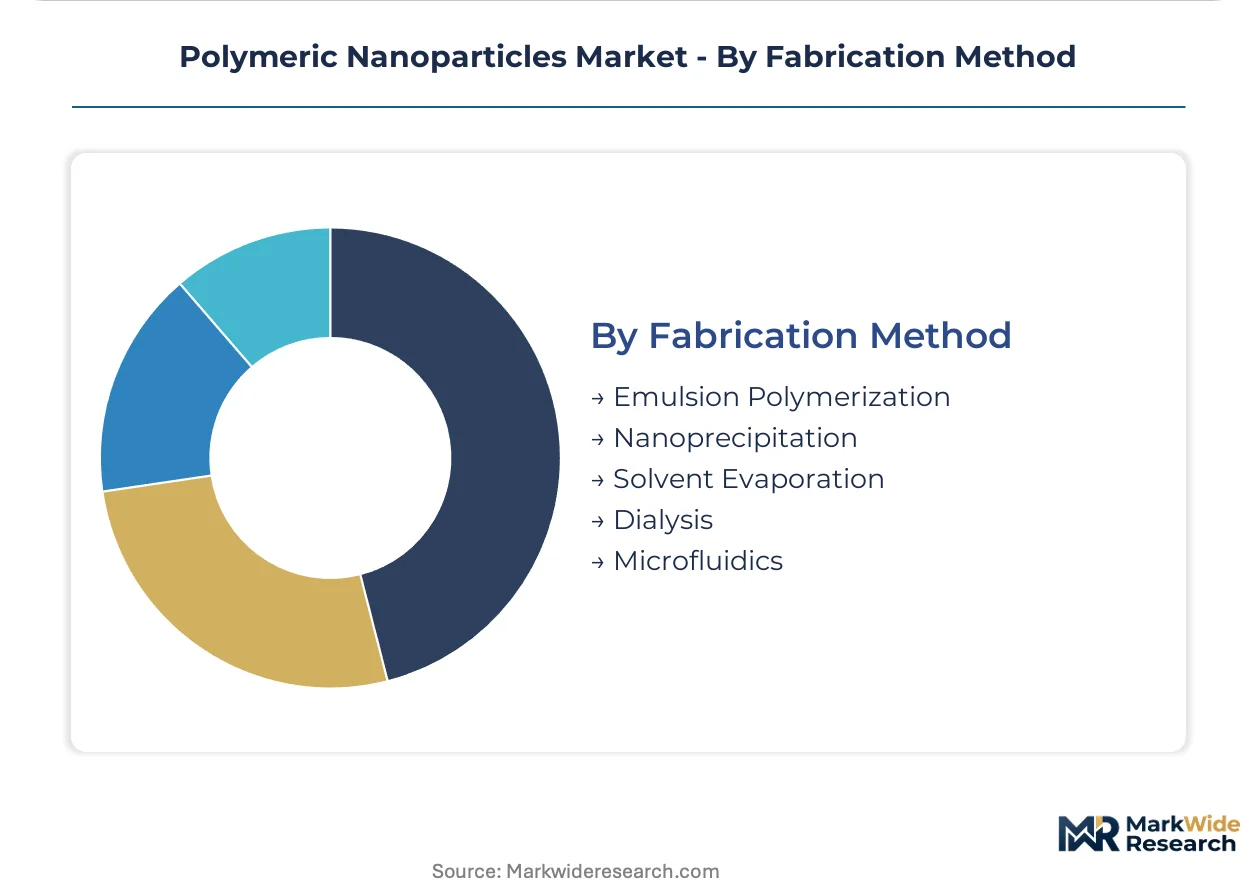
- Emulsion Polymerization:Established aqueous-phase technique for hydrophobic monomer polymerization into nanosphere matrices. German and Japanese manufacturers maintain active production lines with validated critical quality attribute protocols for commercial supply.
- Nanoprecipitation:Solvent displacement method enabling precise control over particle size for hydrophobic drug encapsulation. United States-based CDMOs are retrofitting legacy batch reactors with process analytical technology for real-time release testing.
- Solvent Evaporation:Conventional batch technique for polymeric nanocapsule formation.
- Dialysis:Membrane-based purification for self-assembled micelle systems.
- Microfluidics:Continuous flow processing for tight particle size distribution control.
Regulatory familiarity favors emulsion polymerization; process innovation investment flows toward microfluidics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymeric nanoparticle consumption patterns diverge sharply by geography: the United States and Germany prioritize oncology-targeted drug delivery systems, while China and India concentrate procurement on vaccine delivery platforms and cost-sensitive generic nanomedicines.
United States
FDA's accelerated approval pathways for nanomedicines compress development timelines for oncology sponsors. The 21st Century Cures Act provisions incentivize breakthrough therapy designations for tumor-targeted carriers. Boston-Cambridge biotechnology clusters drive procurement consolidation under single-source CDMO relationships.
Germany
EMA reflection papers on nanotechnology-based medicines standardize characterization protocols for cross-border filings. REACH registration requirements filter mid-scale entrants from resorbable polymer supply chains. Ludwigshafen and Frankfurt chemical parks anchor European nanosphere precursor production.
China
NMPA technical review standards for nanomedicines create first-mover advantages for manufacturers with established pharmacopeial dossiers. State-backed advanced materials parks in Jiangsu and Zhejiang provinces tilt capacity toward domestic polymer nanoparticle production.
India
PLI scheme incentives for domestic pharmaceutical formulation draw technology transfer to Hyderabad and Ahmedabad CDMO clusters. CDSCO quality guidelines for complex generics raise manufacturing standards for export-oriented nanomedicine production.
Japan
PMDA consultations on nanomedicine quality attributes guide sponsor preparation for Sakigake fast-track reviews. Kansai and Kanto pharmaceutical manufacturing belts maintain active polymer nanoparticle production lines for regional supply.
Polymeric Nanoparticles Market Key Industry Players
Capability concentration sits with specialized polymer science divisions of diversified chemical conglomerates; scale advantage sits with contract manufacturing organizations bundling synthesis, fabrication, and aseptic processing. The market structures around three tiers: integrated chemical majors with captive polymer feedstock, mid-scale CDMOs with validated nanoparticle platforms, and emerging technology licensors with microfluidic process patents. Dominant competitive moves include backward integration into resorbable polymer precursor supply and geographic expansion into Indian and Chinese manufacturing clusters.
Among German chemical majors, BASF and Evonik Industries AG occupy positions anchoring European nanosphere precursor supply through Ludwigshafen infrastructure and specialized resorbable polymer portfolios. Cabot Corporation exemplifies North American competition in colloidal silica-polymer hybrid systems. These three represent distinct archetypes: diversified chemical conglomerate, specialized pharmaceutical excipient supplier, and hybrid materials innovator.
| Leading Market Players |
|---|
| Cabot Corporation |
| Precision NanoSystems |
| Arkema |
| Aphios Corporation |
| Hybrid Plastics Inc |
| BASF |
| CD Bioparticles |
| Nanorh |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
German chemical parks in Ludwigshafen and Frankfurt concentrate resorbable polymer precursor supply, anchoring margin pools with CDMOs that bundle polymer synthesis, nanoparticle fabrication, and sterile fill-finish capabilities. This upstream concentration enables premium pricing for integrated service offerings while forcing fragmented polymer suppliers into commoditized feedstock tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement between large-cap pharmaceutical sponsors and integrated CDMOs, compressing spot-market liquidity for standard nanosphere grades. Three-tier pricing structure across GMP-certified premium, validated-standard, and developmental-economy levels reflects FDA/EMA/NMPA registration status. Pricing pressure stems from lipid nanoparticle substitution in nucleic acid applications where polymeric alternatives show lower transfection efficiency. Mid-cap biotechnology firms in the Boston-Cambridge cluster exhibit highest price sensitivity, prioritizing CMC timeline risk reduction over per-unit cost.
Supply Chain Analysis
Export-control restrictions on microfluidic fabrication equipment limit technology transfer to Indian and Chinese manufacturing clusters, constraining capacity expansion timelines. Resorbable polymer production centers on Germany, specialized block copolymer synthesis concentrates in Japan and Switzerland, and sterile fill-finish capacity clusters in the United States and Ireland. Raw material dependencies span PLGA/PLA precursors, PEGylation reagents, and amphiphilic block copolymers. Single-source vulnerability in German chemical parks for pharmaceutical-grade resorbable polymers creates concentration risk. Distribution runs through qualified supplier networks with audited quality agreements rather than open commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymeric nanoparticle procurement increasingly attaches process analytical technology services and regulatory dossier maintenance as recurring-revenue layers expanding faster than base particle fabrication. CDMOs bundling real-time release testing and pharmacopeial submission support capture disproportionate margin expansion.
For Market Incumbents: Entrench position by qualifying second-source polymer suppliers ahead of EMA guideline enforcement on block copolymer impurity profiling, and by retrofitting legacy batch reactors with PAT-enabled feedback loops to compress batch release cycles. Lipid nanopptide substitution in mRNA applications threatens polymeric carrier share; defensive capacity addition in polymersome co-delivery platforms addresses combination therapy protocol demand from Swiss and Japanese research institutes. For New Entrants and Emerging Players: Pursue white-space opportunity in India's Hyderabad and Ahmedabad CDMO clusters where PLI scheme incentives for domestic formulation draw technology transfer away from fragmented European vendor bases. Vaccine delivery applications show most penetrable demand expansion following mRNA platform validation. Go-to-market positioning as NMPA-registered suppliers for Chinese pharmacopeial dossiers creates first-mover advantage against Western incumbents with slower regulatory adaptation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMOs that consolidated polymer synthesis and aseptic processing capabilities but lack integrated PAT infrastructure for real-time release testing. Five-to-ten year viability hinges on backward integration into resorbable polymer precursor supply or geographic expansion into Indian and Chinese manufacturing clusters. Signal to monitor: FDA bioequivalence guidance revisions for complex generic nanomedicines that would force redundant characterization investments and filter out under-equipped contract manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Integration | PAT-enabled feedback loops collapse 14-day batch release windows to 72-hour turnaround at FDA-inspected CDMOs. |
| Backward Integration into Polymer Precursors | Captive resorbable polymer supply insulates against REACH registration burden filtering mid-scale German entrants. |
| Polymersome Co-Delivery Platform Development | Bilayer vesicle architectures enable simultaneous hydrophilic-hydrophobic payload carriage for combination oncology regimens. |
| NMPA Pharmacopeial Dossier Investment | Established Chinese regulatory dossiers create first-mover advantage ahead of evolving nanomedicine technical review standards. |
| Single-Source CDMO Relationship Consolidation | Bundling polymer synthesis, nanoparticle fabrication, and sterile fill-finish compresses CMC timeline risk for Boston-Cambridge biotechnology firms. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at nanomedicine sponsors, CDMO procurement directors, and polymer science R&D directors; and secondary validation against FDA nanotechnology guidance documents, EMA reflection papers on nanotechnology-based medicines, NMPA technical review standards, and pharmacopeial monograph drafts for polymer nanoparticle critical quality attributes. Bottom-up triangulation across fabrication method and application segments was cross-checked against top-down chemical industry trade data and SEC filings from listed polymer suppliers.
Forecast inputs considered oncology pipeline expansion rates, mRNA platform validation trajectories, and regulatory pathway compression effects across the projection horizon. Segmentation modeling incorporated carrier architecture, therapeutic application, end-user organizational structure, and fabrication scale tiers. CAGRs were derived from growth rate reconciliation across demand-side sponsor investment intentions and supply-side capacity expansion announcements. Industry-specific inputs included EMA guideline enforcement timelines and PLI scheme incentive uptake rates in Indian pharmaceutical clusters.
Sensitivities concentrate around FDA bioequivalence guidance revisions for complex generic nanomedicines and EMA quality guideline enforcement timelines for block copolymer starting materials. Forecasts reflect documented assumptions on regulatory pathway maturation and CDMO consolidation trajectories. Material shifts in lipid nanoparticle substitution rates or REACH registration requirement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Nanotools Market