
 Global Nanocrystalline Cellulose Market | 2026-2036
Global Nanocrystalline Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanocrystalline Cellulose Market Foresight
Finland is reconfiguring its forestry value chain around advanced cellulose derivatives, drawing downstream investment into nanocrystalline processing. Borregaard leverages its integrated lignin-cellulose complex in Sarpsborg to sustain captive nanocellulose supply. Stora Enso anchors Nordic capacity through its Sunila biorefinery platform and pilot extraction lines. CelluForce competes from Quebec with commercial-scale acid hydrolysis output directed at North American barrier coating buyers.
Nanocrystalline cellulose consists of rod-shaped cellulose crystallites, typically 3–50 nanometers in width and 100–3,000 nanometers in length, extracted through controlled acid hydrolysis or enzymatic treatment of native cellulose fibers. These crystallites deliver exceptional tensile strength exceeding 1 GPa alongside low thermal expansion, making them functional reinforcements in polymer nanocomposites, rheology modifiers, and oxygen barrier layers. Powder formulations dominate current revenue pools due to established handling infrastructure and dosing compatibility with extrusion and coating lines. Suspension grades in aqueous media are expanding fastest among cosmetics formulators seeking sustainable texturizing agents to replace petrochemical thickeners. Pharmaceutical applications remain nascent but carry premium positioning potential as tablet binders and controlled-release matrices subject to pharmacopeial validation.
FDA bio-based packaging contact notifications and EU REACH polymer additive registrations shape commercialization timelines for food-facing nanocellulose grades. The EU Green Deal's packaging waste directives and Japan's METI bioplastics procurement guidelines are tightening specifications for renewable content claims and biodegradability certification. Stakeholders must monitor evolving ISO/TC 6 nanocellulose terminology standards and toxicological clearance pathways, as regulatory alignment between jurisdictions will determine which production formats achieve cross-border scale.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing commercialization timelines for bio-based barrier materials, forcing converters to qualify nanocellulose ahead of virgin plastic phase-outs.
Growth Catalysts
- EU Green Deal mandates:Binding renewable content targets in food packaging are pulling converters toward cellulose nanomaterial qualification protocols ahead of 2030 compliance deadlines.
- Cosmetics formulators:Suspension-grade nanocrystalline cellulose is displacing petrochemical thickeners as brands reformulate for biodegradability certification.
- Nordic pulp clusters:Integrated biorefinery infrastructure around Borregaard and Stora Enso operations is concentrating extraction capacity and reducing feedstock transit costs.
Market Restraints
- Acid hydrolysis energy intensity:Sulfuric acid recovery and wastewater treatment add 15-25% to production costs versus conventional cellulose derivatives.
- Single-source supply risk:Commercial-scale output concentrates in Sarpsborg, Sunila, and Quebec facilities, creating vulnerability to localized pulp supply disruptions.
- Pharmacopeial validation gaps:Absence of harmonized USP and EP monographs for nanocellulose tablet binders delays pharmaceutical uptake.
Strategic Opportunities
- Japan METI bioplastics procurement:Government purchasing guidelines are creating preferential market access for certified bio-based barrier coatings in food service applications.
- Controlled-release matrices:Pharmaceutical formulators are exploring nanocellulose hydrogels for oral dosage innovation pending toxicological clearance.
- Enzymatic extraction convergence:Cellulase pretreatment combined with mechanical fibrillation is opening lower-energy pathways for cosmetic-grade suspensions.
Industry Challenges
- ISO/TC 6 terminology standardization:Inconsistent definitions between nanocrystalline cellulose, cellulose nanocrystals, and whiskers are complicating cross-border procurement specifications.
- Extrusion line retrofitting:Powder dosing systems designed for mineral fillers require recalibration for nanocellulose's low bulk density and electrostatic behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanocrystalline Cellulose Market |
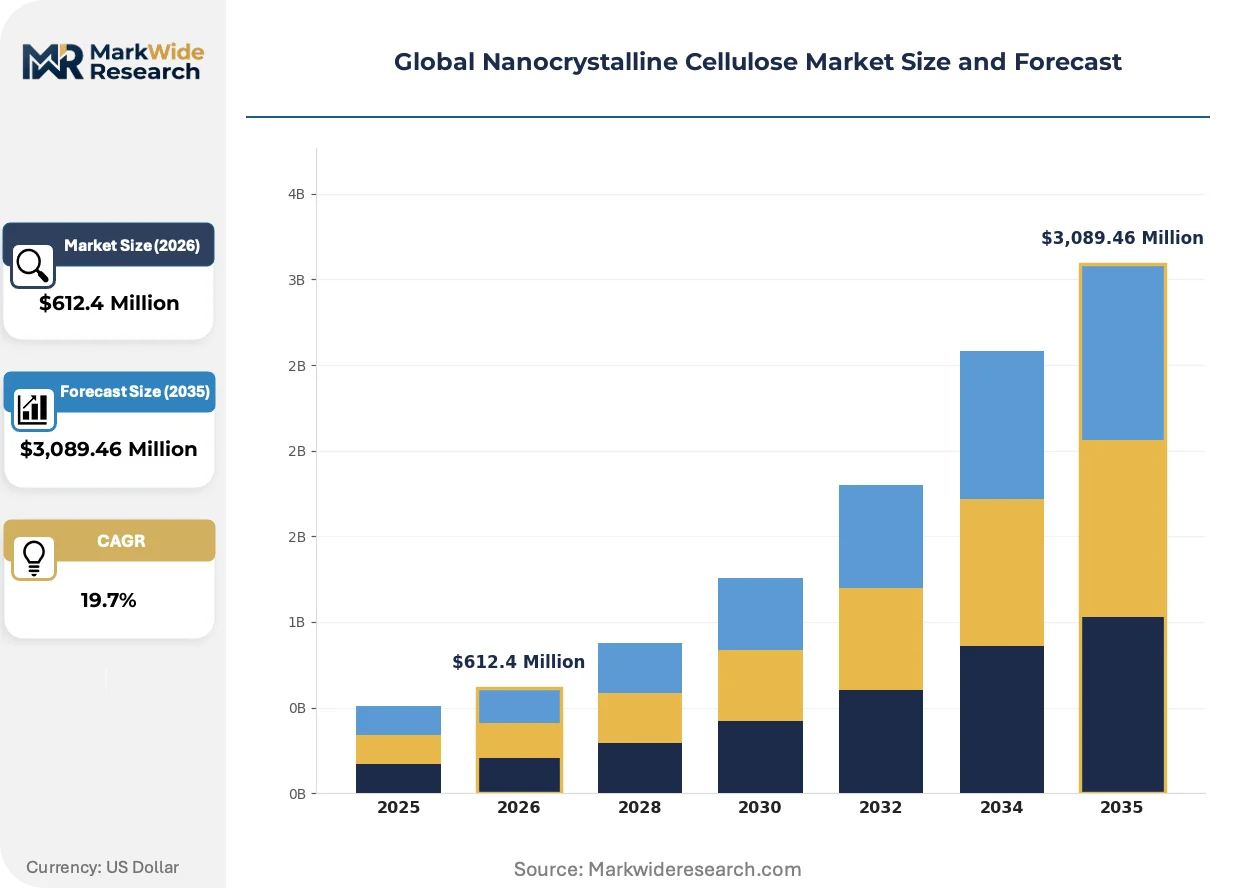
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $3,089.46 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Suspension, Film, Composite, Aerogel Application: Packaging, Cosmetics, Electronics, Pharmaceuticals, Construction End User Industry: Food Processing, Personal Care, Consumer Electronics, Pharmaceutical Manufacturing, Building Materials Technology: Mechanical Treatment, Acid Hydrolysis, Enzymatic Hydrolysis, Oxidative Methods, Ultrasonication |
| Companies Covered | CelluForce, FiberLean, NIPPON PAPER INDUSTRIES, Kruger, Borregaard, GranBio, Melodea, CelluComp, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanocrystalline Cellulose Market Shifts & Advancements
Processing technology is hybridizing with adjacent biorefinery disciplines, while regulatory alignment and procurement specification tightening are compressing qualification cycles for first-time suppliers.
Acid hydrolysis is hybridizing with enzymatic pretreatment protocols to reduce sulfuric acid consumption and energy inputs. Packaging converters in Germany are piloting these modified extraction routes for barrier film applications. The structural consequence is a compression of capital intensity thresholds for mid-scale entrants previously excluded from commercial viability.
REACH polymer additive registrations are tightening data requirements for nanomaterial migration studies in food contact applications. ECHA's updated guidance demands comprehensive toxicological dossiers before market authorization. Nordic suppliers with existing cellulose derivative portfolios are leveraging grandfathered compliance pathways to accelerate clearance timelines relative to new market entrants.
Specification-driven procurement is consolidating buyer power among multinational packaging groups with dedicated bio-based materials teams. These centralized technical purchasing functions are displacing decentralized resin procurement decisions at individual plant levels. The shift is most visible in German and Japanese converter networks where sustainability scorecards now govern supplier qualification.
Global Nanocrystalline Cellulose Market Segmentation
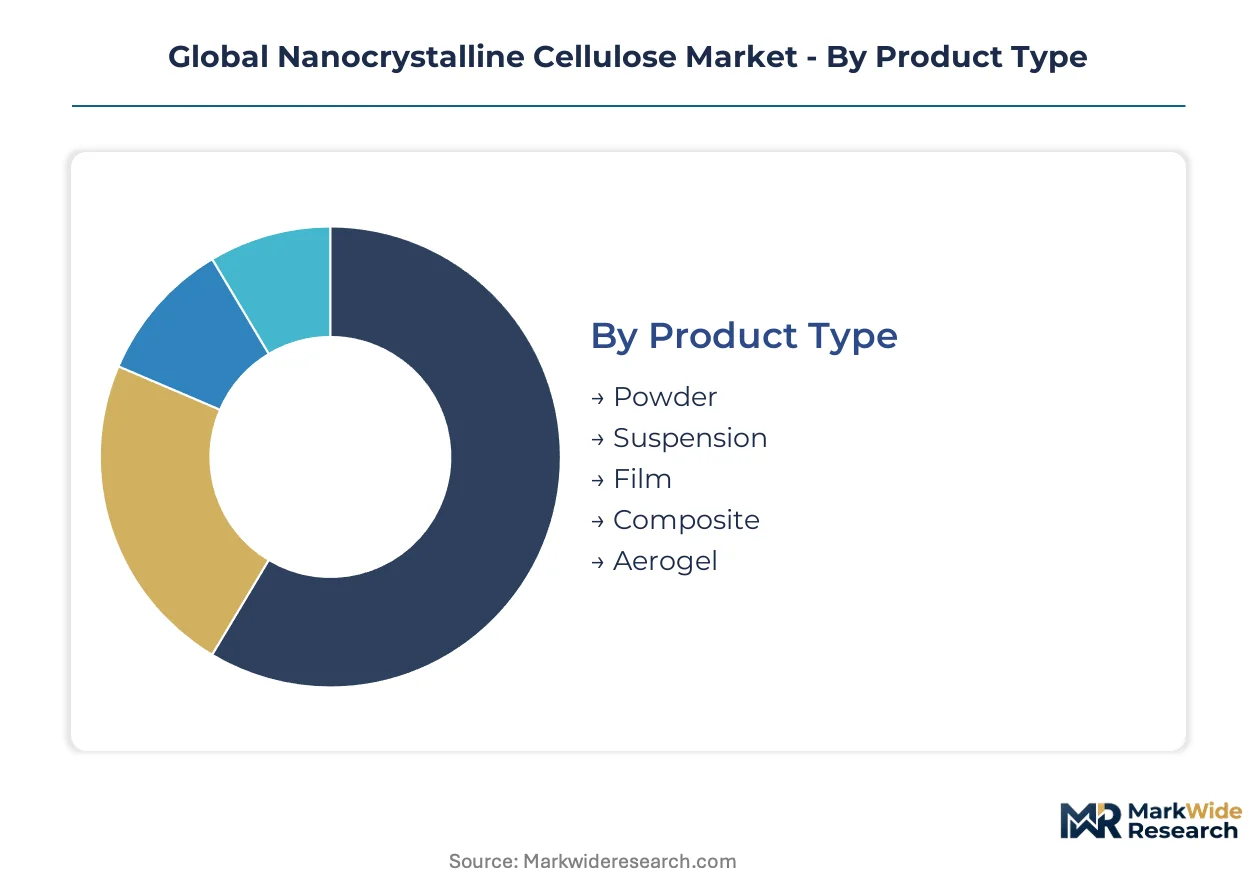
Nanocrystalline cellulose producers must align product formats with distinct customer workflows across barrier packaging, cosmetic formulation, and pharmaceutical compounding. Segment boundaries reflect divergent purity requirements, handling infrastructure, and regulatory clearance pathways that shape commercialization priorities.
Product Type:
Form factor selection governs integration complexity across powder handling systems, liquid dosing equipment, and film casting lines.
- Powder:Dried crystallite aggregates with established bulk handling protocols integrate directly into twin-screw extrusion and dry-blend compounding operations. Food packaging converters in Germany favor powder grades for oxygen barrier masterbatch production where precise dosing into polyethylene matrices is critical.
- Suspension:Aqueous dispersions at 5-15% solids content eliminate dust exposure and enable direct incorporation into water-based coating formulations. Personal care formulators in Japan are qualifying suspension grades for sustainable rheology modification as brands phase out carbomer and xanthan gum thickeners.
- Film:Cast nanocellulose substrates with self-standing mechanical properties serve as biodegradable base layers for multilayer barrier structures.
- Composite:Pre-compounded nanocellulose-polymer concentrates reduce downstream dispersion challenges for injection molders.
- Aerogel:Supercritically dried ultra-lightweight structures target thermal insulation and oil absorption applications with extended qualification timelines.
The dominant share belongs to Powder, while Suspension is closing the gap fastest.
Application:
End-use maturity spans commercial-scale packaging trials through preclinical pharmaceutical exploration.
- Packaging:Oxygen barrier coatings and film reinforcements dominate current offtake as converters respond to EU Green Deal renewable content mandates. Nordic pulp clusters supply qualified grades for dairy and dry goods applications with established migration testing protocols.
- Cosmetics:Rheology modification and emulsion stabilization are displacing petrochemical thickeners in premium skincare lines. Japanese and South Korean formulators lead qualification for biodegradability-certified color cosmetics.
- Electronics:Low-thermal-expansion substrates for flexible printed circuit boards remain developmental with extended OEM validation cycles.
- Pharmaceuticals:Tablet binding and controlled-release matrix applications await harmonized USP-EP monograph development.
- Construction:Cement rheology modification and insulation additives face cost competition from established mineral alternatives.
Packaging commands the largest revenue pool, though Cosmetics exhibits the steepest expansion trajectory.
End User Industry:
Customer technical sophistication ranges from commodity resin procurement to pharmacopeial-grade validation.
- Food Processing:Barrier film converters and rigid packaging manufacturers drive standardized powder grade demand with batch consistency requirements.
- Personal Care:Multinational cosmetic houses and contract manufacturers specify suspension grades with defined particle size distributions for texture engineering.
- Consumer Electronics:Flexible display and printed circuit substrate developers represent emerging demand with extended qualification horizons.
- Pharmaceutical Manufacturing:Dosage form innovators and excipient suppliers await toxicological clearance for oral and topical applications.
- Building Materials:Cement and insulation producers evaluate cost-performance tradeoffs against incumbent additives.
Food Processing anchors volume commitments, while Personal Care is gaining share fastest on sustainability-driven reformulation.
Technology:
Extraction method selection determines capital intensity, energy consumption, and product morphology specifications.
- Acid Hydrolysis:Sulfuric acid treatment of bleached pulp remains the commercial standard for crystallite isolation with controlled aspect ratios. Borregaard's Sarpsborg complex and CelluForce's Quebec facility operate at scale with integrated acid recovery systems.
- Enzymatic Hydrolysis:Cellulase pretreatment combined with mechanical fibrillation reduces chemical inputs and targets cosmetic-grade suspensions with milder processing conditions. German packaging converters are piloting these modified routes for barrier film applications.
- Mechanical Treatment:High-pressure homogenization and grinding without chemical pretreatment yields lower-purity grades for cost-sensitive construction applications.
- Oxidative Methods:TEMPO-mediated oxidation introduces carboxyl surface functionalization for enhanced dispersion stability in polar matrices.
- Ultrasonication:Cavitation-assisted fibrillation remains laboratory-scale with unproven energy economics for commercial deployment.
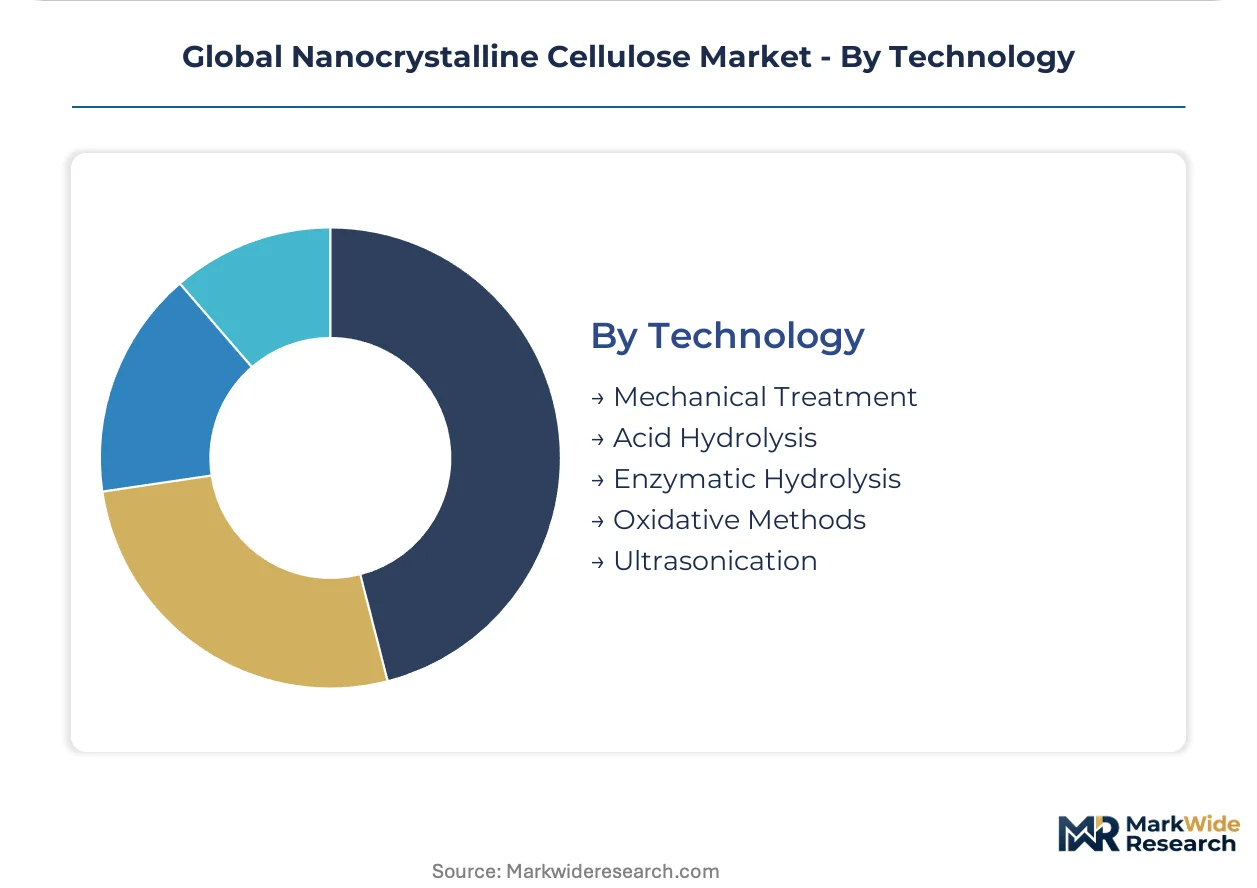
Acid Hydrolysis retains the dominant installed base, though Enzymatic Hydrolysis is climbing the fastest on sustainability metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's biobulk terminal infrastructure underwrites Northwestern Europe's cellulose nanomaterial distribution, while Quebec's St. Lawrence Seaway access anchors North American feedstock flows to barrier coating converters.
Germany
Packaging converters in the Rhine-Ruhr industrial corridor are trialing enzymatic hydrolysis routes for oxygen barrier films. The EU Green Deal's binding renewable content targets are compressing qualification timelines for dairy and dry goods applications. Bavaria's chemical processing clusters near Munich host pilot extrusion lines retrofitting powder dosing systems for nanocellulose masterbatch production.
Japan
Cosmetics formulators in the Kanto region are qualifying suspension-grade nanocrystalline cellulose to replace petrochemical thickeners in color cosmetics. METI's bioplastics procurement guidelines are creating preferential market access for certified bio-based barrier coatings in food service applications. Osaka-based personal care manufacturers are driving biodegradability certification demand through reformulation programs.
Norway
Borregaard's integrated lignin-cellulose complex in Sarpsborg sustains captive nanocellulose supply for European barrier film converters. The EU REACH polymer additive registration framework is accelerating toxicological dossier preparation for food contact grades. The Oslofjord region's pulp processing infrastructure concentrates extraction capacity with integrated acid recovery systems.
Finland
Stora Enso's Sunila biorefinery platform anchors Nordic nanocellulose capacity through pilot extraction lines serving packaging trials. The country's forestry value chain reconfiguration is drawing downstream investment into advanced cellulose derivative processing. Kotka-Hamina port logistics reduce feedstock transit costs for Baltic Sea converter networks.
Canada
CelluForce's Quebec facility operates commercial-scale acid hydrolysis output directed at North American barrier coating buyers. The St. Lawrence Seaway connects Great Lakes pulp sources to Atlantic packaging converter markets. Montreal's materials science research institutes are supporting migration testing protocols for FDA bio-based packaging contact notifications.
Global Nanocrystalline Cellulose Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The nanocrystalline cellulose sector exhibits concentrated supply-side structure with commercial-scale output clustering around integrated biorefinery complexes. Three archetypes dominate: pulp-integrated majors leveraging captive feedstock, independent extraction specialists licensing acid hydrolysis technology, and regional converters backward-integrating into nanomaterial production. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing acid recovery infrastructure and barrier coating qualification pipelines.
Among Nordic pulp-integrated operators, Borregaard and Stora Enso exemplify the captive supply archetype through Norwegian and Finnish biorefinery platforms. CelluForce occupies a position as the North American independent specialist with Quebec-based commercial output. These three anchors represent divergent geographic strategies for serving packaging converter demand across EU Green Deal compliance timelines and Japanese METI procurement frameworks.
| Leading Market Players |
|---|
| CelluForce |
| FiberLean |
| NIPPON PAPER INDUSTRIES |
| Kruger |
| Borregaard |
| GranBio |
| Melodea |
| CelluComp |
| Stora Enso |
| Others |
Supply & Pricing Matrix
Single-source supply risk concentrated in Sarpsborg, Sunila, and Quebec facilities compresses pricing tier spreads between pharmaceutical-grade and industrial-grade nanocrystalline cellulose while simultaneously forcing converters to maintain dual-qualification inventories. EU REACH registration costs and acid recovery infrastructure investments create a structural moat that protects incumbent pricing power against margin erosion from emerging enzymatic extraction routes.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade powder from cosmetic suspension and industrial composite grades, with certification level and acid hydrolysis energy intensity driving spreads between tiers. Price differentiation stems from USP-EP monograph development status and integrated biorefinery feedstock access, with cost compression in standard grades intensifying as German packaging converters pilot enzymatic alternatives. Food processing buyers exhibit highest price sensitivity due to commodity resin substitution options, while pharmaceutical formulators accept premium positioning pending toxicological clearance.
Supply Chain Analysis
Extended payment terms from Nordic pulp-integrated majors to German and Japanese barrier film converters reflect supply-chain finance facilities anchored in Oslofjord and Kotka-Hamina port infrastructure. Geographic supply concentration centers on Norway, Finland, and Canada, with sulfuric acid recovery systems and bleached softwood pulp feedstocks serving as critical input dependencies. Single-source vulnerability runs through Borregaard's Sarpsborg complex for European pharmaceutical-grade output. Distribution feeds from integrated biorefinery platforms directly to converter qualification pipelines, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of integrated acid hydrolysis capacity with validated FDA bio-based packaging contact notifications constrains supply expansion faster than EU Green Deal compliance timelines accelerate demand pull. The capability gap sits with extraction specialists lacking grandfathered REACH polymer additive registration pathways.
For Market Incumbents: Entrench barrier coating qualification pipelines with German and Japanese converters by expanding pilot line partnerships ahead of 2030 renewable content mandates. Defend against enzymatic extraction entrants by accelerating toxicological dossier completion for food contact grades through leveraged ECHA grandfathered compliance pathways. Prioritize acid recovery capacity additions at existing Nordic facilities over greenfield expansion. For New Entrants and Emerging Players: Establish a beachhead in cosmetic-grade suspension supply to South Korean and Japanese formulators seeking biodegradability-certified alternatives to petrochemical thickeners. White-space availability concentrates in enzymatic hydrolysis routes for mid-scale packaging converters excluded from acid hydrolysis capital intensity thresholds. Go-to-market leverage rests on cellulase pretreatment technology licensing paired with regional pulp mill joint ventures. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors platform integrators with captive biorefinery feedstock and existing regulatory clearance portfolios. Long-term viability across the analysis window hinges on pharmacopeial validation completion and cross-jurisdictional ISO/TC 6 terminology standardization. Acquisition target archetype: enzymatic extraction specialists with validated cosmetic-grade output and regional pulp partnerships. Signal to watch: harmonized USP-EP monograph publication timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Acid hydrolysis scale-up at Nordic biorefineries tightens supply for EU Green Deal packaging converters. |
| Backward Integration | Pulp mill partnerships secure bleached softwood feedstock access for enzymatic extraction route commercialization. |
| Long-term Supply Agreement | Converter qualification pipelines with German dairy packaging firms de-risk revenue visibility. |
| Joint Venture | Regional cellulase technology licensing accelerates cosmetic-grade suspension market entry. |
| Green Certification Program | Biodegradability certification alignment with Japan METI procurement guidelines unlocks food service applications. |
Research Methodology
Initial hypotheses were tested against primary input from extraction plant managers, packaging converter procurement leads, cosmetic formulator R&D directors, and pharmaceutical excipient specialists and refined through secondary validation against ECHA REACH registration databases, FDA bio-based packaging contact notification filings, EU Green Deal directive texts, and Nordic pulp industry trade statistics. Bottom-up capacity modeling triangulated with top-down demand segmentation across application workflows.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product format, extraction technology, end-use industry, and regional regulatory cluster. CAGRs derived from installed capacity expansion timelines and converter qualification cycle compression. Industry-specific forecast inputs incorporated EU packaging waste directive compliance deadlines and Japan METI bioplastics procurement guideline implementation trajectories.
Stress conditions across sulfuric acid pricing volatility, pulp feedstock availability disruptions, and pharmacopeial validation timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory alignment between jurisdictions. Macroeconomic contraction, unilateral regulatory restriction, or breakthrough enzymatic extraction cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Single-Walled Carbon Nanotube (SWCNT) Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Nanochemicals Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Nanoparticle Analysis Market