
 Carbon Nanotubes (Cnts) Market | 2026-2036
Carbon Nanotubes (Cnts) Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Nanotubes (Cnts) Market Outlook
ISO/TS 80004-6 nanotube characterization standards is unwinding the supplier landscape, forcing producers to document aspect ratio distributions and metallic impurity thresholds. OCSiAl leverages its single-wall production scale to dominate high-purity dispersion supply for lithium-ion conductive additives. Jiangsu Cnano Technology Co., Ltd. anchors its position through backward integration into catalyst synthesis and continuous CVD reactor design. Nanocyl SA differentiates via specialty functionalized grades qualified for EMA-reviewed medical device applications.
Carbon nanotubes are hollow cylindrical carbon allotropes with diameters of 1–100 nanometers and aspect ratios exceeding 1000:1, produced through chemical vapor deposition, arc discharge, or laser ablation methods that control chirality and defect density for electrical or mechanical performance tuning. Their primary industrial purpose is to impart conductivity or tensile reinforcement at loadings below 5% by weight in otherwise insulating or brittle matrices. MWCNTs occupy the dominant volume position due to lower production cost and established qualification in automotive conductive plastics, while SWCNTs command premium positioning in transparent electrode films where percolation thresholds must minimize optical interference. Functionalized CNTs represent the fastest-growing product category as covalent surface modification enables stable dispersion in polar polymer systems and biocompatible solvents.
EPA oversight under the Toxic Substances Control Act governs pre-manufacture notification for novel CNT variants in the United States, while REACH registration dossiers in Europe mandate granular ecotoxicological data that smaller producers struggle to assemble. China's GB standards for nanomaterial labeling and the SAMR-administered national nano-product certification create a three-jurisdiction compliance burden for multinational suppliers. Stakeholders must monitor how evolving definitions of nanomaterial hazard classifications across these regimes reshape market access requirements and capital allocation priorities for new production capacity.
Market Dynamics
ISO/TS 80004-6 characterization mandates are compressing the supplier base by forcing documentation of aspect ratio distributions and metallic impurity thresholds, privileging producers with captive catalyst synthesis and continuous CVD reactor capabilities.
Growth Catalysts
- REACH purity benchmarks:Tightening ecotoxicological data requirements in Europe are disqualifying smaller producers and consolidating procurement among qualified suppliers with dossier-ready documentation.
- Battery anode demand:Lithium-ion conductive additive specifications are pulling high-purity MWCNT volumes into gigafactory supply chains serving electric vehicle production.
- Aerospace composite adoption:Structural weight reduction mandates from Boeing and Airbus procurement teams are qualifying CNT-reinforced prepreg for next-generation airframe programs.
Market Restraints
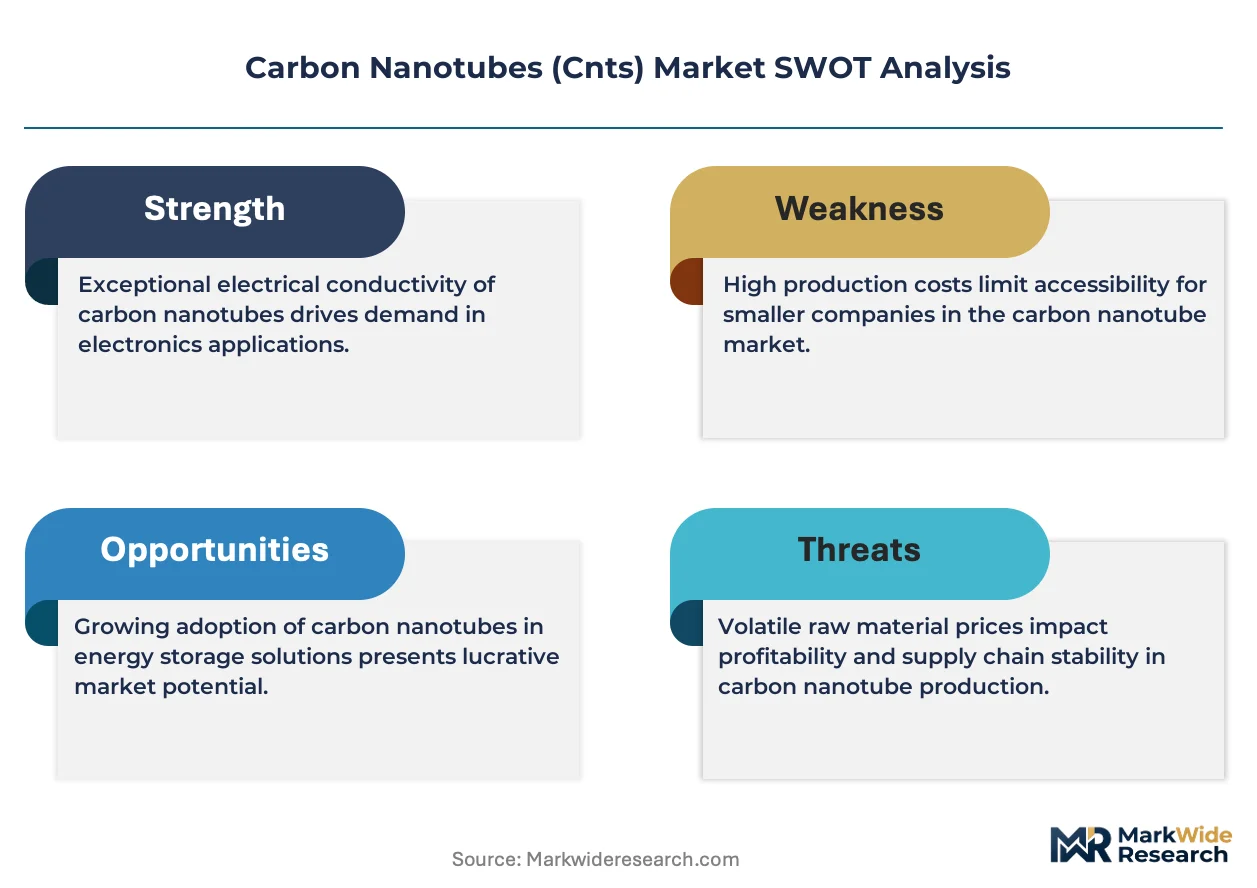
- Iron-based catalyst cost volatility:Ferrocene and nitrate precursor prices fluctuate with steel sector demand, squeezing margin structures for non-integrated CVD operators.
- China supply concentration:Jiangsu and Guangdong provinces host over seventy percent of global MWCNT capacity, creating single-geography disruption exposure for multinational buyers.
- Graphene substitution threat:Two-dimensional carbon allotropes achieve comparable percolation thresholds in conductive polymer applications at reduced loadings.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for advanced chemistry cell manufacturing create localized CNT qualification pathways for battery component suppliers.
- Medical device functionalization:EMA-reviewed surface chemistries enable biocompatible CNT dispersions for implantable sensor and drug delivery platforms.
- SAMR nano-certification:China's national nano-product certification framework rewards early registrants with preferential procurement status in state-backed battery and polymer projects.
Industry Challenges
- ISO/TS 80004-6 metrology talent scarcity:Qualified technicians for electron microscopy and Raman spectroscopy characterization command premium compensation, constraining quality control scaling.
- Continuous CVD reactor capex intensity:Fluidized bed systems with real-time chirality monitoring require capital deployment that mid-cap producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Nanotubes (Cnts) Market |
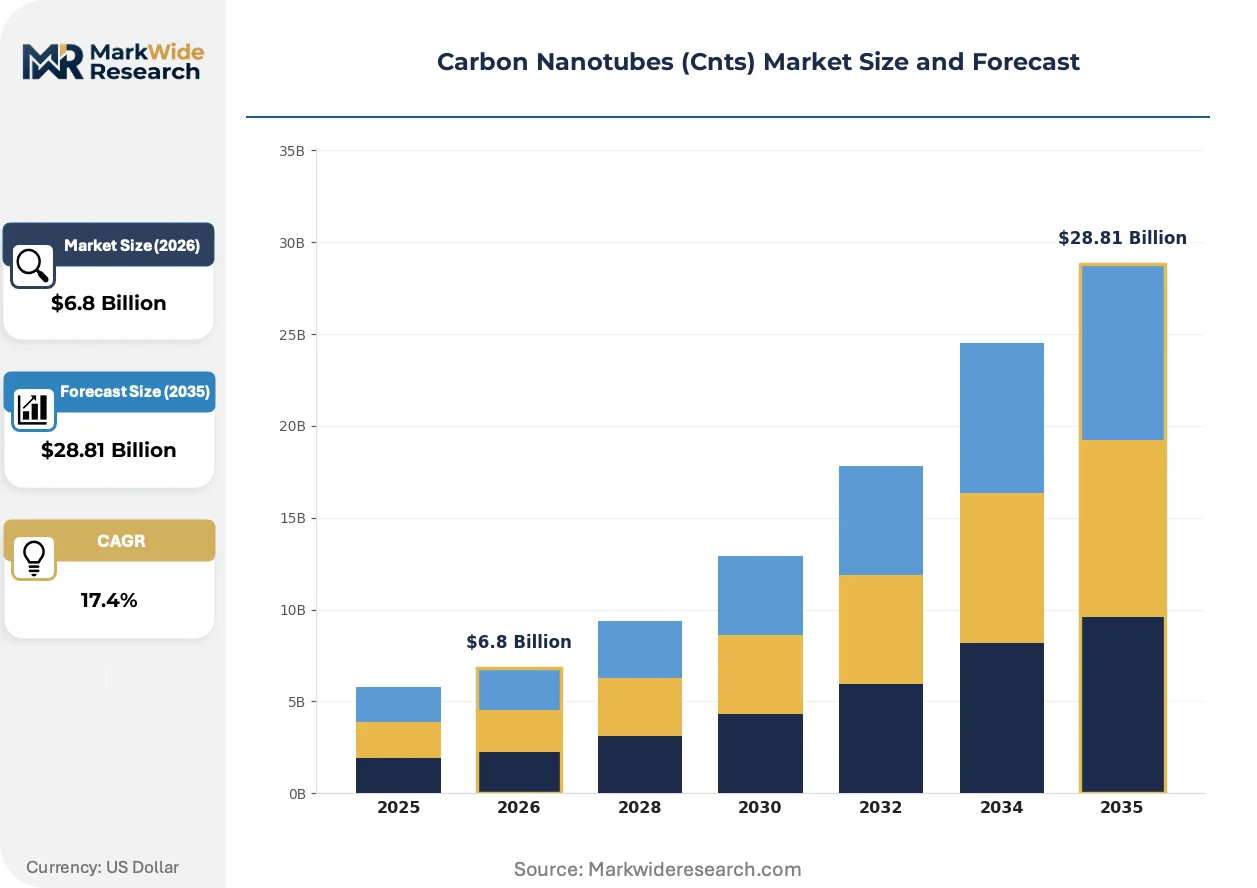
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MWCNTs, SWCNTs, Functionalized CNTs, Pseudo-CNTs End User: Electronics, Aerospace, Automotive Components, Cleantech Application: Composite Materials, Energy Storage, Conductive Coatings, Medical Devices Form: Powder, Dispersion, Film, Yarn |
| Companies Covered | LG Chem, Cabot Corporation, Nanocyl SA, Arkema, Resonac Corporation, OCSiAl, Showa Denko K.K., Chengdu Organic Chemicals Co. Ltd., Jiangsu Cnano Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Nanotubes (Cnts) Market Strategic Shifts
Process intensification and regulatory documentation automation are compressing development cycles while reconfiguring competitive advantage around metrology capabilities rather than reactor scale alone.
Continuous flow CVD reactor design is miniaturizing. Aerospace tier-one suppliers now specify aspect ratio distributions within narrow bands for structural prepreg qualification. This precision requirement is miniaturizing batch-to-batch variation tolerance and forcing producers to deploy in-line spectroscopic monitoring that was previously laboratory-confined.
REACH registration dossier automation tools are proliferating. ECHA's granular ecotoxicological data demands now absorb fifteen to twenty percent of smaller producers' operating budgets. Specialty functionalized grades for medical applications face the steepest documentation burden, driving consolidation toward producers with dedicated regulatory affairs teams.
Buyer concentration in battery supply chains is restructuring commercial terms. Korean and Chinese cathode manufacturers now mandate eighteen-month qualification timelines with locked pricing clauses. This contractual rigidity favors producers with backward integration into catalyst synthesis who can guarantee feedstock cost stability across contract durations.
Carbon Nanotubes (Cnts) Market Segmentation
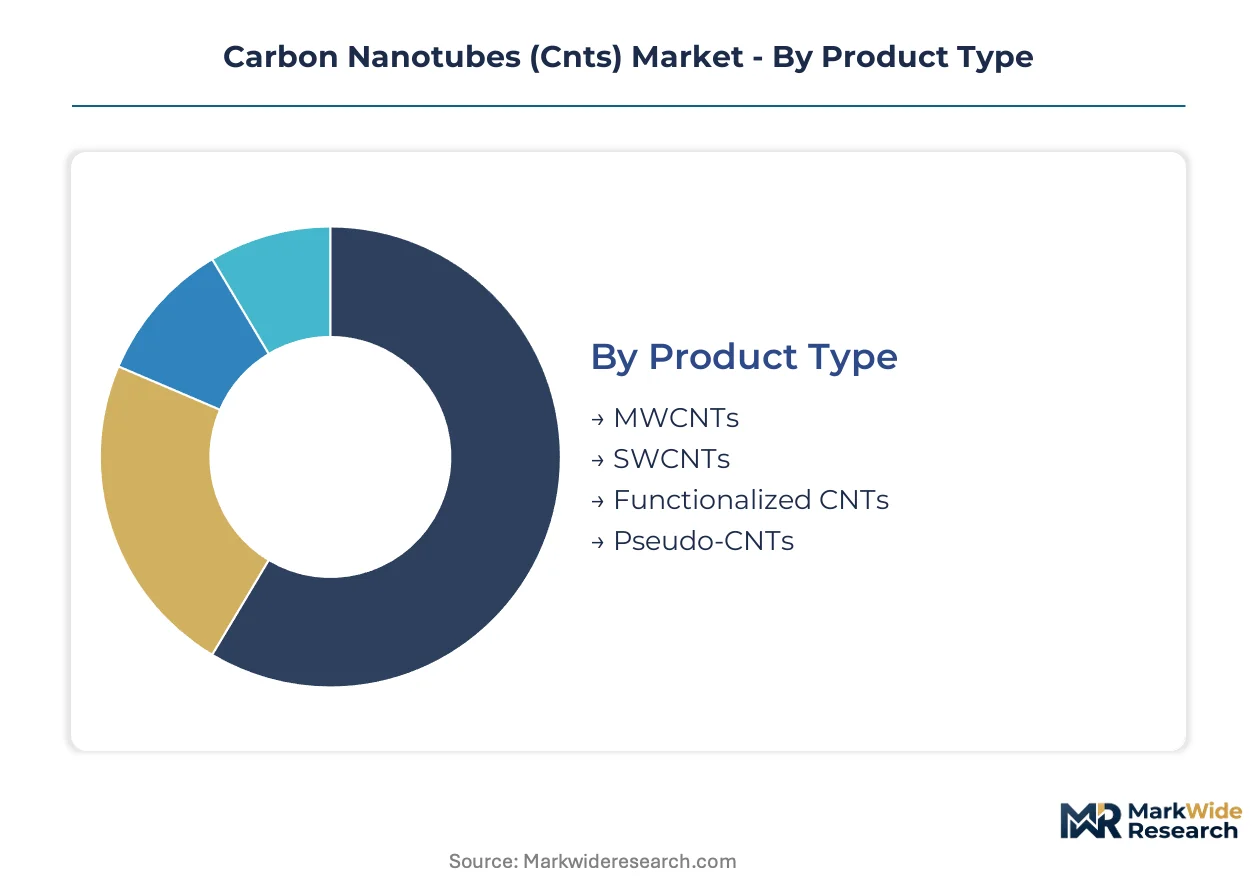
Carbon nanotube procurement splits across four critical dimensions. Product type determines purity thresholds and regulatory pathways. End-user concentration in battery and aerospace sectors reshapes volume allocation and qualification timelines.
Product Type:
REACH dossier requirements and EPA pre-manufacture notification thresholds differentiate compliance burdens across product categories, concentrating procurement among producers with characterization documentation capabilities.
- MWCNTs:Multi-walled architectures with diameters of 10–100 nanometers dominate conductive polymer and battery anode specifications. Korean cathode manufacturers and Chinese gigafactory supply chains pull the majority of industrial-grade volumes. Iron-based catalyst residues must meet tightening ECHA metallic impurity thresholds for European qualification.
- SWCNTs:Single-wall structures with semiconductor-grade chirality control command premium positioning in transparent electrode applications. Optical percolation thresholds below 0.1% loading enable touch panel and display film adoption. OCSiAl's captive production scale anchors high-purity dispersion supply for lithium-ion conductive additives.
- Functionalized CNTs:Covalent surface modification with carboxyl or amine groups enables stable aqueous dispersion.
- Pseudo-CNTs:Carbon nanofiber variants with sub-optimal aspect ratios serve cost-sensitive filler applications.
MWCNTs handle the majority of throughput; Functionalized CNTs is the fastest mover on share.
End User:
Customer concentration in electric vehicle supply chains and next-generation airframe programs is restructuring commercial terms toward long-term qualification contracts.
- Electronics:Transparent conductive film and thermal interface material specifications drive SWCNT and functionalized grade adoption. Display panel manufacturers in Taiwan and South Korea mandate ISO/TS 80004-6 aspect ratio documentation for supplier qualification.
- Aerospace:Boeing and Airbus structural weight reduction programs are qualifying CNT-reinforced prepreg for primary airframe applications. Prepreg specifications now require aspect ratio distributions within narrow bands, forcing producers to deploy in-line spectroscopic monitoring.
- Automotive Components:Conductive plastics for fuel system and body panel applications consume MWCNT volumes at 2–5% loadings.
- Cleantech:Wind turbine blade and solar cell electrode applications represent emerging demand pockets.
Electronics commands the largest procurement volumes; Aerospace is expanding most quickly on program qualification momentum.
Application:
Performance requirements in energy storage and implantable medical devices are splitting the market between commodity conductivity grades and specialty functionalized variants.
- Composite Materials:Structural reinforcement in thermoset and thermoplastic matrices requires surface-treated MWCNTs for interfacial adhesion. Automotive underhood components and sporting goods represent established demand baselines.
- Energy Storage:Silicon-anode conductive additives and cathode current collector coatings pull high-purity MWCNT dispersions. Eighteen-month qualification timelines with locked pricing clauses favor producers with backward integration into catalyst synthesis.
- Conductive Coatings:Anti-static and EMI shielding films for electronics packaging utilize lower-cost MWCNT powder grades.
- Medical Devices:EMA-reviewed surface chemistries enable biocompatible CNT dispersions for implantable sensors and targeted drug delivery platforms.
Composite Materials anchors current volume; Medical Devices is gaining share fastest on regulatory approval pathways.
Form:
Downstream processing economics and dispersion stability requirements determine form factor selection across customer segments.
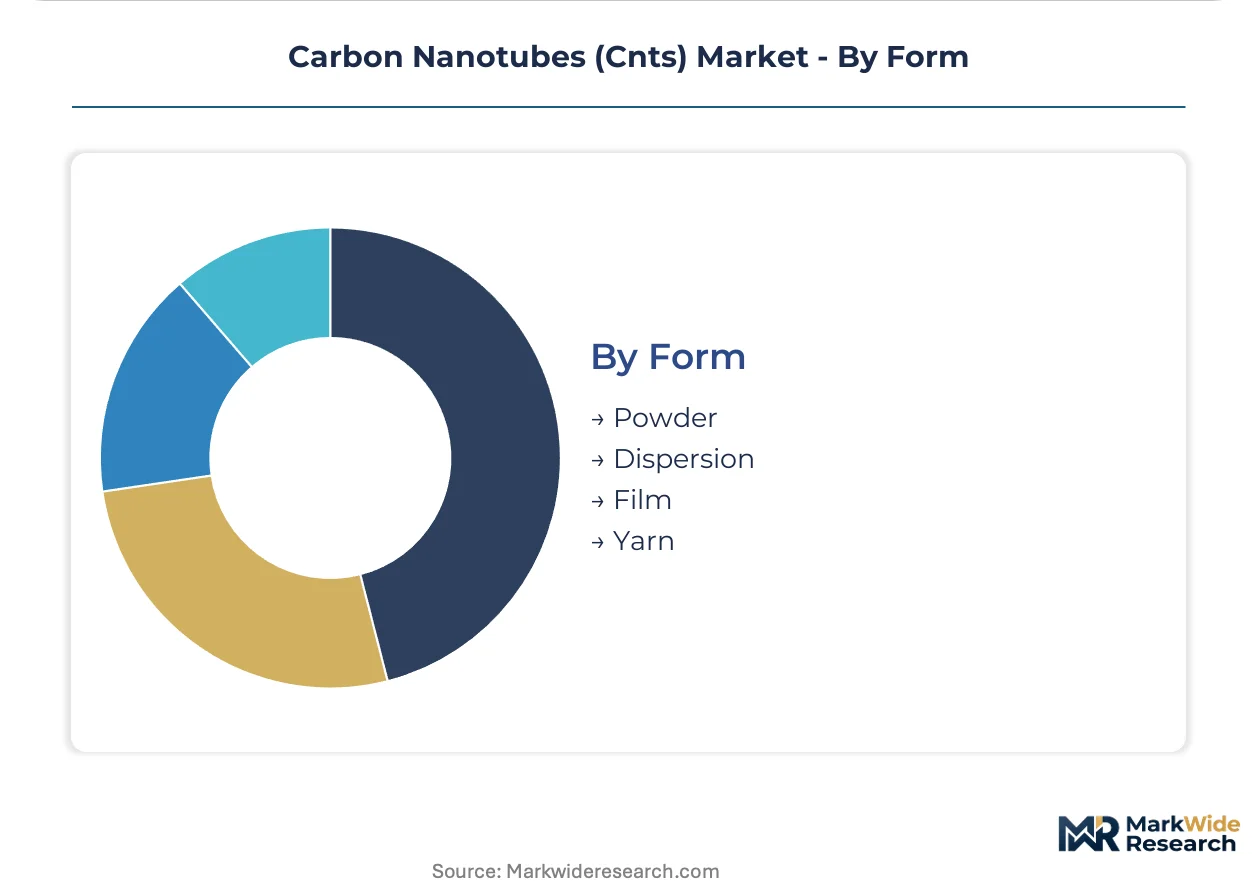
- Powder:Dry bulk material serves masterbatch compounding and cement reinforcement applications where on-site dispersion equipment is available.
- Dispersion:Pre-dispersed aqueous or solvent-based suspensions eliminate agglomeration risks in battery electrode coating and inkjet printing processes.
- Film:Cast or deposited conductive layers for transparent electrode and heater applications.
- Yarn:Continuous fiber assemblies for structural cable and textile integration.
Dispersion captures the dominant value-add position; Film is climbing the fastest on display panel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle battery manufacturers and aerospace tier-one suppliers concentrate procurement decisions across four geographic clusters. Each jurisdiction imposes distinct purity documentation requirements that reshape supplier qualification pathways.
China
Jiangsu and Guangdong provinces host over seventy percent of global MWCNT capacity, serving domestic gigafactory supply chains for battery anode conductive additives. SAMR-administered national nano-product certification creates preferential procurement status for early registrants in state-backed polymer projects. Suzhou-based producers anchor backward integration into catalyst synthesis, guaranteeing feedstock cost stability across eighteen-month contract durations.
United States
Boeing and Airbus structural weight reduction programs are qualifying CNT-reinforced prepreg for next-generation airframe applications. EPA oversight under the Toxic Substances Control Act governs pre-manufacture notification for novel CNT variants. Massachusetts and California research clusters concentrate transparent electrode film development for display panel manufacturers.
Germany
Automotive conductive plastics for fuel system components pull industrial-grade MWCNT volumes from qualified suppliers. REACH registration dossiers mandate granular ecotoxicological data that smaller producers struggle to assemble. Bavaria-based chemical processors specialize in functionalized grades for EMA-reviewed medical device applications.
South Korea
Cathode manufacturers mandate locked pricing clauses across extended qualification timelines. MFDS pharmaceutical regulations intersect with battery material standards for implantable sensor applications. Seoul-Incheon industrial corridor hosts dispersion facilities serving lithium-ion conductive additive specifications.
India
Production-linked incentives for advanced chemistry cell manufacturing create localized CNT qualification pathways for battery component suppliers. BIS nanomaterial labeling standards impose documentation burdens comparable to REACH tier-one requirements. Gujarat and Maharashtra industrial zones attract catalyst synthesis investments from multinational producers.
Carbon Nanotubes (Cnts) Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive catalyst production and continuous CVD reactor capabilities. Tier-one suppliers with backward integration into ferrocene precursor synthesis command procurement preference from Korean and Chinese battery manufacturers. Two strategic archetypes dominate: scale-driven dispersion specialists and functionalization-focused medical-grade purveyors. Competitive intensity centers on capacity expansion in Jiangsu province and strategic partnerships with aerospace tier-one suppliers for prepreg qualification programs.
Within the integrated chemical conglomerate tier, LG Chem and Showa Denko K.K. exemplify producers with diversified material portfolios spanning battery additives and structural composites. Jiangsu Cnano Technology Co., Ltd. anchors Chinese domestic supply through its Zhenjiang-based operations. OCSiAl occupies a distinctive position in single-wall production scale for high-purity dispersion supply. Cabot Corporation represents North American incumbents with carbon black heritage extending into nanotube conductive additives.
| Leading Market Players |
|---|
| LG Chem |
| Cabot Corporation |
| Nanocyl SA |
| Arkema |
| Resonac Corporation |
| OCSiAl |
| Showa Denko K.K. |
| Chengdu Organic Chemicals Co. Ltd. |
| Jiangsu Cnano Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month qualification timelines with locked pricing clauses concentrate procurement leverage among Korean cathode manufacturers and Chinese gigafactory operators, compressing margin buffers for non-integrated producers while rewarding those with captive catalyst synthesis. This contractual rigidity amplifies pricing power differentials between backward-integrated suppliers and merchant market participants.
Pricing Analysis
Cost-plus contracts indexed to ferrocene precursor pricing dominate battery supply chain procurement, with Korean and Chinese cathode manufacturers mandating locked eighteen-month pricing clauses. Price differentiation separates ECHA-qualified grades from industrial-tier MWCNTs, with REACH dossier-ready producers commanding premiums. Cost compression in commodity conductive polymer grades intensifies as Jiangsu capacity expansion outpaces specification tightening. Battery anode additive specifications show least price sensitivity due to qualification switching costs, while automotive conductive plastics buyers exhibit highest sensitivity to per-kilogram differentials.
Supply Chain Analysis
China anchors global MWCNT production with Jiangsu and Guangdong provinces hosting over seventy percent of installed capacity, serving domestic gigafactory supply chains and export markets. Production draws from iron-based catalyst precursors, hydrogen feedstock, and specialized CVD reactor components, with ferrocene pricing tethered to steel sector demand cycles. Single-geography concentration creates disruption exposure from SAMR regulatory shifts or provincial energy rationing. Distribution runs through qualified dispersion facilities in Seoul-Incheon, Zhenjiang, and Bavaria before downstream integration into battery electrode coating and polymer masterbatch operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware as regulatory documentation and dispersion formulation support capture recurring revenue streams from qualification maintenance and custom surface chemistry development.
For Market Incumbents: Secure EMA-reviewed functionalization capabilities before graphene substitution accelerates in transparent electrode applications. Defend margin position by adding captive ferrocene synthesis capacity in Zhenjiang or Gujarat to neutralize catalyst cost volatility. Lock aerospace tier-one prepreg qualification through in-line spectroscopic monitoring investments that meet Boeing and Airbus aspect ratio distribution bands. For New Entrants and Emerging Players: Differentiate on SAMR nano-certification speed to capture preferential procurement status in state-backed battery projects. Target India's PLI-aligned advanced chemistry cell manufacturing corridor where localized qualification pathways remain underdeveloped. Lead with dispersion formulation services rather than commodity powder supply to bypass CVD reactor capex barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to monetize non-core nanomaterial assets with stranded REACH dossier investments. Five-to-ten year viability hinges on regulatory documentation automation capabilities and continuous CVD reactor deployment. Monitor ECHA metallic impurity threshold tightening as the signal indicating consolidation acceleration among dossier-deficient producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Synthesis | Ferrocene precursor captive supply neutralizes steel sector demand volatility for CVD operators. |
| Continuous CVD Reactor Deployment | Fluidized bed systems with real-time chirality monitoring reduce batch-to-batch variation for aerospace qualification. |
| REACH Dossier Automation Investment | Automated ecotoxicological data assembly absorbs fifteen to twenty percent cost burden from smaller competitors. |
| Medical Device Functionalization Partnership | EMA-reviewed surface chemistries open implantable sensor and drug delivery platform revenue streams. |
| India PLI Scheme Alignment | Localized qualification pathways for advanced chemistry cell manufacturing capture subsidy-linked procurement preference. |
Study Parameters
Desk research of customs trade data, SEC chemical sector filings, and SAMR nano-product certification registries preceded structured interviews with CVD plant managers, Korean cathode manufacturer procurement leads, aerospace tier-one composite engineers, and ECHA regulatory affairs specialists. Primary fieldwork captured qualification timeline dynamics, catalyst cost pass-through mechanisms, and dispersion formulation technical requirements. Secondary validation drew from ACC industrial chemical reports, IEA clean technology deployment databases, and ISO/TS 80004-6 characterization protocol documentation. Bottom-up capacity installations and top-down end-use demand estimates were triangulated against trade flow observations.
Variance decomposition across product type, end-user concentration, application performance requirements, and form factor processing economics structured the analytical framework throughout the forecast period. CAGRs were derived from segment-level volume trajectories weighted by purity-adjusted pricing tiers. Industry-specific forecast inputs incorporated silicon-anode conductive additive penetration rates and aerospace prepreg qualification program milestones without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle production scaling or REACH metallic impurity threshold tightening trajectories would require recalibration. Forecasts reflect documented assumptions regarding catalyst precursor cost stability and SAMR certification timeline adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Single-Walled Carbon Nanotube (SWCNT) Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Nanoparticle Contract Manufacturing Market