
 N-Hexane Market | 2026-2036
N-Hexane Market Size, Share, and Industry Trends Forecast 2026-2036
N-Hexane Market Intelligence
Pharmaceutical manufacturing is restructuring its solvent procurement priorities as N-hexane demand shifts toward higher-purity grades for active pharmaceutical ingredient synthesis. Exxon Mobil Corporation leverages its integrated refinery network to sustain cost-competitive feedstock access across North American chemical corridors. Shell plc anchors European supply through its Rotterdam aromatics complex, while Sinopec dominates domestic distribution channels within China's coastal chemical clusters.
N-hexane is a straight-chain aliphatic hydrocarbon with six carbon atoms, boiling point approximately 69°C, produced primarily through crude oil fractionation and subsequent catalytic reforming or molecular sieve separation. Its primary commercial purpose centers on non-polar solvent applications, particularly vegetable oil extraction where it dissolves triglycerides with minimal residual carryover. Industrial grade material occupies the highest volume tier due to bulk edible oil processing requirements, whereas pharmaceutical grade commands concentrated margin pools from stringent residual specification limits. Solvent extraction leads application share through soybean and palm oil refining scale, while chemical synthesis represents the fastest-growing application segment as specialty chemical manufacturers adopt N-hexane for Grignard reaction media and polymerization processes.
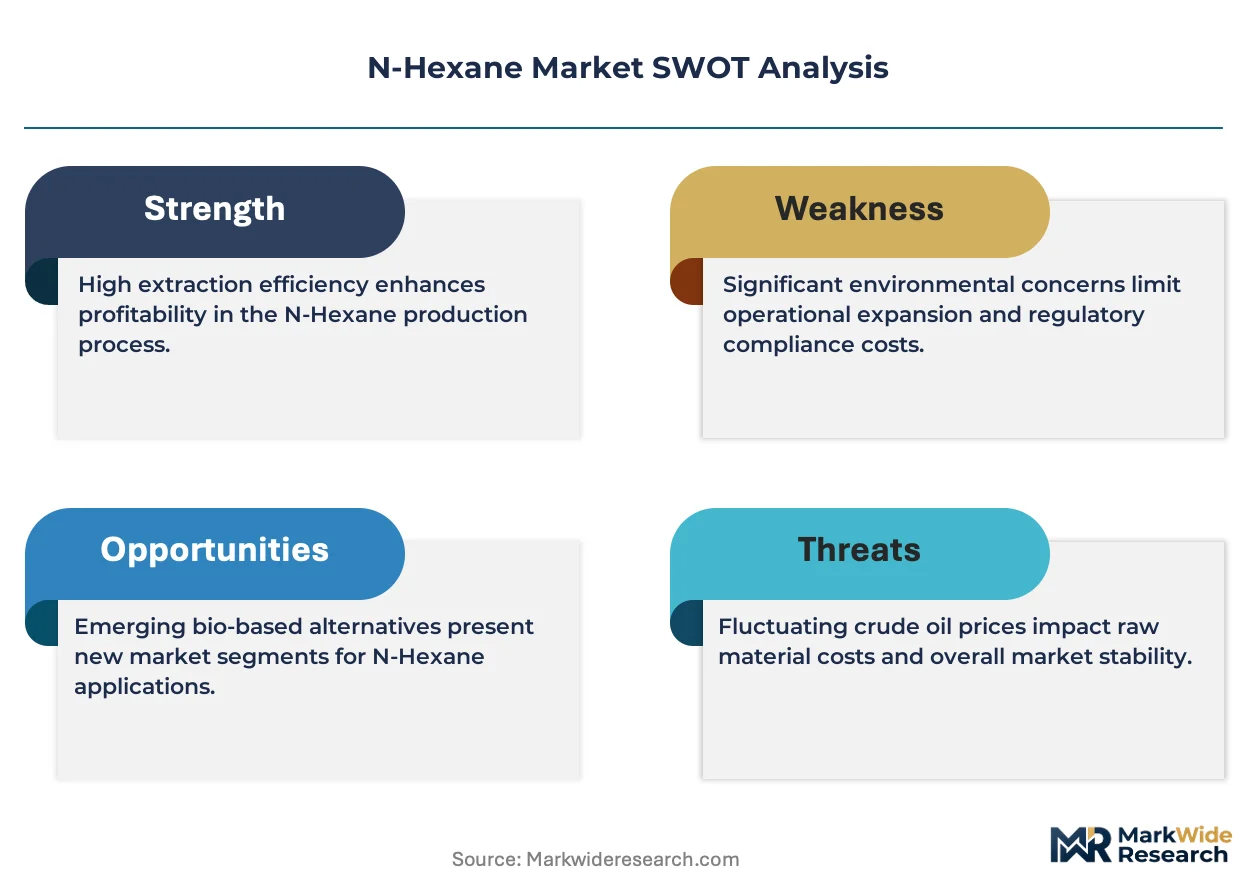
OSHA enforces permissible exposure limits of 500 ppm over eight-hour time-weighted averages, compelling manufacturers to invest in closed-loop handling systems and vapor recovery infrastructure. REACH classification under Annex XVII restrictions shapes European market access through mandatory registration and hazard communication protocols. EPA New Source Performance Standards further govern air emissions from storage and transfer operations. Stakeholders must monitor evolving bio-based hexane alternatives and regional purity standard divergence when allocating capital across grade-specific production assets.
Market Dynamics
Edible oil processors in China and India are driving capacity expansions that pull N-hexane volumes toward Asia-Pacific coastal chemical clusters, while REACH and OSHA tighten purity specifications that fragment grade requirements across regional supply chains.
Growth Catalysts
- Solvent extraction yield efficiency:Soybean and palm oil refiners deploy N-hexane to maximize triglyceride recovery rates with minimal residual carryover, sustaining volume pull from bulk processing facilities.
- REACH Annex XVII registration protocols:European hazard communication mandates elevate pharmaceutical-grade specifications, creating premium tier demand from active pharmaceutical ingredient manufacturers seeking compliance-certain supply.
- China's coastal chemical cluster concentration:Sinopec's integrated refinery-aromatics networks in Shanghai and Ningbo reduce feedstock transit costs for domestic edible oil processors scaling extraction capacity.
Market Restraints
- Crude oil feedstock volatility:N-hexane production costs track naphtha cracking margins, exposing processors to petrochemical price swings without hedge mechanisms.
- OSHA permissible exposure limits:The 500 ppm eight-hour time-weighted average compels capital deployment into closed-loop handling and vapor recovery infrastructure, elevating facility compliance burdens.
- Bio-based hexane substitution:Agricultural-derived hexane alternatives from corn stover and sugarcane bagasse gain traction in European food-grade applications, threatening petrochemical solvent share.
Strategic Opportunities
- Grignard reaction media adoption:Specialty chemical manufacturers in Germany and Switzerland integrate N-hexane into pharmaceutical intermediate synthesis, opening high-margin application channels beyond edible oil extraction.
- India's PLI scheme for food processing:Production-linked incentives for edible oil refining capacity create demand pull from Gujarat and Maharashtra processing zones seeking solvent supply security.
- Pharmaceutical-grade certification expansion:Residual specification limits below 50 ppm enable premium pricing capture from FDA-regulated active pharmaceutical ingredient facilities in New Jersey and Puerto Rico.
Industry Challenges
- Catalytic reforming catalyst regeneration cycles:Molecular sieve separation units require scheduled downtime that disrupts just-in-time delivery commitments to edible oil processors operating continuous extraction lines.
- Cross-border harmonization of purity standards:Divergent residual limits between EPA New Source Performance Standards and ECHA REACH classifications complicate multi-destination export logistics for merchant producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Hexane Market |
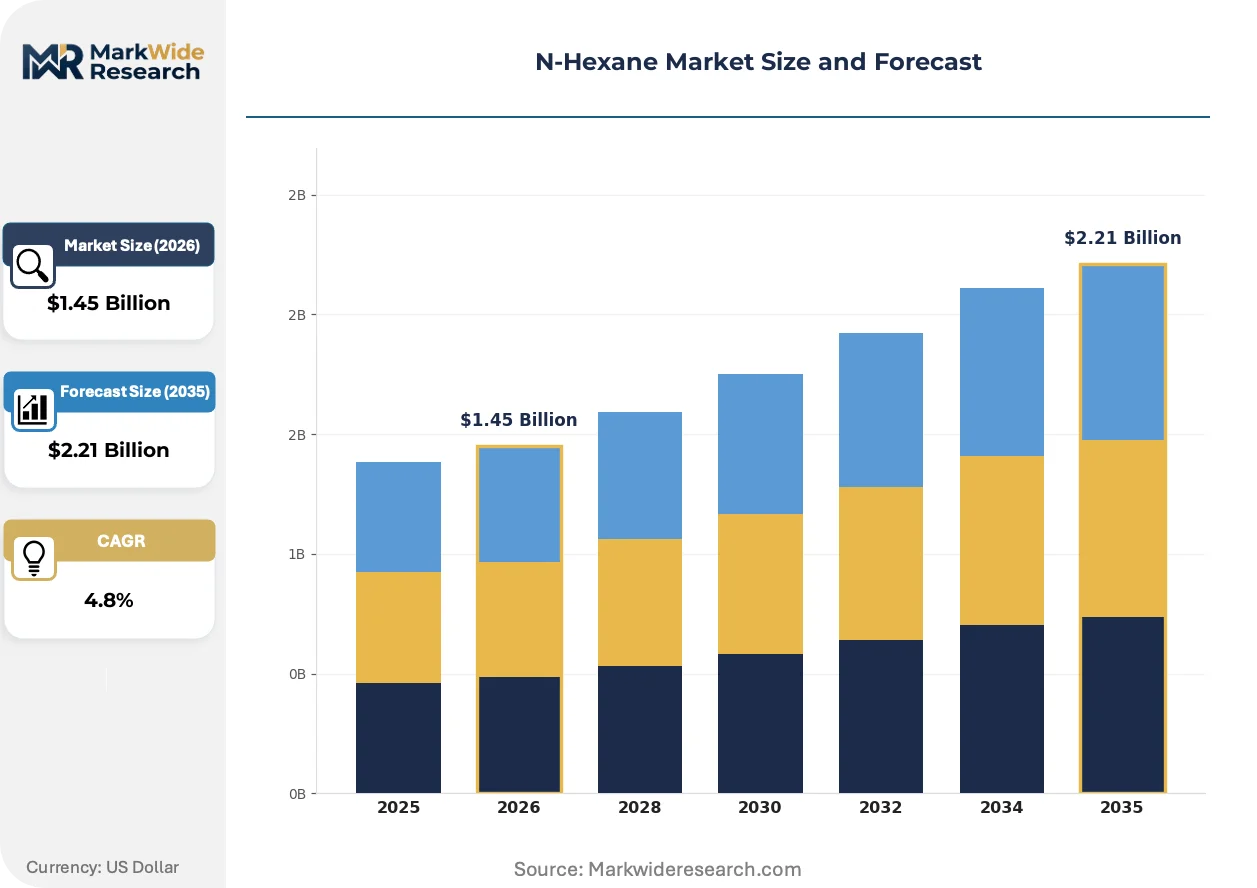
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Laboratory Grade Application: Solvent Extraction, Adhesives, Coatings, Chemical Synthesis End User: Pharmaceuticals, Chemicals, Food & Beverages, Agriculture Packaging Type: Barrels, Drums, IBC Totes, Canisters |
| Companies Covered | Junyuan Petroleum Group, Hindustan Petroleum Corporation Limited, Exxon Mobil Corporation, Phillips 66 Company, Bharat Petroleum Corporation Limited, Shell plc, GFS Chemicals, Sumitomo Chemical Co., Ltd., China Petrochemical Corporation (Sinopec), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Hexane Market Strategic Shifts & Innovations
Process intensification technologies and regulatory chemistry are restructuring how N-hexane is produced, purified, and deployed across extraction and synthesis applications, with digitization penetrating solvent handling systems.
Membrane separation technology is converging with traditional fractional distillation to reduce energy intensity in pharmaceutical-grade N-hexane production. German specialty chemical manufacturers are piloting hybrid purification trains that cut solvent recovery costs by one-third. This convergence is compressing the cost gap between industrial and pharmaceutical grades, enabling margin expansion for integrated refiners.
EPA New Source Performance Standards for air emissions from storage and transfer operations are tightening vapor recovery mandates across US Gulf Coast chemical corridors. Refiners must retrofit floating roof tanks with secondary seal systems or face permit non-compliance. The pharmaceutical extraction segment bears the highest retrofit burden due to stringent residual volatility specifications.
Consolidated procurement contracts are displacing spot-market purchasing among multinational edible oil processors. Cargill and Bunge are negotiating three-year solvent supply agreements with fixed-price escalators tied to naphtha indices. This shift is most visible in Brazil and Argentina, where soybean crushing capacity concentration gives processors leverage over merchant N-hexane suppliers.
N-Hexane Market Segmentation
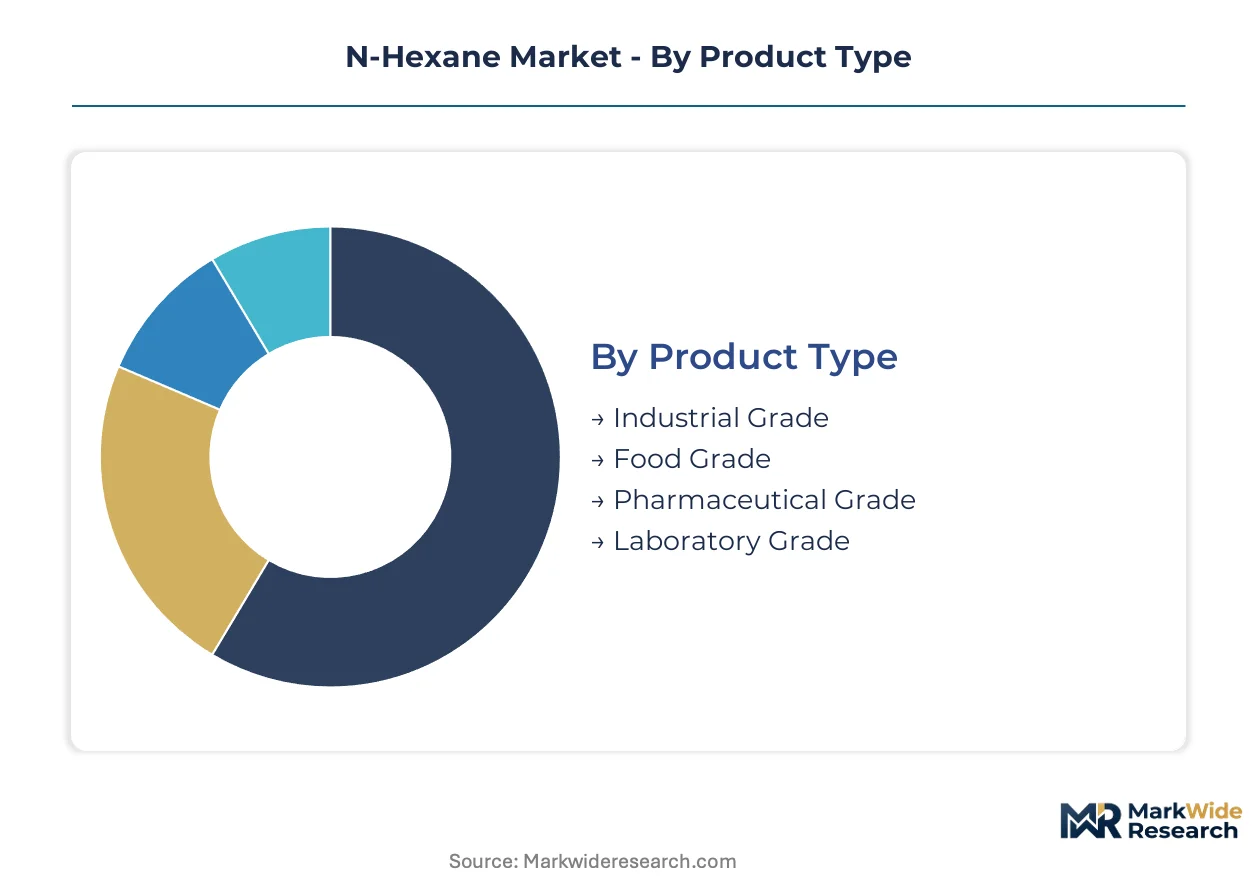
N-hexane procurement patterns diverge sharply across purity tiers and handling formats, with pharmaceutical-grade specifications commanding capital-intensive purification infrastructure while bulk industrial volumes flow through standardized logistics networks. Refiners and distributors must align asset deployment with these structural divides to capture margin where specification premiums justify equipment outlays.
Product Type:
Capital intensity escalates steeply with purity requirements, as molecular sieve separation and catalytic reforming infrastructure must scale to meet residual specification limits.
- Industrial Grade:Standard fractional distillation from naphtha cracking yields material with 95-99% hexane isomer concentration. Soybean processors in China and India absorb the largest volumes, driven by continuous extraction line throughput requirements and minimal residual carryover tolerance.
- Pharmaceutical Grade:Hybrid membrane-distillation trains achieve residual impurities below 50 ppm to satisfy FDA and EMA active pharmaceutical ingredient manufacturing protocols. German and Swiss specialty chemical manufacturers are the primary demand anchors, with Grignard reaction media applications expanding fastest.
- Food Grade:Intermediate purification meets FSSAI and FDA edible oil extraction standards without pharmaceutical-tier equipment investment.
- Laboratory Grade:Small-batch fractional distillation serves analytical chromatography and research synthesis with stringent lot-to-lot consistency requirements.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Pharmaceutical Grade.
Application:
Volume concentration and margin structure pull in opposite directions, with bulk extraction operations generating throughput while synthesis applications yield specification premiums.
- Solvent Extraction:Non-polar triglyceride dissolution dominates vegetable oil refining, particularly soybean and palm oil processing where hexane's 69°C boiling point enables efficient recovery cycling. Cargill and Bunge procurement consolidation in Brazil and Argentina is shifting contract structures toward multi-year supply agreements.
- Chemical Synthesis:Grignard reaction media and polymerization processes demand higher-purity feedstock with controlled moisture content. Specialty manufacturers in Germany and Switzerland are integrating n-hexane into pharmaceutical intermediate production, opening the highest-margin application channel.
- Adhesives:Solvent-borne formulation component for pressure-sensitive and hot-melt adhesive systems in packaging and construction.
- Coatings:Thinning agent for industrial paints and varnishes where evaporation rate control affects film formation quality.
Solvent Extraction retains the largest volume footprint. Chemical Synthesis is climbing the fastest.
End User:
Regulatory exposure varies dramatically across customer categories, with pharmaceutical and food processors facing the most stringent inspection and documentation burdens.
- Food & Beverages:Edible oil refiners in China and India drive absolute demand, with coastal chemical cluster concentration reducing inbound logistics costs. India's PLI scheme for food processing is accelerating capacity additions in Gujarat and Maharashtra.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers in New Jersey and Puerto Rico require certified supply chains with batch traceability and residual volatility documentation. REACH Annex XVII registration protocols in Europe are elevating compliance-certain supply premiums.
- Chemicals:Intermediate producers and specialty formulation houses across the US Gulf Coast and Rotterdam aromatics corridors.
- Agriculture:Pesticide and agrochemical formulation applications with seasonal demand concentration tied to planting cycles.
Food & Beverages commands the dominant demand share. Pharmaceuticals is gaining share fastest.
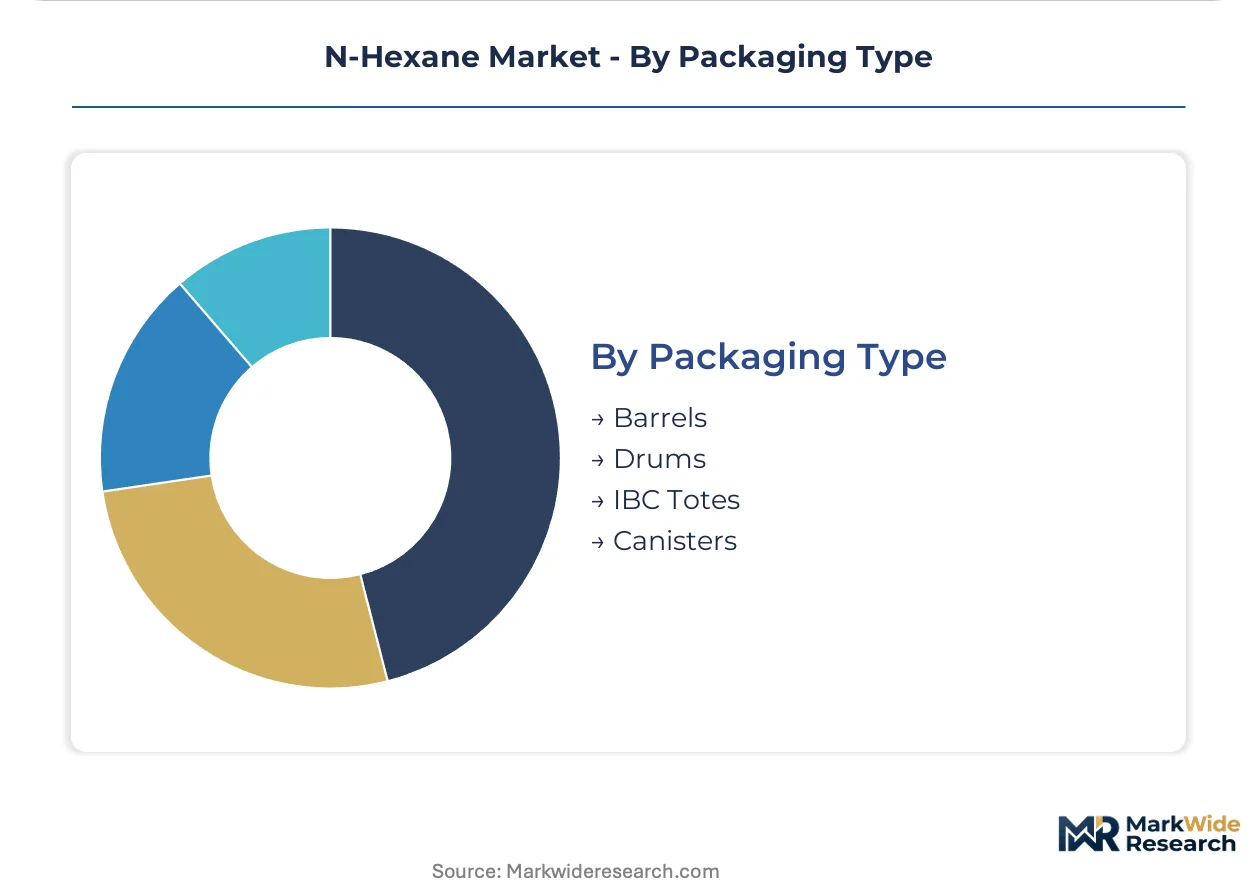
Packaging Type:
Handling infrastructure investment scales with container standardization, as bulk formats reduce per-unit logistics costs while specialized canisters serve laboratory and pharmaceutical customers.
- Drums:200-liter steel drums remain the workhorse format for mid-scale edible oil processors and chemical manufacturers, balancing handling efficiency with inventory flexibility. OSHA 500 ppm exposure limits are driving closed-loop pumping system retrofits at drum discharge stations.
- IBC Totes:Intermediate bulk containers consolidate 1000-liter volumes for large refiners with continuous extraction operations, minimizing container handling labor and vapor emission points.
- Barrels:Traditional 55-gallon format serving smaller processors with limited storage infrastructure.
- Canisters:Sealed aluminum containers for laboratory and pharmaceutical-grade material requiring inert atmosphere preservation.
Most throughput moves through Drums. IBC Totes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal chemical clusters concentrate the dominant N-hexane production capacity, pulling regional supply chains toward Asia-Pacific refining corridors as edible oil processors scale extraction infrastructure.
China
Sinopec's integrated refinery-aromatics networks in Shanghai and Ningbo supply soybean and palm oil processors with cost-competitive feedstock. GB standards and MEE air quality protocols enforce vapor recovery mandates at storage facilities. The Yangtze River Delta chemical corridor anchors domestic distribution channels for coastal edible oil refiners.
India
Gujarat and Maharashtra processing zones drive solvent demand from soybean and cottonseed oil refiners expanding capacity under the PLI scheme for food processing. FSSAI purity specifications govern food-grade hexane imports and domestic production. The Gujarat Chemical Port cluster reduces inbound logistics costs for bulk solvent consumers.
United States
EPA New Source Performance Standards and OSHA 500 ppm exposure limits compel Gulf Coast refiners to deploy closed-loop handling systems at storage terminals. The Texas-Louisiana petrochemical corridor sustains merchant supply to domestic edible oil processors and pharmaceutical API manufacturers in New Jersey.
Germany
REACH Annex XVII registration protocols elevate pharmaceutical-grade specifications for active pharmaceutical ingredient manufacturers in Basel-proximate zones. ECHA hazard communication mandates shape import documentation requirements. The Ludwigshafen chemical complex anchors solvent supply to specialty chemical manufacturers integrating hexane into Grignard reaction media.
Brazil
Soybean crushing capacity concentration in Mato Grosso and Paraná gives processors procurement leverage over solvent suppliers. ANVISA food-grade standards align with FDA residual specifications for export-oriented refiners. The Santos port corridor channels N-hexane imports to interior processing zones.
N-Hexane Market Key Industry Players
Capacity expansion dominates the current landscape as integrated refiners extend molecular sieve separation units to capture pharmaceutical-grade premiums. The market structure consolidates around petrochemical majors with captive naphtha feedstock access, tiered between global integrated players, regional state-owned enterprises, and specialty chemical distributors. Three archetypes prevail: refinery-integrated suppliers with backward control over cracking units, merchant distributors serving fragmented edible oil processors, and pharmaceutical-grade certifiers with hybrid purification infrastructure. Geographic expansion and portfolio diversification toward higher-purity grades constitute the dominant competitive moves.
Within the refinery-integrated tier, Exxon Mobil Corporation and Shell plc exemplify scale-driven positioning through coastal petrochemical corridor concentration. Sinopec occupies a distinct archetype as a state-coordinated supplier anchoring domestic distribution networks. Among Asia-Pacific-based operators, Sumitomo Chemical Co., Ltd. and Junyuan Petroleum Group represent regional specialization patterns. Hindustan Petroleum Corporation Limited and Bharat Petroleum Corporation Limited sit within the Indian public-sector cluster serving domestic edible oil processors. Phillips 66 Company and GFS Chemicals illustrate North American merchant and specialty-grade positioning respectively.
| Leading Market Players |
|---|
| Junyuan Petroleum Group |
| Hindustan Petroleum Corporation Limited |
| Exxon Mobil Corporation |
| Phillips 66 Company |
| Bharat Petroleum Corporation Limited |
| Shell plc |
| GFS Chemicals |
| Sumitomo Chemical Co., Ltd. |
| China Petrochemical Corporation (Sinopec) |
| Others |
Cost & Logistics Intelligence
Captive naphtha cracking integration anchors both supply security and pricing power for N-hexane producers, as integrated refiners control feedstock costs while merchant producers absorb volatile naphtha margin swings. Sinopec's refinery-aromatics networks in Shanghai and Ningbo demonstrate how backward integration into crude fractionation insulates domestic Chinese suppliers from spot market turbulence.
Pricing Analysis
Naphtha cracking margins transmit directly into N-hexane production economics, with contract-based long-term offtake agreements dominating procurement between edible oil processors and integrated refiners. Price differentiation rests on purity grade certification and volume scale, where pharmaceutical-grade material commands substantial premiums over industrial-grade bulk volumes. Pricing pressure stems from bio-based hexane substitution in European food-grade applications, compressing margins for petrochemical-derived solvent. Edible oil refiners in Brazil and Argentina exhibit highest price sensitivity through consolidated procurement leverage, while pharmaceutical API manufacturers in New Jersey and Puerto Rico demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements from FDA-regulated pharmaceutical manufacturers and FSSAI-compliant food processors mandate multi-supplier qualification across China, India, and the United States. Feedstock dependencies center on naphtha from catalytic reforming units, molecular sieve separation catalysts, and vapor recovery infrastructure components. Single-source vulnerability concentrates around Sinopec's coastal chemical clusters, where disruption would cascade through Asia-Pacific edible oil processing. Distribution runs through refinery-integrated terminals, merchant chemical distributors, and direct railcar delivery to continuous extraction facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
N-hexane operates as a regulatory compounder where REACH Annex XVII registration protocols and OSHA exposure limit enforcement continuously elevate purity specifications and compliance documentation burdens, structurally favoring suppliers with certification infrastructure.
For Market Incumbents: Acquire hybrid membrane-distillation purification assets to capture pharmaceutical-grade margin premiums as REACH and FDA specifications tighten. Expand capacity in Gujarat and Maharashtra processing zones under India's PLI scheme for food processing to secure volume anchors against bio-based hexane substitution threats. Strengthen backward integration into naphtha cracking to defend feedstock cost position. For New Entrants and Emerging Players: Begin with pharmaceutical-grade certification for Grignard reaction media applications in Germany and Switzerland, where specialty chemical manufacturers seek compliant supply with residual specifications below 50 ppm. Target laboratory-grade distribution through sealed canister formats for analytical chromatography customers, leveraging lower capital barriers than industrial-scale purification infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for regional pharmaceutical-grade certifiers because fragmented merchant distributors lack hybrid purification infrastructure and FDA batch traceability capabilities. Five-to-ten year viability hinges on regulatory divergence between EPA New Source Performance Standards and ECHA REACH classifications. Watch for bio-based hexane cost parity achievement as the inflection signal for petrochemical solvent displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | Sinopec and Exxon Mobil secure captive feedstock access across Shanghai and Texas-Louisiana corridors. |
| Pharmaceutical-Grade Certification Expansion | Hybrid membrane-distillation trains enable 50 ppm residual compliance for FDA-regulated API facilities. |
| Long-term Supply Agreement Consolidation | Cargill and Bunge negotiate fixed-price escalators tied to naphtha indices in Brazil and Argentina. |
| Vapor Recovery Infrastructure Retrofit | OSHA 500 ppm mandates compel floating roof tank secondary seal deployment at Gulf Coast terminals. |
| Joint Venture in Coastal Chemical Clusters | Sinopec's Rotterdam and Ningbo partnerships reduce logistics costs for edible oil processors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, edible oil procurement leads, pharmaceutical regulatory affairs directors, and specialty chemical R&D heads with secondary validation from customs trade data, ACC and Cefic industry reports, EPA New Source Performance Standards filings, and SEC 10-K disclosures from integrated petrochemical majors. Bottom-up volume modeling across grade tiers and applications triangulated against top-down naphtha cracking capacity assessments.
Historical reference periods anchored the projection horizon to observed naphtha margin cycles, regulatory implementation timelines, and edible oil processing capacity buildouts. Segmentation dimensions modeled include purity grade tier, end-use industry vertical, packaging format standardization, and regional production hub concentration. CAGRs derived from regression analysis against naphtha price indices, soybean crushing capacity expansion rates, and pharmaceutical intermediate synthesis growth patterns.
Several conditions sit outside the modeled scope, including unannounced bio-based hexane technology breakthroughs, abrupt REACH or OSHA regulatory amendments, and geopolitical disruption to China-India naphtha trade flows. Deviation in catalytic reforming catalyst regeneration cycle reliability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Droppers Market
Solvents
Organic Solvents Market
Solvents
Propylene Glycol Ether Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
Wax Dispersion Market
Solvents
Nitromethane Market
Solvents
Piperylene Market
Solvents
High Purity Solvents Market
Solvents
Toluene Derivatives Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
2-Butanone Market
Solvents
N-Pentyl Chloride Market
Solvents
Europe Acetonitrile Market
Solvents
Green Solvents Market
Solvents
Hydrofluoroether Market
Solvents
Dihydromyrcenol Market