
 Global Droppers Market | 2026-2036
Global Droppers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Droppers Market Intelligence
Pharmaceutical buyer concentration is rebalancing as large contract manufacturers consolidate volume while specialty biotech firms fragment procurement across niche suppliers. Gerresheimer AG leverages its borosilicate glass expertise to sustain leadership in high-precision dosing applications. DWK Life Sciences GmbH anchors European laboratory supply chains through specialized graduated dropper formats. Virospack SL competes in cosmetic and essential oil segments with differentiated silicone bulb assemblies.
A dropper is a narrow-tube liquid dispensing device, typically constructed from borosilicate glass or medical-grade polypropylene, employing a compressible bulb to generate vacuum suction for controlled volume extraction and release. The mechanism functions through partial vacuum creation when the bulb decompresses, drawing precise liquid quantities into a calibrated chamber for accurate re-dispensing in pharmaceutical, laboratory, and cosmetic applications. Glass droppers dominate pharmaceutical dispensing where chemical inertness and autoclave compatibility protect biologic formulation integrity, while plastic droppers expand fastest in cosmetic packaging driven by cost efficiency and breakage resistance for e-commerce distribution. Electronic droppers represent an emerging margin pool as digital dosing systems penetrate ophthalmic and pediatric therapeutic segments requiring micro-liter precision.
FDA's container closure guidance and Europe's MDR enforce extractables and leachables testing for pharmaceutical droppers, compelling material traceability investments across supply chains. REACH restrictions on phthalates and ECHA evaluations of silicone additives reshape formulation choices for bulb and tip components in European markets. ISO 15378 certification requirements for primary medicinal packaging extend quality system burdens to Asian contract manufacturers serving regulated markets. Stakeholders must monitor evolving pharmacopeial standards for glass hydrolytic resistance classes as biologic drug portfolios expand.
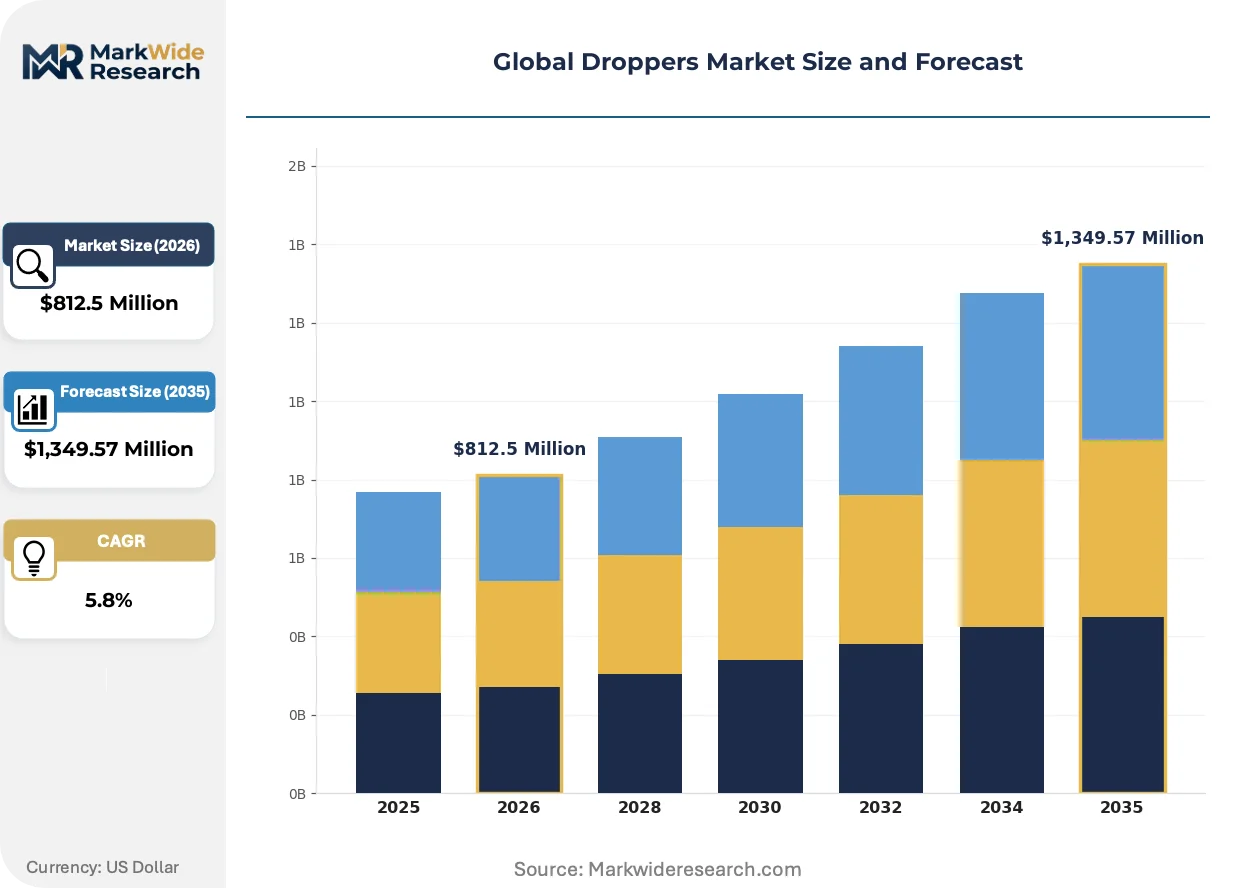
Market Dynamics
Biologic drug format proliferation is fragmenting procurement patterns across pharmaceutical dispensing, forcing suppliers to reconcile precision dosing requirements with divergent material compliance regimes across FDA, EMA, and NMPA jurisdictions.
Growth Catalysts
- Biologic formulation expansion:Monoclonal antibody and cell therapy portfolios multiply vial-and-dropper combinations, pulling demand for hydrolytic class I borosilicate glass. Contract manufacturers in Germany and Switzerland scale dedicated filling lines.
- REACH phthalate restrictions:ECHA evaluations of plasticizer alternatives accelerate silicone bulb formulation innovation. European cosmetic brands preempt compliance by qualifying medical-grade thermoplastic elastomers.
- Home diagnostic penetration:Self-administered ophthalmic and hormone testing kits normalize precision dropper consumption. Direct-to-consumer channels in the United States and South Korea absorb calibrated glass pipette volumes previously reserved for clinical settings.
Market Restraints
- Raw material concentration:High-purity borosilicate glass feedstock concentrates among German and Czech manufacturers. Supply disruptions at any node propagate through pharmaceutical packaging tiers.
- Autoclave compatibility thresholds:Polypropylene droppers face sterilization temperature ceilings that exclude them from parenteral drug applications. Glass retains mandatory status across injectable portfolios.
- Silicone additive scrutiny:ECHA substance evaluations of platinum-cured bulb compounds extend qualification timelines. Reformulation costs compress margins for mid-tier cosmetic suppliers.
Strategic Opportunities
- Pediatric micro-dosing systems:Electronic droppers with digital volume readouts penetrate Japan and Nordic markets where dosing precision carries liability weight. METI reimbursement pathways favor connected device formats.
- E-commerce breakage mitigation:Pharmaceutical-grade plastic droppers with graduated markings capture cosmetic subscription box channels. Amazon and Sephora fulfillment specifications reward drop-shock resistant packaging.
- ISO 15378 certification arbitrage:Asian contract manufacturers investing in primary medicinal packaging quality systems access regulated European and North American markets. Certification gaps among regional competitors create first-mover windows.
Industry Challenges
- Extractables testing capacity:FDA container closure guidance demands analytical chemistry investment that smaller bulb and tip suppliers cannot self-fund. Third-party laboratory queues extend product launch timelines.
- Multi-jurisdiction filing synchronization:Divergent pharmacopeial standards for glass hydrolytic resistance between USP, EP, and JP compendia force redundant qualification batches. Regulatory affairs headcount becomes a binding constraint.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Droppers Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,349.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Droppers, Plastic Droppers, Bulb Pipettes, Graduated Droppers, Electronic Droppers Application: Pharmaceutical Dispensing, Laboratory Use, Cosmetic Packaging, Essential Oil Bottling, Food Flavoring Material: Borosilicate Glass, Polypropylene, Silicone, Low-Density Polyethylene, Thermoplastic Elastomer Sales Channel: Direct Sales, Online Retailers, Medical Distributors, Laboratory Suppliers, Cosmetic Wholesalers |
| Companies Covered | Gerresheimer AG, AptarGroup Inc., Bormioli Pharma S.p.A., DWK Life Sciences GmbH, Comar LLC, Adelphi Healthcare Packaging, Stölzle Oberglas GmbH, Virospack SL, SGD Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Droppers Market Strategic Shifts & Innovations
Dropper architecture is bifurcating between precision pharmaceutical instruments and cost-optimized cosmetic dispensers, with material science and digital dosing technologies carving distinct competitive terrains.
Modular silicone bulb assemblies are modularizing across essential oil and aromatherapy applications. Small-batch cosmetic formulators in France and California swap standardized bulb-tip combinations to differentiate user experience without retooling glass pipette inventories. Component interchangeability compresses SKU proliferation while preserving brand customization.
Europe's MDR and REACH frameworks are tightening material traceability mandates for medical packaging. Extractables and leachables documentation now extends through tier-three suppliers of bulb elastomers and glass surface treatments. German pharmaceutical droppers face accelerated auditing cycles as notified bodies apply consolidated technical documentation requirements.
Direct procurement from specialized glass manufacturers is displacing distributor intermediaries among mid-size biotech firms. These buyers qualify DWK Life Sciences and Gerresheimer directly to secure batch consistency for clinical trial materials. The pattern concentrates in Boston and Basel clusters where regulatory proximity justifies relationship investment.
Global Droppers Market Segmentation
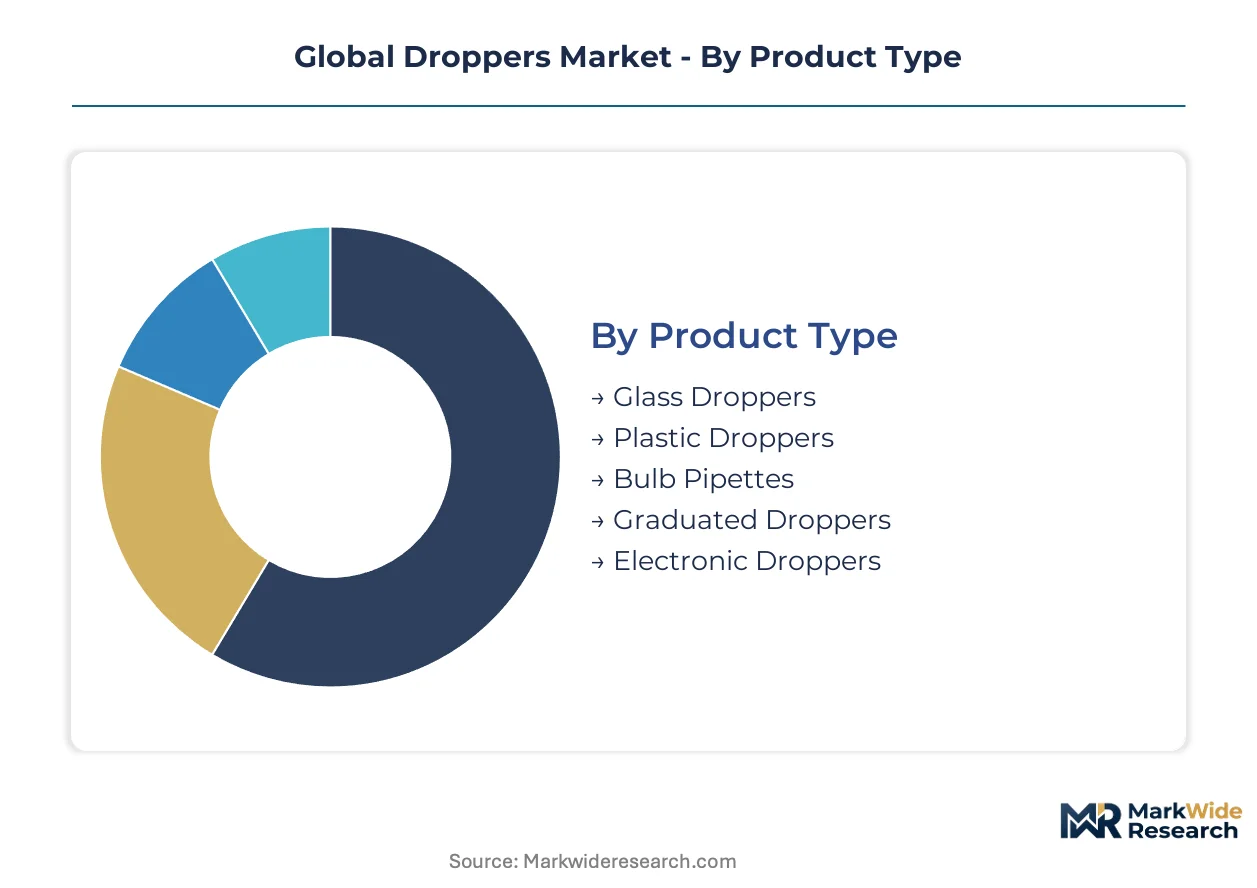
Dropper segmentation reveals divergent material and precision requirements across pharmaceutical, cosmetic, and laboratory end-uses. Suppliers must reconcile hydrolytic glass standards for biologics against cost-optimized plastic formats for e-commerce cosmetics.
Product Type:
Glass and plastic architectures dominate, with electronic formats emerging at the precision frontier.
- Glass Droppers:Borosilicate construction delivers hydrolytic class I inertness mandatory for parenteral and ophthalmic biologics. Demand clusters in German pharmaceutical manufacturing and Swiss contract filling operations where autoclave compatibility protects formulation integrity.
- Plastic Droppers:Medical-grade polypropylene and polyethylene formats expand through cosmetic subscription channels and direct-to-consumer diagnostic kits. Breakage resistance satisfies Amazon and Sephora fulfillment specifications for e-commerce distribution.
- Bulb Pipettes:Simple squeeze-bulb designs serve essential oil and aromatherapy applications with minimal graduated markings.
- Graduated Droppers:Calibrated chamber markings enable precise volume extraction for laboratory titration and clinical dosing protocols.
- Electronic Droppers:Digital volume readouts penetrate pediatric and ophthalmic therapeutic segments requiring micro-liter precision in Japan and Nordic markets.
Mature deployment sits with glass droppers. Newer deployment is concentrated in electronic droppers.
Application:
End-use concentration determines material compliance burdens and pricing architecture.
- Pharmaceutical Dispensing:FDA container closure guidance and EMA MDR requirements enforce extractables testing across primary packaging. Monoclonal antibody and cell therapy portfolios multiply vial-and-dropper combinations, pulling hydrolytic class I borosilicate volumes.
- Laboratory Use:Graduated glass pipettes support analytical chemistry and quality control workflows in academic and industrial research settings.
- Cosmetic Packaging:Silicone bulb assemblies with interchangeable tips enable small-batch formulators in France and California to differentiate user experience without retooling glass inventories.
- Essential Oil Bottling:Amber glass with rubber bulb combinations protects photosensitive formulations from oxidative degradation.
- Food Flavoring:Food-grade plastic droppers serve commercial bakery and beverage manufacturing with cost-efficient volume dispensing.
Regulatory intensity peaks in pharmaceutical dispensing. Volume expansion runs fastest through cosmetic packaging.
Material:
REACH phthalate restrictions and ECHA silicone evaluations are accelerating formulation shifts across bulb and tip components.
- Borosilicate Glass:Hydrolytic resistance classes under USP, EP, and JP compendia govern pharmaceutical acceptance. German and Czech feedstock concentration creates supply vulnerability at any node disruption.
- Polypropylene:Autoclave temperature ceilings exclude this material from parenteral applications, limiting penetration to oral and topical drug formats.
- Silicone:Platinum-cured bulb compounds face extended ECHA qualification timelines, compressing margins for mid-tier cosmetic suppliers.
- Low-Density Polyethylene:Flexible squeeze bottles pair with detachable droppers for food flavoring and household chemical applications.
- Thermoplastic Elastomer:Medical-grade TPE alternatives preempt REACH compliance for European cosmetic brands seeking phthalate-free bulb formulations.
Glass retains mandatory status across injectable portfolios. Thermoplastic elastomer adoption is accelerating fastest in cosmetic segments.
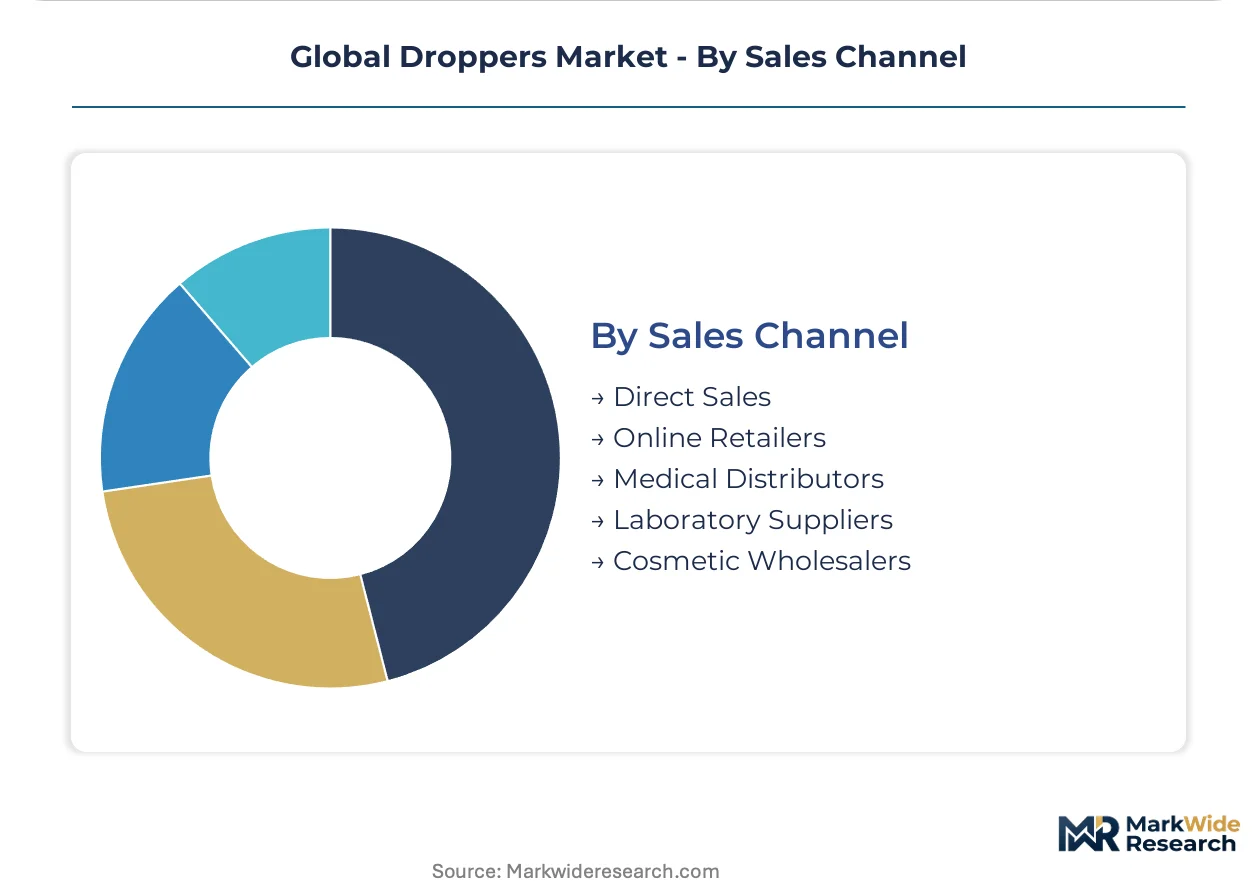
Sales Channel:
Direct procurement patterns are displacing distributor intermediaries among mid-size biotech firms seeking batch consistency.
- Direct Sales:Boston and Basel biotech clusters qualify specialized glass manufacturers directly to secure clinical trial material consistency, bypassing traditional laboratory distributors.
- Online Retailers:Amazon and specialized cosmetic platforms absorb calibrated pipette volumes for home diagnostic and essential oil segments.
- Medical Distributors:McKesson and Cardinal Health channels serve hospital pharmacy and physician office dispensing with ISO 15378-certified primary packaging.
- Laboratory Suppliers:DWK Life Sciences and VWR anchor European and North American research supply chains with specialized graduated formats.
- Cosmetic Wholesalers:Sephora and Ulta fulfillment networks specify drop-shock resistant packaging for subscription box channels.
Consolidated volume flows through medical distributors. Fragmented procurement concentrates in online retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Czech borosilicate glass feedstock concentration anchors pharmaceutical dropper supply chains, with precision manufacturing clusters radiating through Central Europe and North American biotech corridors.
Germany
Monoclonal antibody filling lines in Baden-Württemberg and Bavaria pull hydrolytic class I glass volumes for parenteral biologics. REACH phthalate restrictions accelerate medical-grade thermoplastic elastomer qualification among bulb suppliers. Gerresheimer AG and DWK Life Sciences GmbH anchor precision manufacturing in Mainz and Wertheim, serving Swiss and German contract manufacturers with autoclave-compatible formats.
United States
Boston and San Diego biotech clusters qualify specialized glass manufacturers directly for clinical trial material consistency. FDA container closure guidance enforces extractables and leachables testing across primary packaging tiers. Direct-to-consumer home diagnostic penetration in California and Texas normalizes precision dropper consumption outside clinical settings.
Switzerland
Swissmedic oversight of container closure systems aligns with EMA MDR requirements for biologic drug portfolios. Basel pharmaceutical manufacturing concentrates demand for graduated glass pipettes in cell therapy applications. Contract filling operations near Zurich and Geneva source borosilicate components from adjacent German suppliers to minimize batch variability.
China
NMPA pharmacopeial standards for glass hydrolytic resistance diverge from USP and EP compendia, forcing redundant qualification batches for export-oriented manufacturers. Yangtze River Delta packaging hubs invest in ISO 15378 certification to access regulated European and North American markets. Domestic biologic drug expansion pulls medical-grade dropper demand through Shanghai and Suzhou pharmaceutical corridors.
France
ANSM evaluations of silicone bulb compounds extend qualification timelines for cosmetic and pharmaceutical applications. Small-batch essential oil formulators in Provence and Grasse leverage modular bulb-tip interchangeability to differentiate user experience. Paris-region laboratory suppliers distribute graduated formats through European research supply chains.
Global Droppers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital dosing and connected device formats. The vendor base stratifies across three tiers: precision glass specialists serving regulated pharmaceutical markets, cost-optimized plastic fabricators capturing cosmetic e-commerce channels, and technology developers commercializing electronic micro-dosing systems. Competitive dynamics center on material compliance investments and certification arbitrage rather than price aggression alone. M&A activity concentrates among bulb and tip component suppliers seeking backward integration into elastomer formulation.
Among German precision glass specialists, Gerresheimer AG and DWK Life Sciences GmbH exemplify the regulated-market archetype through borosilicate expertise and primary medicinal packaging certification. Virospack SL represents the differentiated-component tier with specialized silicone bulb assemblies. These three entities anchor distinct competitive vectors: pharmaceutical compliance, laboratory supply chain integration, and cosmetic customization flexibility.
| Leading Market Players |
|---|
| Gerresheimer AG |
| AptarGroup Inc. |
| Bormioli Pharma S.p.A. |
| DWK Life Sciences GmbH |
| Comar LLC |
| Adelphi Healthcare Packaging |
| Stölzle Oberglas GmbH |
| Virospack SL |
| SGD Pharma |
| Others |
Cost & Logistics Intelligence
Borosilicate glassblower skill concentration in Thuringia and Bavaria anchors German precision dropper manufacturing, with labor-cost differentials between these specialized clusters and Asian plastic fabrication centers driving 40-60% spreads between pharmaceutical-grade glass and cosmetic plastic tiers.
Pricing Analysis
Volume concentrates in standardized plastic droppers while margins pool in electronic micro-dosing systems. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified pharmaceutical glass from laboratory-graded formats and cosmetic polypropylene. Pricing pressure stems from REACH compliance costs for silicone bulb reformulation, compressing mid-tier cosmetic supplier margins. Contract manufacturers show lowest price sensitivity; direct-to-consumer cosmetic brands exhibit highest.
Supply Chain Analysis
Return flows for pharmaceutical glass droppers center on autoclave refurbishment cycles and silicone bulb replacement programs rather than end-of-life disposal. German, Czech, and Chinese suppliers dominate borosilicate feedstock and polypropylene molding capacity. Critical dependencies include high-purity sand from Bavarian quarries, platinum-cured silicone from specialized elastomer compounders, and medical-grade polypropylene resin. Single-source vulnerability concentrates in German glassblower labor pools. Distribution runs through medical distributors for regulated pharmaceutical channels, direct procurement for biotech clusters, and cosmetic wholesalers for essential oil segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dropper market is becoming a vertical-integration race as suppliers pursue captive control over borosilicate glass feedstock to secure batch consistency for biologic drug portfolios.
For Market Incumbents: To counter silicone bulb supply disruption from ECHA additive evaluations, Gerresheimer and DWK Life Sciences should deepen backward integration into platinum-cured elastomer formulation and expand autoclave-compatible glass capacity in Baden-Württemberg. Certification arbitrage through accelerated ISO 15378 auditing creates defensive moats against Asian contract manufacturers. For New Entrants and Emerging Players: Small-batch essential oil formulators in Provence and California represent the most penetrable buyer archetype. Electronic micro-dosing systems for pediatric applications in Japan and Nordic markets offer white-space expansion. A modular bulb-tip interchangeability platform enables rapid brand customization without glass inventory retooling. For Investors and Strategic Acquirers: The window for entry favors mid-tier silicone bulb component suppliers with medical-grade thermoplastic elastomer pivot capability. Long-term viability hinges on extractables testing infrastructure ownership. Watch for FDA container closure guidance revisions as inflection signals for laboratory services demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Feedstock | German manufacturers secure hydrolytic class I glass supply against Czech quarry disruptions. |
| ISO 15378 Certification Acceleration | Asian contract manufacturers unlock European and North American pharmaceutical procurement channels. |
| Electronic Micro-Dosing System Launch | Digital volume readouts capture METI-reimbursed pediatric markets in Japan. |
| Modular Bulb-Tip Platform Development | Component interchangeability reduces SKU proliferation for French essential oil formulators. |
| Extractables Testing Laboratory Acquisition | Third-party capacity ownership shortens product launch timelines for EMA MDR compliance. |
Research Approach
FDA container closure guidance documents, EMA MDR technical files, and REACH substance evaluation records formed the secondary backbone. Primary interviews with pharmaceutical packaging procurement managers, regulatory affairs directors at contract manufacturers, borosilicate glass plant engineers, and cosmetic formulator purchasing leads validated demand assumptions. Bottom-up volume modeling triangulated against top-down pharmaceutical biologics pipeline analysis.
Bottom-up segmentation by product type, material composition, application end-use, and regional regulatory cluster anchored the analytical lens. CAGRs derived from regression against monoclonal antibody and cell therapy portfolio expansion trajectories, with cross-reference to e-commerce cosmetic subscription growth patterns. Forecast inputs incorporated autoclave compatibility thresholds and silicone additive qualification timelines.
Revisions become necessary when ECHA substance evaluations accelerate, FDA container closure guidance expands testing requirements, or NMPA pharmacopeial standards diverge further from USP and EP compendia. Practitioners should monitor regulatory filing synchronization costs and extractables laboratory queue lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Solvent Evaporation Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Japan Acetonitrile Market
Solvents
North America Acetonitrile Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
3-Butylene Glycol Market
Solvents
India High Purity Solvents Market
Solvents
Solvent Cement Market
Solvents
Chlorobenzene Market
Solvents
Crotonaldehyde Market
Solvents
Dihydromyrcene Market
Solvents
Citrus Solvents Market
Solvents
Decanol Market
Solvents
Butyl Glycol Market
Solvents
Hexylene Glycol Market
Solvents
Nitromethane Market