
 Europe Acetonitrile Market | 2026-2036
Europe Acetonitrile Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Acetonitrile Market Intelligence
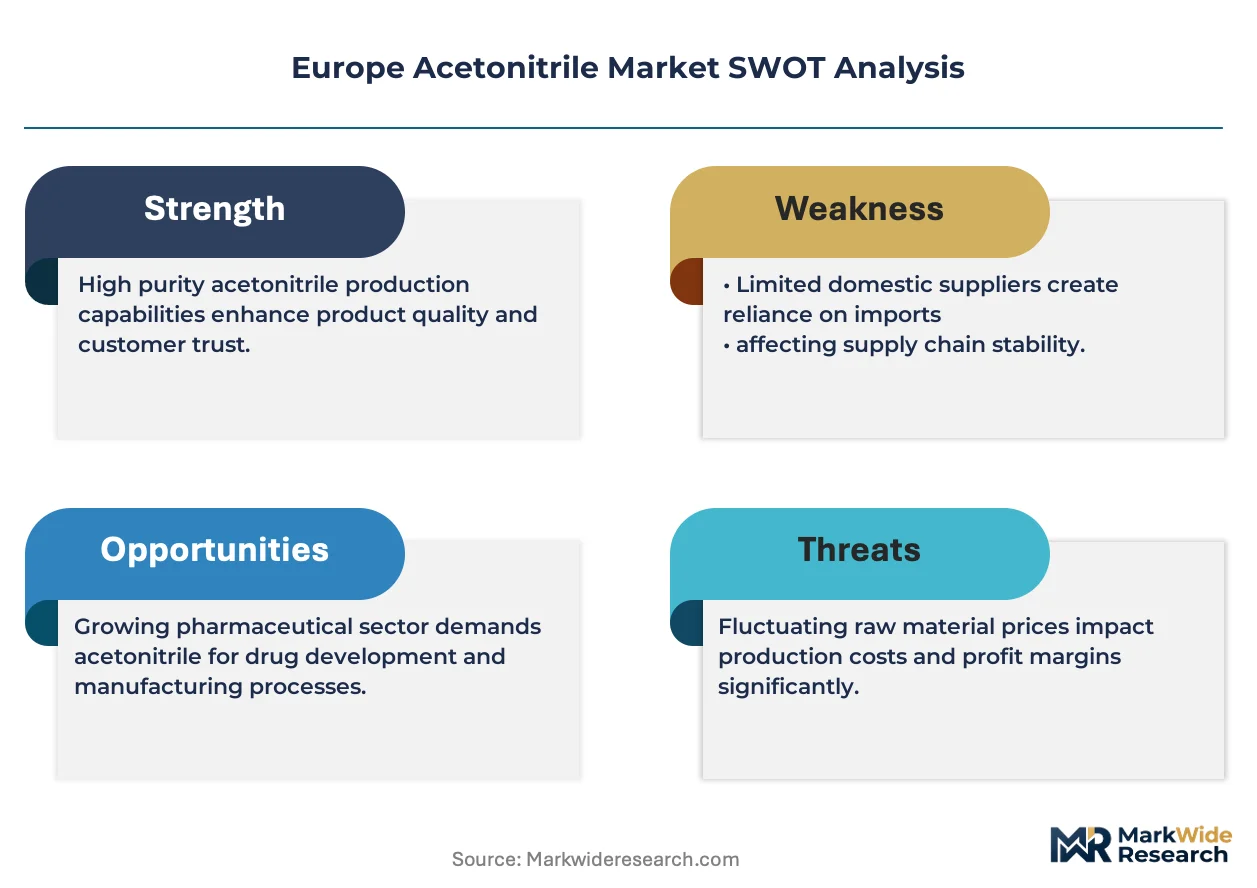
Green chemistry process intensification is tilting European acetonitrile production toward bio-ethylene-derived and recycled feedstock routes. INEOS Group Holdings S.A leverages its integrated petrochemical infrastructure across Belgium and the UK to sustain cost-competitive acrylonitrile co-product streams. Honeywell International, Inc. anchors its position through specialized purification technologies that differentiate its high-purity grades for pharmaceutical chromatography. Anqore BV specializes in regional distribution logistics and controls access to the Benelux research solvent channel.
Acetonitrile is a polar aprotic nitrile solvent with the formula CH3CN, boiling point 82 degrees Celsius, and dielectric constant 37.5, manufactured primarily as a co-product of acrylonitrile synthesis via propylene ammoxidation or through direct acetic acid ammoniation. Its primary industrial purpose centers on high-performance liquid chromatography mobile phases, pharmaceutical synthesis extraction media, and agrochemical formulation diluents. Pharmaceutical applications lead the European consumption structure due to regulatory-mandated analytical purity requirements and the concentration of generic drug manufacturing in Germany and Italy. High Purity grades capture the dominant margin pool because chromatography solvent specifications under European Pharmacopoeia and ISO 17025 accreditation protocols command price premiums over Industrial Grade alternatives. Laboratory Solvents represent the fastest-growing application segment as contract research organizations and biotechnology firms expand outsourced analytical services.
REACH registration obligations under ECHA govern substance volume thresholds and safety data sheet dissemination across all EU member states, while the EU Green Deal's chemical strategy for sustainability imposes carbon footprint disclosure requirements on imported acetonitrile. EMA guidelines for pharmaceutical excipients and analytical reagents further constrain allowable impurity profiles for chromatography-grade material. The F-Gas Regulation's indirect pressure on fluorinated solvent alternatives creates additional demand migration toward acetonitrile in certain industrial cleaning applications. Stakeholders must monitor the implementation timeline for the EU's proposed critical raw materials act and its potential classification of petrochemical-derived solvents against bio-based alternatives.
Market Dynamics
Acetonitrile supply in Europe is tightening around propylene feedstock constraints and acrylonitrile co-production economics, forcing pharmaceutical solvent buyers to secure multi-year contracts with integrated petrochemical producers.
Growth Catalysts
- REACH compliance deadlines:ECHA registration requirements for high-volume substances are consolidating demand toward registered suppliers with established safety dossiers, particularly benefiting German and Belgian refiners.
- Biopharmaceutical expansion:Contract research organizations across the Netherlands and Switzerland are scaling chromatography solvent consumption for monoclonal antibody purification and peptide synthesis workflows.
- Agrochemical formulation:F-Gas Regulation restrictions on fluorinated solvents are redirecting pesticide manufacturers toward acetonitrile-based diluent systems for active ingredient delivery.
Market Restraints
- Propylene price volatility:Acrylonitrile co-production economics tie acetonitrile supply to acrylic fiber and ABS resin demand cycles, creating volume unpredictability for solvent buyers.
- Single-source concentration:Belgium's integrated petrochemical corridor controls the majority of European acetonitrile output, exposing buyers to geographic supply risk.
- Bio-based substitution:EU Green Deal mandates are accelerating development of bio-ethylene-derived acetonitrile pathways, threatening margins for conventional petrochemical producers.
Strategic Opportunities
- Eastern European expansion:Poland and Hungary's emerging generic drug manufacturing clusters present underdeveloped demand for pharmaceutical-grade solvents with limited local supply infrastructure.
- Circular feedstock integration:Chemical recycling of acetonitrile waste streams from pharmaceutical manufacturing aligns with EU Taxonomy criteria for sustainable economic activities.
- Specialized logistics networks:Temperature-controlled solvent distribution partnerships with biotechnology hubs in Denmark and Sweden enable just-in-time delivery for temperature-sensitive chromatography applications.
Industry Challenges
- Analytical chemist scarcity:Pharmaceutical contract manufacturers face recruitment gaps for chromatography method development specialists capable of validating acetonitrile-based mobile phase protocols.
- ISO 17025 accreditation timelines:Laboratory solvent suppliers encounter 12-18 month certification delays for high-purity grade recognition under European Pharmacopoeia standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Acetonitrile Market |
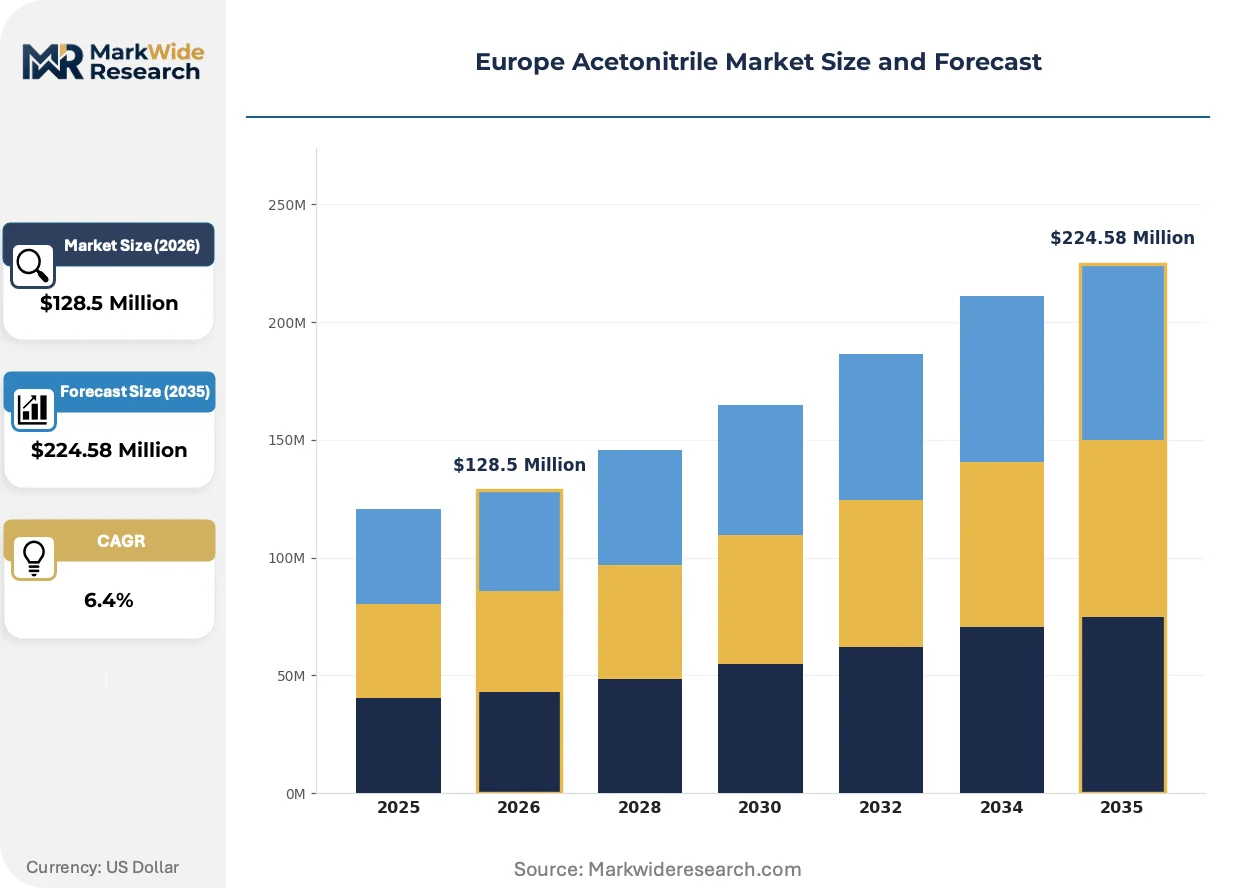
| Market Size in 2026 | $128.5 Million |
| Market Size in 2035 | $224.58 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Pharmaceuticals, Agrochemicals, Synthetic Fibers, Laboratory Solvents Purity Grade: High Purity, Industrial Grade, Reagent Grade, Special Grade End User: Chemical Manufacturers, Research Institutes, Biotechnology Firms, Academic Institutions Packaging Type: Drum, Bottle, Tank, Bulk |
| Companies Covered | INEOS Group Holdings S.A, Honeywell International, Inc., Asahi Kasei Corporation, Avantor, Inc., Thermo Fisher Scientific, Inc., Formosa Plastics Group, Anqore BV, Mitsubishi Chemical Corporation, Cepsa, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Acetonitrile Market Strategic Shifts & Innovations
European acetonitrile production is pivoting toward sustainability-verified supply chains as pharmaceutical buyers embed carbon accounting into procurement criteria and regulators tighten chemical lifecycle disclosure requirements.
Membrane-based solvent purification is migrating from conventional distillation systems toward nanofiltration and pervaporation hybrids that reduce energy intensity in high-purity grade production. Specialty solvent refiners in Germany and Switzerland are adopting these hybrid separation trains to meet pharmaceutical customers' Scope 3 emission reduction targets. The technology is compressing the cost gap between industrial and chromatography grades while enabling smaller batch flexibility for contract research applications.
EU Green Deal chemical strategy implementation is mandating carbon footprint disclosure for imported acetonitrile volumes, compelling non-European suppliers to obtain Product Environmental Footprint certification. This regulatory friction is redirecting procurement toward Benelux and German producers with verified lifecycle data. Pharmaceutical manufacturers in Italy and France are prioritizing regional suppliers to avoid border adjustment mechanism exposure.
Consolidated buying consortiums among mid-sized contract research organizations are displacing spot-market purchasing with multi-year framework agreements that bundle acetonitrile with complementary HPLC solvents. These procurement collectives in the Netherlands and Denmark negotiate volume commitments in exchange for price stability and dedicated inventory buffers. The model is concentrating purchasing power among fewer buyer entities while squeezing distributor margins.
Europe Acetonitrile Market Segmentation
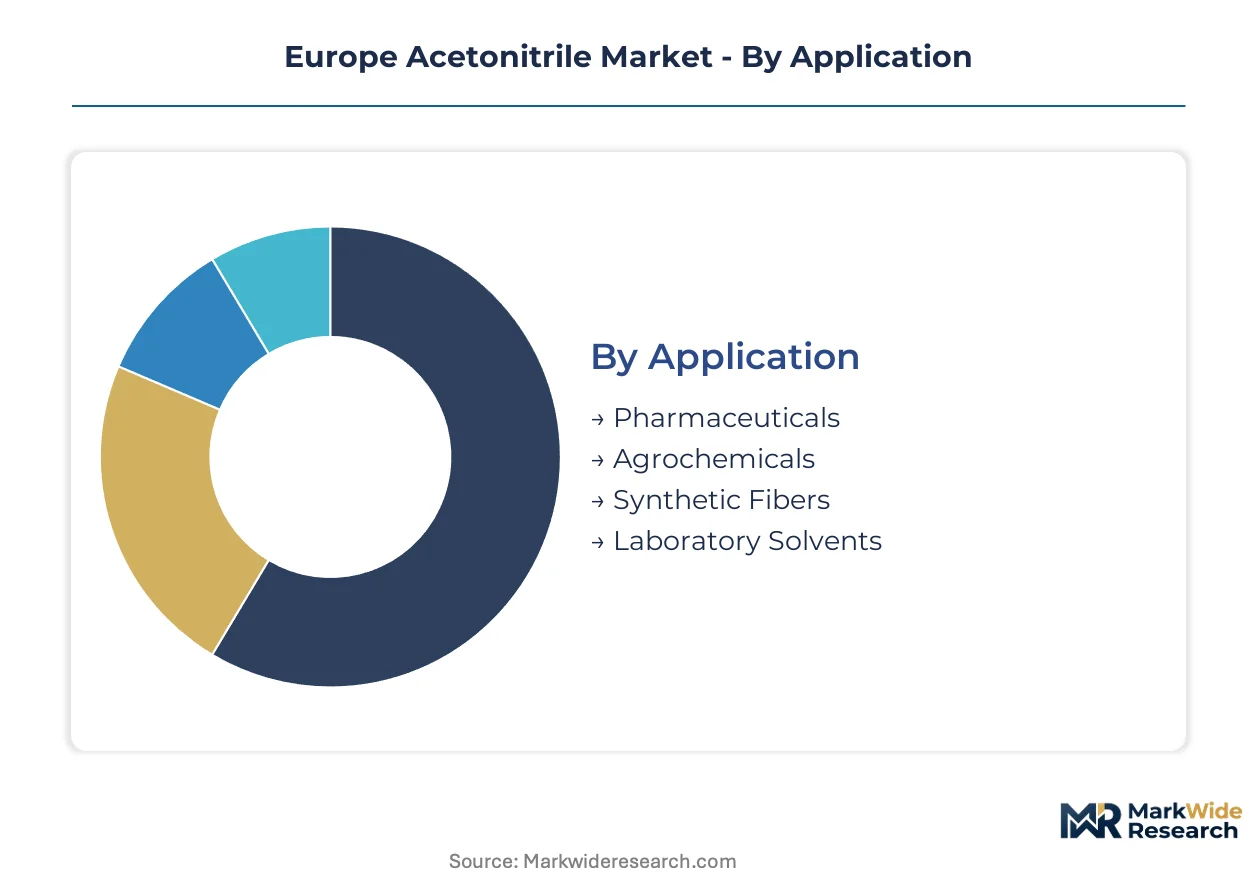
Acetonitrile procurement patterns across Europe diverge sharply by purity specification and end-use criticality, with pharmaceutical buyers demanding ISO 17025-accredited supply chains while industrial consumers prioritize volume flexibility over certification depth. Understanding these segment boundaries enables suppliers to align purification investments with margin capture potential.
Application:
After-sales service intensity varies dramatically across application segments, with pharmaceutical chromatography users requiring technical support for method validation and solvent disposal compliance that agrochemical buyers rarely demand.
- Pharmaceuticals:High-performance liquid chromatography mobile phases and extraction media for active pharmaceutical ingredient synthesis dominate European consumption. German and Italian generic drug manufacturers anchor demand through EMA-mandated analytical purity requirements and continuous manufacturing workflows.
- Laboratory Solvents:Contract research organizations across the Netherlands and Switzerland are scaling consumption for monoclonal antibody purification and peptide synthesis workflows, driving the steepest expansion trajectory among application segments.
- Agrochemicals:Formulation diluents for pesticide active ingredient delivery are gaining share as F-Gas Regulation restrictions redirect manufacturers from fluorinated alternatives.
- Synthetic Fibers:Acrylic fiber production consumes acetonitrile as a process solvent, though propylene feedstock constraints tie volumes to ABS resin demand cycles.
By volume, Pharmaceuticals leads. By growth pace, Laboratory Solvents is ahead.
Purity Grade:
Cost tier stratification separates chromatography-grade refiners pursuing European Pharmacopoeia certification from commodity suppliers serving industrial cleaning applications.
- High Purity:Chromatography specifications under European Pharmacopoeia and ISO 17025 accreditation command substantial price premiums over lower grades. German specialty solvent refiners concentrate production to serve contract research organizations and biotechnology quality control laboratories.
- Industrial Grade:Standard specifications for agrochemical formulation and synthetic fiber processing prioritize volume throughput over impurity profiling. Belgian integrated petrochemical producers leverage acrylonitrile co-production economics to maintain cost positioning.
- Reagent Grade:Analytical applications in academic and government testing laboratories require documented batch consistency and Certificate of Analysis availability.
- Special Grade:Custom specifications for electronics manufacturing and specialized extraction processes command niche premiums with limited supplier competition.
High Purity captures the dominant margin pool. Special Grade shows the most rapid pricing escalation.
End User:
Customer type determines procurement modality, with chemical manufacturers negotiating multi-year framework agreements while academic institutions rely on distributor spot purchasing.
- Chemical Manufacturers:Integrated solvent consumers across Germany's chemical manufacturing corridor require just-in-time delivery and dedicated inventory buffers to sustain continuous production schedules.
- Biotechnology Firms:Denmark and Sweden's expanding biotech hubs demand temperature-controlled distribution networks for temperature-sensitive chromatography applications.
- Research Institutes:National laboratories and government testing facilities in France and Italy prioritize REACH-registered suppliers with established safety dossiers.
- Academic Institutions:University research departments across Europe exhibit fragmented purchasing patterns with high price sensitivity and limited volume commitment.
Chemical Manufacturers dominate absolute consumption. Biotechnology Firms are expanding most quickly.
Packaging Type:
Supply chain configuration and handling infrastructure requirements segment buyers by operational scale and storage capability.
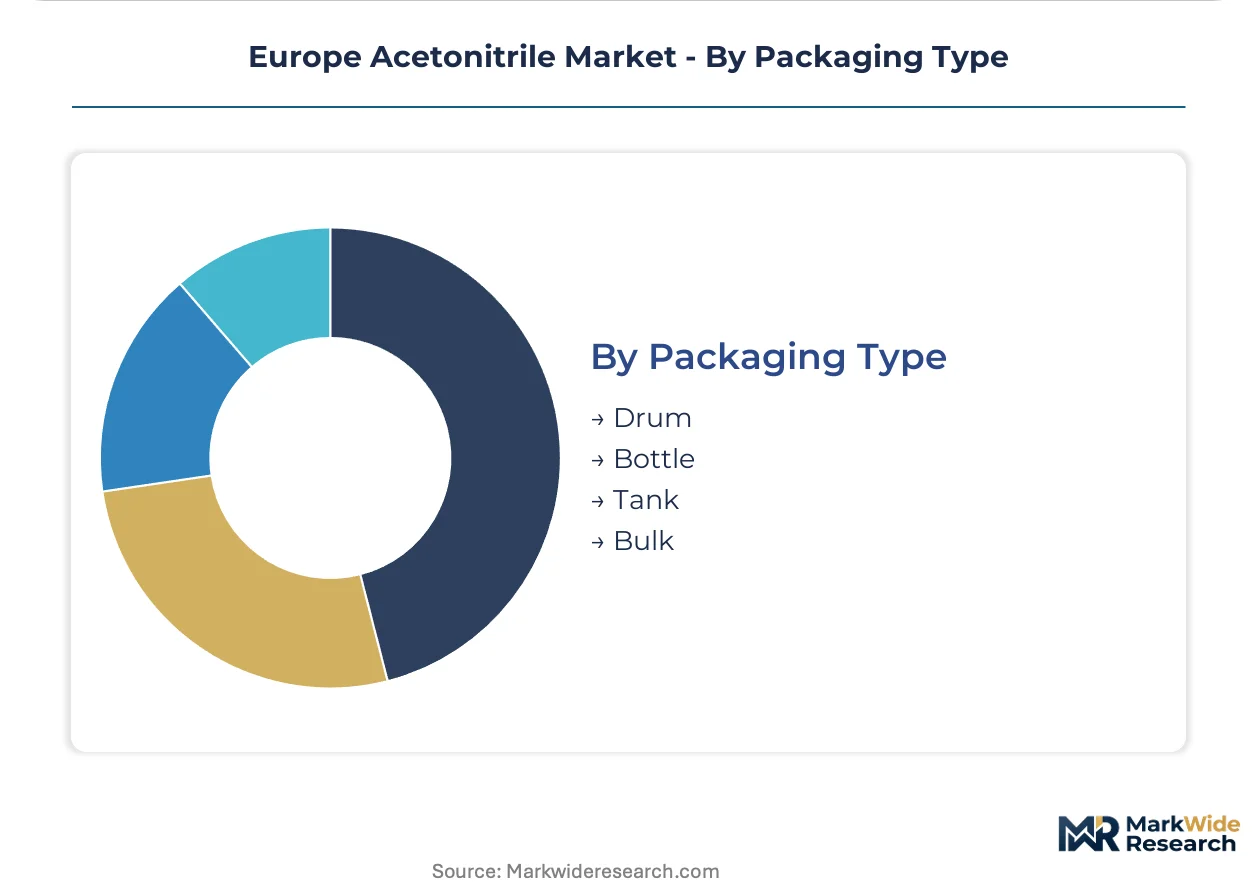
- Bulk:Tanker deliveries to integrated pharmaceutical and agrochemical manufacturing sites minimize per-unit handling costs and packaging waste.
- Tank:Intermediate volume solutions serve mid-sized contract manufacturers with dedicated solvent storage infrastructure.
- Drum:Standard 200-liter containers balance portability with volume efficiency for regional distribution to multiple consumption points.
- Bottle:Laboratory-scale packaging addresses research institute and academic demand with minimal order quantities and flexible specification sourcing.
Bulk leads in volume throughput. Bottle formats are gaining share fastest among emerging biotechnology entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and biotechnology quality control laboratories concentrate acetonitrile procurement across Germany, the Netherlands, and Switzerland, driving demand for REACH-registered, high-purity supply chains.
Germany
Generic drug manufacturers in the Rhine-Ruhr chemical corridor anchor European acetonitrile consumption for HPLC mobile phases and API extraction. EMA pharmaceutical excipient guidelines enforce stringent impurity profiling that favors domestic specialty solvent refiners. Bavaria's biotechnology cluster around Munich sustains temperature-controlled solvent distribution for monoclonal antibody purification workflows.
Belgium
Integrated petrochemical infrastructure near Antwerp generates the majority of European acetonitrile output as acrylonitrile co-product streams. REACH registration obligations under ECHA consolidate supply relationships toward established Belgian producers with complete safety dossiers. The Port of Antwerp-Bruges logistics hub enables bulk tanker deliveries to pharmaceutical manufacturers across the Benelux region.
Netherlands
Contract research organizations in the Randstad metropolitan area scale chromatography solvent consumption for peptide synthesis and analytical method development. EU Green Deal carbon footprint disclosure requirements redirect procurement toward regional suppliers with verified lifecycle data. Eindhoven's emerging biotech corridor demands just-in-time solvent delivery for continuous manufacturing operations.
Switzerland
Pharmaceutical headquarters in Basel and biologics manufacturing in the Lake Geneva region command premium-grade acetonitrile for regulatory-submission batch analysis. Swissmedic guidelines for analytical reagents constrain allowable contaminant levels below European Pharmacopoeia baselines. The country's specialized logistics networks serve as distribution gateways for temperature-sensitive solvents into Alpine research facilities.
Italy
Generic API producers in Lombardy and Emilia-Romagna expand acetonitrile purchases for extraction and crystallization processes. F-Gas Regulation restrictions on fluorinated alternatives redirect agrochemical formulators toward acetonitrile-based diluent systems. Milan's contract manufacturing cluster negotiates multi-year framework agreements to secure volume commitments against propylene feedstock volatility.
Europe Acetonitrile Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure consolidating around integrated petrochemical conglomerates and purified-grade specialists. Three archetypes dominate: acrylonitrile co-producers leveraging propylene economics, specialty solvent refiners pursuing European Pharmacopoeia certification, and regional distributors commanding Benelux logistics access. Competitive moves center on backward integration into propylene supply and purification technology licensing for high-purity grade differentiation.
Among integrated petrochemical conglomerates, INEOS Group Holdings S.A and Asahi Kasei Corporation exemplify scale-driven positioning through acrylonitrile co-production infrastructure. Specialty purification players include Honeywell International, Inc., which occupies a position anchored in analytical-grade solvent technologies, and Anqore BV, representing the regional distribution archetype with Benelux channel control. These three companies illustrate the competitive tension between upstream feedstock security and downstream certification depth that defines European acetonitrile supply.
| Leading Market Players |
|---|
| INEOS Group Holdings S.A |
| Honeywell International, Inc. |
| Asahi Kasei Corporation |
| Avantor, Inc. |
| Thermo Fisher Scientific, Inc. |
| Formosa Plastics Group |
| Anqore BV |
| Mitsubishi Chemical Corporation |
| Cepsa |
| Others |
Cost & Logistics Intelligence
Belgium's Antwerp petrochemical corridor concentrates European acetonitrile capacity as acrylonitrile co-product output, granting integrated producers substantial leverage over chromatography-grade pricing negotiations with pharmaceutical buyers. This geographic supply concentration amplifies cost pass-through power when propylene feedstock volatility disrupts co-production economics.
Pricing Analysis
Cost-plus contracts indexed to propylene spot benchmarks dominate European acetonitrile procurement, with high-purity grades commanding substantial premiums over industrial specifications due to European Pharmacopoeia certification requirements. Price differentiation separates ISO 17025-accredited chromatography material from commodity industrial grades, while contract research organizations exhibit the highest price sensitivity among buyer segments due to fragmented purchasing volumes. Pricing pressure is intensifying as bio-based acetonitrile pathways mature under EU Green Deal carbon accounting mandates, threatening margin structures for conventional petrochemical producers.
Supply Chain Analysis
Single-source vulnerability from Belgium's concentrated acrylonitrile co-production infrastructure exposes pharmaceutical solvent buyers to geographic disruption risk. Supply draws from propylene feedstock streams tied to acrylic fiber and ABS resin demand cycles, with acrylonitrile co-production economics determining available acetonitrile volumes. Distribution runs through the Port of Antwerp-Bruges logistics hub for bulk tanker deliveries, while specialty solvent refiners in Germany and Switzerland operate dedicated temperature-controlled networks for high-purity grade distribution to biotechnology clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European acetonitrile demand is recovering through pharmaceutical manufacturing expansion, with propylene co-production economics creating cyclical supply tightness that favors prepared buyers and integrated producers.
For Market Incumbents: Insulate margin structures by deepening backward integration into propylene supply and accelerating membrane-based purification technology deployment to meet pharmaceutical Scope 3 emission targets. Bio-based substitution threats from EU Green Deal mandates require certification investment in lifecycle carbon accounting to defend high-purity grade positioning against emerging sustainable feedstock competitors. For New Entrants and Emerging Players: Eastern European pharmaceutical manufacturing clusters in Poland and Hungary represent the most penetrable entry point, where generic drug producers lack local high-purity solvent infrastructure and rely on distant German suppliers. Circular feedstock integration through chemical recycling partnerships with contract manufacturers offers a differentiated go-to-market angle aligned with EU Taxonomy sustainable activity criteria. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialty solvent refiners with European Pharmacopoeia certification command scarcity premiums in a market tightening around REACH compliance barriers. Acquisition targets should display verified lifecycle carbon data and established temperature-controlled distribution networks. The signal to watch is implementation timelines for the EU's proposed critical raw materials act classification of petrochemical-derived solvents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive feedstock security insulates INEOS and Asahi Kasei from acrylic fiber demand cycle volatility. |
| Membrane Purification Technology Deployment | Honeywell's nanofiltration hybrids reduce energy intensity for German pharmaceutical customers' emission targets. |
| Circular Feedstock Partnership Development | Chemical recycling alliances with Milan contract manufacturers align with EU Taxonomy sustainable economic activity criteria. |
| Temperature-Controlled Distribution Expansion | Specialized logistics networks serve Denmark and Sweden biotech hubs for temperature-sensitive chromatography applications. |
| REACH Registration Dossier Investment | ECHA compliance consolidation benefits established Belgian and German suppliers against unregistered import competition. |
Research Approach
Initial hypotheses were tested against primary input from specialty solvent refinery plant managers, pharmaceutical procurement leads at generic drug manufacturers, distribution channel partners in the Benelux region, and technical R&D directors at chromatography equipment suppliers, then refined through secondary validation against ECHA registration databases, Cefic chemical industry reports, customs trade flow records, and SEC filings from listed petrochemical conglomerates. Bottom-up volume estimates from end-use consumption patterns were triangulated with top-down production capacity assessments across European acrylonitrile co-producers.
Demand-supply-balance modeling across the analysis window incorporated purity grade tier differentiation, end-use industry segmentation across pharmaceutical and agrochemical applications, packaging format distribution from bulk tankers to laboratory bottles, and regional production hub concentration in Belgium and Germany. CAGRs were derived from regression analysis of historical consumption trends against forecast drivers including biopharmaceutical expansion and F-Gas Regulation substitution effects, with propylene price volatility and bio-based pathway development as key scenario variables.
Practitioners should monitor EU Green Deal chemical strategy implementation timelines and critical raw materials act classification proceedings for early signals of feedstock preference shifts that could revise demand trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Propylene Glycol Market
Solvents
Global Solvents Market
Solvents
Chloromethane Market
Solvents
Isoamylene Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Hydrosol Market
Solvents
Green Solvents Market
Solvents
Alpha-Methylstyrene Market
Solvents
Fluid Neutralizing Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
Global Chloroform Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Phenol Derivatives Market
Solvents
Aprotic Solvents Market
Solvents
Wax Dispersion Market
Solvents
Triacetin Market