
 Dihydromyrcenol Market | 2026-2036
Dihydromyrcenol Market Size, Share, and Industry Trends Forecast 2026-2036
Dihydromyrcenol Market Analysis
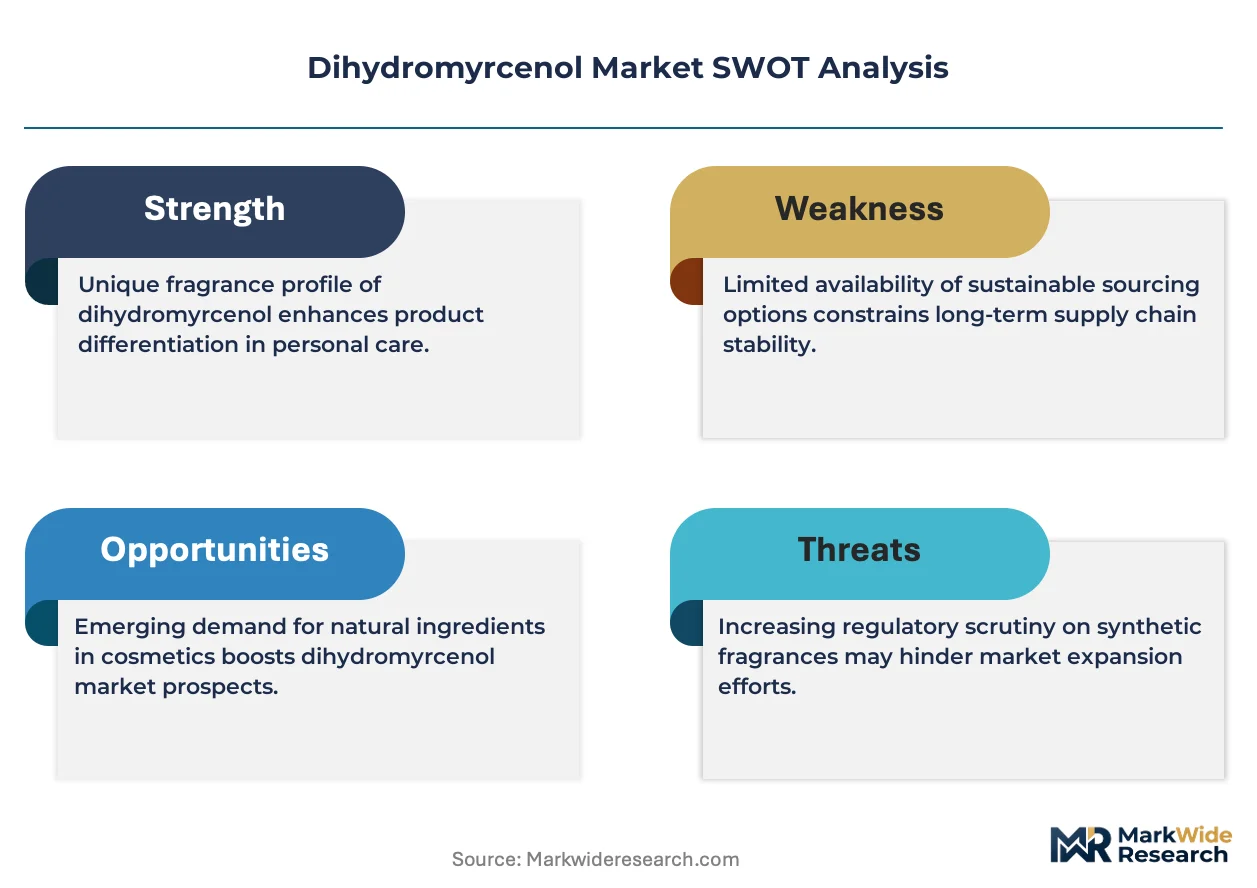
REACH registration requirements for fragrance intermediates is broadening the cost-of-entry calculus for new suppliers entering the European terpenoid alcohol trade. DSM-Firmenich AG leverages captive biotechnology capabilities to secure backward integration into key feedstocks. Takasago International Corporation anchors its position through asymmetric catalysis expertise in terpene transformation. Givaudan SA differentiates via dedicated regulatory affairs teams that navigate complex dossier preparation for novel substance notification.
Dihydromyrcenol is a synthetic terpenoid alcohol with the chemical formula C10H20O, produced through acid-catalyzed hydration of myrcene or hydrogenation of citral derivatives, valued for its fresh citrus-floral odor profile with lime and lavender nuances. The fragrance segment dominates value generation, as fine perfume houses substitute legacy nitro-musks with this biodegradable alternative. Solvent applications for industrial cleaning formulations represent the fastest-growing category, driven by food producers and chemical companies seeking low-toxicity volatile organic compound exempt carriers.
EMA cosmetic ingredient guidelines, ECHA REACH authorization protocols, and EPA TSCA Section 5 premanufacture notices collectively govern substance safety, environmental fate testing, and new chemical notification pathways across the Atlantic. These frameworks elevate compliance spending but simultaneously filter out opportunistic entrants, concentrating margin pools among established producers with dedicated toxicology and regulatory infrastructure. Stakeholders must monitor evolving fragrance allergen labeling thresholds in multiple jurisdictions to anticipate reformulation mandates and raw material qualification timelines.
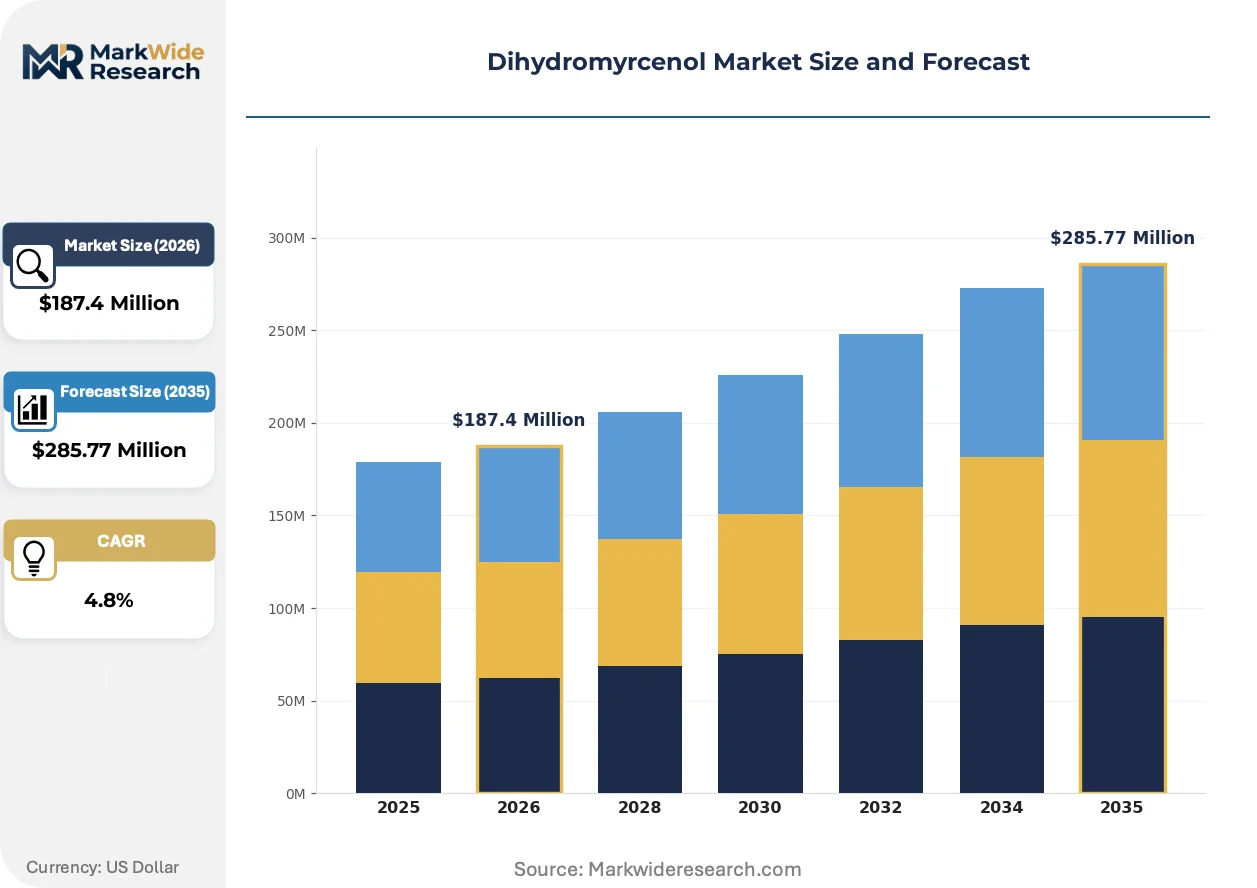
Market Dynamics
EU REACH authorization protocols for fragrance intermediates are restructuring competitive entry barriers, concentrating margin pools among producers with captive toxicology infrastructure and backward-integrated feedstock control.
Growth Catalysts
- REACH registration mandates:ECHA authorization requirements for novel substance notification are filtering out opportunistic suppliers and consolidating procurement relationships with established dossier-capable producers.
- Fine fragrance reformulation:Western European perfume houses are systematically replacing legacy nitro-musks with biodegradable terpenoid alternatives across classic accord portfolios.
- Industrial solvent exemption:EPA TSCA Section 5 premanufacture notices for low-toxicity volatile organic compound carriers are accelerating qualification timelines for food-grade cleaning formulations.
Market Restraints
- Myrcene feedstock volatility:Acid-catalyzed hydration routes depend on turpentine-derived inputs subject to pine harvest cycles and Southeast Asian supply interruptions.
- ECHA dossier preparation costs:REACH compliance spending for toxicology and environmental fate testing elevates breakeven thresholds beyond mid-scale chemical entrants.
- Citral derivative substitution:Hydrogenation pathways compete with direct citrus extraction methods for certain high-purity fragrance applications.
Strategic Opportunities
- Biotechnology convergence:Fermentation-based terpenoid production combined with asymmetric catalysis expertise opens captive supply routes independent of agricultural feedstocks.
- EMA cosmetic allergen thresholds:Tightening fragrance ingredient labeling mandates in European personal care are accelerating qualification of safer, well-documented alternatives.
- Industrial cleaning channel expansion:Direct supply relationships with food producers and chemical compounders bypass traditional fragrance house distribution layers.
Industry Challenges
- Regulatory affairs talent scarcity:Cross-jurisdictional dossier preparation for EMA, ECHA, and EPA frameworks requires specialized toxicologists and environmental chemists in short supply.
- Multi-standard certification timelines:Concurrent EU REACH authorization, EPA TSCA Section 5 notices, and EMA cosmetic ingredient approvals extend product launch cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dihydromyrcenol Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fragrance, Solvent, Flavoring Agent, Intermediate Application: Personal Care, Household Products, Food & Beverage, Industrial Use End User: Cosmetic Manufacturers, Food Producers, Chemical Companies, Retailers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | DSM-Firmenich AG, Takasago International Corporation, Givaudan SA, Privi Speciality Chemicals Limited, DRT, International Flavors & Fragrances Inc., MANE Group, Aurochemicals, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dihydromyrcenol Market Emerging Trajectories
Biocatalytic terpene transformation and tightening fragrance safety standards are actively restructuring production economics and procurement patterns across personal care and industrial solvent applications.
Enzymatic hydration of myrcene is expanding into commercial-scale fragrance intermediate production. Fine fragrance houses in France and Germany are adopting biocatalytic routes to reduce acid-waste streams and secure EU Green Deal-aligned credentials. This technology is expanding into cost-competitive positioning against traditional chemical catalysis for high-purity grades.
REACH authorization protocols for fragrance allergens are compressing formulation flexibility. ECHA's evolving dossier requirements for cumulative exposure assessment are forcing reformulation cycles across legacy perfume portfolios. Fine fragrance segments in Western Europe face the steepest compliance burden, with houses accelerating substitution timelines for nitro-musk replacements.
Direct procurement from compounders is fragmenting traditional fragrance house intermediation. Food producers and industrial chemical formulators in the Netherlands and Switzerland are establishing supply contracts with dihydromyrcenol manufacturers outside conventional distribution channels. This pattern is most visible in solvent applications, where buyers prioritize regulatory documentation speed over brand heritage.
Dihydromyrcenol Market Segmentation
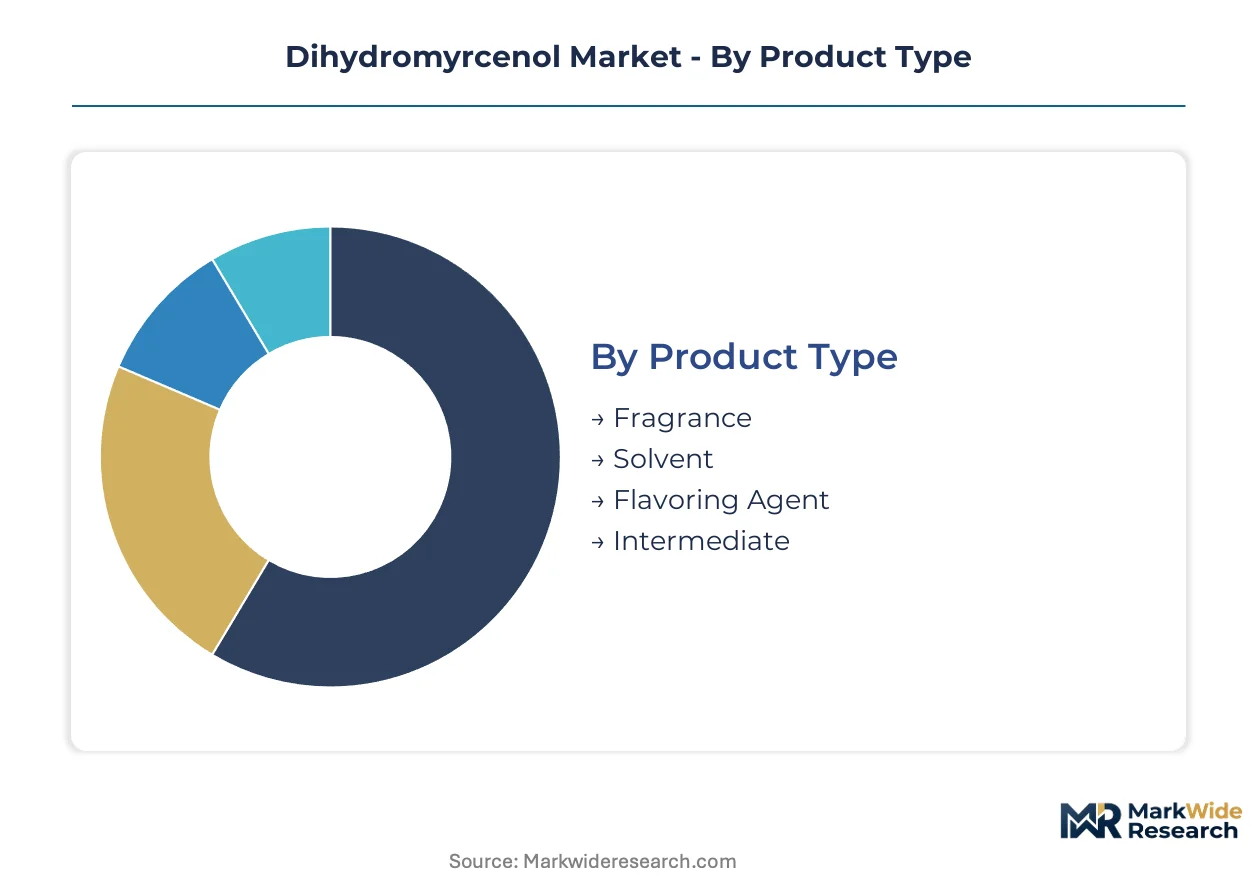
Dihydromyrcenol procurement patterns diverge sharply between embedded fragrance systems and standalone industrial solvent applications. Segmentation reveals how regulatory pressure and supply chain configuration reshape margin capture across personal care, food-grade cleaning, and chemical intermediate channels.
Product Type:
Integration depth varies dramatically: fragrance and solvent grades operate as standalone finished inputs, while intermediates embed deeper in multi-step synthesis chains.
- Fragrance:High-purity terpenoid alcohol meeting IFRA standards for fine perfume and functional fragrance compounding. Western European fine fragrance houses in Grasse and Geneva drive specification tightening for biodegradable nitro-musk replacements under ECHA REACH authorization protocols.
- Solvent:Low-toxicity volatile organic compound exempt carrier for food-grade and industrial cleaning formulations. Food producers in the Netherlands and chemical compounders in Switzerland accelerate direct procurement outside traditional fragrance house distribution layers.
- Flavoring Agent:Food-grade terpenoid alcohol for beverage and confectionery applications requiring FEMA GRAS or EFSA clearance.
- Intermediate:Feedstock for downstream terpenoid synthesis in agrochemical and pharmaceutical manufacturing.
Volume placements concentrate in Fragrance; the faster expansion belongs to Solvent.
Application:
Cost tier stratification separates premium personal care formulations from commodity industrial cleaning, with household products occupying a mid-tier functional positioning.
- Personal Care:Fine fragrances, deodorants, and skin care formulations leveraging dihydromyrcenol's fresh citrus-floral odor profile. EMA cosmetic ingredient guidelines and tightening allergen labeling thresholds in France and Germany accelerate qualification of safer, well-documented alternatives.
- Industrial Use:Food-grade equipment cleaning and chemical process solvents benefiting from EPA TSCA Section 5 premanufacture notice pathways for low-toxicity carriers.
- Household Products:Laundry detergents, surface cleaners, and air care formulations requiring cost-competitive fragrance performance.
- Food & Beverage:Limited direct flavor applications constrained by stringent FEMA GRAS and EFSA safety dossier requirements.
Personal Care commands the dominant value share; Industrial Use is gaining share fastest on regulatory tailwinds.
End User:
Customer type fragmentation distinguishes between formulation-integrated buyers and specification-driven procurement offices.
- Cosmetic Manufacturers:Fine fragrance houses and personal care formulators requiring REACH-registered, IFRA-compliant terpenoid alcohol with full toxicology documentation. DSM-Firmenich AG and Givaudan SA maintain captive supply relationships or dedicated regulatory affairs teams for dossier navigation.
- Chemical Companies:Industrial solvent buyers prioritizing regulatory documentation speed and EPA TSCA compliance over brand heritage.
- Food Producers:Cleaning formulation departments seeking food-grade solvent alternatives with rapid qualification timelines.
- Retailers:Private-label fragrance and household product marketers with limited technical specification capability.
Cosmetic Manufacturers anchor volume commitments; Chemical Companies show the steepest procurement acceleration.
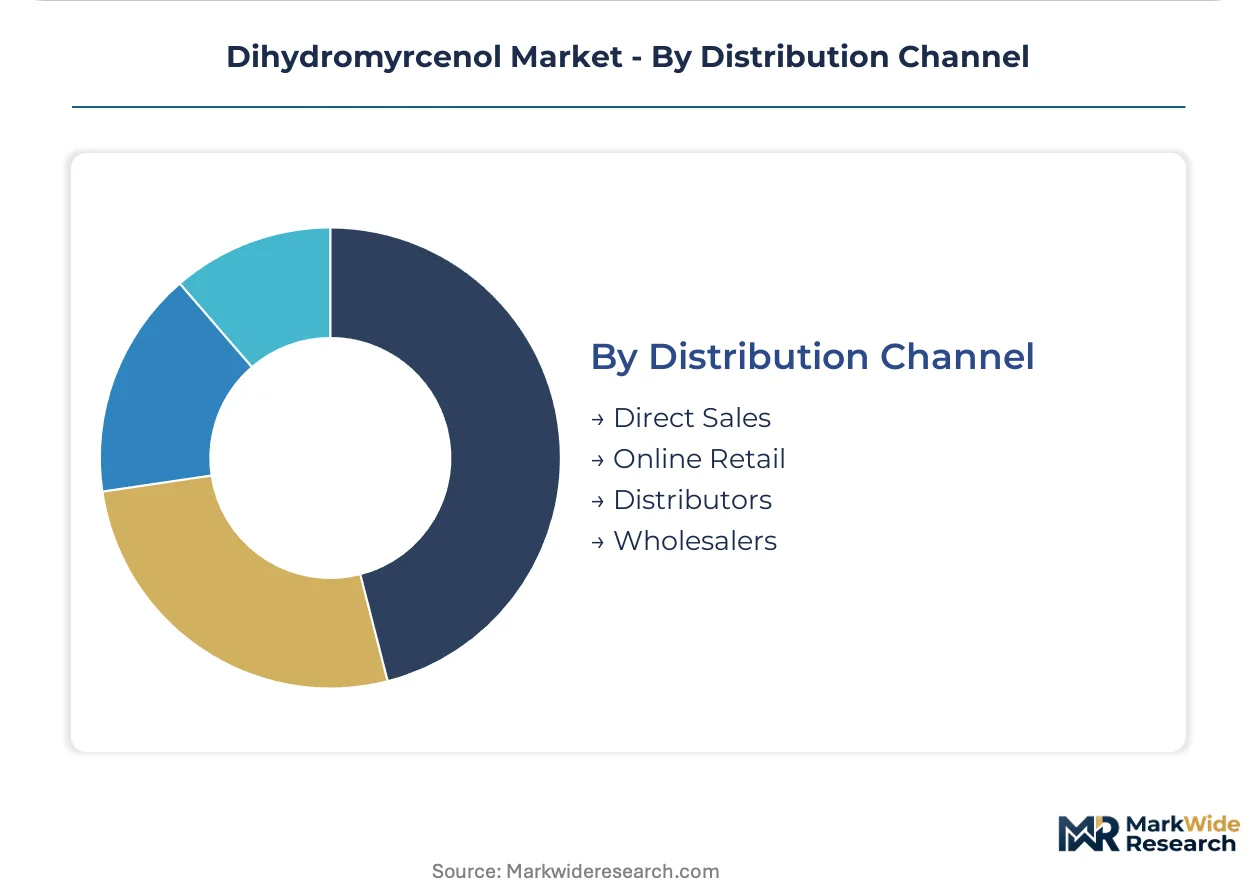
Distribution Channel:
Supply concentration patterns favor direct relationships for volume buyers, while fragmented channels serve smaller formulation accounts.
- Direct Sales:Long-term supply contracts between dihydromyrcenol manufacturers and major fragrance houses or industrial compounders. Takasago International Corporation leverages asymmetric catalysis expertise to anchor direct procurement relationships.
- Distributors:Regional chemical distributors serving mid-scale personal care and household product formulators with inventory and technical support.
- Online Retail:Limited to small-volume laboratory and specialty chemical procurement with minimal regulatory documentation.
- Wholesalers:Bulk commodity handling for industrial solvent applications with standardized specification requirements.
Direct Sales capture the largest volume flows; Distributors face margin compression from channel fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse's fragrance chemical cluster in southeastern France concentrates European terpenoid alcohol production capacity under EU Green Deal-aligned tax incentives for sustainable chemistry.
France
Fine fragrance houses in Grasse drive specification tightening for biodegradable nitro-musk replacements. ECHA REACH authorization protocols filter supplier qualification toward dossier-capable producers. The Provence-Alpes-Côte d'Azur region anchors reformulation activity as perfume houses accelerate substitution timelines.
Germany
Industrial chemical compounders in Leverkusen and Ludwigshafen expand direct procurement of low-toxicity solvent carriers. EMA cosmetic ingredient guidelines compress formulation flexibility for personal care applications. The North Rhine-Westphalia chemical corridor concentrates backward-integrated feedstock control among established producers.
Switzerland
Geneva-based fragrance headquarters prioritize regulatory documentation speed over brand heritage in supplier selection. Swissmedic alignment with EMA thresholds accelerates qualification of safer alternatives. The Basel-Zurich corridor houses dedicated regulatory affairs teams navigating multi-jurisdictional dossier preparation.
Netherlands
Food producers in Rotterdam and Amsterdam establish supply contracts for food-grade cleaning formulations outside traditional fragrance channels. EPA TSCA Section 5 premanufacture notice pathways qualify low-toxicity carriers for industrial applications. The Randstad logistics hub enables rapid regulatory documentation exchange with North American buyers.
United States
Flavor and fragrance compounders in New Jersey and Ohio seek EPA-compliant volatile organic compound exempt carriers for industrial cleaning. TSCA Section 5 notification timelines compress procurement decisions toward pre-qualified suppliers. The Mid-Atlantic chemical belt fragments traditional distribution layers through direct manufacturer relationships.
Dihydromyrcenol Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across fragrance intermediate supply. The vendor base organizes around three tiers: integrated fragrance houses with captive biotechnology capabilities, independent terpenoid specialists with asymmetric catalysis expertise, and regional compounders serving industrial solvent channels. Strategic moves concentrate on M&A for regulatory infrastructure and capacity expansion in fermentation-based production routes.
Within the integrated tier, DSM-Firmenich AG and Givaudan SA exemplify archetypes combining captive supply control with dedicated regulatory affairs capabilities. Takasago International Corporation occupies a distinct position through catalysis-focused specialization. These three anchors represent divergent pathways to margin defense: biotechnology convergence, dossier navigation infrastructure, and process chemistry expertise respectively.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Takasago International Corporation |
| Givaudan SA |
| Privi Speciality Chemicals Limited |
| DRT |
| International Flavors & Fragrances Inc. |
| MANE Group |
| Aurochemicals |
| Symrise AG |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap terpenoid specialists in southeastern France and western Germany anchor supply discipline through multi-generational feedstock relationships, translating agricultural input stability into contract pricing power that resists spot-market volatility. This ownership pattern concentrates margin defense among established producers while squeezing price flexibility for distributors caught between REACH compliance costs and industrial buyer demands for documentation speed.
Pricing Analysis
Short lead-time premiums command substantial markups in fine fragrance channels where Grasse-based houses reformulate classic accords on accelerated timelines. Three-tier pricing structure across IFRA-certified premium, standard fragrance grade, and economy solvent tiers separates specification levels, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier intensifies because food-grade cleaning buyers prioritize regulatory documentation speed over brand heritage. Chemical compounders in Switzerland and the Netherlands exhibit the highest price sensitivity, while captive supply relationships at integrated fragrance houses insulate them from spot fluctuations.
Supply Chain Analysis
Direct-to-fragrance-house channels handle high-purity terpenoid demand, while distributor networks serve mid-scale personal care formulators requiring inventory and technical support. Geographic supply concentration centers on France, Germany, and Switzerland, with the Provence-Alpes-Côte d'Azur region hosting backward-integrated feedstock control. Raw material dependencies draw from turpentine-derived myrcene, citral derivatives from citrus processing, and emerging fermentation-based terpenoid feedstocks. Single-source vulnerability runs through Southeast Asian pine harvest cycles that interrupt acid-catalyzed hydration routes. Distribution runs through long-term supply contracts for volume buyers, with regional chemical distributors serving fragmented smaller accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization costs and multi-standard certification timelines are consolidating supplier relationships around established producers with dedicated toxicology infrastructure, forcing weaker compounders toward exit or acquisition. This consolidation dynamic favors dossier-capable incumbents with backward-integrated feedstock control.
For Market Incumbents: Deepen captive biotechnology capabilities to secure fermentation-based terpenoid production independent of agricultural feedstock volatility. Expand asymmetric catalysis capacity in the North Rhine-Westphalia chemical corridor to anchor direct procurement relationships with industrial solvent buyers. EMA cosmetic allergen threshold tightening threatens formulation flexibility at downstream customers, creating demand pull for well-documented alternative supply. For New Entrants and Emerging Players: Food producers seeking food-grade cleaning formulations outside traditional fragrance house distribution layers represent the most penetrable buyer archetype. Target direct supply relationships with Rotterdam and Amsterdam-based cleaning formulation departments that prioritize EPA TSCA Section 5 documentation speed over brand heritage. A regulatory-first go-to-market angle emphasizing rapid dossier preparation capabilities bypasses entrenched fragrance intermediate channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale terpenoid specialists in Germany with stranded citral derivative hydrogenation capacity and incomplete REACH registration portfolios. Long-term viability across the analysis window hinges on biotechnology convergence and regulatory affairs infrastructure that mid-caps cannot self-fund. The signal to watch is ECHA fragrance allergen labeling threshold announcements that trigger reformulation mandates and raw material requalification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive myrcene supply from turpentine processing insulates DSM-Firmenich AG from Southeast Asian harvest interruptions. |
| Green Manufacturing Transition | Enzymatic hydration routes align Takasago International Corporation with EU Green Deal chemistry incentives in Grasse. |
| Long-term Supply Agreement | Direct contracts with Swiss chemical compounders fragment traditional fragrance house intermediation layers. |
| Regulatory Infrastructure Acquisition | Dedicated toxicology teams at Givaudan SA compress ECHA dossier preparation timelines for novel substance notification. |
| Capacity Expansion | Fermentation-based terpenoid production builds supply routes independent of pine harvest cycle volatility. |
Methodological Framework
Document review covered ECHA REACH authorization protocols, EMA cosmetic ingredient guidelines, EPA TSCA Section 5 premanufacture notices, and trade data from French and German chemical industry associations, complemented by interviews with fragrance house procurement directors, regulatory affairs leads at terpenoid manufacturers, industrial solvent buyers at food producers, and technical R&D directors at asymmetric catalysis specialists. Bottom-up volume modeling from application-level consumption patterns triangulated against top-down value estimates from producer revenue disclosures.
Historical capacity utilization and price formation patterns cross-referenced against expert panel input on reformulation timelines and regulatory threshold evolution. Segmentation dimensions modeled include product purity grade, end-use application channel, customer integration depth, and regional regulatory cluster. CAGRs derived from trend extrapolation adjusted for substitution elasticity and compliance cost pass-through assumptions, with biotechnology adoption curves and REACH registration completion rates as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA fragrance allergen threshold revisions, fermentation-based terpenoid production cost curves, and Southeast Asian pine harvest disruptions. Forecasts reflect assumptions around regulatory timeline stability and feedstock substitution elasticity without claiming predictive certainty. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Diethyl Ether Market
Solvents
Global 2-Ethoxyethanol Market
Solvents
Acetone Market
Solvents
6-Xylenol Market
Solvents
Dihydromyrcene Market
Solvents
2-Phenylethanol Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Hydrocarbon Solvents Market
Solvents
Japan Acetonitrile Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Aliphatic Solvents Market
Solvents
Global Glycidol Market
Solvents
Asia-Pacific Ethane Market
Solvents
Methyl Formate Market
Solvents
Benzyl Alcohol Market
Solvents
Ketone-Based Solvents Market