
 2-Butanone Market | 2026-2036
2-Butanone Market Size, Share, and Industry Trends Forecast 2026-2036
2-Butanone Market Analytics
ISO 9001 quality management certification is rotating as a baseline gate for supplier qualification across the 2-butanone value chain, filtering out smaller traders from direct supply relationships with multinational formulators. Mitsubishi Chemical Corporation leverages captive butanol feedstock and integrated dehydrogenation capacity to sustain cost leadership across Northeast Asian supply corridors. Eastman Chemical Company anchors its position through specialized pharmaceutical-grade purification trains that serve FDA-regulated drug manufacturing clients. BASF SE competes on backward integration into acetic acid derivatives and controlled logistics networks spanning the Rhine-Ruhr industrial cluster.
2-Butanone, commonly designated methyl ethyl ketone or MEK, is a four-carbon aliphatic ketone produced industrially through the dehydrogenation of secondary butanol over copper or zinc oxide catalysts at temperatures near 400°C, yielding a colorless liquid with a flash point of approximately -9°C and solubility parameter matched to a broad range of resins and polymers. Its primary commercial purpose centers on dissolution and viscosity reduction in coatings, adhesives, and extraction processes where fast evaporation rates and moderate polarity prove functionally essential. Solvent-grade material still occupies the dominant volume position, though pharmaceutical-grade specifications now capture the thickest margin pools as regulatory purity thresholds tighten across drug manufacturing jurisdictions. The automotive end-user segment leads absolute consumption through OEM refinishing and component bonding applications, while electronics-grade demand concentrates in semiconductor wafer cleaning and photoresist stripping workflows.
EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants framework constrain US manufacturing site emissions and product labeling requirements, while REACH registration obligations in Europe mandate full toxicological dossiers for continued import and domestic production above one-tonne thresholds. China's Ministry of Ecology and Environment enforces dual carbon goals that are tightening energy intensity benchmarks for butanol dehydrogenation units, pressuring older coal-based feedstock routes. Stakeholders must monitor how divergent carbon accounting methodologies across these three regulatory zones reshape landed cost competitiveness and determine where incremental capacity investments can secure long-term supply contracts.
Market Dynamics
Regulatory fragmentation across major industrial jurisdictions is forcing producers to maintain parallel compliance architectures, elevating fixed cost structures while compressing margins on commodity-grade material.
Growth Catalysts
- REACH registration thresholds:European formulators now demand full toxicological dossiers above one-tonne import volumes, filtering out non-compliant traders and consolidating volume with certified producers.
- Adhesive manufacturing expansion:China's packaging and construction sectors pull solvent-grade material at accelerating rates for hot-melt and pressure-sensitive formulations.
- Butanol dehydrogenation catalyst advances:Copper-zinc oxide systems with improved selectivity are reducing energy intensity per tonne of MEK output.
Market Restraints
- Secondary butanol feedstock volatility:Crude oil price swings transmit directly into naphtha-derived butanol costs, squeezing dehydrogenation unit economics.
- Northeast Asian supply concentration:Integrated producers with captive butanol supply dominate export flows, leaving merchant buyers exposed to allocation decisions.
- Aqueous coating substitution:Waterborne acrylic and polyurethane systems are capturing share in architectural applications where slow evaporation is acceptable.
Strategic Opportunities
- Pharmaceutical-grade purification:FDA-regulated drug manufacturing clients pay substantial premiums for material meeting USP monograph specifications.
- Semiconductor wafer cleaning:Electronics-grade demand concentrates in South Korea and Taiwan for photoresist stripping and precision substrate preparation.
- India's specialty chemicals PLI scheme:Domestic production incentives for downstream derivatives create captive MEK absorption potential.
Industry Challenges
- ISO 9001 certification timelines:Smaller traders face 12-18 month qualification periods to regain direct supply relationships with multinational formulators.
- Dual carbon compliance costs:China's Ministry of Ecology and Environment benchmarks are pressuring older coal-based feedstock routes toward costly retrofit or shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Butanone Market |
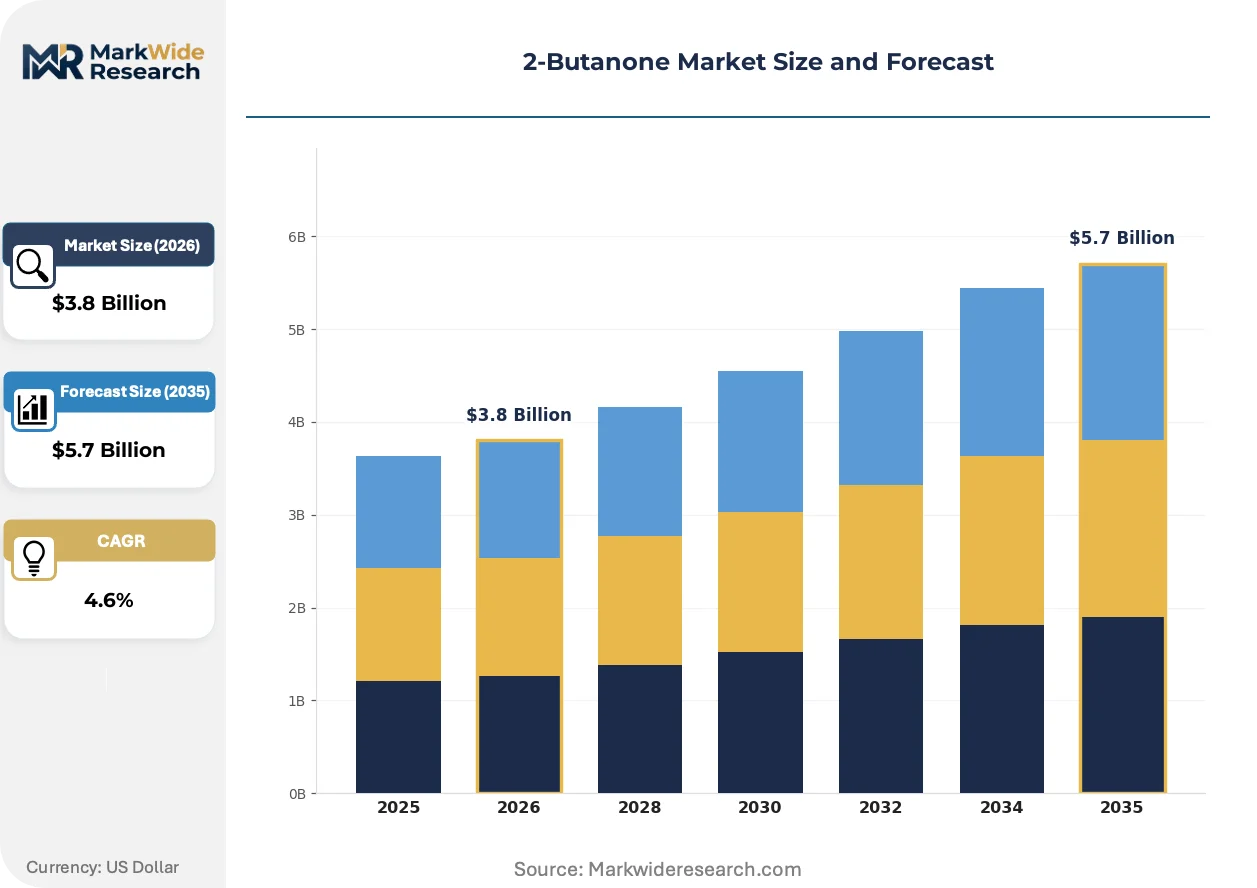
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Grade, Industrial Grade, Pharmaceutical Grade, Analytical Grade Application: Paints, Coatings, Adhesives, Plastics End User: Manufacturing, Automotive, Aerospace, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Mitsubishi Chemical Corporation, Eastman Chemical Company, BASF SE, Shell, ExxonMobil, Celanese Corporation, Mitsui Chemicals, Inc., Maruzen Petrochemical, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Butanone Market Evolving Landscape
Process intensification and regulatory compliance automation are converging to reshape competitive economics, with differentiation shifting from scale toward specification fidelity and carbon-accounting transparency.
Membrane-based solvent recovery systems are supplanting conventional distillation trains in large coating facilities. Automotive OEM refinishing operations in Germany and Japan are deploying these units to meet volatile organic compound capture mandates. The technology is compressing net solvent consumption per unit of throughput while locking buyers into service contracts with equipment suppliers.
EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants framework now mandate continuous emissions monitoring at US manufacturing sites. Facility operators must install and maintain fenceline detection systems with quarterly reporting obligations. Paint and coating formulators are responding by qualifying suppliers with verified stack emission data, creating documentation barriers for import-dependent traders.
Specification-driven procurement now dominates pharmaceutical and electronics verticals, displacing spot-market purchasing for critical raw materials. Buyers in these segments negotiate multi-year supply agreements with embedded purity guarantees and audit rights. This pattern is most pronounced in FDA-regulated drug manufacturing corridors of New Jersey and North Carolina, where supplier qualification costs exceed six figures per vendor.
2-Butanone Market Segmentation
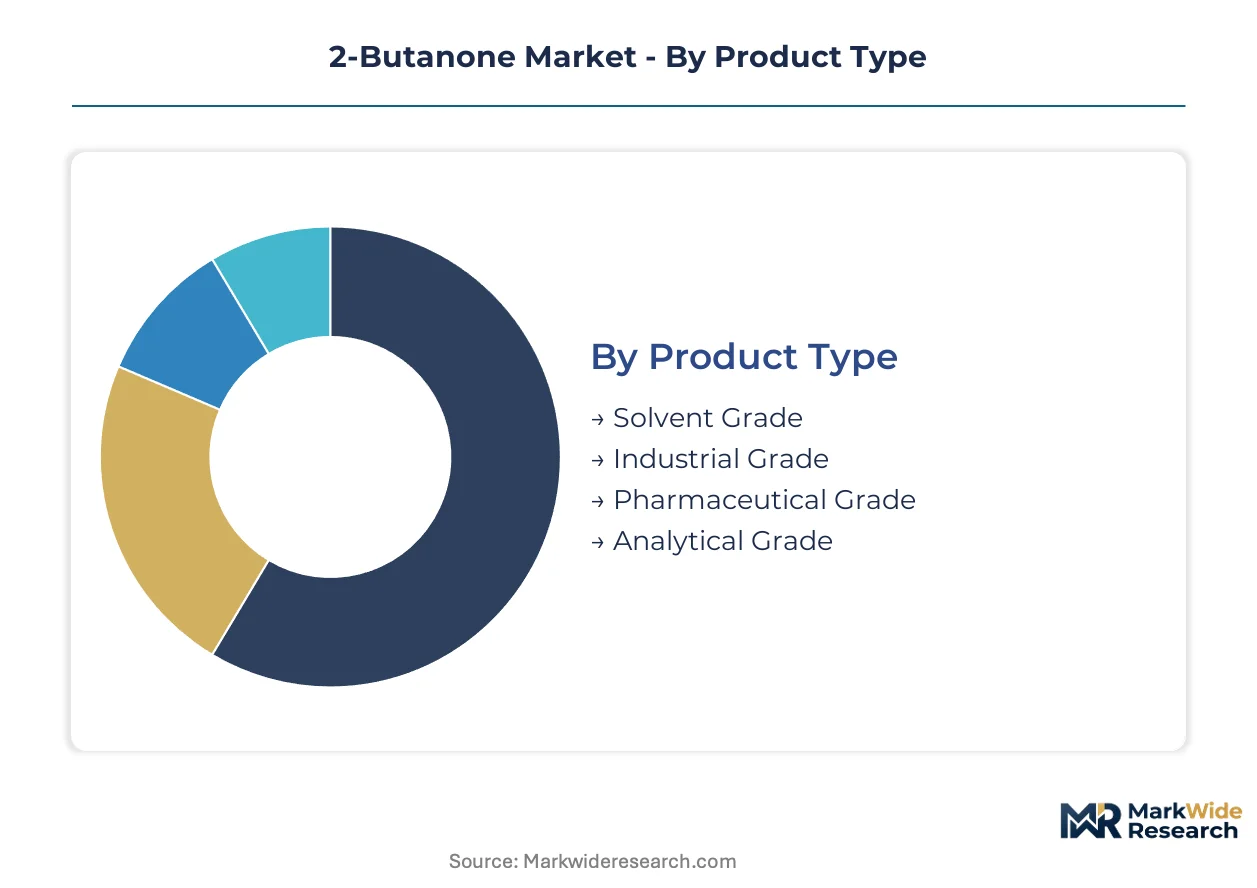
Regulatory purity thresholds and end-use performance requirements fragment the 2-butanone market into sharply differentiated specification tiers. Each segment commands distinct qualification protocols, margin structures, and supply chain access rules that reshape competitive positioning across solvent, pharmaceutical, and electronics corridors.
Product Type:
REACH registration obligations in Europe and FDA monograph requirements in the United States enforce divergent purity standards that stratify producer capabilities and customer access.
- Solvent Grade:Standard industrial specifications with 99% minimum purity serve coatings and adhesive formulations where residual moisture and trace organics are functionally tolerable. China's packaging sector pulls the densest volume flows for hot-melt and pressure-sensitive bonding applications, though dual carbon energy benchmarks are pressuring coal-based dehydrogenation routes.
- Pharmaceutical Grade:USP-compliant purification trains achieve sub-ppm impurity profiles mandatory for FDA-regulated drug manufacturing. New Jersey and North Carolina formulators negotiate multi-year supply agreements with embedded audit rights and six-figure qualification costs per vendor, capturing the thickest margin pools in the value chain.
- Industrial Grade:Intermediate specifications bridge commodity solvent and high-purity applications, typically serving cleaning and extraction processes where moderate purity suffices.
- Analytical Grade:Ultra-high purity for laboratory reference standards and chromatography applications, commanding premium pricing through specialized distribution channels.
Solvent Grade handles the majority of throughput; Pharmaceutical Grade is expanding most quickly on share as regulatory purity thresholds tighten across drug manufacturing jurisdictions.
Application:
Evaporation rate requirements and volatile organic compound exposure limits determine formulation compatibility across coating, bonding, and polymer processing workflows.
- Paints:Fast-drying alkyd and acrylic systems rely on MEK's moderate polarity and flash point near -9°C for viscosity reduction and flow control. German automotive OEM refinishing operations deploy membrane-based solvent recovery to meet fenceline emission mandates, compressing net consumption per unit throughput.
- Adhesives:Hot-melt and pressure-sensitive formulations exploit solubility parameter matching to natural rubber and synthetic elastomers. China's construction and packaging sectors concentrate demand acceleration as domestic adhesive production capacity expands.
- Coatings:Industrial protective and decorative finishes balance cure speed with application window, facing substitution pressure from waterborne acrylic systems where slow evaporation is acceptable.
- Plastics:Polymer dissolution and processing aid applications in PVC and acrylic fabrication, with demand tied to extrusion and molding throughput cycles.
Adhesives dominates absolute volume pull; Electronics-facing coating applications are gaining share fastest as semiconductor capital expenditure concentrates in South Korea and Taiwan.
End User:
Specification stringency and procurement scale separate spot-market commodity buyers from qualified-supply contract partners across industrial verticals.
- Manufacturing:Broad industrial solvent consumption spans equipment cleaning, degreasing, and process chemistry, with procurement patterns tracking macro industrial production indices.
- Automotive:OEM refinishing and component bonding operations anchor absolute consumption, with German and Japanese facilities leading volatile organic compound capture technology deployment.
- Aerospace:Mil-spec and OEM-qualified material for composite fabrication and surface preparation, with qualification timelines extending 18-24 months for new supplier entry.
- Electronics:Semiconductor wafer cleaning and photoresist stripping demand electronics-grade specifications with sub-ppb metallic impurity limits. South Korean and Taiwanese foundries concentrate the fastest-expanding demand corridor as advanced node production scales.
Manufacturing absorbs the widest volume base; Electronics is climbing the fastest on specification-driven contract migration away from spot purchasing.
Distribution Channel:
Documentation burdens and certification requirements filter channel access, with ISO 9001 qualification rotating as a baseline gate for direct supply relationships.
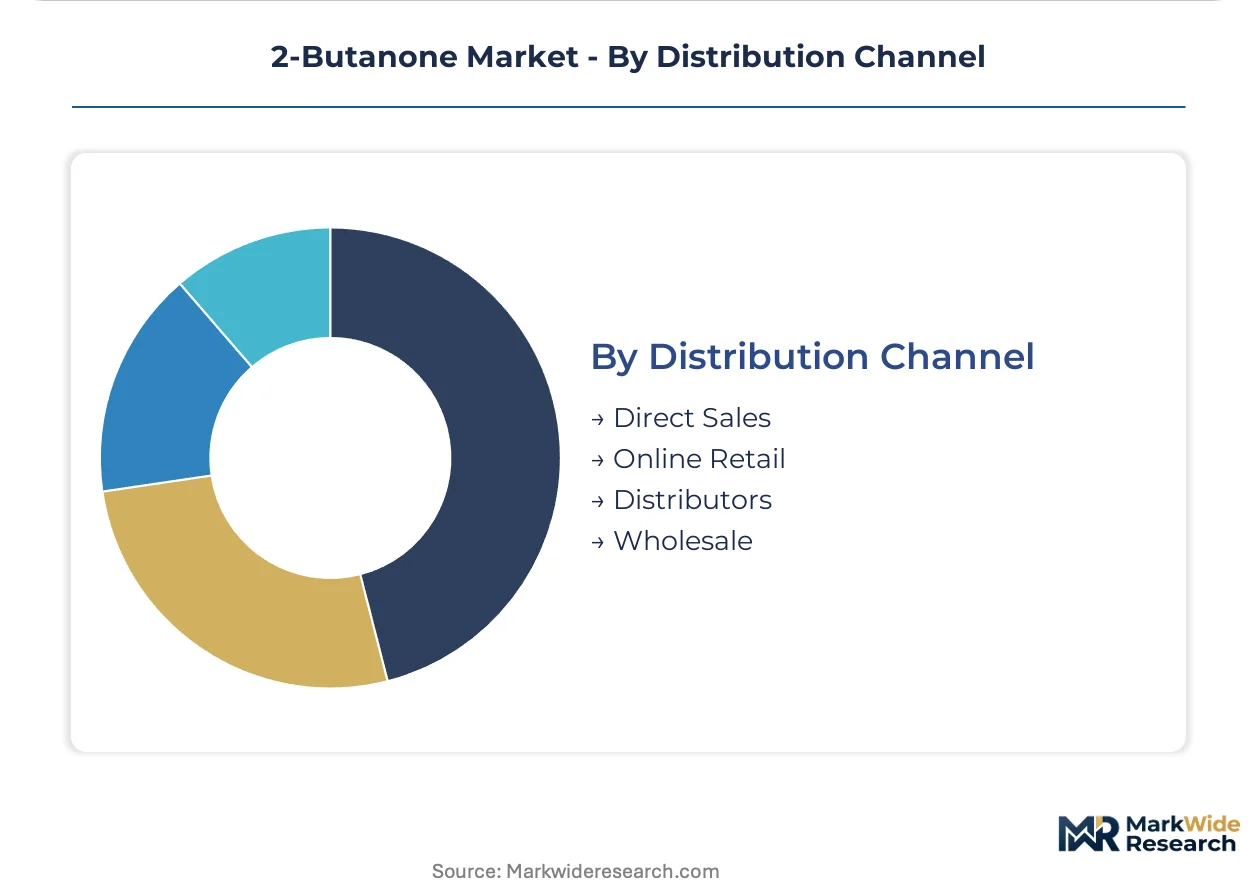
- Direct Sales:Multinational formulators in FDA-regulated corridors negotiate multi-year agreements with embedded purity guarantees and quarterly audit rights, bypassing intermediaries to secure specification fidelity.
- Distributors:Regional chemical distributors maintain qualified supplier networks and local inventory positions for mid-tier manufacturers lacking direct procurement scale.
- Wholesale:Volume aggregation for commodity-grade material serving smaller coating and adhesive compounders with standardized specifications.
- Online Retail:Emerging channel for analytical grade and small-volume industrial orders, constrained by hazardous material shipping regulations and documentation requirements.
Direct Sales commands the highest value throughput; Online Retail is gaining share fastest as digital procurement platforms penetrate laboratory and small-batch manufacturing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon targets and India's PLI scheme for specialty chemicals are redirecting investment flows across Asian supply corridors. European REACH enforcement and US EPA fenceline monitoring are elevating compliance costs for cross-border traders. Japanese and South Korean electronics clusters are absorbing specification-grade volumes at premium contract terms.
China
Packaging and construction adhesive manufacturers in the Yangtze River Delta pull solvent-grade material at accelerating rates. The Ministry of Ecology and Environment enforces tightening energy intensity benchmarks for butanol dehydrogenation units. Shandong Province hosts concentrated dehydrogenation capacity where older coal-based feedstock routes face costly retrofit or shutdown decisions.
United States
Automotive OEM refinishing operations and FDA-regulated drug manufacturers in New Jersey anchor pharmaceutical-grade consumption. EPA National Emission Standards for Hazardous Air Pollutants mandate continuous fenceline monitoring with quarterly reporting obligations. The Gulf Coast petrochemical corridor maintains integrated butanol-to-MEK production chains serving domestic coating formulators.
Germany
Automotive refinishing facilities deploy membrane-based solvent recovery systems to meet volatile organic compound capture mandates. ECHA REACH registration obligations require full toxicological dossiers for import volumes above one-tonne thresholds. The Rhine-Ruhr industrial cluster hosts backward-integrated producers with controlled logistics networks spanning coating and adhesive compounders.
India
Domestic adhesive production capacity expansion in Maharashtra and Gujarat creates captive MEK absorption potential. The PLI scheme for specialty chemicals incentivizes downstream derivative manufacturing with local content requirements. Gujarat's chemical manufacturing zones attract investment in purification trains serving pharmaceutical formulation clusters.
South Korea
Semiconductor foundries in the Seoul Capital Area and Busan-Ulsan corridor drive electronics-grade demand for wafer cleaning and photoresist stripping. MFDS alignment with international pharmaceutical purity standards supports contract manufacturing growth. Pyeongtaek and Hwaseong industrial complexes concentrate advanced node production scaling precision substrate preparation workflows.
2-Butanone Market Competitive Landscape
Player mix skews toward integrated petrochemical conglomerates with captive butanol feedstock and regional chemical specialists with specification-grade purification capabilities. Market structure concentrates volume among Northeast Asian producers controlling dehydrogenation capacity and European majors with backward integration into acetic acid derivatives. Two strategic archetypes dominate: scale-driven commodity suppliers competing on energy intensity and margin-capture specialists serving FDA-regulated pharmaceutical corridors. Competitive moves center on catalyst technology licensing for energy efficiency gains and multi-year supply agreements with embedded purity guarantees.
Within the integrated petrochemical tier, Mitsubishi Chemical Corporation exemplifies captive feedstock advantages through Northeast Asian supply corridors. Eastman Chemical Company and BASF SE occupy positions on the specification-grade vector, with the former anchoring pharmaceutical-grade purification capabilities and the latter representing backward-integrated production architecture. These three entities illustrate how feedstock control, regulatory compliance depth, and geographic positioning stratify competitive access across solvent, pharmaceutical, and electronics-grade market tiers.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Eastman Chemical Company |
| BASF SE |
| Shell |
| ExxonMobil |
| Celanese Corporation |
| Mitsui Chemicals, Inc. |
| Maruzen Petrochemical |
| The Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with naphtha-indexed price clauses lock in supply access for multinational coating formulators while insulating buyers from feedstock volatility in China's dual carbon compliance corridors. These structures concentrate pricing power with integrated producers holding captive butanol supply, squeezing merchant buyers exposed to spot allocation decisions.
Pricing Analysis
Cost-plus contracts indexed to naphtha benchmarks dominate solvent-grade transactions, with copper-zinc oxide catalyst efficiency and energy intensity per tonne as secondary adjustment factors. Price differentiation separates pharmaceutical-grade USP-compliant material from standard industrial specifications, with FDA-regulated corridors commanding substantial premiums. Pricing pressure intensifies as waterborne acrylic systems capture architectural coating share where slow evaporation proves acceptable. Spot-market commodity buyers in adhesive manufacturing exhibit highest price sensitivity, while electronics-grade semiconductor clients prioritize specification fidelity over unit cost.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan container terminals fluctuate with regional energy benchmark volatility, compressing landed margins for import-dependent traders. Supply concentrates in China, South Korea, and Japan, with Shandong Province dehydrogenation units and Ulsan petrochemical corridors anchoring Northeast Asian export flows. Feedstock draws from naphtha-derived secondary butanol and coal-based butanol routes, with the latter facing retrofit pressure under MEE dual carbon enforcement. Single-source vulnerability runs through integrated producers controlling captive butanol supply. Distribution runs through direct sales contracts for pharmaceutical-grade material and regional distributors for commodity solvent volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne coating substitution threatens solvent-grade volume pools, demanding that incumbents defend specification-grade positions where performance requirements resist aqueous reformulation.
For Market Incumbents: Secure pharmaceutical-grade purification train capacity in FDA-regulated corridors to capture premium margin pools as regulatory purity thresholds tighten. Lock in multi-year offtake agreements with embedded audit rights to displace spot-market competitors. Backward integration into acetic acid derivatives and controlled Rhine-Ruhr logistics networks reinforces position against merchant traders facing ISO 9001 qualification barriers. For New Entrants and Emerging Players: ISO 9001 certification fast-tracks enable direct supply relationships with multinational formulators filtering out non-compliant traders. Target India's specialty chemicals PLI scheme corridors for downstream derivative absorption, where domestic content requirements create captive MEK demand. Electronics-grade semiconductor wafer cleaning specifications in South Korea and Taiwan offer penetrable white-space for purification specialists. For Investors and Strategic Acquirers: Regional chemical specialists with specification-grade capabilities and established FDA audit relationships represent priority acquisition targets. Long-term viability hinges on carbon-accounting transparency and catalyst technology licensing positions as energy intensity benchmarks tighten across jurisdictions. Monitor MEE enforcement actions on Shandong coal-based feedstock routes as inflection indicator for supply restructuring and consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive butanol supply insulates Mitsubishi Chemical from naphtha volatility across Northeast Asian corridors. |
| Pharmaceutical-Grade Purification Investment | USP-compliant trains capture FDA-regulated premiums in New Jersey and North Carolina drug manufacturing clusters. |
| Long-term Supply Agreement | Multi-year contracts with embedded purity guarantees displace spot purchasing in semiconductor wafer cleaning workflows. |
| Green Manufacturing Transition | Copper-zinc oxide catalyst advances reduce energy intensity per tonne under China's MEE dual carbon benchmarks. |
| Joint Venture | Regional distribution partnerships penetrate India's PLI-incentivized specialty chemicals manufacturing zones. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, ACC/Cefic industry reports, SEC 10-K filings, and regulatory dossier submissions. Bottom-up volume modeling across solvent, pharmaceutical, and electronics-grade tiers triangulated against top-down macro industrial production indices.
Across the analysis window, the forecasting framework segmented by grade tier, end-use industry, packaging format, and regional production hub to isolate specification-driven contract migration patterns. CAGRs derived from energy intensity trajectories, catalyst technology adoption curves, and regulatory compliance cost escalations. Semiconductor capital expenditure cycles and pharmaceutical purity threshold tightening served as industry-specific demand inputs.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement, MEE dual carbon benchmark adherence, and naphtha-butanol price correlation stability; material deviation would warrant model refresh. Specific risk factors include aqueous coating substitution acceleration, coal-based feedstock route shutdowns, and fenceline monitoring cost pass-through failures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Acetone Market
Solvents
Solvent Cement Market
Solvents
Ethyl Acetate Market
Solvents
Aprotic Solvents Market
Solvents
Hydrosol Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Citrus Solvents Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Dibutyl Ether Market
Solvents
Butyl Acetate (BAC) Market
Solvents
Diethanolamine (DEA) Market
Solvents
Solvent Green 7 Market
Solvents
India High Purity Solvents Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Propylene Glycol Ether Market