
 Chromatography Accessories and Consumables Market | 2026-2036
Chromatography Accessories and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatography Accessories and Consumables Market Analysis
Pharma-grade consumable specifications are rotating toward higher purity thresholds and validated batch documentation. Thermo Fisher Scientific leverages its integrated analytical workflow portfolio to sustain premium positioning in regulated laboratories. Merck KGaA anchors its European supply chain with membrane and filtration consumables that integrate directly with chromatography systems. Agilent Technologies differentiates through its cross-platform column chemistries that compete across both liquid and gas chromatography modalities.
Chromatography accessories and consumables encompass columns, filters, tubing, and vials engineered from borosilicate glass, stainless steel, and specialized polymeric substrates with pore sizes ranging from 1.7 to 30 micrometers, functioning to separate, purify, and quantify chemical mixtures in analytical and preparative workflows. Liquid chromatography columns command the largest installed base due to biopharmaceutical peptide and monoclonal antibody analysis, while gas chromatography consumables retain mature demand in environmental testing and petrochemical quality control. Sample preparation applications generate recurring revenue streams through solvent, filter, and vial replacement cycles that outpace capital instrument sales.
FDA current good manufacturing practice standards and EMA analytical procedure guidelines mandate method-specific consumable qualification, forcing laboratories to maintain validated supplier relationships and documented traceability. ISO 17025 accreditation requirements and USP general chapters on chromatography further constrain sourcing flexibility for contract research organizations and quality control laboratories. Stakeholders must monitor evolving pharmacopeial standards and supplier audit burdens as the primary variables shaping procurement strategy and total cost of ownership calculations.
Market Dynamics
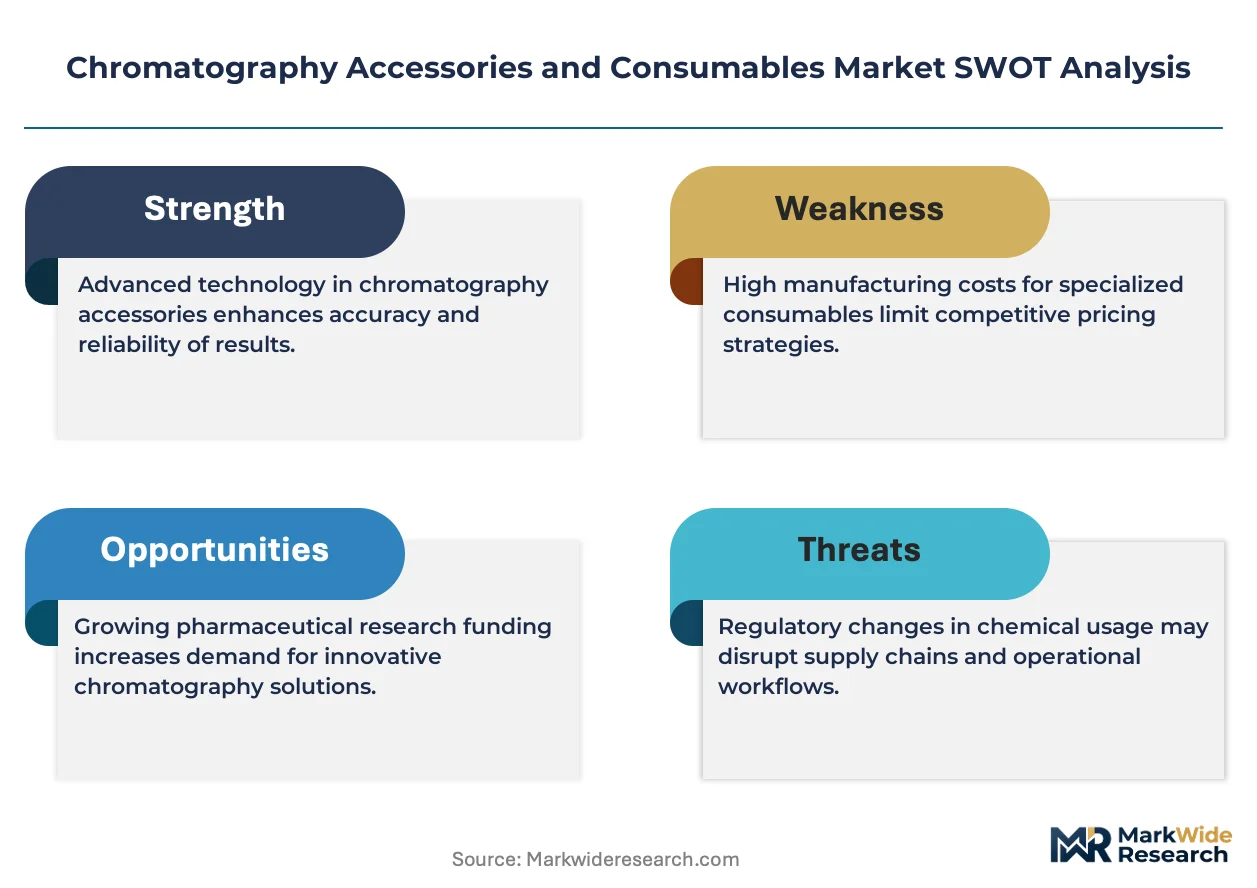
Biosimilar method validation requirements from FDA and EMA are forcing laboratories into documented supplier relationships with traceable batch records, compressing sourcing flexibility and elevating qualification costs across quality control operations.
Growth Catalysts
- EMA biosimilar guidelines:Tightened analytical procedure standards mandate method-specific consumable qualification, locking laboratories into recurring high-purity purchases with validated documentation trails.
- Biopharmaceutical peptide analysis:Liquid chromatography columns capture expanding installed bases as monoclonal antibody manufacturing scales drive column replacement cycles.
- Germany:Concentrated demand for high-performance chromatography columns anchors European procurement volumes and shapes regional supplier prioritization.
Market Restraints
- Borosilicate glass supply concentration:Specialized vial and column substrate manufacturing clusters in select European and Asian supplier networks create input vulnerability.
- ISO 17025 accreditation timelines:Extended laboratory certification cycles delay new consumable vendor onboarding and extend incumbent lock-in periods.
- Gas chromatography maturity:Environmental testing and petrochemical quality control segments show flat replacement velocity compared to biopharma liquid chromatography expansion.
Strategic Opportunities
- China:NMPA regulatory convergence with ICH standards creates openings for Western consumable suppliers with pre-validated documentation systems.
- Preparative workflow integration:Membrane filtration consumables that dock directly with chromatography systems enable bundled procurement contracts.
- Sample preparation automation:Robotic solvent handling and filter placement systems reduce manual intervention and expand recurring filter and vial pull-through.
Industry Challenges
- Analytical method transfer expertise:Shortage of chromatographers capable of executing validated consumable switches between supplier platforms extends project timelines.
- Legacy HPLC system compatibility:Newer sub-2-micron particle columns require pressure-rated hardware upgrades that strain capital allocation in contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatography Accessories and Consumables Market |
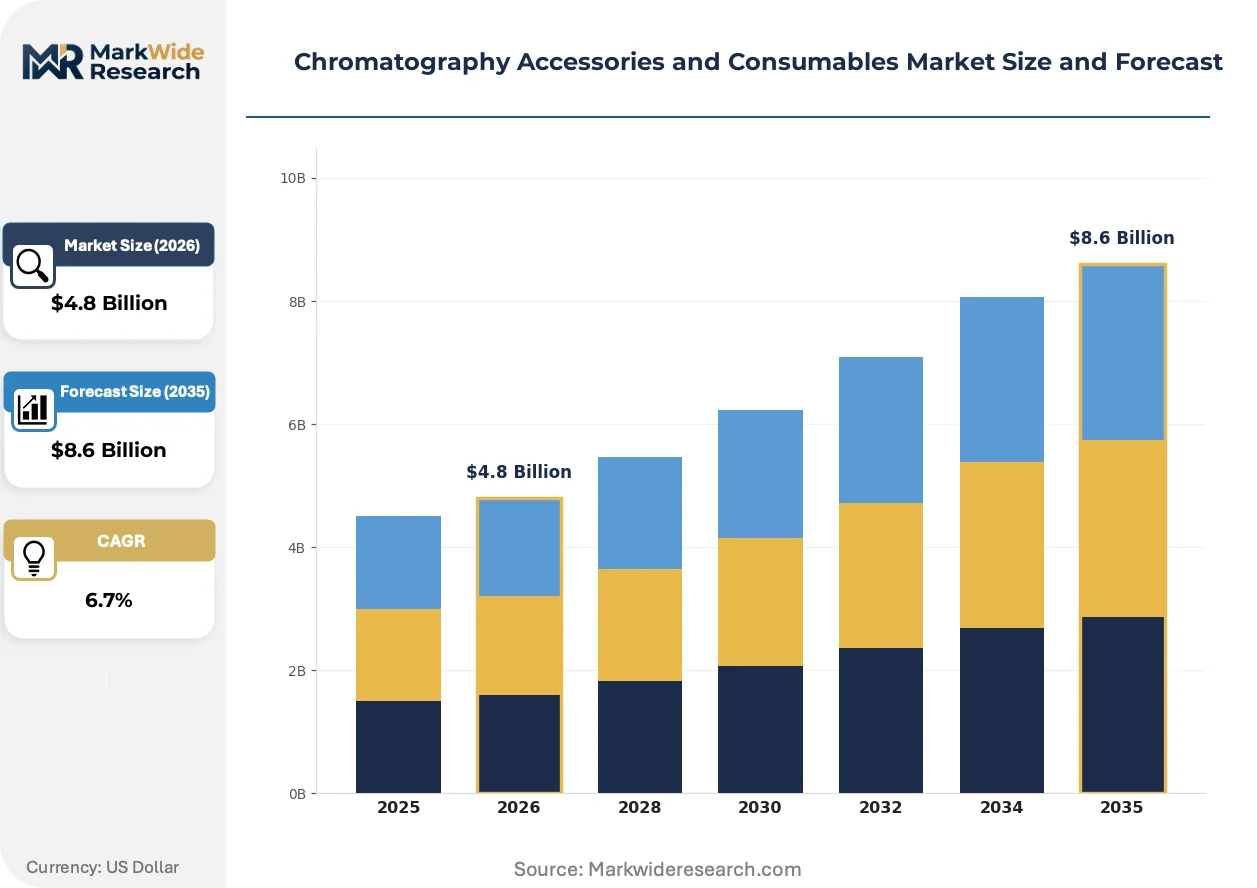
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Columns, Filters, Tubing, Vials Technology: Liquid Chromatography, Gas Chromatography, Ion Chromatography, Supercritical Fluid Chromatography End User: Pharmaceutical, Food & Beverage, Environmental Testing, Research Laboratories Application: Quality Control, Sample Preparation, Method Development, Purification |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Agilent Technologies, Inc., Avantor, Inc., Bio-Rad Laboratories, Inc., Waters Corporation, PerkinElmer Inc., Restek Corporation, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatography Accessories and Consumables Market Emerging Trajectories
Superficially porous particle technology and single-use filtration manifolds are compressing run times and cleaning validation burdens, while digital batch record systems rewire how laboratories document consumable traceability.
Superficially porous particle column packings combine solid core structures with porous outer shells to reduce diffusion path lengths and enable faster separations at lower backpressures. Biopharmaceutical quality control laboratories in the United States and Germany are adopting these substrates for high-throughput peptide mapping workflows. This substrate architecture is supplanting fully porous particles in regulated method development, compressing analytical cycle times and reducing solvent consumption per sample.
EMA analytical procedure guidelines now require documented equivalency demonstrations when switching between consumable lots or suppliers, extending qualification protocols beyond prior notification requirements. Contract manufacturing organizations face expanded audit documentation burdens for column chemistry changes. European quality control laboratories are responding by consolidating supplier portfolios and negotiating multi-year framework agreements with single-source validation packages.
Consolidated procurement platforms are aggregating consumable purchasing across multiple analytical instrument brands, displacing instrument-captive ordering systems. Large pharmaceutical manufacturers in the United States and China are centralizing chromatography consumable buying through group purchasing organizations that negotiate enterprise pricing. This channel shift concentrates negotiating leverage with buyers and pressures traditional distributor margins on filters, vials, and solvents.
Chromatography Accessories and Consumables Market Segmentation
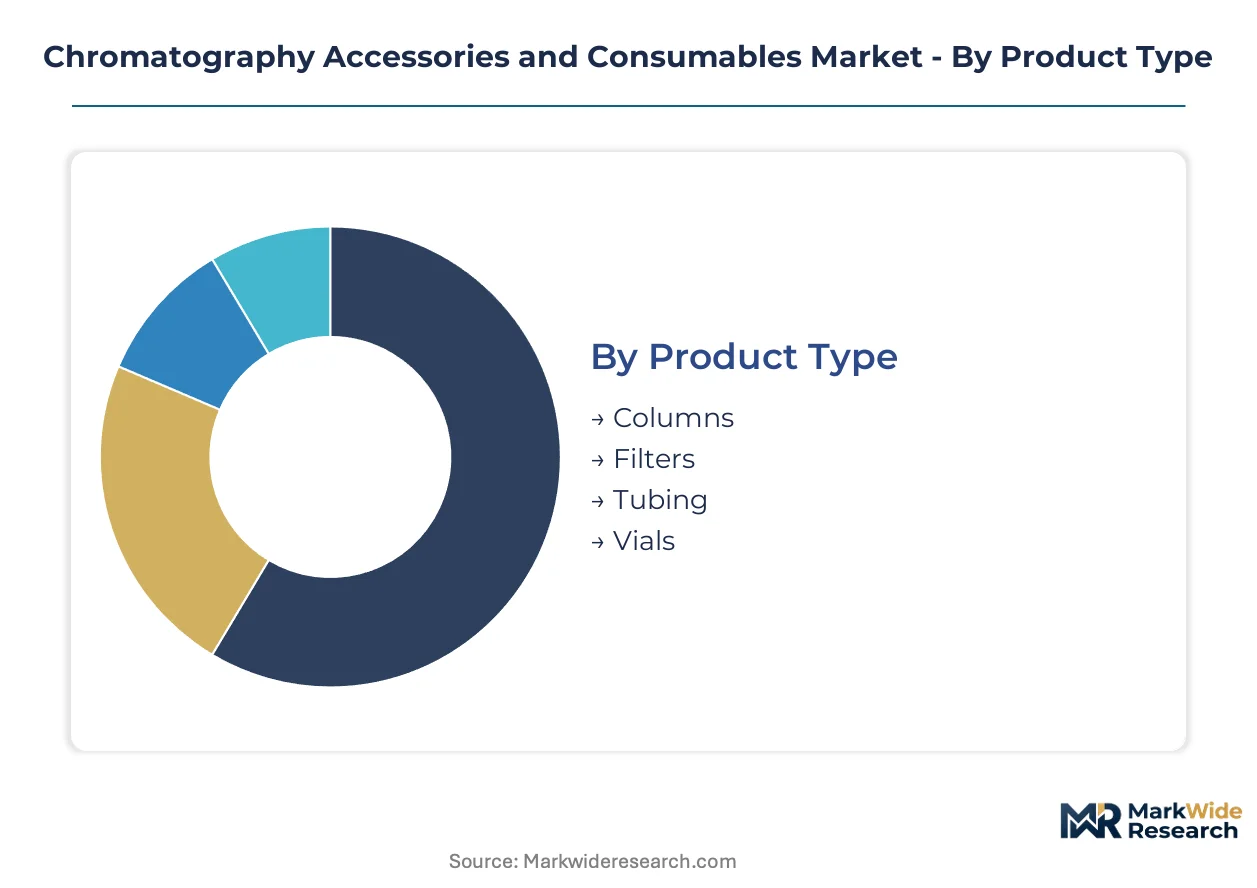
Regulatory qualification requirements fragment procurement patterns across product categories, with validated batch documentation forcing laboratories into segment-specific sourcing strategies. Technology choices lock end-users into consumable ecosystems that resist cross-platform substitution.
Product Type:
FDA and EMA good manufacturing practice standards mandate material-specific qualification protocols that elevate purity thresholds for certain consumable formats.
- Columns:Stainless steel and polymeric substrates with 1.7 to 30 micrometer pore sizes anchor biopharmaceutical peptide mapping workflows. German quality control laboratories concentrate demand for superficially porous particle packings that compress analytical cycle times under tightened EMA analytical procedure guidelines.
- Filters:Membrane filtration consumables integrate directly with chromatography systems to enable bundled procurement contracts. Merck KGaA anchors European supply chains with validated documentation trails that satisfy ISO 17025 accreditation requirements.
- Tubing:Borosilicate glass and specialized polymeric substrates handle solvent delivery under pressure-rated specifications.
- Vials:Engineered borosilicate glass formats support sample containment with documented traceability for contract manufacturing organization audits.
Established volume favors columns; emerging adoption favors filters.
Technology:
Application-specific separation mechanisms concentrate replacement revenue in modalities serving high-throughput regulated workflows.
- Liquid Chromatography:High-performance liquid chromatography columns command the largest installed base due to monoclonal antibody manufacturing scale. United States biopharmaceutical quality control departments expand consumables procurement programs for peptide analysis under FDA biosimilar guidelines.
- Gas Chromatography:Mature environmental testing and petrochemical quality control segments show flat replacement velocity compared to biopharma expansion. Agilent Technologies competes across this modality with cross-platform column chemistries.
- Ion Chromatography:Specialized separation of ionic species serves environmental compliance monitoring and pharmaceutical counterion analysis.
- Supercritical Fluid Chromatography:Emerging chiral separations and complex mixture resolution gain traction in method development laboratories.
Replacement cycles concentrate in liquid chromatography; method development laboratories drive supercritical fluid adoption.
End User:
Customer-type procurement authority shapes contract structures, with centralized purchasing organizations consolidating negotiating leverage.
- Pharmaceutical:Quality control departments and contract manufacturing organizations face expanded audit documentation burdens for consumable lot changes. China concentrates demand as NMPA regulatory convergence with ICH standards creates openings for Western suppliers with pre-validated systems.
- Research Laboratories:Academic and government facilities prioritize cost containment over validated documentation, enabling second-source flexibility.
- Environmental Testing:Regulatory compliance monitoring sustains recurring gas chromatography consumable demand.
- Food & Beverage:Contaminant detection and quality verification drive filter and vial replacement cycles.
Procurement centralization favors pharmaceutical; sourcing flexibility favors research laboratories.
Application:
Workflow positioning determines consumable pull-through velocity, with recurring revenue concentrated in high-frequency operational stages.
- Quality Control:Validated method execution requires locked supplier relationships with traceable batch records. Thermo Fisher Scientific sustains premium positioning through integrated analytical workflow portfolios that satisfy FDA current good manufacturing practice standards.
- Sample Preparation:Solvent, filter, and vial replacement cycles outpace capital instrument sales. Robotic automation systems expand recurring pull-through while reducing manual intervention.
- Method Development:Exploratory consumable switching demands sourcing flexibility that conflicts with qualification requirements.
- Purification:Preparative scale separations integrate membrane filtration with chromatography systems for bundled contracts.
Recurring revenue concentrates in quality control; automation integration favors sample preparation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract research organizations in India and China exhibit the highest price elasticity for chromatography consumables, while FDA-regulated biopharmaceutical manufacturers in the United States and Germany absorb premium pricing for validated batch documentation. This demand-elasticity contrast shapes regional procurement strategies and supplier prioritization across quality control operations.
United States
Biopharmaceutical quality control departments drive column replacement cycles through expanded monoclonal antibody manufacturing. FDA biosimilar guidelines mandate method-specific consumable qualification with traceable documentation trails. The Boston-Cambridge biotech cluster concentrates demand for superficially porous particle packings in high-throughput peptide mapping workflows.
Germany
European quality control laboratories anchor procurement volumes for high-performance chromatography columns under tightened EMA analytical procedure standards. ISO 17025 accreditation requirements extend vendor onboarding timelines and reinforce incumbent supplier relationships. The Rhine-Main metropolitan region hosts centralized purchasing organizations negotiating multi-year framework agreements with single-source validation packages.
China
NMPA regulatory convergence with ICH standards creates procurement openings for Western consumable suppliers with pre-validated documentation systems. Domestic biopharmaceutical manufacturing scale drives liquid chromatography column demand. The Yangtze River Delta biotech corridor concentrates quality control laboratory expansion and consumables procurement centralization.
India
Contract research organizations and generic pharmaceutical manufacturers prioritize cost containment over validated documentation, enabling second-source flexibility for filters and vials. CDSCO manufacturing standards are tightening analytical method validation requirements for export-oriented facilities. The Hyderabad-Visakhapatnam pharmaceutical belt concentrates environmental testing and quality control laboratory operations.
Japan
PMDA pharmaceutical manufacturing standards sustain demand for high-purity consumables with documented traceability in biopharmaceutical quality control. Method development laboratories drive adoption of emerging chromatography modalities including supercritical fluid chromatography. The Kansai region's analytical instrumentation cluster shapes regional supplier relationships and technology adoption patterns.
Chromatography Accessories and Consumables Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the chromatography accessories and consumables market. Integrated analytical workflow portfolios command premium positioning in regulated laboratories, while specialized consumable fabricators compete on volume and replacement cycle velocity. Three archetypes dominate: diversified life science conglomerates with captive distribution, pure-play consumable specialists with regional manufacturing density, and analytical instrument manufacturers with instrument-captive consumable ecosystems. M&A activity concentrates supplier portfolios, while multi-year framework agreements with validated documentation packages lock in recurring revenue streams.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify integrated portfolio strategies that bundle consumables with analytical instrumentation and workflow software. Agilent Technologies, Inc. occupies a distinct position bridging instrument manufacturing and cross-platform column chemistries. These three entities anchor competitive dynamics through their validated documentation capabilities and established relationships with FDA-regulated and EMA-regulated quality control operations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Agilent Technologies, Inc. |
| Avantor, Inc. |
| Bio-Rad Laboratories, Inc. |
| Waters Corporation |
| PerkinElmer Inc. |
| Restek Corporation |
| Shimadzu Corporation |
| Others |
Supply Flow & Price Mechanics
Specialized borosilicate glass furnace capacity in Germany and China shapes both supply concentration and price floors for chromatography consumables. Scale economies in validated batch documentation systems lock smaller fabricators out of premium tiers while concentrating procurement leverage among multi-site pharmaceutical manufacturers.
Pricing Analysis
FDA current good manufacturing practice standards dictate the pricing tier structure across chromatography accessories and consumables. Three-tier pricing structure across premium, standard, and economy levels separates validated documentation packages from basic laboratory grades. Price differentiation hinges on ISO 17025 accreditation status and EMA analytical procedure guideline compliance. Cost compression in economy-tier filters and vials is intensifying because contract research organizations in India prioritize cost containment over traceability. Research laboratories exhibit highest price sensitivity; FDA-regulated biopharmaceutical manufacturers absorb premium positioning.
Supply Chain Analysis
Germany and China anchor specialized substrate manufacturing for chromatography columns and borosilicate glass vials. European supply chains draw from concentrated borosilicate glass furnace networks and stainless steel tubing fabrication clusters. Single-source vulnerability concentrates in membrane filtration consumables where Merck KGaA anchors validated documentation trails. Distribution runs through instrument-captive channels and consolidated group purchasing organizations that negotiate enterprise pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates defensive moats in chromatography consumables, as FDA and EMA qualification requirements lock laboratories into validated supplier relationships with documented traceability.
For Market Incumbents: Fortify documentation capabilities and multi-year framework agreements to defend against emerging pure-play consumable specialists. Expand backward integration into borosilicate glass substrate production to reduce input vulnerability from European furnace concentration. Prioritize certification investment for ISO 17025-accredited batch record systems that extend incumbent lock-in periods. For New Entrants and Emerging Players: Service-layer gaps in automated sample preparation consumables present white-space targets where incumbents under-serve mid-tier contract research organizations. Target China's NMPA-regulated quality control laboratories as the most penetrable geography given regulatory convergence with ICH standards. Pursue direct-to-laboratory digital procurement platforms as the primary go-to-market angle to bypass established distributor margins. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among consumable specialists with validated documentation packages and instrument-captive ecosystems. Long-term viability favors acquisition targets with membrane filtration integration capabilities and pre-qualified supplier status under EMA analytical procedure guidelines. Watch for NMPA regulatory enforcement intensity as the signal indicating inflection in Western supplier penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Framework Agreement | Locks pharmaceutical manufacturers into single-source validation packages under EMA guidelines. |
| Backward Integration into Substrates | Captive borosilicate glass production reduces supply vulnerability from European furnace concentration. |
| Sample Preparation Automation | Robotic solvent handling expands recurring filter and vial pull-through in quality control workflows. |
| Regulatory Documentation Investment | Pre-validated batch record systems satisfy FDA biosimilar method validation requirements. |
| Digital Procurement Platform Launch | Direct-to-laboratory channels displace instrument-captive ordering systems and distributor margins. |
Methodological Framework
Operator-level perspectives from quality control laboratory managers, regulatory affairs specialists at contract manufacturing organizations, chromatography instrument procurement leads, and membrane filtration R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 483 observation databases, EMA inspection reports, USP general chapter documentation, and ISO 17025 accreditation registries. Bottom-up consumable volume estimates triangulated against top-down biopharmaceutical manufacturing capacity expansion data.
Sensitivity analysis tested forecast outputs against variable regulatory enforcement intensity and biopharmaceutical capital expenditure cycles across the projection horizon. Segmentation dimensions modeled include product type, technology modality, end-user procurement authority, and application workflow positioning. CAGRs derived from replacement cycle velocity analysis and validated supplier relationship tenure data. Industry-specific inputs incorporated monoclonal antibody manufacturing scale projections and NMPA regulatory convergence timelines.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA regimes; material policy shifts would require re-modeling qualification burden trajectories and supplier audit documentation requirements. Specific risks include borosilicate glass supply disruption, ISO 17025 accreditation timeline extensions, and biosimilar guideline tightening beyond current analytical procedure standards. Recalibration cycles align with material shifts in regulatory enforcement patterns and biopharmaceutical manufacturing capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Hydrometer Market
Testing Equipment
Viscometer Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market