
 High Purity Solvents Market | 2026-2036
High Purity Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Solvents Market Outlook
The capital-intensity divergence between integrated petrochemical majors and specialized solvent refiners is unwinding traditional competitive boundaries. BASF SE leverages its Ludwigshafen Verbund site to sustain backward integration into acetonitrile and tetrahydrofuran feedstocks. Thermo Fisher Scientific anchors North American laboratory demand through its Fisher Chemical portfolio, while Merck KGaA dominates ultra-high-purity grades for European pharmaceutical chromatography.
High purity solvents are organic liquids refined to sub-ppm impurity levels, typically achieving water content below 0.01% and particulate filtration to 0.2 microns for semiconductor and analytical applications. Their primary purpose centers on eliminating contaminant interference during pharmaceutical quality testing, electronics wafer processing, and high-performance liquid chromatography. The grade dimension shows HPLC and ultra-pure categories commanding the deepest margin pools as semiconductor nodes shrink below 7nm. Application demand in electronics outpaces chemical synthesis, where aromatics and ketones face substitution pressure from aqueous cleaning systems.
EPA standards under the Clean Air Act and OSHA permissible exposure limits constrain solvent volatility and worker safety protocols in U.S. manufacturing facilities. REACH registration requirements and the EU Green Deal's chemical sustainability targets are redirecting European procurement toward bio-based alcohol alternatives. China's GB standards and MEE environmental enforcement are elevating qualification barriers for imported solvents. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Semiconductor node shrinkage below 5nm is fragmenting solvent specifications across foundry tiers, forcing refiners to maintain parallel production lines for HPLC-grade and sub-ppb electronic grades.
Growth Catalysts
- Advanced Lithography Nodes:Taiwan and South Korean foundries consume escalating volumes of ultra-high-purity acetonitrile and propylene glycol monomethyl ether acetate for EUV resist processing.
- REACH Authorization Thresholds:ECHA's tightening impurity ceilings for SVHC substances are compelling pharmaceutical chromatography labs to upgrade solvent grades, sustaining premium pricing power.
- GB Standards Enforcement:China's MEE environmental inspections are disqualifying low-purity domestic suppliers, redirecting procurement toward import-qualified refiners.
Market Restraints
- Feedstock Volatility:Acetonitrile supply tightens with acrylic fiber production cycles, exposing solvent margins to petrochemical co-product availability swings.
- East Asian Concentration:Taiwan, South Korea, and Japan host 70% of leading-edge wafer capacity, creating geographic demand risk from seismic or geopolitical disruption.
- Aqueous Substitution:Electronics cleaning applications are piloting supercritical CO2 and ozonated water systems that eliminate solvent-based surface preparation.
Strategic Opportunities
- Indian Pharmaceutical Expansion:CDSCO's tightened analytical method validation rules are creating import substitution potential for EU-grade solvent localization.
- Bio-Based Alcohol Pathways:EU Green Deal chemical sustainability targets are redirecting European procurement toward fermentation-derived ethanol and isopropanol certified under mass-balance schemes.
- Direct Foundry Contracting:Samsung and TSMC are consolidating supplier bases, offering volume commitments to refiners willing to co-locate purification facilities near Hsinchu or Pyeongtaek clusters.
Industry Challenges
- Specialized Purification Talent:Operating molecular sieve and distillation systems for sub-ppb production requires chemists with semiconductor contamination control expertise that outpaces vocational training output.
- Multi-Jurisdiction Certification Lag:Simultaneous qualification under EPA Method 8260, REACH Annex XVII, and China's GB/T 23992-2009 extends product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Solvents Market |
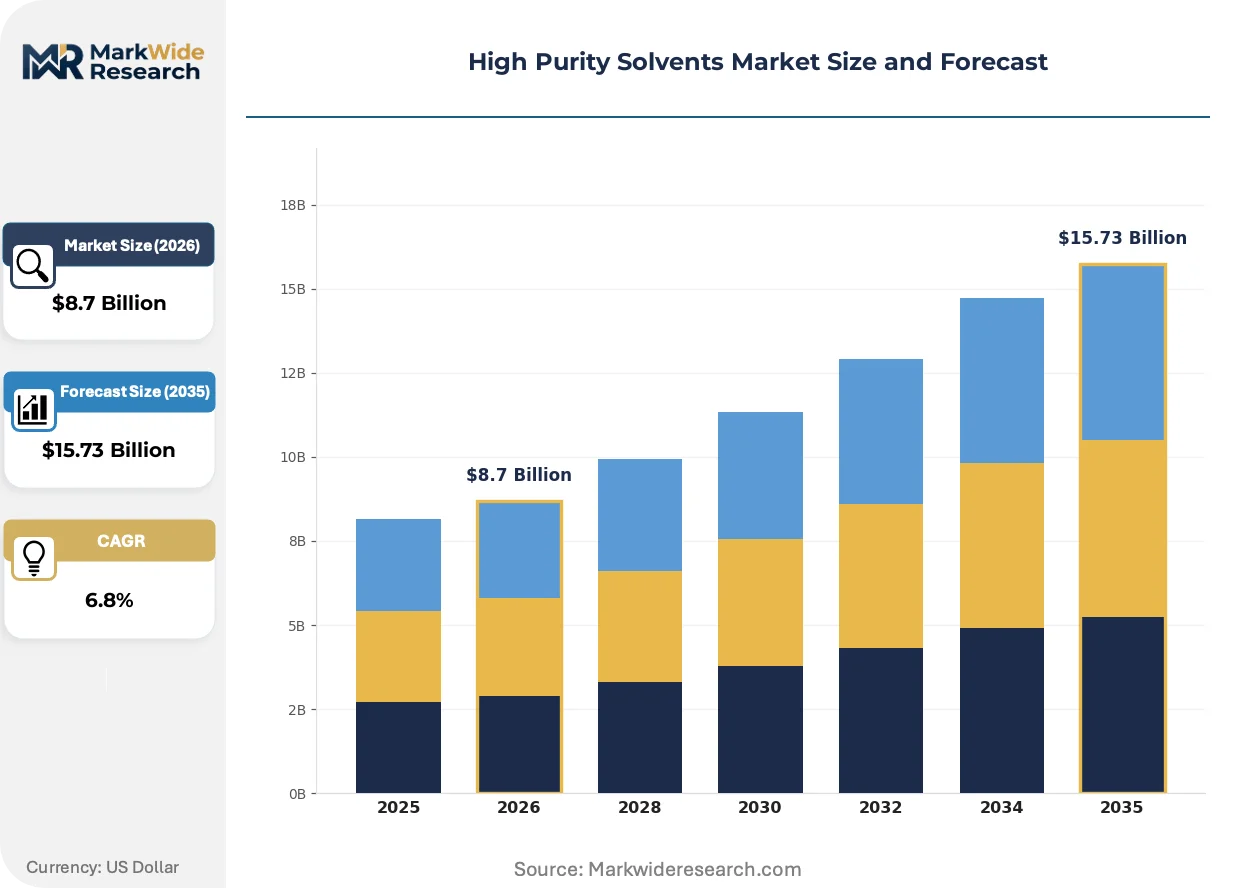
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohols, Ketones, Aldehydes, Aromatics Grade: Analytical Grade, Reagent Grade, Ultra-Pure Grade, HPLC Grade Application: Pharmaceuticals, Chemical Synthesis, Coatings, Electronics End User: Research Laboratories, Chemical Manufacturers, Electronics Industry, Pharmaceutical Companies |
| Companies Covered | BASF SE, ExxonMobil, Asahi Kasei Corp, Thermo Fisher Scientific, Evonik Industries AG, Dow, Linde, Merck KGaA, Tedia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Solvents Market Strategic Shifts
Point-of-use purification systems are compressing traditional supply chains, while regulatory divergence between EPA, REACH, and GB frameworks is multiplying formulation variants. Refiners must now engineer solvent portfolios for jurisdiction-specific impurity signatures rather than universal grades.
Continuous chromatography systems are fragmenting batch purification economics. Astrea Bioseparations and other equipment vendors are deploying simulated moving bed technology that cuts solvent consumption per kilogram of pharmaceutical active ingredient by 40%. Biologics manufacturers in Ireland and Massachusetts are retrofitting existing facilities, while greenfield sites in Singapore specify continuous systems from commissioning. The technology is fragmenting the traditional scale economies of large-batch solvent recovery, favoring modular, smaller-volume refiners.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone are forcing electronics cleaners toward alternative polar aprotic solvents. The ECHA sunset date for reproductive toxicity classification is accelerating qualification of dimethyl sulfoxide and sulfolane blends in German and Dutch coating operations. Semiconductor packaging houses are responding with dual-track formulations that maintain performance while pre-positioning for authorization loss.
Consolidated procurement through foundry-level chemical management services is displacing individual solvent purchasing. Entegris and DuPont are contracting directly with TSMC and Intel for total fluid management, bundling purification, distribution, and waste recovery. This model concentrates specification-setting power with semiconductor manufacturers in Taiwan and Arizona, compressing margins for standalone solvent suppliers unable to integrate logistics capabilities.
High Purity Solvents Market Segmentation
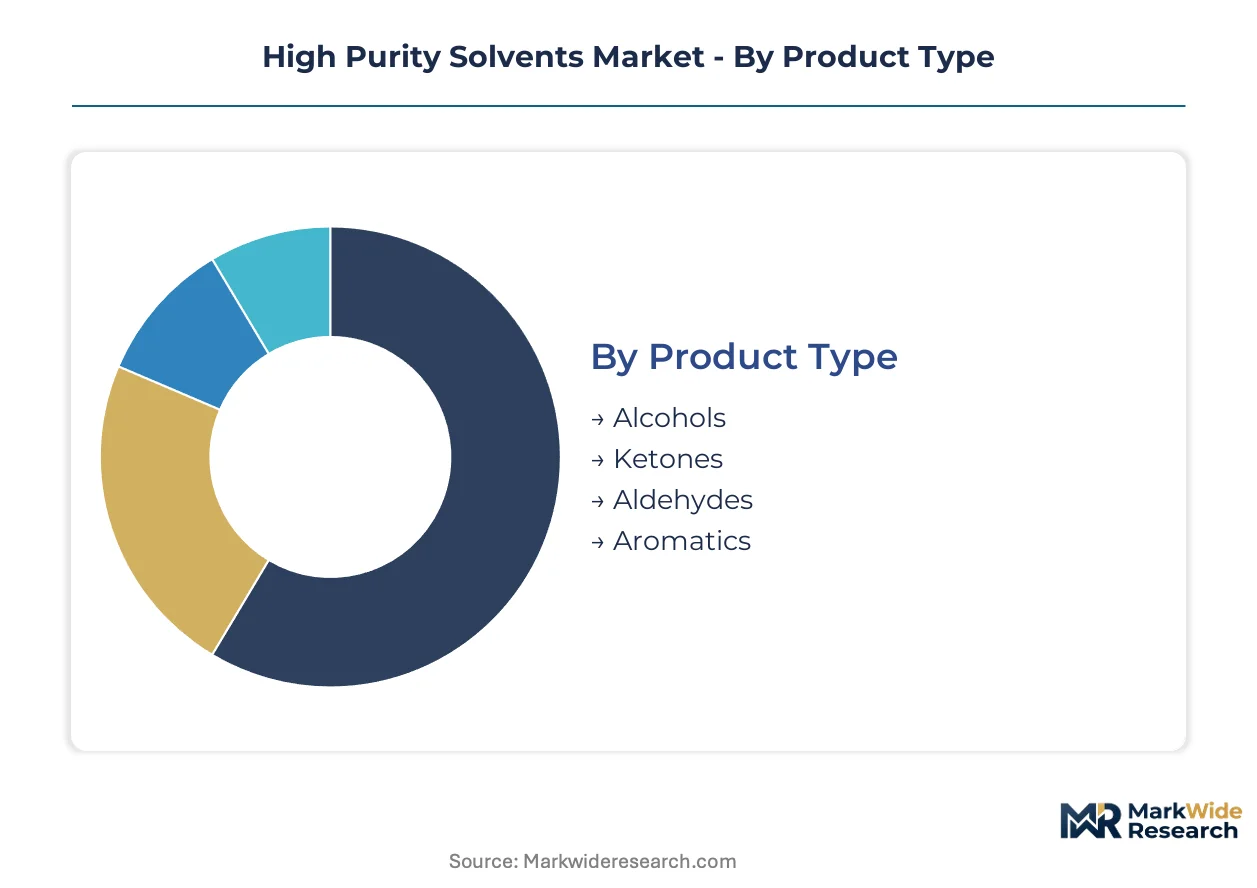
High purity solvent procurement fragments across technical specifications that determine allowable impurity thresholds for semiconductor lithography versus pharmaceutical quality control. Grade differentiation and end-use certification requirements create pricing spreads that often exceed 300% between analytical and ultra-pure tiers.
Product Type:
Alcohols face the strongest substitution pressure from aqueous and supercritical CO2 cleaning systems in electronics surface preparation, while ketones and aromatics retain irreplaceable roles in resist dissolution and polymer synthesis.
- Alcohols:Isopropanol and methanol achieve sub-ppm metal ion specifications through multi-stage molecular sieve drying. Taiwan foundries consume escalating volumes for wafer dehydration steps prior to EUV resist coating, though ozonated water pilots threaten long-term volume growth in front-end cleaning.
- Ketones:Acetone and methyl ethyl ketone dominate photoresist stripping applications where polarity matching prevents substrate damage. South Korean packaging houses specify electronic-grade ketones for advanced fan-out wafer-level processing, with supply security tightening during acrylic fiber production downturns that constrain acetonitrile co-product availability.
- Aldehydes:Formaldehyde and acetaldehyde derivatives serve specialized cross-linking chemistry in coating formulations.
- Aromatics:Toluene and xylene isomers persist in photoresist solvent blends despite REACH authorization pressures on reproductive toxicity classifications.
Alcohols retain volume leadership; ketones hold the steepest expansion curve.
Grade:
Cost stratification across certification tiers separates commodity laboratory supply from semiconductor-qualified production, with qualification timelines spanning 18-24 months for multi-jurisdiction registration.
- Analytical Grade:General laboratory solvents meeting ACS specifications for titration and extraction workflows. Indian pharmaceutical QC labs under CDSCO tightened method validation rules are upgrading from technical grades, creating import substitution demand for EU-certified local production.
- Reagent Grade:Higher purity tiers for synthetic chemistry where trace contaminants catalyze side reactions.
- Ultra-Pure Grade:Sub-ppb metal ion and particle specifications for semiconductor node processing below 7nm. TSMC and Samsung consolidate supplier bases around refiners co-locating purification facilities near Hsinchu and Pyeongtaek clusters, bundling logistics with point-of-use filtration services.
- HPLC Grade:UV-transparent solvents with guaranteed low baseline absorbance for chromatographic detection. ECHA tightening of SVHC impurity ceilings compels European pharmaceutical labs to upgrade solvent grades, sustaining premium pricing power for Merck KGaA and Thermo Fisher Scientific portfolios.
Ultra-Pure Grade captures the steepest margin expansion; HPLC Grade anchors the largest installed base.
Application:
End-use concentration in East Asian electronics corridors outpaces chemical synthesis demand, where environmental compliance costs accelerate process redesign toward solvent-free alternatives.
- Electronics:EUV resist processing and wafer cleaning consume acetonitrile, propylene glycol monomethyl ether acetate, and specialized fluorinated solvents. Taiwan, South Korea, and Japan host 70% of leading-edge capacity, creating geographic demand risk from seismic or geopolitical disruption.
- Pharmaceuticals:Chromatographic method development and quality control testing drive HPLC-grade consumption. Continuous chromatography systems from Astrea Bioseparations cut solvent consumption per kilogram of active ingredient by 40%, fragmenting traditional batch purification economics.
- Chemical Synthesis:Reaction media and extraction solvents face displacement pressure from green chemistry principles and REACH Annex XVII restrictions.
- Coatings:Precision formulation of thin-film electronics and optical components.
Electronics commands the fastest volume growth; pharmaceuticals sustains the most stable pricing environment.
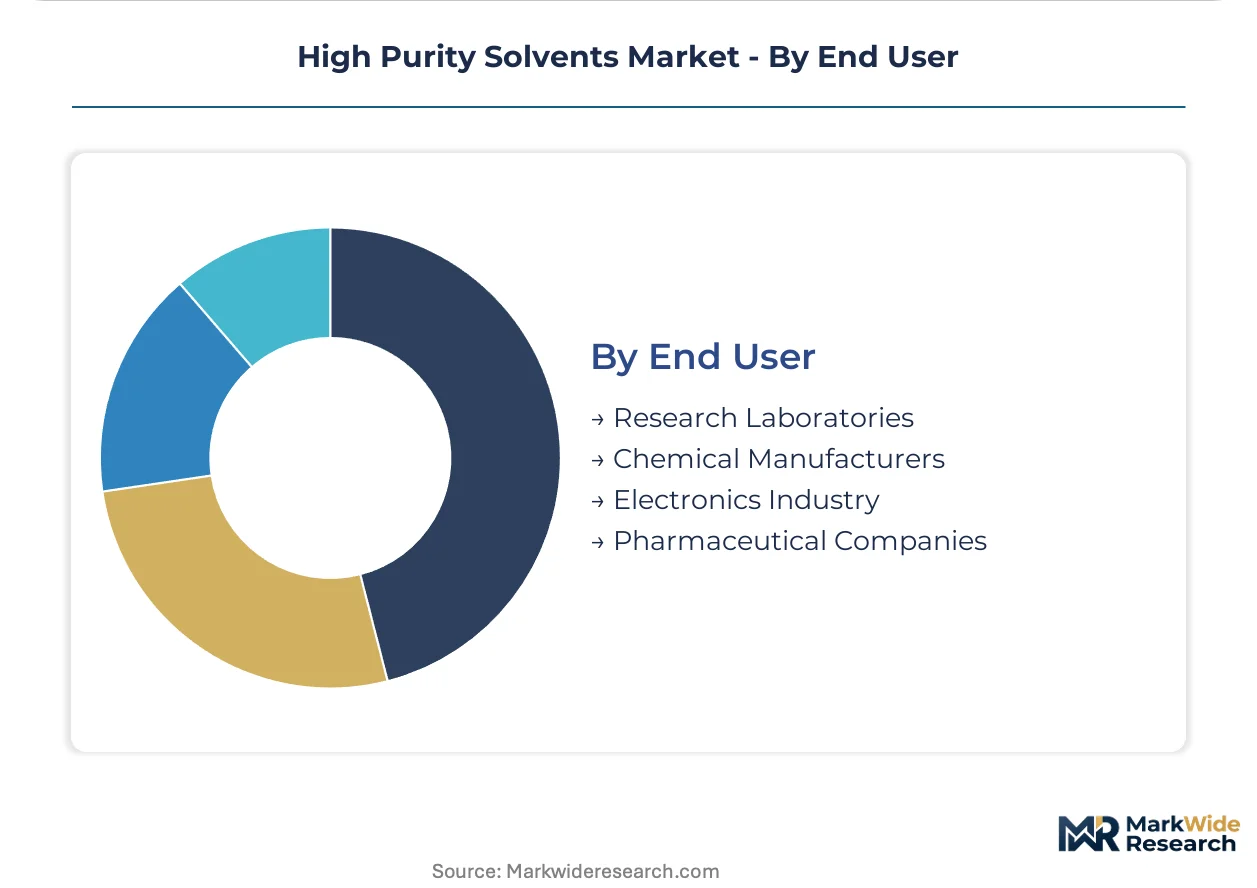
End User:
Customer type determines procurement modality, with consolidated chemical management services displacing individual solvent purchasing for the largest semiconductor manufacturers.
- Electronics Industry:Foundry and packaging houses contract total fluid management through Entegris and DuPont, bundling purification, distribution, and waste recovery. This model concentrates specification-setting power with TSMC and Intel, compressing margins for standalone suppliers lacking integrated logistics.
- Pharmaceutical Companies:Quality control and analytical method validation drive grade-sensitive procurement. CDSCO enforcement in India and EMA standards in Europe create multi-jurisdiction compliance burdens that favor established suppliers with established registration portfolios.
- Research Laboratories:Academic and government facilities with fragmented purchasing and lower volume thresholds.
- Chemical Manufacturers:Process-scale consumption for intermediate and active ingredient synthesis.
Electronics Industry leads absolute consumption growth; Pharmaceutical Companies provide the most defensible margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in East Asian electronics corridors while European pharmaceutical demand sustains premium margins through regulatory compliance costs. The divergence reflects foundry-grade solvent scarcity against REACH-driven grade inflation in analytical applications.
United States
Intel's Arizona and Oregon fabrication complexes drive ultra-pure solvent procurement for advanced packaging development. EPA Method 8260 and OSHA permissible exposure limits constrain volatility specifications in domestic manufacturing. The Phoenix-Tucson corridor attracts Entegris and DuPont chemical management services co-located with Intel's expanding foundry footprint.
Taiwan
TSMC's Hsinchu and Tainan Science Parks consume escalating acetonitrile volumes for EUV resist processing at 3nm and 2nm nodes. The island's environmental regulations under the Environmental Protection Administration tighten wastewater discharge standards for solvent recovery operations. Kaohsiung's Lin-hai Industrial Park hosts concentrated specialty chemical storage and distribution infrastructure serving southern foundry clusters.
South Korea
Samsung and SK Hynix anchor propylene glycol monomethyl ether acetate demand for advanced DRAM and logic wafer production. MFDS pharmaceutical standards and MEE-aligned environmental enforcement elevate import qualification barriers for solvent refiners. The Pyeongtaek semiconductor cluster drives supplier consolidation around integrated purification-logistics providers.
Germany
Merck KGaA's Darmstadt operations dominate HPLC-grade supply for European pharmaceutical chromatography under EMA quality guidelines. REACH Annex XVII restrictions on N-methyl-2-pyrrolidone force electronics manufacturers toward alternative polar aprotic solvent formulations. The Ludwigshafen chemical complex sustains backward integration into acetonitrile and tetrahydrofuran feedstocks through BASF SE's Verbund operations.
China
Domestic foundry expansion by SMIC and Hua Hong Semiconductor strains local ultra-pure solvent purification capacity. GB standards enforcement by MEE disqualifies low-purity domestic suppliers, redirecting procurement toward import-qualified refiners. The Yangtze River Delta concentration of semiconductor packaging houses creates regional demand density for electronic-grade ketones and alcohols.
High Purity Solvents Market Competitive Environment
Concentration sits with integrated petrochemical majors and specialized refiners maintaining parallel production lines for divergent grade specifications. The market structure fragments across three tiers: multinational chemical conglomerates with captive feedstock access, laboratory supply specialists with established regulatory registration portfolios, and regional refiners serving jurisdiction-specific demand. Strategic moves center on foundry co-location commitments and bio-based alcohol pathway development under EU Green Deal targets.
Within the integrated chemical tier, BASF SE and Merck KGaA exemplify divergent specialization—one anchored in Ludwigshafen feedstock control, the other in Darmstadt pharmaceutical-grade certification. Thermo Fisher Scientific occupies a position bridging laboratory supply scale with North American distribution density. These three represent distinct competitive archetypes: petrochemical backward integration, pharma-grade regulatory mastery, and analytical-channel market presence.
| Leading Market Players |
|---|
| BASF SE |
| ExxonMobil |
| Asahi Kasei Corp |
| Thermo Fisher Scientific |
| Evonik Industries AG |
| Dow |
| Linde |
| Merck KGaA |
| Tedia |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month multi-jurisdiction certification timelines compress inventory flexibility for refiners serving TSMC and Samsung, concentrating pricing power with integrated purification-logistics providers while forcing standalone suppliers to absorb working capital strain.
Pricing Analysis
Configured-to-order pricing for foundry-specific ultra-pure grades commands spreads exceeding 300% above standard analytical tiers. Three-tier pricing structure across ultra-pure, HPLC, and reagent levels differentiates by metal ion specification and particle filtration depth. Cost compression in analytical-grade alcohols is intensifying because ozonated water pilots threaten front-end cleaning volumes. Electronics manufacturers show lowest price sensitivity due to node-shrinkage imperatives, while research laboratories face acute budget constraints.
Supply Chain Analysis
Strait of Malacca transit underwrites acetonitrile feedstock flows from Ludwigshafen and Jurong Island to Hsinchu and Pyeongtaek clusters. Production gravity centers on Germany, Taiwan, and South Korea for ultra-purification capacity. Feedstock supply draws from acrylic fiber co-product cycles, petroleum-derived ketone streams, and bio-ethanol fermentation pathways. Single-source vulnerability concentrates in molecular sieve media and specialized distillation column fabrication. Distribution runs through Entegris and DuPont chemical management services bundling point-of-use filtration with waste recovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High purity solvents function as a service-attach business where point-of-use purification and waste recovery contracts expand faster than commodity solvent volumes, rewarding integrated logistics capabilities over standalone refining.
For Market Incumbents: Shield premium positioning by co-locating sub-ppb purification facilities adjacent to Samsung and TSMC clusters, while accelerating bio-based alcohol certification under EU Green Deal mass-balance schemes to preempt REACH-driven substitution. Aqueous cleaning pilots and supercritical CO2 systems threaten long-term electronics demand; backward integration into acetonitrile feedstocks defends margin structure against petrochemical co-product volatility. For New Entrants and Emerging Players: CDSCO fast-track certification for EU-grade solvent localization offers entry into Indian pharmaceutical QC labs upgrading from technical grades under tightened method validation rules. White-space concentrates in fermentation-derived isopropanol for European coating operations and modular continuous chromatography solvent supply for Irish and Massachusetts biologics manufacturers. Direct contracting with mid-tier foundries bypasses consolidated Entegris-DuPont procurement channels. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because multi-jurisdiction certification portfolios compound defensibility as EPA, REACH, and GB standards diverge. Target refiners with established registrations across all three frameworks rather than geographic specialists. Watch for MEE enforcement intensity in China as the signal indicating import-substitution window closure versus continued foreign supplier reliance.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Co-location Commitment | TSMC and Samsung consolidate supplier bases around integrated purification-logistics providers near Hsinchu and Pyeongtaek. |
| Bio-Based Alcohol Pathway Development | EU Green Deal chemical sustainability targets redirect European procurement toward fermentation-derived ethanol and isopropanol. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA Method 8260, REACH Annex XVII, and GB/T 23992-2009 qualification extends product launch timelines but locks out competitors. |
| Continuous Chromatography System Integration | Astrea Bioseparations technology cuts solvent consumption per kilogram of pharmaceutical active ingredient by 40%. |
| Total Fluid Management Contracting | Entegris and DuPont bundle purification, distribution, and waste recovery for Intel and TSMC, compressing standalone supplier margins. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at specialty solvent refineries, procurement leads at semiconductor foundries, distribution channel partners serving analytical laboratories, and technical R&D directors in pharmaceutical chromatography divisions, and refined through secondary validation against customs/trade data, ECHA registration databases, SEC 10-K filings from listed chemical conglomerates, and MEE environmental enforcement disclosures. Bottom-up volume modeling across grade tiers and end-use applications was triangulated against top-down market sizing from petrochemical feedstock flow analysis.
Variance decomposition across the projection horizon isolates volume drivers by grade tier, end-use industry, and regional production hub, with CAGRs derived from foundry capacity expansion schedules and pharmaceutical method validation upgrade cycles. Modeled inputs include semiconductor node shrinkage trajectories, REACH authorization sunset dates for N-methyl-2-pyrrolidone, and GB standards enforcement intensity metrics from MEE inspection disclosures.
Underlying assumptions cover sustained East Asian foundry capital expenditure, stable acrylic fiber production cycles for acetonitrile co-product availability, and gradual aqueous substitution rather than abrupt displacement in electronics cleaning. Deviation risk concentrates in seismic disruption to Taiwan supply clusters, REACH Annex XVII expansion to additional solvent classes, and faster-than-anticipated supercritical CO2 adoption. Practitioners should keep alternative scenarios live as regulatory divergence and cleaning technology substitution trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Hydrofluoroether Market
Solvents
Ethyl Acetate Market
Solvents
Butyl Acetate (BAC) Market
Solvents
Ethane Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Hydrocarbon Solvents Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Allyl Cyanide Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Butane Market
Solvents
Global Bio Solvents Market
Solvents
1, 1-Difluoroethane Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Acetone Market
Solvents
Chloroacetonitrile Market