
 2 - Ethyl Anthraquinone Market | 2026-2036
2 - Ethyl Anthraquinone Market Size, Share, and Industry Trends Forecast 2026-2036
2 - Ethyl Anthraquinone Market Analysis
Modular packaging configurations for specialty chemicals is rebalancing procurement patterns among dye and pigment manufacturers. BASF leverages integrated anthraquinone production networks across European sites. Clariant anchors its position through specialized pigment-grade formulations. Jilin Zirui New Material Co., Ltd. dominates regional supply chains with backward integration into key intermediates.
2-Ethyl anthraquinone functions as a catalytic carrier in the anthraquinone process for hydrogen peroxide synthesis, typically supplied at purity levels exceeding 98 percent with controlled isomer ratios to optimize oxidation cycle efficiency. The compound serves as the workhorse intermediate enabling continuous auto-oxidation production of hydrogen peroxide at industrial scale. Industrial grade product types command the largest volume share due to bulk hydrogen peroxide manufacturing requirements, while specialty grade segments capture disproportionate margin pools from pharmaceutical and high-specification dye applications. Chemical intermediates application segments exhibit the strongest structural momentum as downstream agrochemical and polymer additive markets expand formulation complexity.
EPA oversight of chemical manufacturing emissions shapes production facility siting and wastewater treatment investments for US-based producers. ECHA REACH registration requirements mandate comprehensive substance dossiers that elevate compliance costs for importers into European Union markets. China's MEE enforces increasingly stringent VOC discharge limits around chemical industrial parks. Stakeholders must monitor regulatory divergence between jurisdictions when evaluating capacity expansion timelines and certification strategies.
Market Dynamics
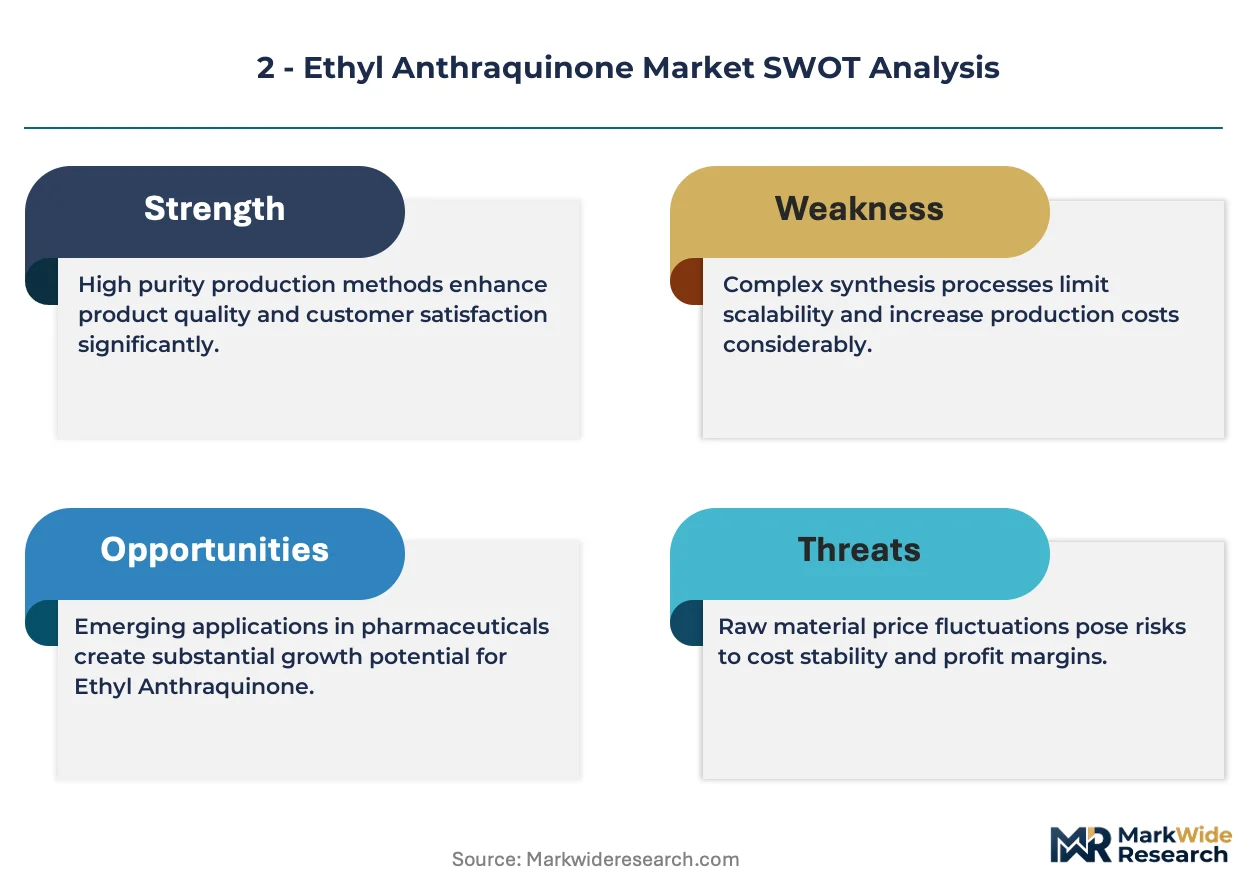
The hydrogen peroxide industry's pivot toward mega-scale production facilities is compressing supplier margins while elevating purity specifications for catalytic carriers. This structural pressure favors producers with integrated intermediate capabilities and penalizes merchant suppliers lacking backward integration into anthraquinone precursors.
Growth Catalysts
- Hydrogen peroxide capacity expansion:Chemical manufacturers in China are commissioning world-scale auto-oxidation plants that consume multi-thousand-tonne quantities of 2-ethyl anthraquinone annually, tightening spot market availability.
- REACH substance dossier completion:ECHA registration requirements for 2-ethyl anthraquinone have locked in compliant European suppliers, creating a certification moat against unregistered import competition.
- Specialty dye formulation complexity:Agrochemical and polymer additive developers are specifying controlled isomer ratios that command premium pricing over standard industrial grades.
Market Restraints
- Crude oil derivative volatility:Ethylbenzene and phthalic anhydride feedstock costs swing with benzene complex pricing, compressing conversion margins for non-integrated producers.
- Supplier geographic concentration:Backward-integrated Chinese producers control roughly two-thirds of merchant supply, exposing buyers to single-country logistics and trade policy risks.
- Process water treatment intensity:EPA effluent limitations guidelines for organic chemical manufacturing impose capital-intensive biological treatment systems on US production facilities.
Strategic Opportunities
- Pharmaceutical-grade certification:ICH Q7 compliance for active pharmaceutical ingredient intermediates opens margin pools in hydrogen peroxide sterilization applications for medical device manufacturing.
- India chemical cluster development:Gujarat and Maharashtra industrial corridors are attracting hydrogen peroxide investments that will require virgin anthraquinone catalyst supply without existing local production.
- Process analytical technology integration:Inline spectroscopic monitoring of oxidation cycle efficiency is unifying quality specifications between catalyst suppliers and peroxide operators, enabling long-term offtake contracting.
Industry Challenges
- Specialized chemical engineering talent:The anthraquinone process requires expertise in auto-oxidation reactor design and solvent recovery systems that few universities now teach.
- Multi-year REACH re-registration timelines:ECHA's 2023 updated dossier requirements demand fresh toxicological and environmental fate studies that delay market access for new European entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2 - Ethyl Anthraquinone Market |
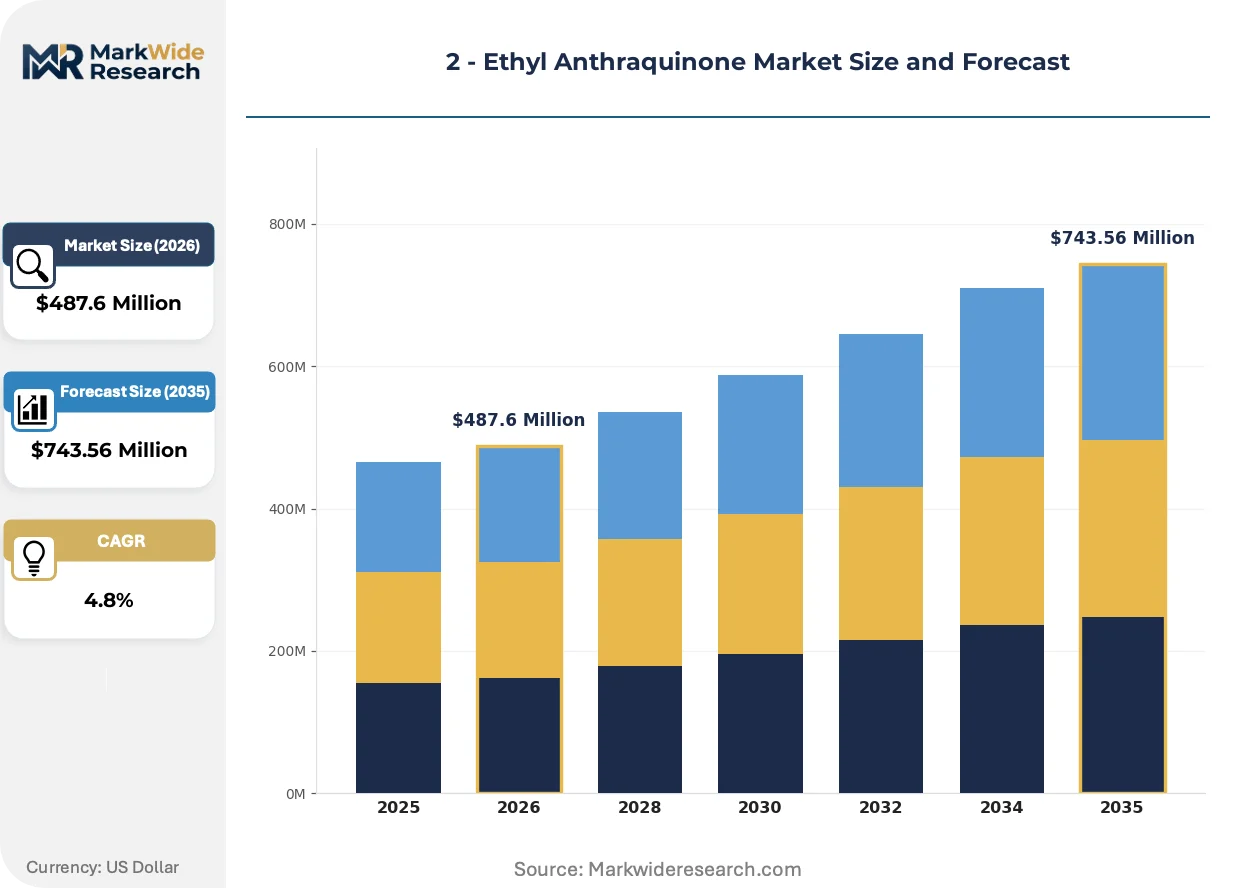
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Grade, Industrial Grade, Laboratory Grade, Specialty Grade Application: Dyes, Pigments, Pharmaceuticals, Chemical Intermediates End User: Chemical Manufacturers, Pharmaceutical Companies, Paint and Coating Industry, Textile Industry Packaging Type: Drums, Bags, Containers, Bulk |
| Companies Covered | BASF, Clariant, DIC Corporation, Jilin Zirui New Material Co., Ltd., Changzhou Hongyu Chemical Co., Ltd., Hebei Kailite Sensitizing Chemicals Co., Henan Baofeng Chemical Industry Co., Solvay, Lanxess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2 - Ethyl Anthraquinone Market Emerging Trajectories
Digital process control systems and closed-loop solvent recovery are compressing the cost structure of anthraquinone-based hydrogen peroxide production. These advances are reshaping supplier qualification criteria and accelerating consolidation among merchant catalyst producers.
Continuous flow reactor technology is unifying oxidation and extraction stages into single-unit operations. Hydrogen peroxide operators in Germany and Belgium are retrofitting existing auto-oxidation trains with modular flow chemistry skids. This convergence is enabling real-time adjustment of 2-ethyl anthraquinone concentration profiles, reducing catalyst consumption per tonne of peroxide output.
China's MEE has tightened VOC emission limits for chemical industrial parks operating anthraquinone process facilities. The regulation mandates sealed material handling systems and vapor recovery units for all organic intermediate production. Hydrogen peroxide manufacturers in the Yangtze River Delta are responding by qualifying only catalyst suppliers with certified closed-loop packaging and bulk delivery capabilities.
Specification-driven contracting is displacing spot procurement for high-volume hydrogen peroxide operations. Large chemical producers in the US Gulf Coast are negotiating three to five-year offtake agreements with isomer ratio guarantees and technical service attachments. This shift concentrates purchasing power among integrated energy-chemical conglomerates and marginalizes smaller merchant suppliers lacking analytical certification laboratories.
2 - Ethyl Anthraquinone Market Segmentation
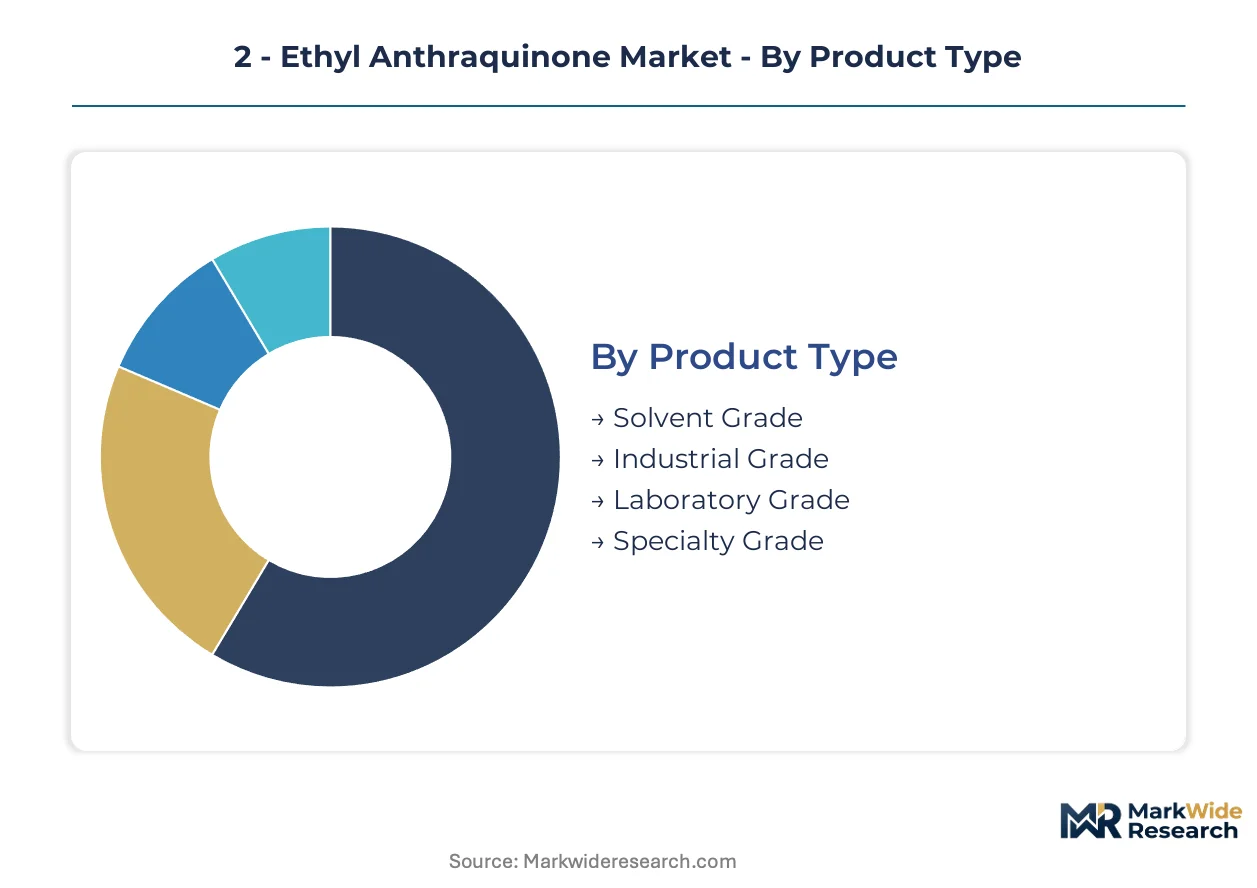
2-Ethyl anthraquinone procurement patterns diverge sharply across purity tiers and end-use specifications. Hydrogen peroxide manufacturers drive volume concentration toward industrial grades, while pharmaceutical and specialty dye applications extract premium pricing through certification requirements.
Product Type:
Upgrade cycles from standard industrial grades to higher-purity alternatives are compressing as hydrogen peroxide operators tighten oxidation efficiency specifications.
- Industrial Grade:Supplied at purity levels exceeding 98 percent with controlled isomer ratios for continuous auto-oxidation processes. Hydrogen peroxide mega-plants in China consume multi-thousand-tonne quantities annually, tightening spot availability for non-contract buyers.
- Specialty Grade:Formulated with precise isomer distributions and low impurity profiles for pharmaceutical sterilization and high-specification dye synthesis. ECHA REACH registration requirements lock in compliant European suppliers, creating certification moats against unregistered import competition.
- Solvent Grade:Optimized for dissolution characteristics in organic carrier systems used in agrochemical formulation.
- Laboratory Grade:Packaged in smaller volumes for analytical method development and process validation work.
Industrial Grade sits at the top of the volume ranking, with Specialty Grade climbing the fastest.
Application:
Cost tier differentiation separates bulk chemical manufacturing from formulation-intensive downstream segments demanding technical service attachments.
- Chemical Intermediates:Serving as catalytic carriers and building blocks for polymer additives and agrochemical actives. Downstream markets in India and China are expanding formulation complexity, driving structural momentum for virgin anthraquinone supply.
- Dyes:Anthraquinone-derived colorants for textile and industrial applications requiring controlled substitution patterns. Modular packaging configurations are rebalancing procurement patterns among specialty pigment manufacturers seeking just-in-time delivery.
- Pigments:High-performance colorants with thermal and light stability specifications for coatings and plastics.
- Pharmaceuticals:ICH Q7-compliant intermediates for hydrogen peroxide sterilization in medical device manufacturing, opening margin pools through certification barriers.
Chemical Intermediates dominates current volume flows, with Pharmaceuticals gaining share fastest on sterilization demand expansion.
End User:
Customer type fragmentation reflects divergent procurement power between integrated chemical conglomerates and fragmented specialty formulators.
- Chemical Manufacturers:World-scale hydrogen peroxide producers negotiating three to five-year offtake agreements with isomer ratio guarantees. Specification-driven contracting concentrates purchasing power among US Gulf Coast and Yangtze River Delta operators.
- Pharmaceutical Companies:Sterilization-grade hydrogen peroxide buyers requiring batch documentation and audit trails for medical device manufacturing compliance.
- Paint and Coating Industry:Pigment-grade consumers with moderate volume requirements and price-sensitive procurement patterns.
- Textile Industry:Dye intermediate buyers concentrated in regional manufacturing clusters with seasonal demand fluctuations.
Chemical Manufacturers command the largest volume share, with Pharmaceutical Companies expanding most quickly on sterilization protocol adoption.
Packaging Type:
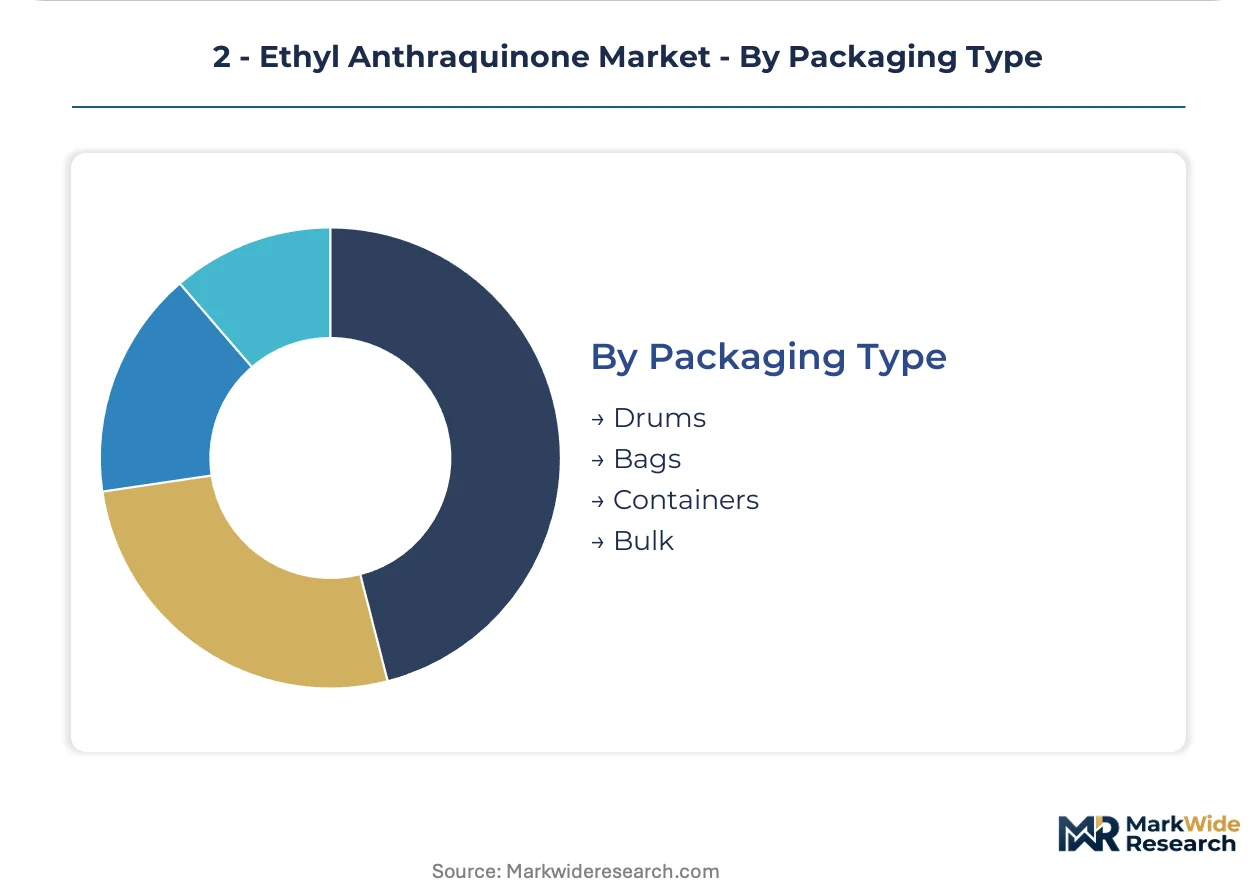
Supply concentration around bulk delivery capabilities is marginalizing drum and bag suppliers lacking sealed material handling systems.
- Bulk:Dedicated tanker and railcar deliveries for world-scale hydrogen peroxide facilities. China's MEE mandates vapor recovery units and sealed transfer systems, qualifying only suppliers with certified closed-loop logistics.
- Drums:Standard steel and composite containers for mid-volume chemical manufacturers with established material handling infrastructure.
- Containers:Intermediate bulk units for regional distribution to secondary formulators.
- Bags:Woven and lined configurations for specialty pigment and laboratory-grade shipments.
Bulk leads procurement volumes, with Container formats climbing fastest on modular flow chemistry skid adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The anthraquinone process for hydrogen peroxide synthesis achieved industrial scale in Germany during the 1950s, establishing the Rhine-Ruhr corridor as the foundational production geography before capacity expansion shifted toward feedstock-advantaged regions.
China
World-scale hydrogen peroxide mega-plants in the Yangtze River Delta consume multi-thousand-tonne quantities of 2-ethyl anthraquinone annually. MEE enforcement of VOC discharge limits around chemical industrial parks mandates sealed material handling systems and vapor recovery units for all organic intermediate production. Jilin Zirui New Material Co., Ltd. anchors regional supply chains through backward integration into key anthraquinone precursors.
Germany
BASF leverages integrated anthraquinone production networks across European sites to serve hydrogen peroxide operators retrofitting auto-oxidation trains with modular flow chemistry skids. ECHA REACH registration requirements for 2-ethyl anthraquinone have locked in compliant European suppliers, creating a certification moat against unregistered import competition. The Rhine-Ruhr and Ludwigshafen chemical clusters concentrate specification-driven contracting with three to five-year offtake agreements.
United States
EPA oversight of chemical manufacturing emissions shapes production facility siting and wastewater treatment investments for US-based producers of catalytic carriers. Large chemical producers in the US Gulf Coast negotiate long-term supply agreements with isomer ratio guarantees and technical service attachments. The Texas-Louisiana petrochemical corridor hosts hydrogen peroxide operators demanding pharmaceutical-grade certification for sterilization applications.
India
Gujarat and Maharashtra industrial corridors are attracting hydrogen peroxide investments that will require virgin anthraquinone catalyst supply without existing local production. CDSCO alignment with ICH Q7 standards for active pharmaceutical ingredient intermediates opens margin pools in medical device manufacturing sterilization. Mumbai-Pune and Ahmedabad-Vadodara chemical clusters are emerging as procurement hubs for specialty-grade formulations.
Belgium
Solvay's heritage in peroxide chemistry sustains demand for high-purity catalytic carriers with controlled isomer distributions. ECHA REACH substance dossier completion elevates compliance costs for importers, reinforcing positions of registered European suppliers. The Port of Antwerp chemical cluster enables bulk delivery logistics for world-scale hydrogen peroxide facilities serving Northwestern European markets.
2 - Ethyl Anthraquinone Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and purity tiers, with REACH-registered European suppliers capturing disproportionate returns while merchant Chinese producers compete on scale and feedstock integration. The supplier base concentrates around backward-integrated chemical conglomerates and specialized anthraquinone manufacturers, with limited presence of pure-play traders. Three archetypes dominate: integrated multinational chemical groups with captive intermediate production, regional Chinese producers with coal-chemical feedstock advantages, and European specialists with pharmaceutical-grade certification capabilities. Capacity expansion in China's chemical industrial parks and REACH re-registration compliance investments represent the dominant competitive moves reshaping supply availability.
Among Germany-based integrated chemical groups, BASF exemplifies the multinational archetype with cross-site production network coordination. Clariant occupies a position within the specialty-grade tier through pigment-grade formulation focus. Jilin Zirui New Material Co., Ltd. represents the Chinese regional producer archetype with backward integration into key intermediates. These three anchors illustrate how geographic feedstock advantages, regulatory certification moats, and end-use specialization stratify competitive returns across the catalytic carrier supply base.
| Leading Market Players |
|---|
| BASF |
| Clariant |
| DIC Corporation |
| Jilin Zirui New Material Co., Ltd. |
| Changzhou Hongyu Chemical Co., Ltd. |
| Hebei Kailite Sensitizing Chemicals Co. |
| Henan Baofeng Chemical Industry Co. |
| Solvay |
| Lanxess |
| Others |
Supply Flow & Price Mechanics
Backward integration into anthraquinone precursors anchors both supply security and pricing power for producers serving hydrogen peroxide mega-plants. Chinese producers with captive ethylbenzene and phthalic anhydride production command margin resilience against feedstock volatility that merchant suppliers cannot match.
Pricing Analysis
Three-tier pricing structure across specialty, industrial, and solvent grades separates pharmaceutical-certified carriers from standard bulk supply. Price differentiation hinges on isomer ratio precision and REACH registration status, with European-registered suppliers capturing premiums against unregistered imports. Pricing pressure stems from mega-scale hydrogen peroxide operators consolidating purchasing power through multi-year offtake agreements. Chemical manufacturers prove least price-sensitive due to specification lock-in, while paint and coating buyers exhibit highest elasticity.
Supply Chain Analysis
Specialized chemical engineering talent shortages in the Yangtze River Delta and Rhine-Ruhr corridor constrain capacity expansion timelines for anthraquinone process facilities. Manufacturing concentrates in China, Germany, and Belgium, with feedstock supply drawing from coal-chemical complexes and benzene derivative networks. Single-country logistics exposure creates vulnerability given Chinese producers control roughly two-thirds of merchant supply. Distribution runs through dedicated tanker and railcar bulk delivery to world-scale hydrogen peroxide facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH re-registration requirements elevate compliance barriers and consolidate returns among dossier-complete suppliers.
For Market Incumbents: Lock in specification-driven contracting with hydrogen peroxide operators through isomer ratio guarantees and embedded technical service teams. Deepen backward integration into phthalic anhydride and ethylbenzene precursors to defend margins against crude derivative volatility. Prioritize pharmaceutical-grade certification investments to capture sterilization application premiums before CDSCO alignment with ICH Q7 standards accelerates in India. For New Entrants and Emerging Players: REACH registration gaps in the European Union open a window for specialty-grade producers with existing dossier compliance to establish import substitution positions. Target Gujarat and Maharashtra hydrogen peroxide investments in India requiring virgin anthraquinone catalyst supply without local production infrastructure. Lead with modular packaging configurations and sealed material handling systems that satisfy China's MEE VOC emission mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH re-registration timelines and capital-intensive biological treatment requirements marginalize non-integrated merchant suppliers. Position for five-to-ten year value capture around producers with pharmaceutical-grade certification capabilities and Yangtze River Delta logistics access. Monitor CDSCO enforcement alignment with ICH Q7 standards as the inflection signal for sterilization-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylbenzene and phthalic anhydride production insulates margins from benzene complex volatility. |
| Pharmaceutical-Grade Certification | ICH Q7 compliance opens sterilization application margins in medical device manufacturing supply chains. |
| Long-term Supply Agreement | Three-to-five year offtake contracts with isomer ratio guarantees lock in volume with mega-scale hydrogen peroxide operators. |
| Green Manufacturing Transition | Closed-loop solvent recovery and sealed material handling systems satisfy China's MEE VOC discharge limits. |
| Joint Venture | Partnerships with hydrogen peroxide operators in Gujarat and Maharashtra industrial corridors secure offtake without local production. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydrogen peroxide plant managers, procurement leads at dye manufacturers, distribution channel partners, and technical R&D directors with secondary validation. Customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA registration databases anchored volume estimates. Bottom-up capacity assessments and top-down consumption models triangulated market sizing across grade tiers and end-use applications.
Historical reference periods spanning installed capacity expansions and regulatory milestone implementations anchored the projection horizon. The analytical framework modeled grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from segment-level growth rate reconciliation against macro chemical manufacturing indicators. Forecast inputs incorporated hydrogen peroxide capacity buildout schedules and REACH re-registration completion timelines.
Revisions become necessary when ECHA dossier requirement updates, MEE emission standard tightening, or feedstock cost dislocations materialize beyond modeled ranges. Forecasts reflect assumptions about continuous auto-oxidation process dominance and specification convergence between catalyst suppliers and peroxide operators. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
N-Pentyl Chloride Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Industrial Solvents Market
Solvents
Global Tert-Butanol Market
Solvents
Potassium Formate Market
Solvents
North America Acetonitrile Market
Solvents
North America Toluene Market
Solvents
Green Solvents Market
Solvents
Hydrocarbon Solvents Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Global Solvent Evaporation Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Phenylacetonitrile Market
Solvents
Global Xylenols Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Trichloroacetyl Chloride Market