
 Toluene Derivatives Market | 2026-2036
Toluene Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Toluene Derivatives Market Analytics
Pharmaceutical formulation is restructuring demand patterns across the Toluene Derivatives Market as parenteral drug manufacturers expand benzyl alcohol adoption for protein stabilization and preservative functions. BASF SE leverages its integrated aromatics chain to sustain cost-competitive benzyl alcohol supply to European drug manufacturers. Exxon Mobil Corporation anchors North American feedstock reliability through refinery-tied toluene extraction and downstream derivative coordination. Covestro AG specializes in high-purity benzoic acid streams for polycarbonate precursor synthesis, differentiating on specification consistency.
Toluene derivatives comprise aromatic compounds manufactured through oxidation, chlorination, sulfonation, or hydrogenation of toluene feedstock, typically achieving purities above 99.5% for pharmaceutical-grade benzyl alcohol and benzoic acid applications. These intermediates serve as essential building blocks for plastics, solvents, preservatives, and agrochemical actives across industrial chemistry. Benzoic acid dominates value capture due to its role in polyester plasticizers and alkyd resins, while benzyl alcohol exhibits the fastest structural expansion driven by injectable drug formulation requirements. Toluene sulfonic acid maintains mature demand in coatings catalyst applications, with margin pools concentrating in pharmaceutical-grade certification tiers.
EPA oversight of toluene emissions under the Clean Air Act shapes US manufacturing facility permitting and downstream product handling protocols. ECHA REACH registrations enforce purity documentation and supply chain communication obligations for European benzoic acid and benzyl chloride importers. China's MEE implements dual carbon goals that tighten energy efficiency benchmarks for toluene oxidation processes. Stakeholders must monitor evolving pharmaceutical-grade certification requirements and carbon border adjustment mechanisms to secure long-term contract viability.
Market Dynamics
Pharmaceutical-grade benzyl alcohol certification requirements are compressing supplier margins while concentrating volume among integrated aromatics producers capable of sustaining REACH documentation and dual-carbon compliance across their oxidation chains.
Growth Catalysts
- Injectable drug formulation expansion:Parenteral protein stabilization protocols are elevating benzyl alcohol uptake across sterile drug manufacturing, with FDA preservative guidelines tightening purity thresholds that favor certified suppliers.
- REACH registration enforcement:ECHA documentation mandates for benzoic acid and benzyl chloride importers are filtering out non-compliant traders, consolidating contract flows toward registered European manufacturers.
- China's oxidation capacity scaling:Domestic toluene derivative output expansion is displacing import dependency for regional coatings and adhesive formulators, redirecting trade flows within Asia-Pacific supply networks.
Market Restraints
- Feedstock cost volatility:Toluene pricing tracks crude oil and naphtha arbitrage windows, compressing derivative margins when upstream aromatics spike without downstream pass-through mechanisms.
- Supply concentration in coastal China:Over half of merchant benzoic acid capacity clusters in Shandong and Jiangsu provinces, exposing buyers to regional logistics disruptions and carbon-policy enforcement variability.
- Pharmaceutical-grade certification barriers:FDA and EMA validation timelines for benzyl alcohol excipient status extend 18-24 months, freezing new entrants from sterile drug supply chains regardless of technical capability.
Strategic Opportunities
- India specialty chemical expansion:CDSCO pharmaceutical-grade certification pathways and PLI scheme incentives are attracting benzoic acid derivative investment for domestic and export formulation supply.
- Biobased benzoic acid routes:Fermentation-derived aromatic platforms are converging with conventional oxidation economics, offering carbon-intensity credentials for EU Green Deal-aligned procurement mandates.
- Direct API manufacturer contracting:Bypassing traditional distributor tiers through qualified supplier programs is capturing margin compression from pharmaceutical procurement consolidation.
Industry Challenges
- Process analytical technology integration:Continuous manufacturing transitions for benzyl alcohol require PAT validation expertise scarce among legacy batch-optimized engineering teams.
- Multi-jurisdiction dossier maintenance:Sustaining concurrent FDA DMF, EMA CEP, and NMPA registration filings demands dedicated regulatory affairs capacity that mid-scale oxidation specialists struggle to staff.
- Legacy oxidation asset retrofit costs:China's MEE dual-carbon efficiency benchmarks are forcing catalytic reactor upgrades or shutdowns at aging toluene oxidation facilities without captive feedstock integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toluene Derivatives Market |
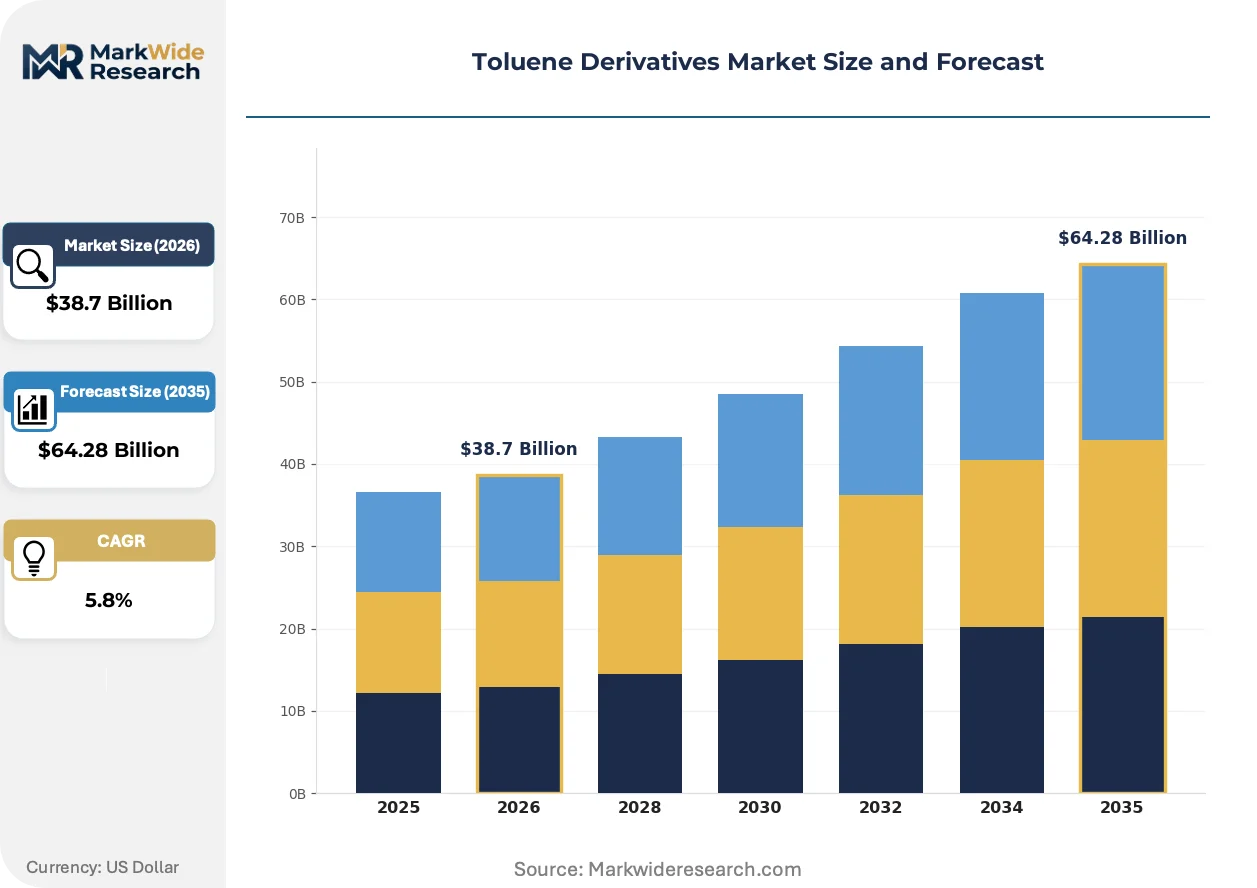
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzoic Acid, Benzyl Alcohol, Toluene Sulfonic Acid, Benzyl Chloride Application: Adhesives, Coatings, Pharmaceuticals, Agrochemicals End User: Chemical Manufacturing, Automotive, Construction, Consumer Goods Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | China Petroleum & Chemical Corporation, Exxon Mobil Corporation, Royal Dutch Shell, BASF SE, Covestro AG, SK Innovation, Formosa Chemicals & Fibre Corporation, LyondellBasell Industries, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toluene Derivatives Market Evolving Landscape
Catalytic process intensification and regulatory data transparency requirements are restructuring how toluene derivative producers compete on specification consistency and carbon accountability rather than scale alone.
Continuous flow oxidation technology is converging with real-time spectroscopic monitoring to enable tighter benzyl alcohol purity control. Pharmaceutical manufacturers in Germany and Switzerland are qualifying these systems for sterile drug excipient supply, compressing batch-to-batch variability that previously required extensive release testing and inventory buffering.
REACH Article 33 supply chain communication obligations are forcing benzoic acid importers to document SVHC content down to 0.1% concentration thresholds. Downstream polycarbonate precursor manufacturers are responding by sourcing exclusively from registered European producers, excluding non-EU traders from specification-critical applications regardless of price position.
Formulation houses are consolidating benzyl alcohol procurement through qualified supplier programs that bundle technical documentation, audit access, and volume commitments. This behavioral shift is displacing spot-market purchasing in parenteral drug manufacturing, with the transition most visible among mid-scale generic injectable producers in India seeking CDSCO inspection readiness.
Toluene Derivatives Market Segmentation
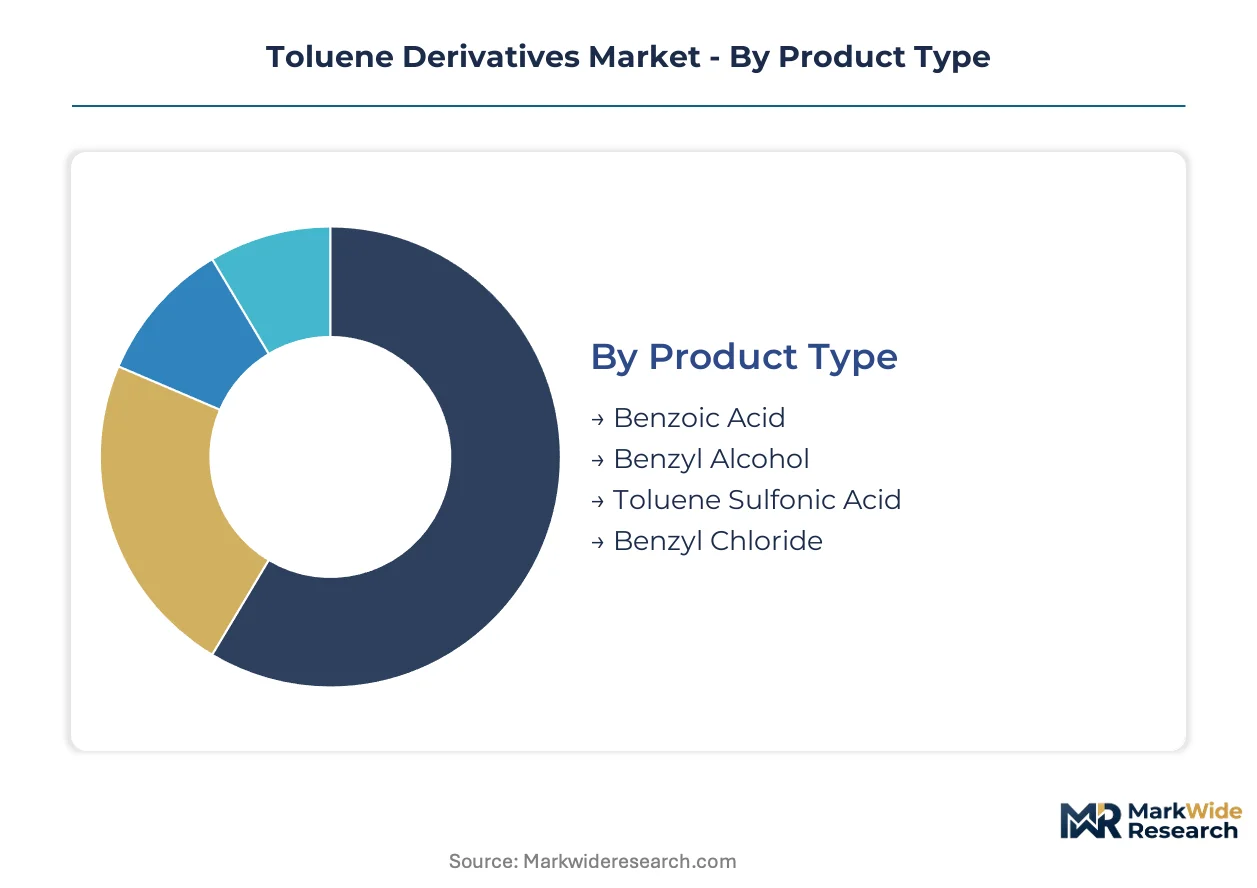
Toluene derivative producers compete across distinct specification tiers and end-use requirements that reshape margin capture. Segmentation reveals how pharmaceutical-grade certification, automotive coating specifications, and construction adhesive formulations concentrate value in differentiated supply streams.
Product Type:
Supply concentration clusters around oxidation-derived aromatics where integrated producers control feedstock-to-derivative economics.
- Benzoic Acid:White crystalline powder exceeding 99.5% purity serves polyester plasticizer and alkyd resin synthesis. Demand concentrates in Germany and China's Shandong province for polycarbonate precursor manufacturing, with REACH registration requirements filtering non-compliant importers from European specification-critical supply.
- Benzyl Alcohol:Clear liquid aromatic alcohol functions as parenteral drug preservative and protein stabilizer. Injectable formulation expansion across Swiss and Indian sterile drug manufacturers drives uptake, though FDA DMF validation timelines extending 18-24 months freeze new entrants from excipient supply chains.
- Toluene Sulfonic Acid:Strong organic acid catalyst dominates esterification reactions in industrial coatings production.
- Benzyl Chloride:Colorless reactive intermediate feeds agrochemical active and fragrance compound synthesis, with chlorination process emissions subject to EPA Clean Air Act permitting.
Today's leader: Benzoic Acid. Tomorrow's challenger: Benzyl Alcohol.
Application:
Cost tier differentiation separates commodity-grade from pharmaceutical-certified streams, with certification premiums widening.
- Pharmaceuticals:Sterile drug formulation demands benzyl alcohol excipient grades meeting USP-NF and EP monographs. Parenteral protein stabilization protocols across German and Swiss manufacturers elevate uptake, with procurement consolidating through qualified supplier programs that bundle audit access and technical documentation.
- Coatings:Alkyd resin and polyester formulations consume benzoic acid for plasticizer integration. Automotive OEM specification tightening in Germany and Japan drives high-purity requirements, with toluene sulfonic acid catalysis enabling low-temperature cure systems.
- Adhesives:Construction and packaging bonding applications utilize benzoic acid derivatives for tackifier modification.
- Agrochemicals:Benzyl chloride intermediates synthesize herbicide and fungicide actives for crop protection formulators.
Volume concentrates in Coatings. Margin concentrates in Pharmaceuticals.
End User:
Customer type segmentation reveals how captive consumption versus merchant supply reshapes contract structures and pricing transparency.
- Chemical Manufacturing:Integrated aromatics producers consume toluene derivatives internally for downstream polymer and specialty chemical synthesis. BASF's Ludwigshafen complex exemplifies captive benzoic acid consumption for polycarbonate precursor manufacturing, insulating from merchant market volatility.
- Automotive:OEM coating specifications drive high-purity benzoic acid demand for exterior finish durability and corrosion resistance.
- Construction:Adhesive and sealant formulators source benzoic acid for modified alkyd binders in structural applications.
- Consumer Goods:Personal care and household product manufacturers utilize benzyl alcohol as fragrance solvent and preservative.
Captive consumption dominates Chemical Manufacturing. Merchant growth concentrates in Automotive specification tightening.
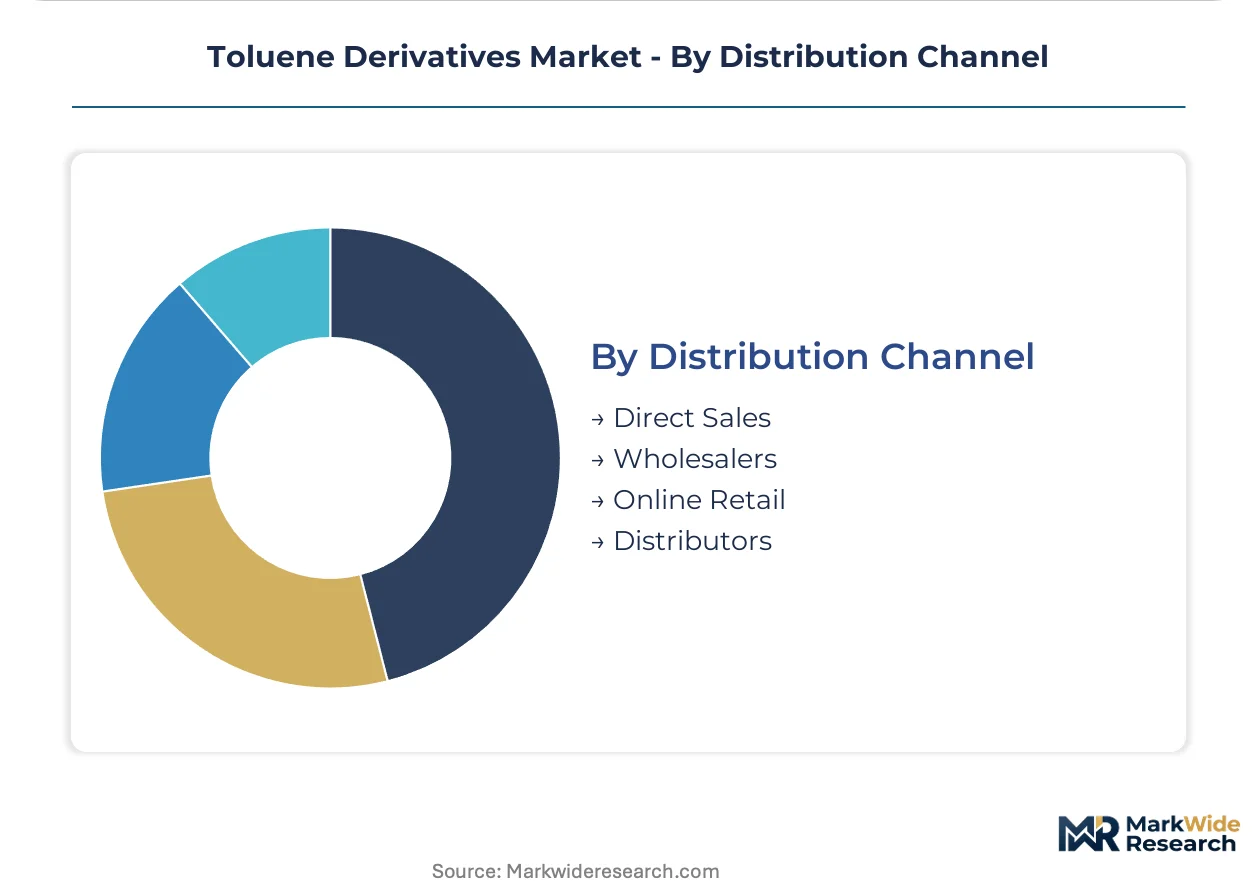
Distribution Channel:
Geography of demand reshapes channel selection, with qualified supplier programs displacing traditional wholesale tiers in pharmaceutical supply.
- Direct Sales:Long-term contracts link integrated producers to pharmaceutical API manufacturers and automotive coating formulators. Technical service bundling and audit access justify channel preference for sterile drug excipient supply, with Swiss and German manufacturers leading qualification.
- Distributors:Regional chemical distributors serve mid-scale coatings and adhesive formulators with inventory buffering and blended shipment logistics.
- Wholesalers:Volume aggregation for construction and consumer goods applications enables price discovery in less specification-critical segments.
- Online Retail:Emerging channel for laboratory-scale and specialty grade procurement, with documentation limitations restricting pharmaceutical-grade penetration.
Direct Sales commands pharmaceutical value. Distributors retain coatings and construction share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting toluene derivative investment toward jurisdictions with clearer certification pathways and lower compliance friction, while mature markets impose documentation burdens that filter merchant traders from specification-critical supply chains.
China
Domestic oxidation capacity scaling in Shandong and Jiangsu provinces is displacing import dependency for regional coatings and adhesive formulators. MEE dual-carbon efficiency benchmarks are forcing catalytic reactor upgrades at aging facilities without captive feedstock integration. Merchant benzoic acid output concentrates in coastal clusters serving polycarbonate precursor demand from local polymer producers.
Germany
Automotive OEM coating specifications drive high-purity benzoic acid demand for exterior finish durability and corrosion resistance. ECHA REACH registration requirements filter non-compliant importers from European specification-critical supply, consolidating contract flows toward registered domestic manufacturers. BASF's Ludwigshafen complex exemplifies captive consumption insulating from merchant market volatility.
United States
EPA Clean Air Act oversight shapes manufacturing facility permitting and downstream product handling protocols for toluene oxidation processes. Refinery-tied toluene extraction anchors North American feedstock reliability through downstream derivative coordination. Gulf Coast petrochemical corridors sustain cost-competitive supply to pharmaceutical and coatings formulators.
India
CDSCO pharmaceutical-grade certification pathways and PLI scheme incentives are attracting benzoic acid derivative investment for domestic and export formulation supply. Parenteral drug manufacturers in Gujarat and Maharashtra are expanding benzyl alcohol uptake for protein stabilization. Mid-scale generic injectable producers are consolidating procurement through qualified supplier programs.
Switzerland
Swissmedic oversight and stringent pharmaceutical manufacturing standards elevate benzyl alcohol excipient requirements for sterile drug formulation. German and Swiss manufacturers lead qualification of continuous flow oxidation systems for tighter purity control. Basel-region pharmaceutical clusters drive specification premiums that favor certified European suppliers over merchant traders.
Toluene Derivatives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated aromatics producers commanding pharmaceutical-grade certification tiers while merchant traders retain coatings and construction volume. The vendor base concentrates around three strategic archetypes: captive-integrated petrochemical majors, standalone oxidation specialists, and regional distributors with inventory buffering capabilities. M&A activity targets backward integration into toluene feedstock security, while capacity expansion concentrates in coastal China and the US Gulf Coast.
Among integrated petrochemical majors, China Petroleum & Chemical Corporation and Exxon Mobil Corporation exemplify the captive-consumption archetype, leveraging refinery-tied feedstock access to sustain cost-competitive derivative supply. BASF SE occupies a position representing European specification leadership, anchoring REACH-registered supply chains for pharmaceutical and automotive coating applications. These three entities illustrate how feedstock integration and regulatory documentation capacity concentrate contract flows in an increasingly filtered competitive environment.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| Exxon Mobil Corporation |
| Royal Dutch Shell |
| BASF SE |
| Covestro AG |
| SK Innovation |
| Formosa Chemicals & Fibre Corporation |
| LyondellBasell Industries |
| SABIC |
| Others |
Value Network & Pricing Analysis
Integrated petrochemical majors with refinery-tied feedstock access anchor supply discipline, while standalone oxidation specialists face margin compression from pharmaceutical-grade certification investments and China's MEE dual-carbon compliance costs. This ownership split concentrates pricing power among backward-integrated producers capable of absorbing regulatory documentation burdens without spot-market exposure.
Pricing Analysis
Direct-to-pharmaceutical-manufacturer contracts command premium spreads over distributor-mediated coatings supply, with three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade benzoic acid streams. FDA DMF and EMA CEP certification tiers widen price differentiation by fifteen-to-twenty percentage points against uncertified merchant supply. Cost compression in technical-grade benzoic acid intensifies because Shandong province capacity additions outpace coatings demand growth. Generic injectable producers in India exhibit highest price sensitivity, while Swiss and German sterile drug manufacturers prioritize audit access and documentation bundling over unit economics.
Supply Chain Analysis
Specialized chemical engineering talent scarcity in Germany's Ludwigshafen corridor and Switzerland's Basel region constrains continuous flow oxidation system deployment. Merchant benzoic acid supply concentrates in China, Germany, and the United States, with Shandong province oxidation clusters feeding Asia-Pacific polycarbonate precursor demand. Feedstock toluene draws from refinery aromatics extraction and naphtha cracking operations tethered to crude oil price volatility. Single-source vulnerability runs through coastal China's carbon-policy enforcement variability, which threatens unannounced production halts at aging oxidation assets. Distribution runs through qualified supplier programs for pharmaceutical-grade benzyl alcohol, while regional chemical distributors retain coatings and construction adhesive volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Toluene Derivatives Market represents a late-cycle quality story as parenteral drug formulation protocols elevate pharmaceutical-grade benzyl alcohol specifications above commodity oxidation economics.
For Market Incumbents: To counter margin compression from REACH registration documentation and MEE dual-carbon retrofit requirements, BASF SE and Exxon Mobil Corporation should deepen backward integration into refinery-tied toluene feedstock security while accelerating continuous flow oxidation technology deployment for batch-to-batch variability reduction. Captive consumption at Ludwigshafen and Gulf Coast petrochemical corridors insulates integrated majors from merchant market volatility that threatens standalone oxidation specialists. For New Entrants and Emerging Players: Capture white-space opportunity in India's CDSCO-certified benzyl alcohol supply for domestic generic injectable producers consolidating procurement through qualified supplier programs. Fermentation-derived biobased benzoic acid routes offer penetrable positioning for EU Green Deal-aligned procurement mandates, with carbon-intensity credentials differentiating against conventional oxidation economics. Direct API manufacturer contracting bypasses distributor margin layers that concentrate in European pharmaceutical supply. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone oxidation specialists without captive feedstock integration or pharmaceutical-grade certification dossiers. Long-term viability over the next decade hinges on REACH-registered European assets with established EMA CEP filings and dual-carbon compliance infrastructure already deployed. Watch for NMPA registration acceleration among Indian benzoic acid derivative producers as the inflection signal for Asia-Pacific specification-critical supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Feedstock | Refinery-tied aromatics extraction secures cost-competitive supply for oxidation chains at BASF Ludwigshafen and Sinopec Shandong complexes. |
| Pharmaceutical-Grade Certification Investment | FDA DMF and EMA CEP filings unlock sterile drug excipient supply to Swiss and German parenteral manufacturers. |
| Continuous Flow Oxidation Deployment | Real-time spectroscopic monitoring enables tighter benzyl alcohol purity control for protein stabilization protocols. |
| Biobased Benzoic Acid Route Development | Fermentation-derived aromatic platforms align with EU Green Deal carbon-intensity procurement mandates. |
| Qualified Supplier Program Participation | Technical documentation bundling and audit access displace spot-market purchasing among Indian generic injectable producers. |
Research Methodology
Coverage spans China, Germany, the United States, India, and Switzerland, with primary inputs from each regional cluster combining interviews with plant managers at oxidation facilities, procurement leads at downstream pharmaceutical and coatings OEMs, distribution channel partners, and technical R&D directors specializing in catalytic process intensification. Secondary validation draws from customs and trade data, Cefic and ACC industry reports, SEC 10-K filings, ECHA REACH registration databases, and FDA DMF filings. Bottom-up capacity and consumption modeling triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with segmentation modeling across product type, application, end user, and distribution channel dimensions. CAGRs derive from regression analysis against historical capacity utilization, feedstock cost pass-through elasticity, and regulatory enforcement intensity. Industry-specific forecast inputs include pharmaceutical formulation expansion rates for parenteral drugs and automotive OEM coating specification tightening in Germany and Japan.
Feedstock cost volatility, regulatory enforcement acceleration, and pharmaceutical-grade certification timeline extensions are the dominant revision risks that could compress or extend projected market trajectories. Forecasts reflect assumptions about sustained REACH registration compliance and MEE dual-carbon benchmark implementation without material deviation in enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Dihydromyrcenol Market
Solvents
Acetone Derivatives Market
Solvents
Global Chloroform Market
Solvents
Methyl Formate Market
Solvents
Fluorinated Solvents Market
Solvents
Ethoxydiglycol Market
Solvents
Global Glycidol Market
Solvents
Hydrocarbon Solvents Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Dihydromyrcene Market
Solvents
Pharmaceutical Solvent Market
Solvents
Wax Dispersion Market
Solvents
N-Pentyl Chloride Market
Solvents
Citrus Solvents Market
Solvents
Methyl Ethyl Ketone (MEK) Market