
 Green Solvents and Bio-Solvents Market | 2026-2036
Green Solvents and Bio-Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Green Solvents and Bio-Solvents Market Foresight
Direct procurement partnerships between bio-refinery operators and specialty chemical distributors is rewriting how green solvents reach industrial formulators. BASF SE leverages its integrated biotechnology platforms to secure feedstock certainty across European manufacturing networks. Cargill Incorporated anchors North American supply through corn-derived ethanol infrastructure that sustains cost parity with conventional solvents. Evonik Industries AG competes on fermentation-derived specialty alcohols that differentiate performance in high-purity pharmaceutical applications.
Green solvents and bio-solvents comprise renewable-derived liquid media formulated from biomass feedstocks including corn starch, sugarcane bagasse, and vegetable oils, typically achieving purity grades above 99.5% through molecular distillation or enzymatic refinement processes that replace petroleum-derived aromatic and aliphatic hydrocarbons in industrial formulations. Ethyl lactate dominates margin pools in precision cleaning and electronics applications where low toxicity and biodegradability command premium positioning. Ethanol leads volume throughput across paints and coatings formulations where VOC compliance mandates have accelerated substitution timelines. Propanol occupies a specialized niche in pharmaceutical synthesis where residual solvent guidelines from pharmacopeial authorities constrain acceptable impurity profiles.
EPA VOC regulations and REACH authorization requirements are forcing reformulation investments across coatings and adhesives manufacturers, while FDA residual solvent guidelines in ICH Q3C constrain bio-solvent qualification pathways for pharmaceutical excipients. The EU Green Deal chemical strategy and state-level air quality mandates in California and New York are converging to expand addressable demand. Stakeholders must monitor feedstock price volatility in agricultural commodities and the pace of fermentation scale-up to assess capacity adequacy against tightening compliance deadlines.
Market Dynamics
REACH authorization deadlines are compressing substitution timelines for petrochemical solvents across European coatings and pharmaceutical supply chains. Formulators face immediate reformulation mandates as ECHA adds aromatic hydrocarbons to the SVHC candidate list, forcing capital redeployment toward fermentation-derived alternatives before 2030 compliance cliffs.
Growth Catalysts
- EU Green Deal chemical strategy:The strategy mandates renewable feedstock quotas in industrial solvents, compelling coatings manufacturers in Germany and France to qualify bio-based ethyl lactate for automotive refinish applications.
- Pharmaceutical residual solvent guidelines:ICH Q3C impurity thresholds are disqualifying traditional chlorinated solvents from active pharmaceutical ingredient synthesis, opening qualification pathways for bio-propanol in sterile manufacturing.
- Electronics precision cleaning:Semiconductor fabricators in the Netherlands are substituting N-methyl-2-pyrrolidone with bio-derived formulations to meet customer sustainability scorecard requirements.
Market Restraints
- Agricultural commodity volatility:Corn starch and sugarcane bagasse prices fluctuate with weather patterns and ethanol policy shifts, compressing margin stability for bio-refinery operators.
- Fermentation scale-up bottlenecks:Industrial biotechnology capacity concentrates in established European and North American clusters, limiting supply elasticity against sudden regulatory demand spikes.
- Performance parity gaps:Bio-solvent evaporation rates and solvency parameters in high-temperature coatings lag petrochemical benchmarks, restricting adoption in aerospace and marine protective systems.
Strategic Opportunities
- India specialty chemicals expansion:CDSCO alignment with ICH guidelines creates first-mover advantage for bio-solvent suppliers qualifying excipient grades for domestic generic pharmaceutical production.
- Carbon accounting integration:CSRD disclosure requirements position bio-solvent procurement as Scope 3 reduction lever for EU-based multinational formulators seeking supply chain decarbonization.
- Enzymatic refinement advances:Continuous processing technology from synthetic biology platforms collapses unit production costs for high-purity lactate esters, enabling price competition in commodity coatings segments.
Industry Challenges
- Pharmacopeial certification timelines:USP-NF and EP monograph updates for novel bio-solvent grades require multi-year stability data packages, delaying commercial launch in injectable drug formulations.
- Blending infrastructure retrofit:Existing solvent storage and distribution networks require material compatibility verification and tank cleaning protocols before handling hygroscopic bio-alcohols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Solvents and Bio-Solvents Market |
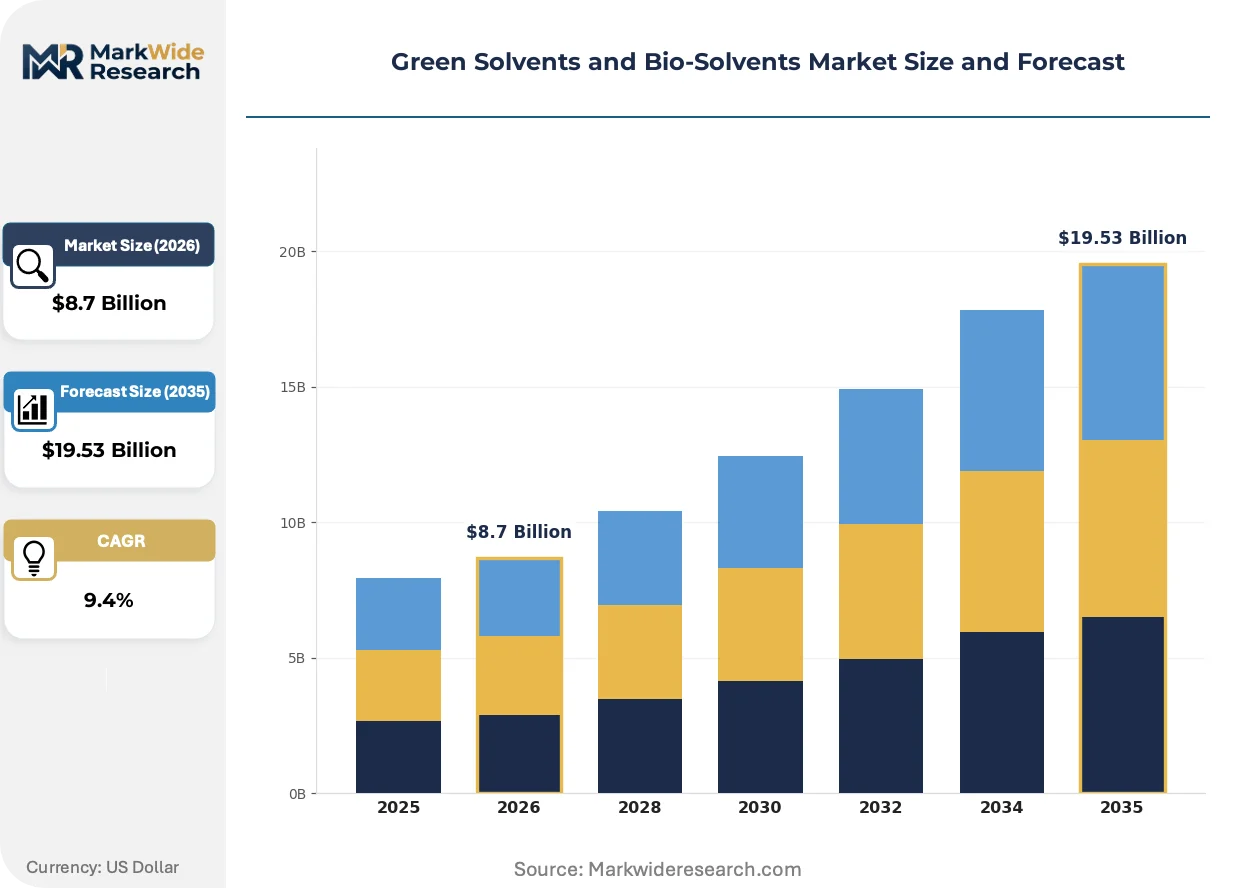
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetone, Ethanol, Propanol, Ethyl Lactate Application: Paints, Coatings, Adhesives, Cleaning Agents End User: Manufacturing, Automotive, Pharmaceuticals, Food Industry Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Dow Inc., Solvay, Cargill Incorporated, Corbion, LyondellBasell Industries Holdings, Evonik Industries AG, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Solvents and Bio-Solvents Market Shifts & Advancements
Biotechnology platforms are collapsing the cost structure of specialty solvent production while regulatory disclosure mandates rewire buyer-supplier relationships. Three concurrent developments are restructuring competitive position.
Continuous enzymatic esterification is collapsing the capital intensity barrier between commodity ethanol and high-margin specialty esters. Pharmaceutical excipient manufacturers in Switzerland and Germany are adopting modular bioreactor systems that convert corn-derived feedstock directly to USP-grade ethyl lactate without intermediate isolation steps. This bypass is collapsing the traditional toll-manufacturing layer that previously captured margin in multi-step chemical synthesis.
REACH sunset date acceleration for N-methyl-2-pyrrolidone and glycol ethers is forcing coatings formulators to requalify entire product lines before 2026 authorization reviews. Industrial maintenance coating suppliers in France and Belgium are submitting dossiers for bio-based dipropylene glycol alternatives to secure downstream customer continuity. The segment most affected—automotive OEM refinish—responds by consolidating supplier panels to those with verified renewable feedstock certification.
Direct contracting between bio-refinery operators and formulator procurement functions is displacing traditional distributor intermediaries in solvent categories above 500-ton annual volume. Coatings manufacturers in the Netherlands now negotiate fixed-price, multi-year supply agreements for bio-ethanol that transfer price volatility risk upstream. This pattern is most visible in architectural paint supply chains where sustainability scorecard weighting in retailer selection criteria concentrates purchasing power with certified renewable suppliers.
Green Solvents and Bio-Solvents Market Segmentation
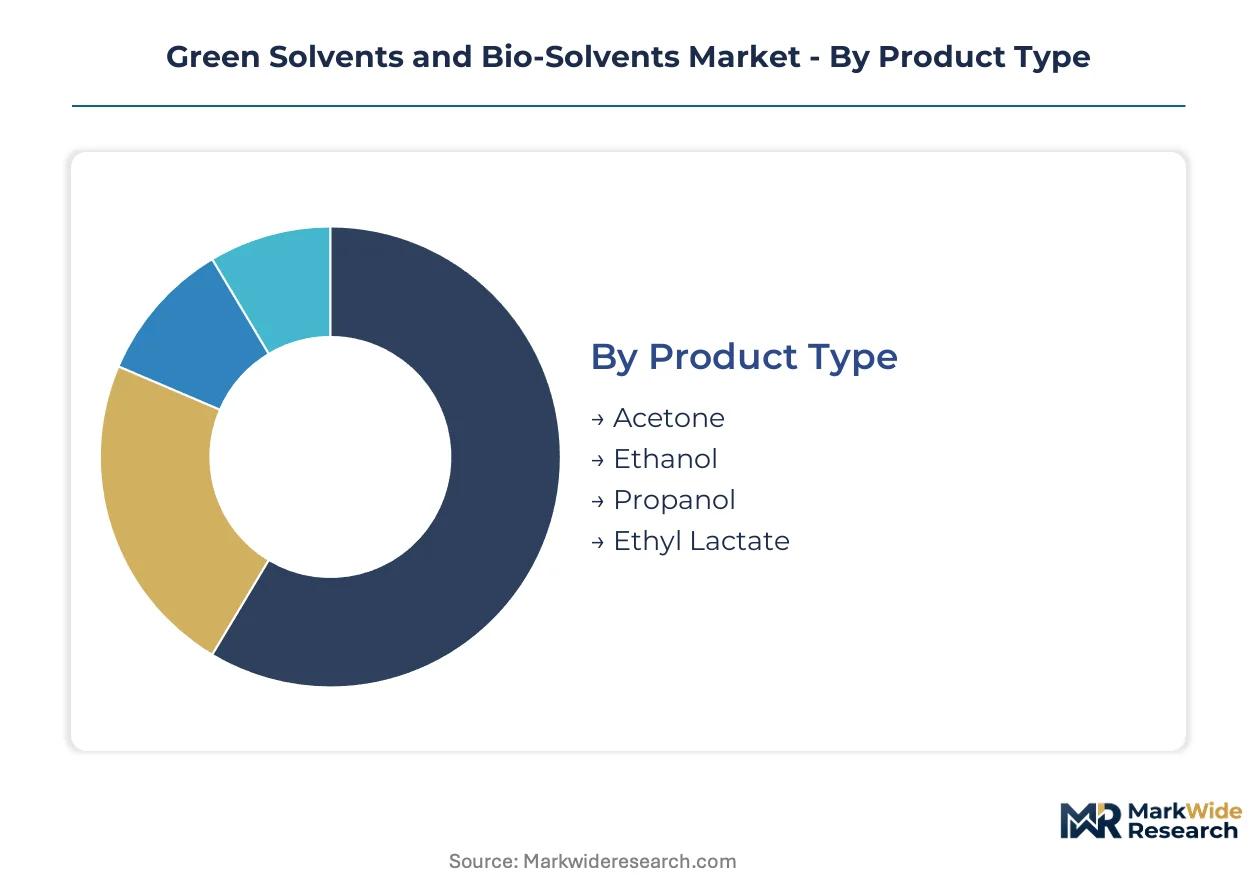
Segmentation in green solvents reveals how regulatory pressure and feedstock economics split demand across purity grades and end-use specifications. Manufacturers configure production assets differently for pharmaceutical-grade fermentation outputs versus commodity coatings formulations.
Product Type:
Cost tier structures separate commodity alcohols from specialty esters with distinct margin profiles and capital requirements.
- Ethanol:Corn and sugarcane fermentation yields industrial-grade alcohol above 99.5% purity through molecular sieving. Volume concentrates in architectural coatings across Germany and France where VOC mandates have compressed substitution timelines for aromatic hydrocarbons.
- Ethyl Lactate:Esterification of lactic acid with ethanol produces a biodegradable solvent with low surface tension for precision cleaning. Demand clusters in Netherlands semiconductor fabrication and Swiss pharmaceutical excipient manufacturing where customer sustainability scorecards weight renewable content.
- Acetone:Bio-based routes through fermentation-derived isopropanol oxidation remain cost-challenged against petrochemical cumene processes.
- Propanol:Fermentation-derived n-propanol serves pharmaceutical synthesis with pharmacopeial-grade specifications for residual solvent limits.
Ethanol commands the established base. The steepest expansion runs through ethyl lactate.
Application:
Application mix tracks how regulatory deadlines cascade through coatings, adhesives, and cleaning product supply chains.
- Paints:Waterborne acrylic and alkyd formulations incorporate bio-ethanol as co-solvent to balance open time and VOC compliance. German automotive refinish shops have qualified bio-based systems ahead of REACH authorization reviews.
- Cleaning Agents:Precision electronics cleaning demands ultra-low residue specifications that bio-ethyl lactate satisfies for Netherlands semiconductor fabricators replacing N-methyl-2-pyrrolidone.
- Coatings:Industrial maintenance applications in Belgium and France are requalifying dipropylene glycol alternatives ahead of sunset dates.
- Adhesives:Pressure-sensitive adhesive formulations in packaging applications face less stringent performance requirements that accommodate bio-solvent evaporation rate profiles.
Paints anchor current volume. Cleaning agents climb the fastest on semiconductor capital expansion.
End User:
Customer type determines specification stringency from food-grade purity to pharmaceutical monograph compliance.
- Pharmaceuticals:ICH Q3C residual solvent guidelines disqualify chlorinated hydrocarbons from active ingredient synthesis, opening qualification pathways for bio-propanol in sterile manufacturing suites.
- Automotive:OEM refinish operations in Germany consolidate supplier panels to certified renewable feedstock holders as retailer sustainability scorecards concentrate purchasing power.
- Manufacturing:General industrial formulators across France and Belgium face immediate reformulation mandates as ECHA expands SVHC candidate listings.
- Food Industry:Extraction and processing applications require GRAS or food-grade certifications that bio-ethanol from corn starch satisfies for flavor and fragrance compounds.
Manufacturing holds the volume base. Pharmaceuticals gain share fastest on regulatory exclusion of traditional solvents.
Distribution Channel:
Channel structure reflects volume scale and the displacement of intermediaries in large-account procurement.
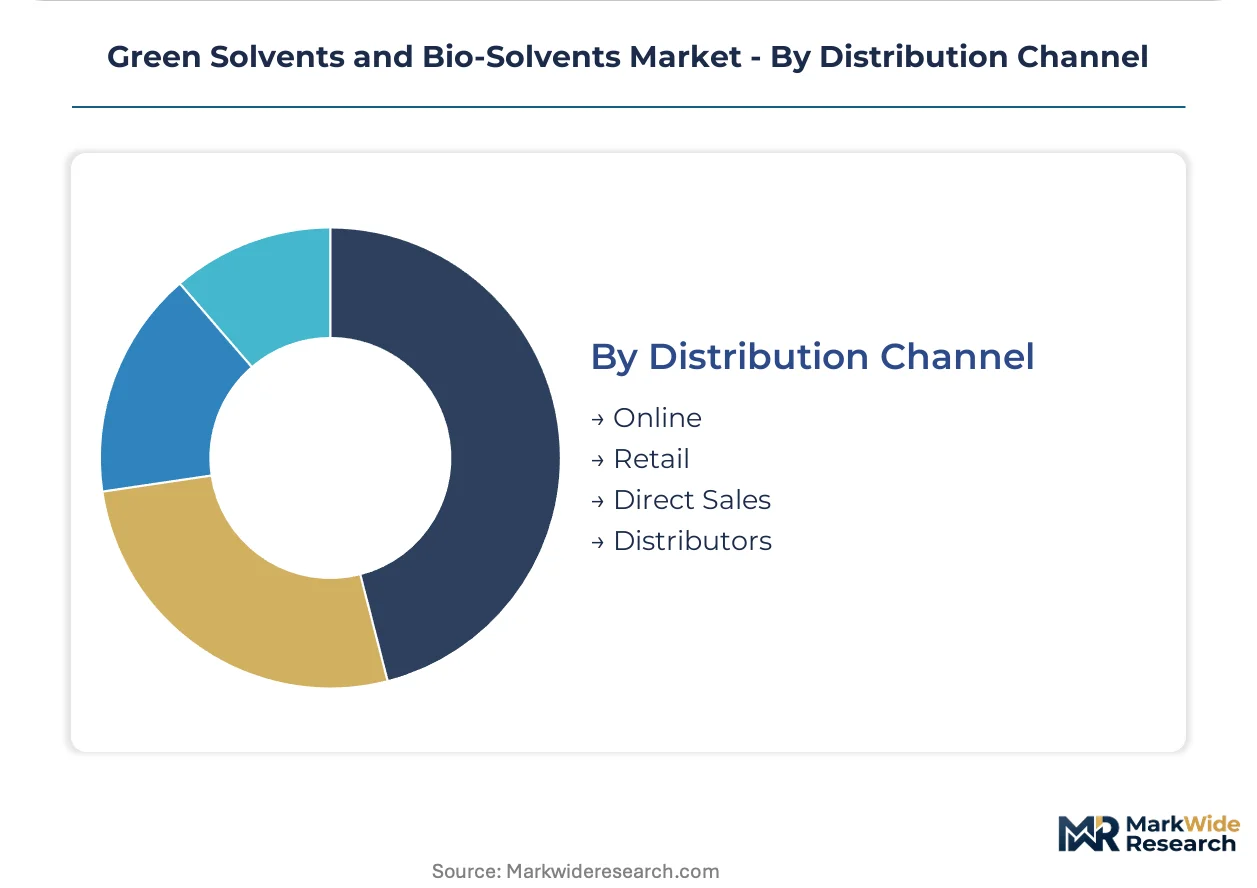
- Direct Sales:Coatings manufacturers above 500-ton annual volume negotiate fixed-price, multi-year supply agreements that transfer agricultural commodity volatility risk upstream to bio-refinery operators.
- Distributors:Specialty chemical distributors retain role in fragmented small-volume accounts requiring technical service and blending capabilities.
- Online:Digital procurement platforms serve research-scale and pilot-batch customers with catalog-grade specifications.
- Retail:Architectural paint and consumer cleaning product channels move packaged bio-solvent formulations through building supply and home improvement networks.
Direct sales command the established base. The steepest expansion runs through distributor partnerships with certified renewable portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's biofuel terminal infrastructure anchors European green solvent distribution, handling fermentation-derived ethanol and ethyl lactate shipments from North Sea bio-refineries to coatings manufacturers across the continent.
Germany
Automotive OEM refinish operations in Stuttgart and Munich drive bio-ethanol demand for waterborne coating systems. REACH authorization reviews from ECHA compress substitution timelines for aromatic hydrocarbons ahead of 2026 deadlines. The BASF Ludwigshafen complex anchors integrated biotechnology platforms supplying fermentation-derived specialty alcohols to pharmaceutical manufacturers.
United States
Corn belt ethanol infrastructure sustains cost parity for bio-solvents against petrochemical benchmarks in architectural coatings. EPA VOC regulations in California and New York accelerate reformulation investments across adhesives and cleaning product supply chains. The Gulf Coast petrochemical corridor hosts retrofitted fermentation capacity serving pharmaceutical-grade propanol demand from New Jersey manufacturing clusters.
Netherlands
Semiconductor fabricators in Eindhoven substitute N-methyl-2-pyrrolidone with bio-derived precision cleaning formulations. CSRD disclosure requirements position bio-solvent procurement as Scope 3 reduction lever for EU-based multinational formulators. The Rotterdam-Botlek industrial zone concentrates enzymatic esterification capacity for high-purity ethyl lactate production.
India
Domestic generic pharmaceutical production expansion creates qualification pathways for bio-propanol in sterile manufacturing suites. CDSCO alignment with ICH Q3C guidelines opens excipient-grade bio-solvent markets previously blocked by residual solvent restrictions. Maharashtra and Gujarat host emerging fermentation capacity targeting food-grade ethanol for flavor and fragrance extraction applications.
Switzerland
Pharmaceutical excipient manufacturers in Basel adopt modular bioreactor systems for USP-grade ethyl lactate production. Swissmedic pharmacopeial certification timelines constrain novel bio-solvent commercial launch in injectable drug formulations. The Swiss-German border region concentrates precision fermentation expertise serving high-purity solvent demand from Novartis and Roche supply chains.
Green Solvents and Bio-Solvents Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and fermentation technology. The market structures around three tiers: diversified chemical conglomerates with integrated biotechnology assets, agricultural processors leveraging crop-derived feedstock advantages, and specialty fermentation houses competing on purity grades. Consolidation pressure concentrates among coatings and pharmaceutical formulators seeking supply security against agricultural commodity volatility. Dominant competitive moves include backward integration into corn starch and sugarcane supply bases, plus multi-year direct contracting that transfers price risk upstream.
Among diversified chemical conglomerates, BASF SE and Evonik Industries AG represent platform integrators with European biotechnology infrastructure. Cargill Incorporated exemplifies the agricultural processor archetype, anchoring North American supply through crop-derived ethanol networks. These three occupy positions across distinct competitive tiers without overlapping strategic emphasis.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Dow Inc. |
| Solvay |
| Cargill Incorporated |
| Corbion |
| LyondellBasell Industries Holdings |
| Evonik Industries AG |
| Clariant AG |
| Others |
Supply & Pricing Matrix
The Rotterdam-Botlek industrial zone anchors European bio-solvent capacity, where enzymatic esterification clusters concentrate production economics and transfer pricing leverage downstream to coatings formulators negotiating multi-year supply agreements.
Pricing Analysis
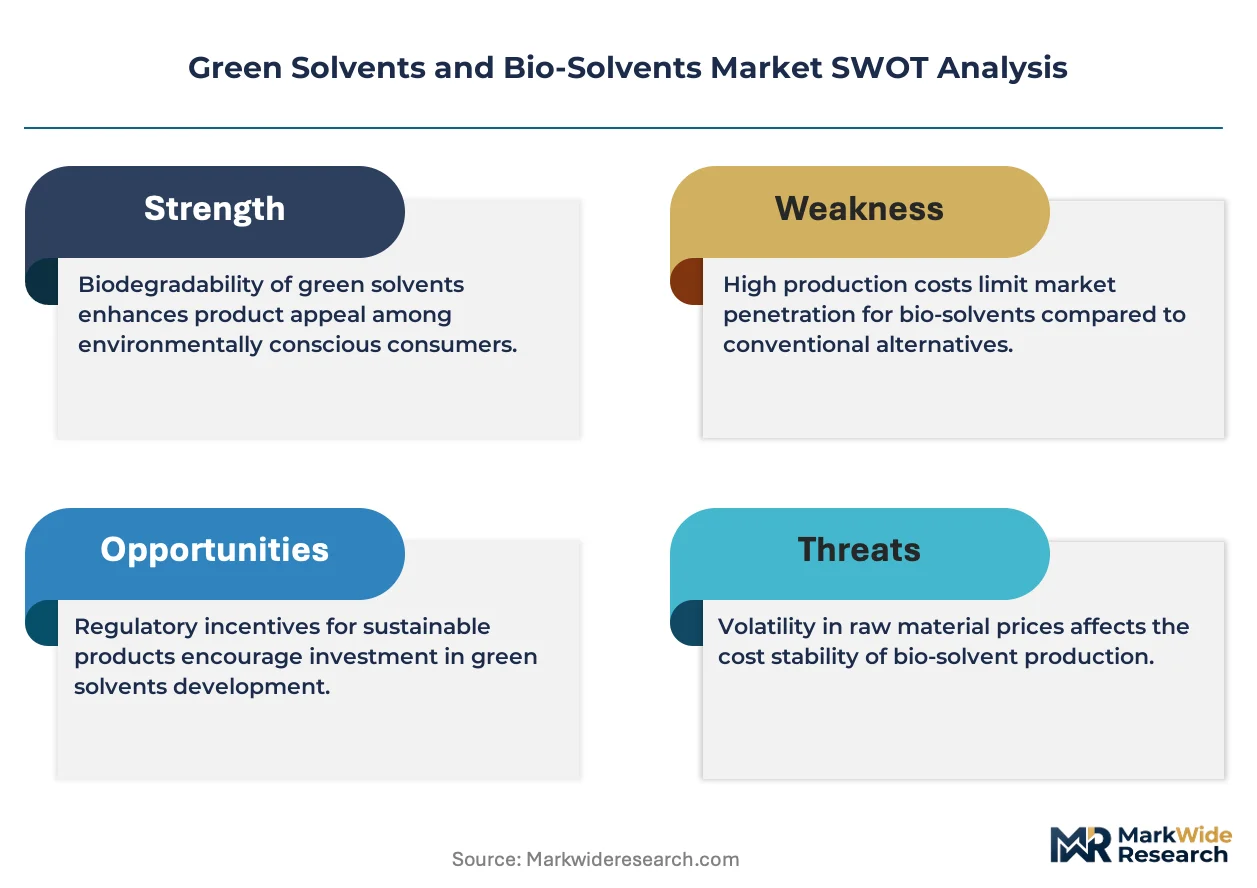
Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade levels separates margin pools by certification stringency and purity thresholds. Price differentiation rests on USP-NF monograph compliance versus technical-grade specifications, with volume-scale discounts compressing unit costs for coatings manufacturers above 500-ton annual offtake. Cost compression in commodity ethanol is intensifying because corn starch feedstock volatility transfers margin pressure from agricultural markets. Small-batch pharmaceutical formulators exhibit highest price sensitivity, while semiconductor fabricators accept premium positioning for ultra-low residue specifications.
Supply Chain Analysis
Export-control restrictions on fermentation technology licensing limit capacity expansion in emerging production regions, constraining supply elasticity against regulatory demand spikes. Production concentrates in Germany, the Netherlands, and the United States, where established bio-refinery infrastructure draws from corn starch, sugarcane bagasse, and vegetable oil feedstocks. Single-source vulnerability concentrates in lactic acid supply for ethyl lactate esterification, with distribution running through direct procurement partnerships that displace traditional distributor intermediaries in large-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical upswing driven by REACH authorization deadlines compressing substitution timelines for petrochemical solvents across European coatings and pharmaceutical supply chains.
For Market Incumbents: Insulate margin positions through backward integration into corn starch and sugarcane supply bases, securing feedstock certainty against agricultural commodity volatility. Lock in multi-year direct contracting with coatings manufacturers above 500-ton annual volume to transfer price risk upstream and defend against emerging fermentation houses competing on purity grades.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical excipient markets where CDSCO alignment with ICH Q3C guidelines creates qualification pathways for bio-propanol in sterile manufacturing. Target modular bioreactor system deployments that collapse capital intensity barriers between commodity ethanol and high-margin specialty esters, leveraging technical service partnerships to bypass established distributor networks.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA VOC mandates and REACH sunset dates structurally expand addressable demand regardless of macro cyclicality. Target specialty fermentation houses with verified pharmacopeial certifications and captive corn-derived feedstock infrastructure. Watch ECHA SVHC candidate list expansion velocity as the inflection signal for substitution timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn starch and sugarcane supply base control insulates margin stability against agricultural commodity price spikes. |
| Long-term Supply Agreement | Fixed-price multi-year contracts with coatings manufacturers transfer price volatility risk upstream to bio-refinery operators. |
| Green Manufacturing Transition | Continuous enzymatic esterification adoption collapses unit production costs for USP-grade ethyl lactate in pharmaceutical applications. |
| Joint Venture | Partnerships between bio-refinery operators and specialty chemical distributors rewrite channel economics for fragmented small-volume accounts. |
| Capacity Expansion | Fermentation scale-up in Maharashtra and Gujarat targets food-grade ethanol demand from India's flavor and fragrance extraction sector. |
Research Methodology
Initial hypotheses were tested against primary input from bio-refinery plant managers, coatings procurement leads at downstream OEMs, pharmaceutical regulatory affairs directors, and specialty chemical distribution channel partners and refined through secondary validation against ECHA authorization databases, EU customs trade data, SEC 10-K filings from diversified chemical conglomerates, and CDSCO regulatory alignment notifications. Bottom-up volume triangulation across feedstock fermentation capacity and top-down demand aggregation from end-use industry substitution timelines were reconciled to establish market sizing.
Demand-supply balance modeling across the projection horizon incorporated grade-tier segmentation, end-use industry application mix, regional production hub concentration, and certification-level purity requirements. CAGRs were derived from regression analysis of historical substitution rates against regulatory deadline proximity, with forecast inputs including REACH sunset date acceleration schedules and semiconductor capital expansion pipelines for precision cleaning applications.
Macroeconomic conditions sit as an overlay; deviation in corn futures pricing and ethanol policy shifts would shift the trajectory of bio-solvent cost parity against petrochemical benchmarks. Forecasts reflect documented assumptions regarding fermentation scale-up timelines and pharmacopeial certification completion rates. Cross-checking against ECHA SVHC candidate list update frequency and EPA VOC regulatory action calendars is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Fluorinated Solvents Market
Solvents
Diethanolamine (DEA) Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Dihydromyrcenol Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Global Furfural Solvent Market
Solvents
Japan Acetonitrile Market
Solvents
Vapor Degreasing Solvents Market
Solvents
N-Hexane Market
Solvents
Acetone Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Citrus Solvents Market
Solvents
Decanol Market
Solvents
GCC Acetonitrile Market