
 Piperylene Market | 2026-2036
Piperylene Market Size, Share, and Industry Trends Forecast 2026-2036
Piperylene Market Outlook
Specialty chemical distribution is narrowing as integrated producers consolidate direct-to-miller relationships. ZEON Corporation leverages captive piperylene supply from its Japanese petrochemical complexes to serve Asian rubber manufacturers. Eastman Chemical Company anchors North American demand through backward integration into C5 fraction separation. Shell Chemicals competes on global scale, operating dedicated piperylene extraction units across multiple refining corridors.
Piperylene is a conjugated diolefin hydrocarbon with the formula C5H8, typically recovered from steam cracker C5 fractions at purity grades ranging from 65% to 90% depending on end-use requirements. It serves primarily as a monomer feedstock for aliphatic hydrocarbon resins, unsaturated polyester resins, and specialty elastomers. The polymer grade segment dominates value capture, as adhesive and sealant manufacturers pay premiums for controlled molecular weight distribution. Chemical synthesis applications are expanding fastest, with piperylene-derived intermediates displacing conventional diene sources in pharmaceutical building blocks. Catalytic cracking technology leads installed capacity, though steam cracking yields are improving through advanced C5 separation trains.
EPA hazardous air pollutant standards constrain US refinery-based piperylene emissions, while REACH registration mandates European importers to document substance identity and safe-use conditions. China's MEE enforces volatile organic compound limits on C5 derivative processing facilities, pushing upgrades to closed-loop recovery systems. Stakeholders must monitor how evolving carbon border adjustments in the EU and prospective US chemical tariffs reshape interregional monomer trade economics.
Market Dynamics
Steam cracker operators are consolidating C5 fraction separation capacity, tightening piperylene supply availability for merchant resin producers while integrated chemical majors deepen captive consumption.
Growth Catalysts
- Automotive Lightweighting Mandates:Bonding applications in electric vehicle assembly are displacing mechanical fasteners, pulling polymer-grade piperylene into structural adhesive formulations.
- REACH Purity Upgrades:European chemical registration requirements for substance identity documentation are filtering lower-grade material from pharmaceutical intermediate supply chains.
- China Steam Cracker Expansion:Domestic C5 fraction capacity additions in Ningbo and Dalian are reducing import dependency for East Asian hydrocarbon resin manufacturers.
Market Restraints
- Naphtha Feedstock Volatility:Piperylene extraction economics track steam cracker feedstock costs, exposing merchant producers to crude-linked margin compression.
- Integrated Supply Concentration:Captive consumption by Asian petrochemical majors limits spot market liquidity and independent processor access.
- Regulatory Emission Controls:EPA hazardous air pollutant standards constrain US refinery-based extraction unit throughput and expansion permitting.
Strategic Opportunities
- Pharmaceutical Building Block Pivot:Piperylene-derived diene intermediates are penetrating synthetic routes for active pharmaceutical ingredients, commanding purity premiums over commodity resin applications.
- Closed-Loop Recovery Systems:China's MEE volatile organic compound enforcement is creating equipment upgrade demand for C5 derivative processors seeking compliance certification.
- Carbon Border Positioning:EU carbon border adjustment mechanism documentation requirements favor producers with verified low-emission extraction technology.
Industry Challenges
- Catalytic Process Engineering Talent:Advanced C5 separation train operation requires specialized expertise scarce outside major integrated petrochemical employers.
- Polymer Grade Certification Timelines:Adhesive manufacturer qualification protocols for new piperylene sources extend 18-24 months, freezing supplier switches.
- Legacy Fractionation Integration:Brownfield steam cracker retrofits face mechanical constraints accommodating next-generation extraction column designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piperylene Market |
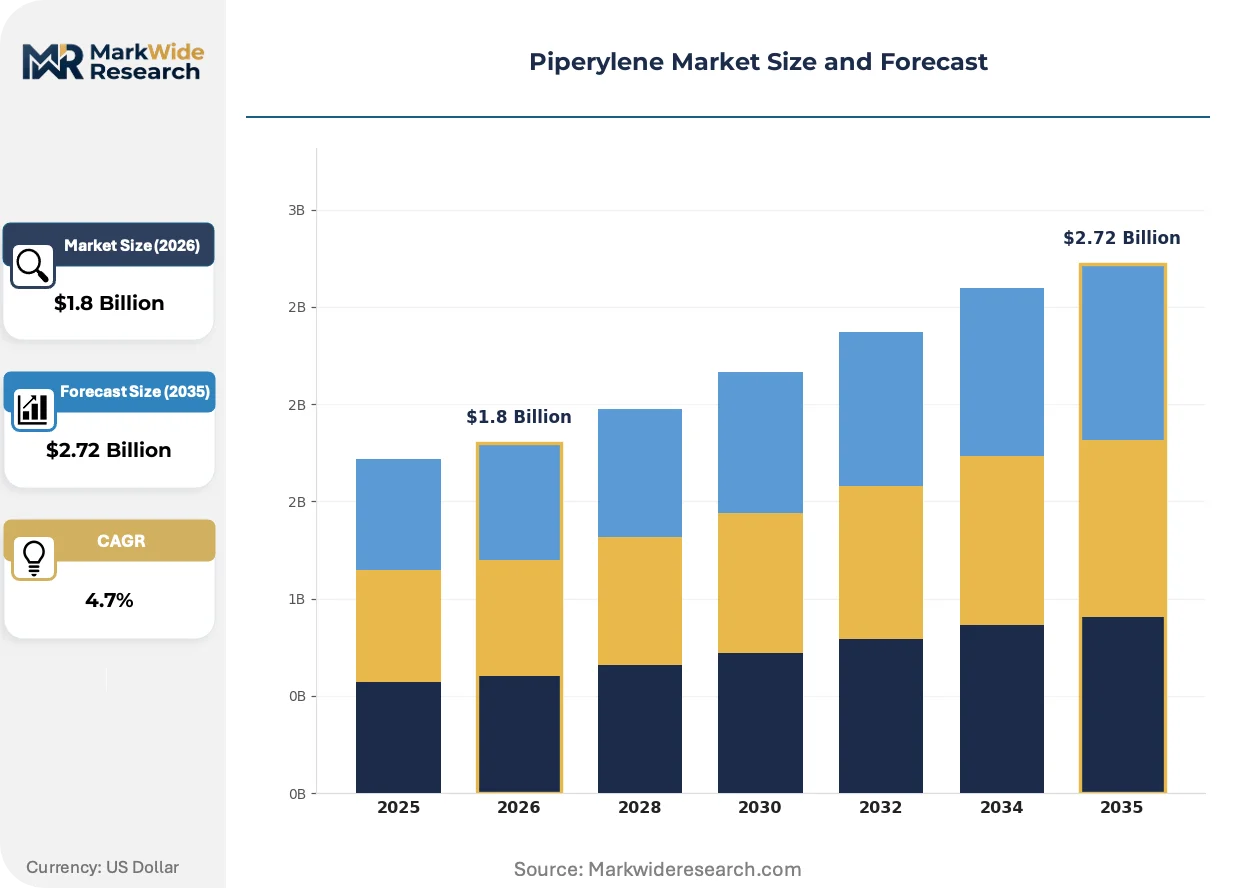
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piperylene, Monomer, Polymer, Additive Application: Rubber Production, Chemical Synthesis, Coatings, Adhesives End User: Automotive, Construction, Pharmaceuticals, Consumer Goods Technology: Catalytic Cracking, Steam Cracking, Isomerization, Dehydrogenation |
| Companies Covered | ZEON Corporation, Eastman Chemical Company, Shell Chemicals, Formosa Chemical, Sinopec Corporation, LOTTE Chemical Corporation, LyondellBasell Industries N.V., The Dow Chemical Company, Chevron Phillips Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piperylene Market Strategic Shifts
Process intensification in C5 separation and shifting purity requirements across end-use verticals are redefining competitive advantage away from scale toward extraction precision and application-specific customization.
Membrane-assisted pervaporation for piperylene purification is rendering obsolete energy-intensive extractive distillation configurations. Adhesive formulators in Germany and Japan are qualifying membrane-refined material for high-performance sealant applications. The technology is compressing capital requirements for mid-scale processors seeking polymer-grade output without billion-dollar steam cracker investments.
REACH registration dossier completeness requirements for substance identity and safe-use conditions are tightening documentation burdens on European importers. Hydrocarbon resin manufacturers dependent on non-EU piperylene sources face extended substance evaluation timelines. The pharmaceutical intermediate segment is responding by qualifying domestic EU extraction capacity to circumvent import documentation uncertainty.
Direct mill supply contracts are displacing traditional specialty chemical distribution for volume adhesive manufacturers. Large tire and rubber goods producers in Thailand and Indonesia are negotiating pipeline deliveries from integrated Asian petrochemical complexes. This channel compression is most visible in Southeast Asia, where geographic proximity to Japanese and Korean steam cracker networks enables just-in-time monomer supply without distributor inventory carrying costs.
Piperylene Market Segmentation
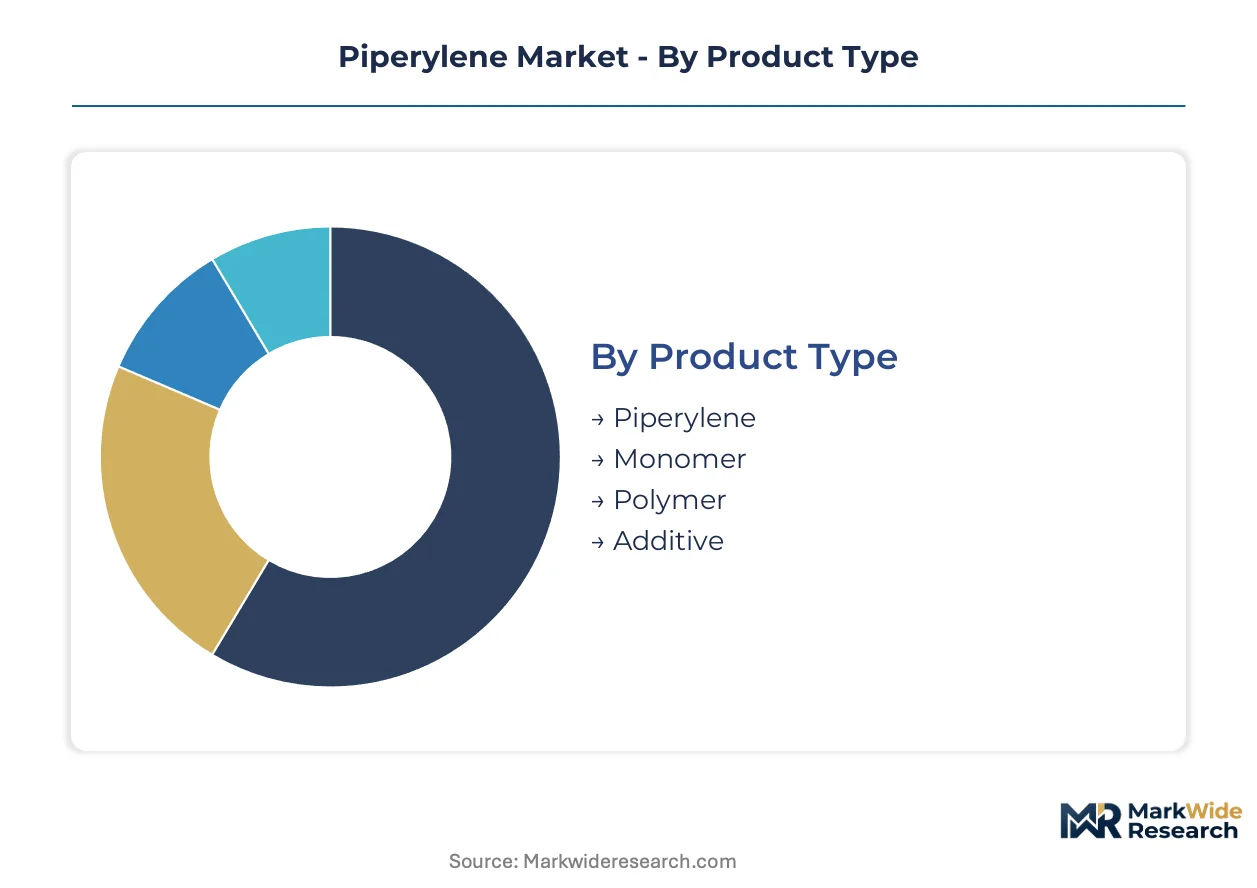
Piperylene's value chain fragments across technical specifications, conversion technologies, and end-use purity requirements. Each segmentation layer carries distinct margin profiles and qualification timelines that reshape supplier economics.
Product Type:
Cycle times vary dramatically by processing depth — raw monomer turns weekly while formulated additives tie up inventory for months.
- Piperylene:Crude C5 fraction-derived material at 65-90% purity serves as feedstock for downstream resin polymerization. Refinery extraction units in Texas and Rotterdam supply merchant markets where hydrocarbon resin manufacturers blend to specification.
- Monomer:Polymer-grade material commands purity premiums from adhesive formulators seeking controlled molecular weight distribution. Japanese steam cracker operators capture value through direct pipeline contracts to Southeast Asian rubber manufacturers.
- Polymer:Aliphatic hydrocarbon resins dominate consumption volume across tire manufacturing and pressure-sensitive adhesive applications. REACH registration dossier requirements are filtering non-compliant material from European pharmaceutical intermediate supply chains.
- Additive:Functionalized derivatives modify elastomer performance in automotive sealant formulations. Chinese C5 derivative processors face MEE volatile organic compound enforcement driving closed-loop recovery system upgrades.
Polymer dominates installed base. Monomer is where expansion concentrates.
Application:
Margin structures diverge sharply between commodity rubber feedstock and pharmaceutical-grade chemical synthesis.
- Rubber Production:Tire manufacturers consume bulk volumes of polymer-grade piperylene for synthetic elastomer production. Thailand and Indonesia negotiate pipeline deliveries from integrated Japanese and Korean petrochemical complexes.
- Chemical Synthesis:Pharmaceutical intermediate applications displace conventional diene sources in active pharmaceutical ingredient routes. ECHA substance identity documentation requirements extend qualification timelines for non-EU sourced material.
- Coatings:Aliphatic hydrocarbon resins provide UV stability and adhesion in industrial protective coatings. Automotive lightweighting mandates pull material into electric vehicle assembly bonding applications.
- Adhesives:Structural adhesive formulations for electric vehicle assembly displace mechanical fasteners. German and Japanese formulators qualify membrane-refined piperylene for high-performance sealant specifications.
Rubber production anchors volume throughput. Chemical synthesis is climbing the fastest.
End User:
Customer concentration and contract structures separate project-driven construction demand from continuous automotive consumption.
- Automotive:Electric vehicle manufacturers specify polymer-grade material for structural bonding and lightweighting applications. Direct mill supply contracts displace traditional specialty chemical distribution for volume tire producers.
- Construction:Sealant and coating applications track infrastructure investment cycles with pronounced seasonality. Chinese domestic steam cracker expansions in Ningbo and Dalian reduce import dependency for regional construction chemical manufacturers.
- Pharmaceuticals:Active pharmaceutical ingredient synthetic routes demand documented substance identity and safe-use conditions. European hydrocarbon resin manufacturers qualify domestic extraction capacity to circumvent import documentation uncertainty.
- Consumer Goods:Pressure-sensitive adhesives for packaging and labels consume standardized polymer grades. EPA hazardous air pollutant standards constrain US refinery-based extraction unit throughput serving this segment.
Automotive commands pricing power. Pharmaceuticals is gaining share fastest.
Technology:
Capital intensity and feedstock flexibility separate legacy refinery configurations from purpose-built chemical complexes.
- Catalytic Cracking:Petroleum refinery-integrated units extract piperylene from FCC C5 streams with moderate purity yields. Brownfield retrofits face mechanical constraints accommodating next-generation extraction column designs.
- Steam Cracking:Naphtha-fed ethylene crackers generate concentrated C5 fractions enabling high-purity piperylene recovery. Membrane-assisted pervaporation technology is compressing capital requirements for mid-scale processors seeking polymer-grade output.
- Isomerization:Catalytic processes convert non-conjugated dienes to piperylene for specialized chemical synthesis feedstock. Advanced C5 separation train operation requires specialized expertise scarce outside major integrated petrochemical employers.
- Dehydrogenation:Selective hydrogen removal from pentane streams produces piperylene for regions lacking steam cracker infrastructure. EU carbon border adjustment mechanism documentation requirements favor producers with verified low-emission extraction technology.
Steam cracking dominates installed base. Membrane-assisted pervaporation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Botlek pipeline corridor underwrites Europe's piperylene distribution architecture, while Ningbo-Zhoushan port infrastructure anchors Asia-Pacific monomer flows to resin manufacturers.
United States
Gulf Coast steam cracker expansions near Houston and Baytown are tightening C5 fraction availability for merchant resin producers. EPA hazardous air pollutant standards constrain refinery-based extraction unit throughput along the Texas-Louisiana corridor. Baton Rouge and Lake Charles host concentrated hydrocarbon resin manufacturing clusters where producers qualify polymer-grade material for automotive adhesive specifications.
China
Domestic steam cracker additions in Ningbo and Dalian are reducing import dependency for East Asian hydrocarbon resin manufacturers. MEE volatile organic compound limits on C5 derivative processing facilities are pushing upgrades to closed-loop recovery systems. The Yangtze River Delta concentration of adhesive formulators is absorbing expanded regional monomer supply through direct pipeline contracts.
Germany
REACH chemical registration requirements are filtering lower-grade piperylene from pharmaceutical intermediate supply chains. ECHA substance identity documentation mandates extend qualification timelines for non-EU sourced material. The Cologne-Leverkusen chemical corridor hosts integrated extraction capacity serving domestic hydrocarbon resin manufacturers seeking compliance certification.
Japan
Captive piperylene supply from Chiba and Yokkaichi petrochemical complexes serves Asian rubber manufacturers through direct mill contracts. METI industrial standards govern purity specifications for adhesive and sealant applications. The Keiyo industrial zone maintains concentrated C5 fraction separation capacity with pipeline connectivity to Southeast Asian tire producers.
South Korea
Yeosu and Ulsan steam cracker networks generate concentrated C5 fractions enabling high-purity piperylene recovery for export markets. MFDS pharmaceutical-grade substance documentation requirements align with ECHA standards for active pharmaceutical ingredient intermediate supply. Daesan industrial complex operators are qualifying membrane-refined material for German and Japanese adhesive formulator specifications.
Piperylene Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the value chain. The piperylene market exhibits consolidated supply-side structure with integrated petrochemical majors controlling extraction capacity and merchant availability. Three archetypes dominate: captive-consuming steam cracker operators, backward-integrated resin manufacturers, and technology-licensed mid-scale processors. Competitive moves concentrate on direct-to-miller contract displacement of distributor channels and membrane-assisted pervaporation technology licensing for purity-tier expansion.
Within the integrated operator tier, ZEON Corporation and Eastman Chemical Company exemplify contrasting geographic anchoring strategies. ZEON occupies a position representing Japanese captive supply dominance through Chiba and Yokkaichi complex connectivity. Eastman anchors North American demand architecture through upstream control over C5 fraction separation infrastructure. Shell Chemicals sits within the global scale archetype, with multi-corridor extraction unit presence spanning Rotterdam, Singapore, and Houston refining networks. These three entities collectively represent the supply concentration constraining spot market liquidity for independent processors.
| Leading Market Players |
|---|
| ZEON Corporation |
| Eastman Chemical Company |
| Shell Chemicals |
| Formosa Chemical |
| Sinopec Corporation |
| LOTTE Chemical Corporation |
| LyondellBasell Industries N.V. |
| The Dow Chemical Company |
| Chevron Phillips Chemical Company |
| Others |
Value Chain & Pricing Dynamics
The Ningbo-Zhoushan petrochemical cluster concentrates regional C5 fraction separation capacity, compressing spot market liquidity and amplifying pricing power for integrated operators serving East Asian hydrocarbon resin manufacturers through direct pipeline contracts.
Pricing Analysis
Three-tier pricing structure across polymer-grade, monomer-grade, and crude C5 feedstock levels anchors contract negotiations. Price differentiation rests on purity certification and REACH dossier completeness for European pharmaceutical intermediate supply chains. Cost compression in standard-grade material intensifies as Chinese domestic steam cracker expansions reduce import dependency. Independent processors exhibit highest price sensitivity due to captive supply exclusion, while automotive adhesive formulators absorb premiums for documented molecular weight distribution control.
Supply Chain Analysis
Tariff exposure between the United States and prospective carbon border adjustment jurisdictions dominates supply chain risk assessment for merchant resin producers. Geographic supply concentration centers on China, Japan, and South Korea, with the Keiyo and Yeosu industrial zones feeding Southeast Asian tire manufacturers. Raw material dependencies include naphtha feedstock, specialized C5 separation catalysts, and membrane pervaporation modules. Distribution runs through direct mill supply contracts displacing traditional specialty chemical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where polymer-grade qualification timelines create 18-24 month switching costs that entrench incumbent positions against merchant challengers.
For Market Incumbents: Entrench position through backward integration into C5 fraction separation infrastructure in the US Gulf Coast corridor. Deepen captive supply relationships with Southeast Asian tire manufacturers facing substitution risk from bio-based diene alternatives. Prioritize membrane-assisted pervaporation technology licensing to mid-scale processors seeking polymer-grade output without billion-dollar steam cracker investments. For New Entrants and Emerging Players: Pursue pharmaceutical intermediate applications where REACH substance identity documentation requirements filter non-compliant imports and command purity premiums over commodity resin markets. Target closed-loop recovery system deployment for Chinese C5 derivative processors under MEE volatile organic compound enforcement pressure. Lead with compliance certification services bundled with membrane-refined material supply. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because ECHA documentation mandates and EPA hazardous air pollutant standards continuously raise barriers to merchant market participation. Acquisition targets include mid-scale processors with qualified membrane pervaporation capacity and established automotive adhesive formulator relationships. Monitor carbon border adjustment mechanism implementation timelines as the critical inflection signal for low-emission extraction technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C5 Separation | Eastman Chemical's upstream control over fractionation infrastructure anchors North American supply security. |
| Membrane Pervaporation Technology Licensing | Daesan complex operators qualify refined material for German adhesive specifications without steam cracker capital. |
| Direct Mill Supply Contract Expansion | ZEON Corporation's pipeline connectivity to Chiba and Yokkaichi complexes displaces distributor inventory carrying costs. |
| REACH Dossier Completeness Investment | Cologne-Leverkusen corridor extraction capacity serves domestic resin manufacturers circumventing import documentation uncertainty. |
| Closed-Loop Recovery System Deployment | Yangtze River Delta processors achieve MEE volatile organic compound compliance certification through equipment upgrades. |
Study Parameters
The analysis maps C5 fraction separation technologies, piperylene-derived product grades, and end-use application verticals, each validated through plant managers at integrated petrochemical complexes, procurement leads at hydrocarbon resin manufacturers, distribution channel partners, and technical R&D directors specializing in catalytic processes. Primary interview findings triangulate against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical majors, and EPA emission disclosure records. Bottom-up capacity modeling and top-down demand segmentation converge on volume estimates.
Assumptions held fixed include prevailing REACH registration requirements, EPA hazardous air pollutant standards, and MEE volatile organic compound enforcement intensity; variables tested include naphtha feedstock cost trajectories and carbon border adjustment mechanism coverage expansion. The analytical framework segments by purity grade, end-use industry, extraction technology, and regional production hub across the projection horizon. CAGRs derive from installed capacity utilization trends and substitution elasticity estimates for adhesive and pharmaceutical applications. Forecast inputs include steam cracker expansion timelines in Ningbo and Dalian and membrane pervaporation adoption rates.
Sensitivities concentrate around crude-linked naphtha price volatility, REACH substance evaluation timeline extensions, and prospective US chemical tariff implementations. Forecasts reflect documented assumptions on regulatory enforcement continuity and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Ethyl Lactate Market
Solvents
Global Glycidol Market
Solvents
Meta-Xylene Market
Solvents
Global Chloroform Market
Solvents
Chloromethane Market
Solvents
Fluorinated Solvents Market
Solvents
Tetraethyl Benzene Market
Solvents
3-Butylene Glycol Market
Solvents
Global Bio Solvents Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
Fluid Neutralizing Market
Solvents
Global Ink Solvents Market
Solvents
Chlorobenzene Market
Solvents
Propylene Glycol Ether Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
Nitroglycerin Market