
 Nitromethane Market | 2026-2036
Nitromethane Market Size, Share, and Industry Trends Forecast 2026-2036
Nitromethane Market Analysis
Buyer concentration among specialty chemical distributors is recalibrating procurement patterns across the nitromethane value chain. Angus Chemical Company leverages its integrated nitroalkane production platform to sustain supply reliability for North American fuel additive customers. Shandong Baoyuan Chemical anchors volume output from Shandong Province, competing on scale against regional Chinese peers. Eastman Chemical Company differentiates through pharmaceutical-grade purity standards that command premium positioning in laboratory end-use segments.
Nitromethane is a colorless, oily liquid with the chemical formula CH₃NO₂ and a boiling point of 101.2°C, produced primarily through vapor-phase nitration of propane or direct nitration of methane, serving as both a high-energy fuel component and a versatile chemical intermediate. The fuel additive segment dominates volume consumption due to persistent demand from drag racing and motorsports applications where oxygen content enhances combustion efficiency. Chemical intermediate applications for pharmaceutical manufacturing represent the fastest-expanding margin pool, as specialty synthesis requirements drive specification upgrades. Industrial solvent demand remains mature, with pricing pressure from substitute polar aprotic solvents limiting growth.
EPA regulations under the Clean Air Act constrain racing fuel formulations, while China's MEE enforces emission controls on nitration facilities, and REACH in Europe mandates registration for import volumes above one tonne annually. These frameworks elevate compliance costs for smaller traders while creating barriers that favor producers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving restrictions on nitroalkane transportation classifications and assess backward integration into captive nitration capacity to secure supply continuity.
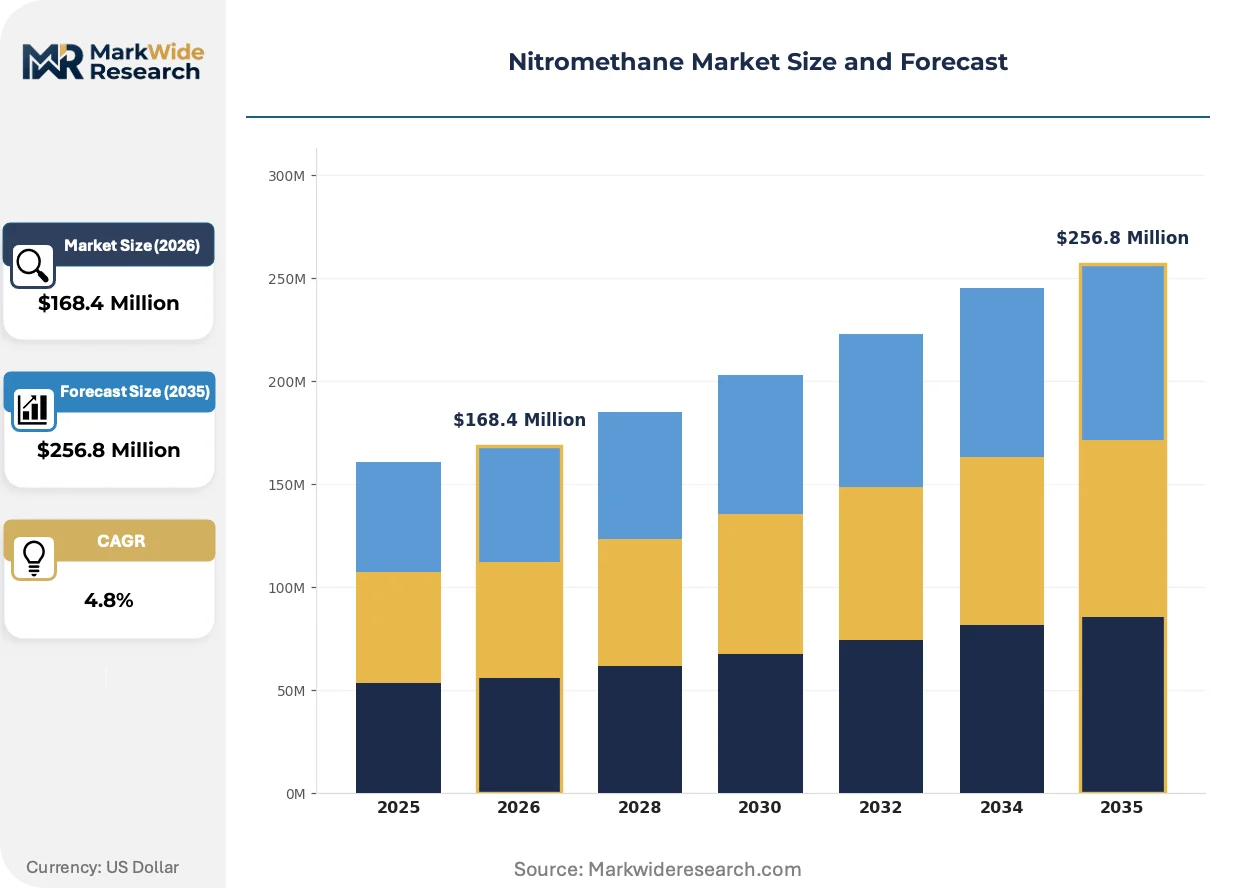
Market Dynamics
China's MEE emission controls on nitration facilities are compressing marginal production capacity while drag racing demand in Texas and California pulls supply toward fuel-grade purity specifications, creating a bifurcation between industrial solvent and high-performance fuel markets.
Growth Catalysts
- MEE nitration facility standards:China's environmental ministry mandates cleaner production pathways, accelerating capital deployment into vapor-phase nitration upgrades that reduce NOx emissions and yield higher-purity output for pharmaceutical intermediates.
- Drag racing fuel specifications:NHRA and IHRA competition categories in the United States specify oxygenated fuel blends, locking in baseline consumption for nitromethane as a combustion enhancer in top fuel and funny car divisions.
- Pharmaceutical synthesis demand:Specialty API manufacturers in India and Switzerland require nitroalkane intermediates for cephalosporin and cardiovascular drug production, pulling specification upgrades across the supply base.
Market Restraints
- Propane feedstock volatility:Natural gas liquid pricing swings in the US Gulf Coast directly transmit to nitration economics, compressing margins for non-integrated producers during winter heating demand spikes.
- Shandong production concentration:China's nitromethane output clusters in Shandong Province, exposing buyers to single-point logistics disruptions from port congestion or provincial environmental inspections.
- Dimethyl sulfoxide substitution:Pharmaceutical and electronics solvents increasingly specify DMSO for polar aprotic applications, displacing nitromethane in coating and extraction processes where flash point requirements permit.
Strategic Opportunities
- Brazilian motorsports expansion:Stock Car Pro Series and drag racing infrastructure buildout in São Paulo state creates import demand for US-blended racing fuels, bypassing domestic nitration capacity constraints.
- Green nitration process patents:Electrochemical methane nitration technologies under development at ETH Zurich and MIT promise to eliminate thermal NOx generation, aligning with EU Green Deal industrial decarbonization targets.
- Direct-to-team distribution:Racing fuel compounders are bypassing traditional chemical distributors to contract directly with NHRA teams, capturing margin previously allocated to specialty chemical traders.
Industry Challenges
- Explosives precursor licensing:Nitromethane's classification under EU Regulation 98/2013 on explosives precursors mandates customer verification and transaction reporting, extending sales cycles for laboratory and small-batch fuel customers.
- Captive nitration engineering:Backward integration into propane nitration requires $40-60 million in specialized reactor and safety systems, limiting balance sheet capacity for mid-scale fuel blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitromethane Market |
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $256.8 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Additive, Industrial Solvent, Chemical Intermediate, Antiknock Agent Application: Racing Fuel, Solvent for Chemicals, Pharmaceutical Manufacturing, Specialty Coatings End User: Aerospace, Automotive, Chemical Manufacturing, Laboratories Packaging Type: Drums, Bottles, Bulk Containers, Totes |
| Companies Covered | Angus Chemical Company, Shandong Baoyuan Chemical Co. Ltd., Deepak Chem Tech Limited, Linyi Yuanbo Chemical Co. Ltd., Hubei Grand Fuchi Pharmaceutical & Chemicals Co. Ltd., Greenchem Industries LLC, Wego Chemical & Mineral Corp, Eastman Chemical Company, INEOS Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitromethane Market Emerging Trajectories
Electrochemical production methods and regulatory pressure on thermal nitration emissions are restructuring how nitromethane purity grades map to end-use economics, while procurement patterns in racing fuels fragment toward direct manufacturer relationships.
Electrochemical methane nitration is electrifying the technology landscape for nitroalkane production. Swiss and German engineering firms pilot membrane-cell reactors that operate below 80°C, eliminating thermal NOx formation. Specialty chemical producers in Basel and Ludwigshafen evaluate licensing terms for commercial deployment. This technology is electrifying competitive positioning by decoupling production economics from natural gas price cycles.
REACH registration requirements for nitroalkane import volumes above one tonne annually are tightening market access for non-EU producers. ECHA substance evaluation dossiers now demand extended aquatic toxicity data, extending compliance timelines for Chinese exporters. Fuel additive distributors in Rotterdam and Hamburg consolidate sourcing relationships to reduce registration cost burdens across their portfolios.
Spec-driven procurement now dominates racing fuel purchasing, with NHRA teams requesting certificate-of-analysis documentation for every drum rather than accepting distributor blending. Direct contracts between Texas fuel compounders and individual race teams disintermediate traditional chemical distributors. This pattern concentrates most visibly in California and Florida, where professional drag racing teams operate dedicated fuel testing programs.
Nitromethane Market Segmentation
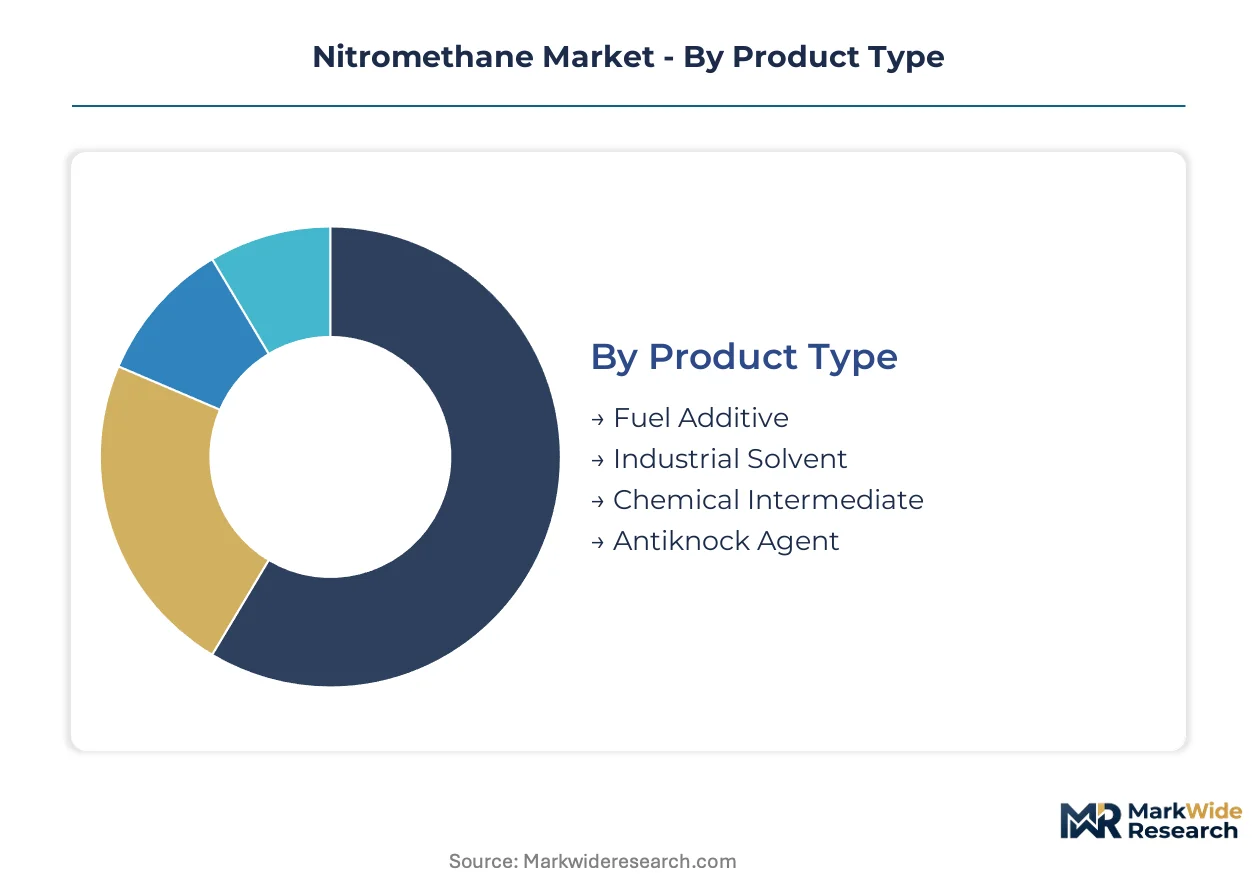
Nitromethane's bifurcated demand structure—split between high-volume fuel additives and specification-intensive pharmaceutical intermediates—requires granular segmentation to map capital deployment and margin capture. Each dimension reveals distinct competitive dynamics: product type determines nitration purity requirements, while packaging choices reflect hazardous material handling economics.
Product Type:
Fuel additive production demands the heaviest capital commitment, requiring dedicated vapor-phase nitration trains and explosion-proof storage infrastructure that can exceed $50 million per integrated site.
- Fuel Additive:Oxygenated formulations for drag racing and motorsports command 98.5% minimum purity with strict moisture specifications below 0.1%. NHRA competition rules in the United States lock in baseline consumption for top fuel and funny car divisions, with Texas and California compounders pulling supply toward drum-scale certification programs.
- Chemical Intermediate:Pharmaceutical-grade material requires 99.5% purity with full traceability documentation for cephalosporin and cardiovascular API synthesis. Swiss and Indian manufacturers drive specification upgrades as they qualify new suppliers under EMA and CDSCO filing requirements.
- Industrial Solvent:Standard-grade material serves extraction and cleaning applications where flash point tolerance permits substitution by DMSO.
- Antiknock Agent:Blending component for specialty gasoline formulations faces regulatory pressure from EPA Clean Air Act constraints on oxygenate content.
Fuel additive absorbs the bulk of installed capacity; chemical intermediate is expanding most quickly.
Application:
Volume concentration varies sharply by application maturity, with racing fuel representing a stable demand pool while pharmaceutical manufacturing climbs the steepest specification curve.
- Racing Fuel:NHRA and IHRA categories mandate nitromethane blends for professional divisions. Texas fuel compounders now contract directly with individual race teams, bypassing traditional chemical distributors and capturing margin previously allocated to specialty traders.
- Pharmaceutical Manufacturing:Cephalosporin antibiotic synthesis and cardiovascular drug production in Basel and Hyderabad require nitroalkane intermediates with full CoA documentation. REACH registration demands for EU import volumes above one tonne annually favor producers with dedicated regulatory affairs capabilities.
- Solvent for Chemicals:Extraction and reaction media applications face pricing pressure from polar aprotic substitutes.
- Specialty Coatings:Electronics and industrial finishes specify nitromethane where rapid evaporation and solvent power justify handling costs.
Racing fuel commands the largest volume commitment; pharmaceutical manufacturing posts the steepest expansion trajectory.
End User:
Customer concentration patterns split between high-volume automotive procurement and fragmented laboratory purchasing that demands flexible packaging and rapid fulfillment.
- Automotive:Professional drag racing teams and fuel compounders in California, Texas, and Florida drive drum-scale demand with certificate-of-analysis requirements for every shipment. Direct manufacturer relationships are displacing distributor intermediation.
- Chemical Manufacturing:Integrated nitration operators like Angus Chemical Company supply captive requirements while serving external fuel additive customers from Louisiana production platforms.
- Aerospace:Specialized propulsion research applications require ultra-high purity with full material traceability.
- Laboratories:Analytical and research consumption fragments across academic and industrial R&D facilities with small-batch ordering patterns.
Automotive pulls the majority of fuel-grade output; chemical manufacturing integrates most heavily upstream.
Packaging Type:
Hazardous material classification and customer scale determine packaging economics, with bulk containers offering the lowest per-unit cost for integrated compounders while drums serve fragmented team-level demand.
- Drums:Standard 55-gallon steel drums dominate racing fuel distribution, enabling NHRA teams to verify lot-specific CoA documentation before blending. California and Florida teams increasingly specify dedicated drum labeling with chain-of-custody tracking.
- Bulk Containers:Tank truck and railcar deliveries serve Texas and Louisiana fuel compounders with integrated storage and blending operations, minimizing handling costs for high-volume customers.
- Totes:Intermediate bulk containers serve mid-scale chemical manufacturers with flexible volume requirements.
- Bottles:Laboratory-scale packaging supports analytical and R&D applications with strict lot control.
Bulk containers move the greatest tonnage; drums generate the highest per-unit margin through certification services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drag racing fuel specifications in the United States and pharmaceutical-grade demand from Swiss and Indian manufacturers concentrate consumption across distinct purity tiers. China's Shandong Province dominates nitration capacity while facing environmental compliance pressure. Regulatory fragmentation between EPA, REACH, and MEE frameworks shapes regional trade flows.
United States
NHRA and IHRA competition categories mandate oxygenated fuel blends for professional drag racing divisions. EPA regulations under the Clean Air Act constrain racing fuel formulations while allowing motorsports exemptions. Texas and California chemical manufacturing clusters host fuel compounders who now contract directly with race teams, bypassing traditional distributors.
China
Shandong Province anchors domestic nitration output with concentrated propane-to-nitromethane conversion capacity. MEE emission controls on nitration facilities are compressing marginal production capacity and accelerating capital deployment into cleaner vapor-phase upgrades. Port congestion and provincial environmental inspections expose buyers to single-point logistics disruptions from this geographic concentration.
Switzerland
Specialty API manufacturers in Basel require nitroalkane intermediates for cephalosporin and cardiovascular drug production with full traceability documentation. Swissmedic and EMA filing requirements drive specification upgrades across the supply base. ETH Zurich pilots electrochemical methane nitration technologies that promise to eliminate thermal NOx generation.
India
Hyderabad and Mumbai pharmaceutical corridors pull nitromethane demand for cephalosporin antibiotic synthesis and cardiovascular API manufacturing. CDSCO filing requirements and import quality standards favor producers with dedicated regulatory affairs capabilities. Domestic nitration capacity remains limited, creating import dependence for pharmaceutical-grade material.
Germany
REACH registration requirements for nitroalkane import volumes above one tonne annually tighten market access for non-EU producers. ECHA substance evaluation dossiers now demand extended aquatic toxicity data, extending compliance timelines. Fuel additive distributors in Rotterdam and Hamburg consolidate sourcing relationships to reduce registration cost burdens across their portfolios.
Nitromethane Market Vendor Landscape
United States producers anchor one tier; Chinese specialists hold volume-scale positions; European operators concentrate on pharmaceutical-grade purity standards. The vendor base splits between integrated nitration operators and fuel-blending compounders who source intermediate material. Three archetypes dominate: captive chemical manufacturers with backward integration, regional nitration specialists serving industrial solvent markets, and fuel-focused compounders with direct racing team relationships. Capacity expansion and direct-to-team distribution represent the dominant competitive moves reshaping procurement patterns.
Among North American integrated producers, Angus Chemical Company and Eastman Chemical Company exemplify divergent strategic positioning. Angus occupies the fuel-additive supply tier through Louisiana-based nitration platforms. Eastman sits within the specification-intensive pharmaceutical intermediate segment where purity premiums command pricing power. Shandong Baoyuan Chemical Co. Ltd. represents the scale-driven Chinese archetype, competing on volume output from Shandong Province against regional peers facing MEE compliance pressure. These three anchors illustrate how geographic origin and end-use focus stratify competitive positioning across purity grades.
| Leading Market Players |
|---|
| Angus Chemical Company |
| Shandong Baoyuan Chemical Co. Ltd. |
| Deepak Chem Tech Limited |
| Linyi Yuanbo Chemical Co. Ltd. |
| Hubei Grand Fuchi Pharmaceutical & Chemicals Co. Ltd. |
| Greenchem Industries LLC |
| Wego Chemical & Mineral Corp |
| Eastman Chemical Company |
| INEOS Enterprises |
| Others |
Supply Flow & Price Mechanics
Captive nitration capacity in Louisiana and Texas anchors supply reliability for North American fuel compounders while compressing margin capture for non-integrated blenders who must source intermediate material at spot-equivalent terms. This integration choice concentrates pricing power among producers with backward control over propane feedstock and vapor-phase reactor assets, leaving distributor-dependent buyers exposed to natural gas liquid price cycles.
Pricing Analysis
Volume-mass fuel additive shipments trade at compressed margins against specification-intensive pharmaceutical-grade material that commands substantial purity premiums. Three-tier pricing structure across pharmaceutical-grade, fuel-grade, and industrial-solvent levels reflects certification burden and traceability documentation requirements. Cost compression in standard-grade solvent tiers is intensifying because DMSO substitution erodes volume commitments. Racing fuel teams show the least price sensitivity due to NHRA mandate lock-in, while laboratory buyers negotiate aggressively on small-batch orders.
Supply Chain Analysis
China's MEE emission controls on nitration facilities are reshaping sourcing patterns by compressing Shandong Province output and accelerating import demand for cleaner-produced material. Propane feedstock, nitric acid, and specialized reactor catalysts constitute the critical input stack. Single-source vulnerability concentrates in Shandong's port-dependent logistics corridor. Distribution runs through integrated fuel compounders in Texas and California who blend directly for NHRA teams, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
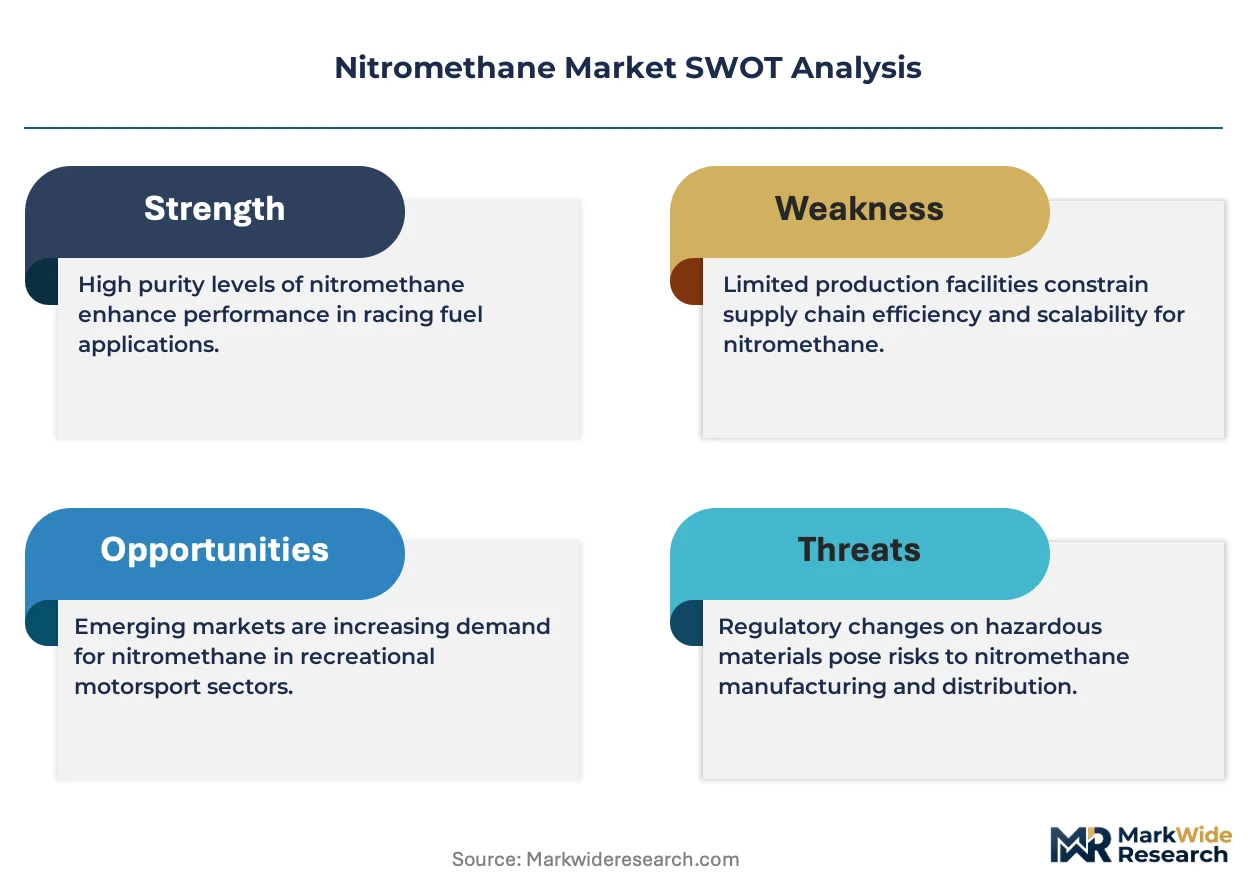
This market is a vertical-integration race where captive nitration capacity determines supply security and margin retention against feedstock volatility. Players are pursuing upstream control over propane-to-nitromethane conversion assets as the decisive competitive lever.
For Market Incumbents: Cement supply continuity by expanding vapor-phase nitration capacity in Louisiana and Texas corridors. Lock in long-term propane offtake agreements with Gulf Coast natural gas liquid processors. Electrochemical nitration patents from ETH Zurich and MIT represent an emerging technology threat that could obsolete thermal reactor economics; secure licensing options or R&D partnerships now. For New Entrants and Emerging Players: REACH registration requirements in Europe open a window for specialized regulatory affairs capabilities that incumbent Chinese producers lack. Target pharmaceutical-grade intermediate supply to Swiss and Indian API manufacturers who demand full CoA documentation. Build direct relationships with Basel and Hyderabad formulation houses rather than competing on fuel-grade volume where integrated incumbents hold cost advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale fuel compounders with established NHRA team relationships and drum-scale certification infrastructure. The five-to-ten year viability window favors producers with demonstrated MEE compliance or electrochemical technology licenses. Watch for electrochemical nitration pilot scale-up announcements from Swiss and German engineering firms as the inflection signal for technology disruption timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitration Capacity | Captive propane-to-nitromethane conversion secures supply continuity against Shandong logistics disruptions. |
| Green Manufacturing Transition | Electrochemical reactor licensing from ETH Zurich aligns production with EU Green Deal decarbonization mandates. |
| Long-term Supply Agreement | Multi-year propane offtake contracts with Gulf Coast processors hedge against winter heating demand price spikes. |
| Direct-to-Team Distribution | Bypassing specialty chemical distributors captures margin previously allocated to drum-scale certification intermediaries. |
| Regulatory Compliance Investment | REACH registration and ECHA dossier capabilities unlock pharmaceutical-grade access to Basel and Hyderabad API manufacturers. |
Methodological Framework
Multi-period observation of NHRA competition rules, MEE emission enforcement patterns, and REACH registration timelines anchored the trend analysis, supplemented by interviews with fuel compounder procurement leads, pharmaceutical API manufacturing directors, Shandong Province plant managers, and specialty chemical distribution channel partners. Secondary validation drew from EPA Clean Air Act filings, ECHA substance evaluation dossiers, customs trade data for nitroalkane imports, and SEC 10-K disclosures from integrated chemical producers. Bottom-up segment sizing triangulated against top-down market envelope checks.
The input-output matrix framed demand modeling across fuel additive, chemical intermediate, and industrial solvent grades, with purity tier and end-use industry as cross-cutting segmentation dimensions. CAGRs were derived from rolling regression of historical volume patterns against projected regulatory enforcement intensity and motorsports participation trends. Propane feedstock pricing volatility and electrochemical technology readiness levels served as scenario-conditioning variables throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for electrochemical methane nitration would alter the outlook if commercial deployment accelerates beyond pilot scale. Forecasts reflect assumptions around MEE enforcement consistency, NHRA rule stability, and Swissmedic filing requirement evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global 2-Ethoxyethanol Market
Solvents
Nitroglycerin Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Solvent Recovery Systems Market
Solvents
Solvent Cement Market
Solvents
Global Acetonitrile Market
Solvents
Glycerol Market
Solvents
Global Ethyl Lactate Market
Solvents
Allyl Cyanide Market
Solvents
1,2-Ethanedithiol Market
Solvents
3-Butylene Glycol Market
Solvents
Propylene Glycol Ether Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Global Solvents Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Butyl Acetate (BAC) Market