
 Tile and Stone Adhesive Market | 2026-2036
Tile and Stone Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Tile and Stone Adhesive Market Analytics
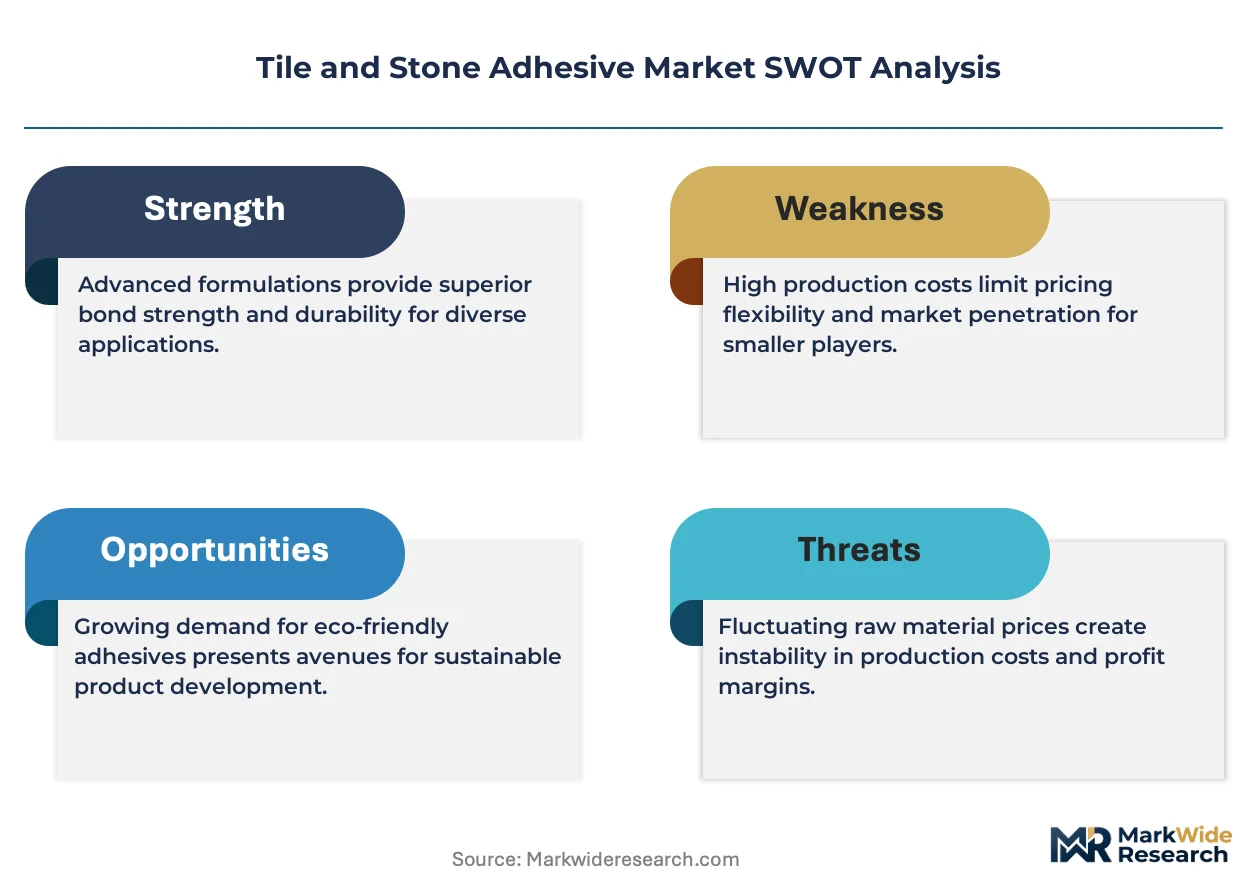
Premium-grade thin-set mortar is rotating toward large-format porcelain installations that demand higher bond strength and reduced lippage. MAPEI S.p.A. leverages its vertical integration into polymer additives to control raw material quality across European plants. LATICRETE International, Inc. sustains technology leadership in epoxy-based systems for submerged applications. Pidilite Industries Limited dominates distribution depth across India's tier-two and tier-three cities through extensive dealer networks.
Tile and stone adhesive comprises cementitious, resin-based, or organic formulations engineered to bond rigid surfacing materials to substrates under load, moisture, and thermal stress; polymer-modified cement mortars typically achieve tensile adhesion strengths exceeding 1.0 MPa after 28 days of curing. Thin-set mortar occupies the largest volume share due to its versatility across ceramic and porcelain applications, while epoxy adhesives command the highest margin pools in swimming pool and industrial settings where chemical resistance is non-negotiable. Commercial spaces represent the fastest-growing application segment as retail and hospitality operators prioritize accelerated installation schedules.
GB standards in China and REACH in Europe jointly restrict solvent content and mandate disclosure of hazardous substance thresholds, compelling manufacturers to reformulate toward low-emission acrylic and urethane systems. The US EPA and OSHA enforce workplace exposure limits during adhesive mixing and application, shaping contractor training requirements and product labeling protocols. Stakeholders must monitor evolving certification harmonization between Asian and European testing regimes to avoid redundant compliance costs.
Market Dynamics
Large-format porcelain tile installations are compressing curing cycles and demanding polymer-modified mortars with tensile adhesion above 1.5 MPa, forcing manufacturers to reformulate cementitious bases while maintaining workability for contractor crews.
Growth Catalysts
- GB Standards (China):Tightening VOC limits under GB 30982 are accelerating water-based acrylic reformulations across construction chemical portfolios, opening premium positioning for low-emission systems.
- DIY Renovation Surge:Residential homeowners in North American and European markets are driving ready-mixed adhesive consumption through home improvement retail channels, expanding addressable volume beyond professional contractors.
- Polymer Additive Advances:Redispersible polymer powders with enhanced hydrophobicity are enabling exterior facade applications previously restricted to resin-based systems, broadening thin-set mortar use cases.
Market Restraints
- Portland Cement Volatility:Energy-intensive clinker production faces carbon pricing pressure in the EU ETS system, transmitting input cost instability to cementitious adhesive margins.
- Epoxy Raw Material Concentration:Bisphenol-A and amine hardener supply chains concentrate in Northeast Asian petrochemical complexes, creating geographic vulnerability for high-performance adhesive producers.
- REACH Registration Burden:Novel polymer chemistries face extended ECHA evaluation timelines, delaying product launches by 18-36 months versus conventional formulations.
Strategic Opportunities
- India Western States:Gujarat and Maharashtra commercial flooring projects are concentrating demand for rapid-setting adhesives capable of 24-hour return-to-service, favoring localized production investments.
- Swimming Pool Submerged Applications:Epoxy-based systems for chemical-resistant pool linings command margin premiums 3-4x above standard thin-set, with untapped residential pool renovation segments in Mediterranean climates.
- EU Green Deal Procurement Mandates:Public construction tenders increasingly specify Environmental Product Declarations, rewarding manufacturers with verified lifecycle data and circular material content.
Industry Challenges
- Skilled Applicator Shortage:Large-format tile installation demands specialized training in lippage control and substrate preparation, with certified installer pools failing to match project growth in high-demand metros.
- Multi-Standard Certification Complexity:Divergent ISO 13007, ANSI A118, and EN 12004 testing protocols force redundant product validation for cross-border projects, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tile and Stone Adhesive Market |
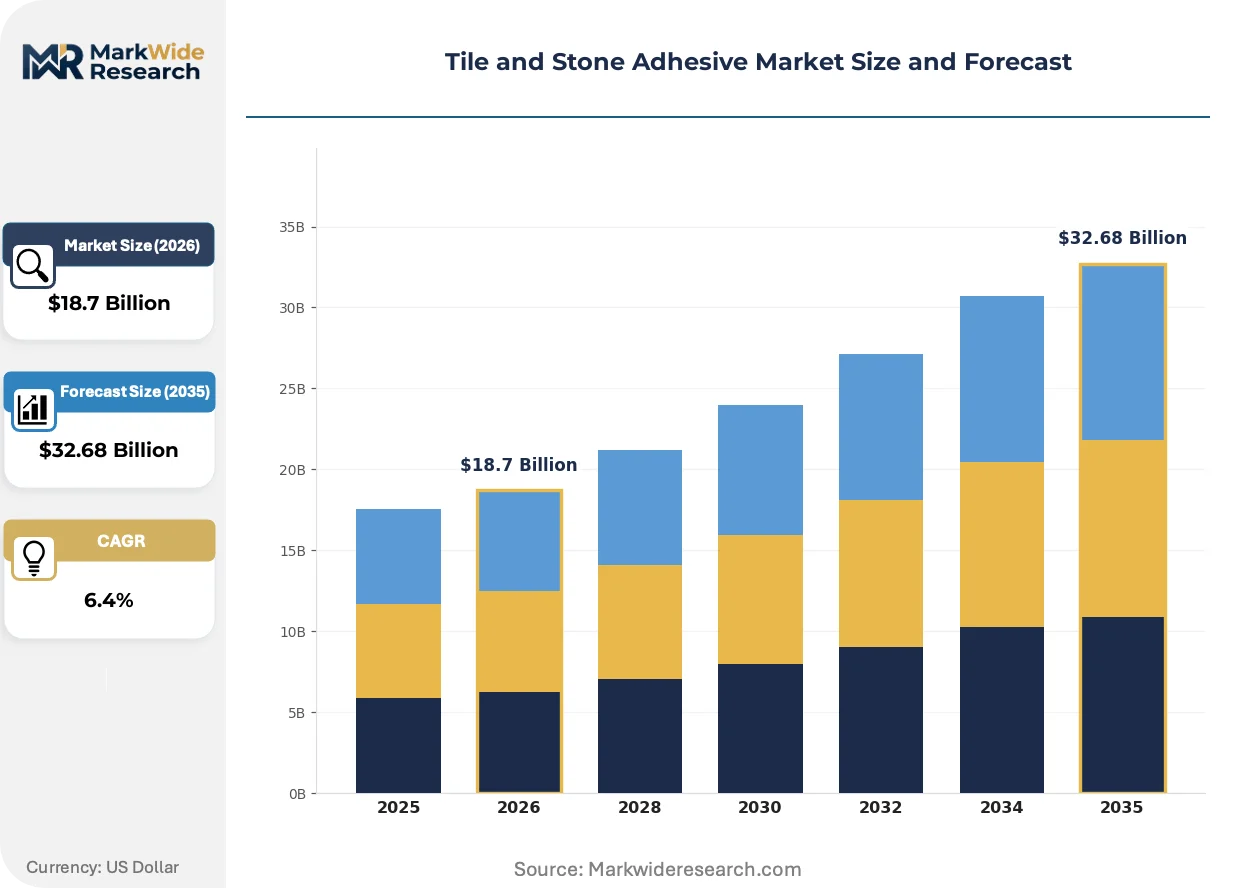
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-set Mortar, Epoxy Adhesives, Mastic, Urethane Adhesives Application: Interior Flooring, Exterior Facades, Swimming Pools, Commercial Spaces End User: Contractors, DIY Enthusiasts, Construction Companies, Renovators Material: Ceramic Tiles, Natural Stone, Porcelain Tiles, Glass Tiles |
| Companies Covered | Bostik S.A.S., Saint-Gobain Weber, MAPEI S.p.A., Fosroc International Limited, Henkel AG & Co. KGaA, ARDEX GmbH, LATICRETE International, Inc., Pidilite Industries Limited, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tile and Stone Adhesive Market Evolving Landscape
Reformulation chemistry and installation methodology are converging to address thermal cycling stress in exterior cladding while compressing project timelines for commercial flooring contractors.
Hybrid polymer-cement systems incorporating silane-modified polymers are supplanting traditional latex-modified mortars in exterior facade applications. Commercial contractors in Germany and Australia are specifying these systems for porcelain cladding on high-rise buildings. The shift is compressing warranty exposure for installers while opening specification channels previously dominated by mechanical fastening.
REACH restrictions on isocyanate-containing products are forcing epoxy adhesive manufacturers toward amine-free curing agents and bio-based diluents. Industrial flooring contractors in the Netherlands and Belgium face mandatory substitution planning for existing product lines. Swimming pool specialists are responding fastest, with several Nordic installers already transitioning to waterborne urethane hybrids for submerged tile beds.
Specification authority is migrating from general contractors to specialized flooring consultants who bundle adhesive selection with moisture mitigation and surface preparation scope. Hospitality and retail rollout programs in the United Arab Emirates and Saudi Arabia are consolidating procurement through these consultant-led packages, compressing traditional distributor influence and favoring adhesive suppliers with certified installation training networks.
Tile and Stone Adhesive Market Segmentation
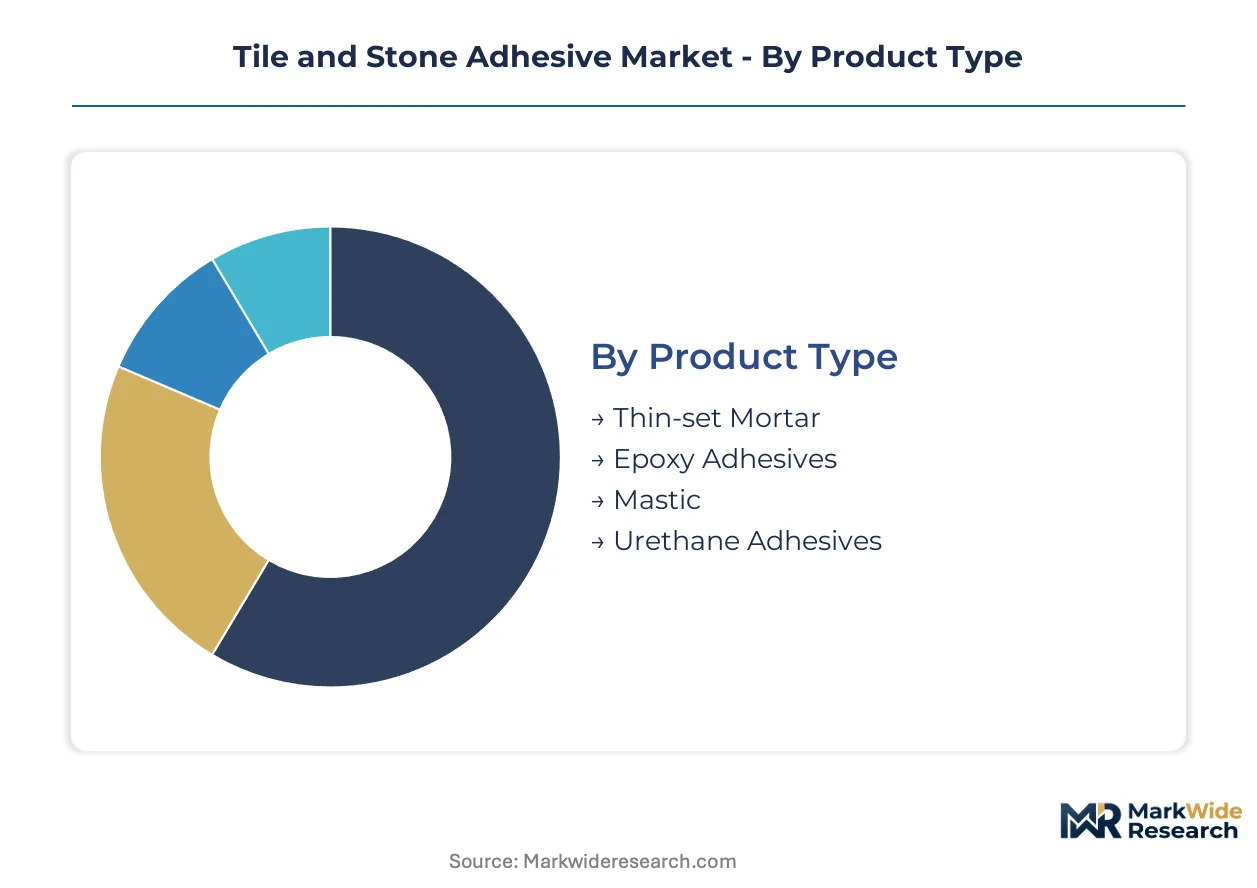
Segmentation in tile and stone adhesives reveals divergent margin structures across formulation chemistry and installation setting. Product type and application segment together determine pricing power, while end-user channel and substrate material dictate technical specification requirements.
Product Type:
Epoxy adhesives capture the highest margin pools due to chemical resistance premiums, while thin-set mortar dominates absolute volume throughput.
- Thin-set Mortar:Polymer-modified cementitious formulations achieve tensile adhesion exceeding 1.0 MPa after 28 days. Demand concentrates in India's western states where Gujarat and Maharashtra commercial flooring projects require rapid-setting variants capable of 24-hour return-to-service.
- Epoxy Adhesives:Two-part systems incorporating bisphenol-A and amine hardeners deliver submerged performance for swimming pool linings. Swimming pool specialists in Mediterranean climates command margin premiums 3-4x above standard thin-set for chemical-resistant installations.
- Mastic:Organic solvent-based or acrylic formulations serve light-duty interior applications with pre-mixed convenience for DIY renovation channels.
- Urethane Adhesives:Moisture-curing systems with enhanced flexibility address exterior facade movement joints; Nordic installers are transitioning to waterborne hybrids under REACH substitution mandates.
The dominant share belongs to thin-set mortar, while epoxy adhesives are closing the gap fastest through specification in high-value submerged applications.
Application:
Commercial spaces generate the steepest specification upgrades as retail and hospitality operators compress installation schedules.
- Commercial Spaces:Retail rollout programs in the United Arab Emirates and Saudi Arabia consolidate procurement through flooring consultant-led packages. These projects specify polymer-modified mortars with tensile adhesion above 1.5 MPa for large-format porcelain.
- Interior Flooring:Residential renovation activity among North American and European DIY enthusiasts expands ready-mixed adhesive consumption through home improvement retail channels.
- Exterior Facades:Porcelain cladding on high-rise buildings in Germany and Australia deploys hybrid polymer-cement systems with silane-modified polymers, compressing warranty exposure for installers.
- Swimming Pools:Submerged tile beds demand epoxy-based or waterborne urethane hybrid systems with complete chemical resistance; this segment faces mandatory substitution planning under Netherlands and Belgium regulations.
Commercial spaces command specification authority, while exterior facades are expanding most quickly through high-rise porcelain cladding adoption.
End User:
Contractor channels concentrate technical expertise requirements, whereas DIY channels reward packaging simplicity and pre-mixed convenience.
- Contractors:Certified installation training networks determine specification influence as flooring consultants bundle adhesive selection with moisture mitigation scope.
- DIY Enthusiasts:Home improvement retail channels in North America and Europe drive ready-mixed mastic and thin-set consumption with simplified application instructions.
- Construction Companies:Large-format tile installation demands specialized training in lippage control; certified installer pools are failing to match project growth in high-demand metros.
- Renovators:Residential pool renovation segments in Mediterranean climates represent untapped demand for epoxy-based systems with rapid return-to-service.
Contractors retain specification control, while DIY enthusiasts are gaining share fastest through retail channel expansion.
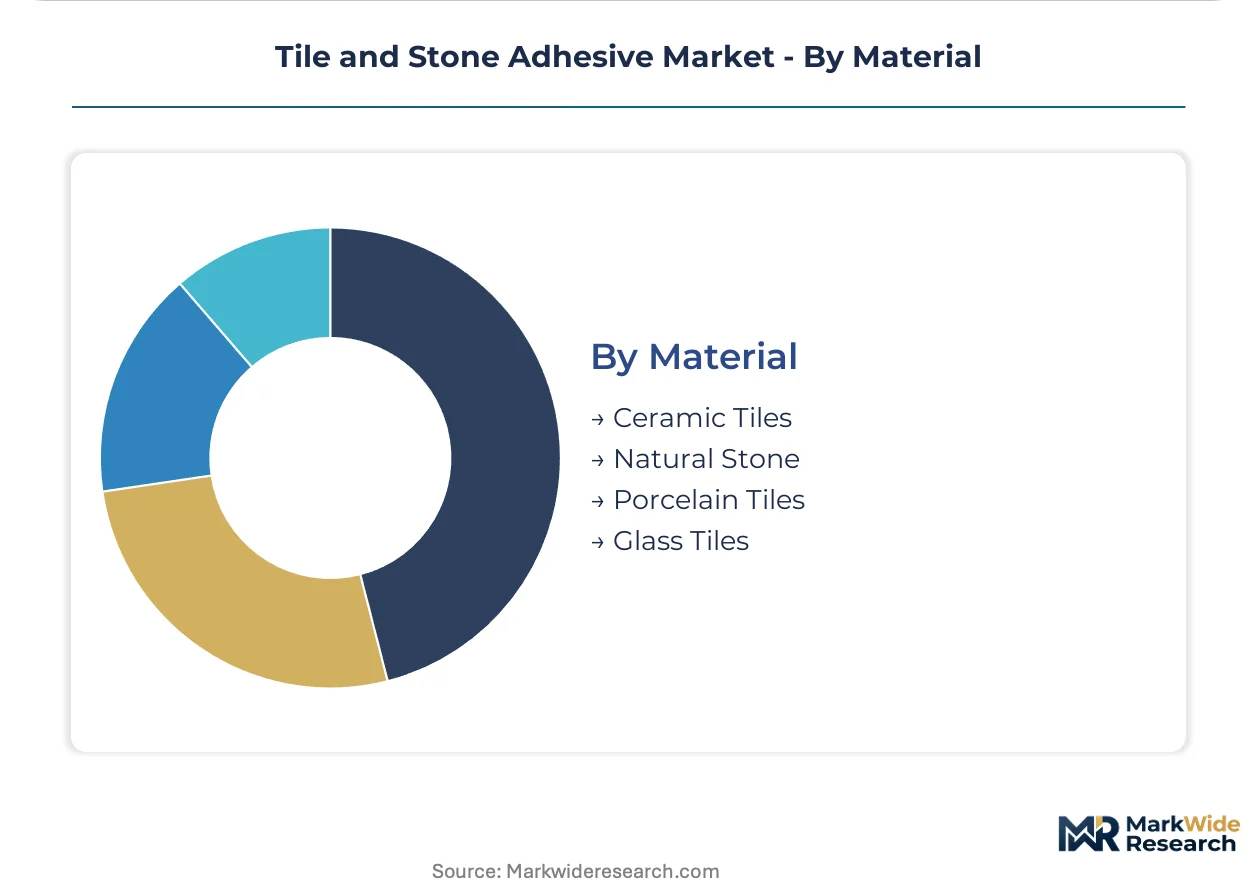
Material:
Porcelain tiles drive the most demanding adhesive specifications due to large-format dimensions and low porosity.
- Porcelain Tiles:Large-format installations compress curing cycles and demand polymer-modified mortars with reduced lippage; China's GB standards for construction chemicals are tightening VOC limits and pushing reformulation toward water-based systems.
- Ceramic Tiles:Standard wall and floor applications maintain thin-set mortar dominance across residential and light commercial projects.
- Natural Stone:Heavy, moisture-sensitive substrates require specialized bonding agents with enhanced flexibility and substrate preparation protocols.
- Glass Tiles:Translucent installations demand white or transparent adhesive formulations with non-staining characteristics for aesthetic consistency.
Porcelain tiles anchor technical specification, while natural stone is climbing the fastest through premium residential and hospitality applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinker production clusters in China, Germany, and India transmit input cost volatility to cementitious adhesive margins worldwide. Regional regulatory divergence—GB standards in China, REACH in Europe, EPA enforcement in the United States—compels manufacturers to maintain parallel formulation portfolios. Demand concentrates in metropolitan construction corridors where large-format porcelain specification drives polymer-modified mortar upgrades.
China
Commercial flooring projects in Shanghai and Guangzhou specify rapid-setting thin-set mortars for 24-hour return-to-service. GB 30982 standards under MEE tighten VOC limits and mandate water-based acrylic reformulations. The Yangtze River Delta anchors polymer additive manufacturing, with Zhejiang and Jiangsu provinces supplying redispersible powders to domestic mortar producers.
Germany
Porcelain cladding on high-rise buildings in Frankfurt and Munich deploys hybrid polymer-cement systems with silane-modified polymers. ECHA REACH restrictions on isocyanate-containing products force epoxy manufacturers toward amine-free curing agents. The North Rhine-Westphalia industrial corridor concentrates construction chemical R&D, with Cologne-Düsseldorf metro plants serving Benelux export markets.
India
Gujarat and Maharashtra commercial flooring projects concentrate demand for rapid-setting adhesives capable of accelerated curing cycles. BIS certification requirements for construction chemicals tighten quality thresholds for imported polymer additives. The Mumbai-Pune industrial belt hosts blending facilities serving western state retail and hospitality rollout programs.
United States
DIY renovation activity in Texas and Florida expands ready-mixed adhesive consumption through home improvement retail channels. EPA and OSHA enforce workplace exposure limits during adhesive mixing, shaping contractor training protocols. The Southeast construction corridor—Atlanta, Charlotte, Miami—generates specification volume for large-format porcelain in hospitality and retail fit-outs.
United Arab Emirates
Hospitality and retail rollout programs in Dubai and Abu Dhabi consolidate procurement through flooring consultant-led packages. MOHAP and local municipal authorities enforce construction product labeling standards for imported adhesives. The Dubai Design District and EXPO 2020 legacy districts drive specification upgrades toward polymer-modified mortars with enhanced bond strength.
Tile and Stone Adhesive Market Competitive Landscape
Concentration sits with diversified construction chemical conglomerates and specialized adhesive manufacturers operating across tiered technology segments. The vendor base stratifies between scale-driven polymer producers, regional formulation specialists, and application-technology providers. Three archetypes dominate: European-headquartered construction chemical majors with captive polymer additive supply; Asia-Pacific formulation specialists with distribution depth in emerging markets; and North American technology providers focused on high-performance epoxy and urethane systems. Competitive dynamics center on backward integration into polymer raw materials and certification network expansion for large-format tile installation training.
Within the European-headquartered tier, MAPEI S.p.A. and Saint-Gobain Weber exemplify scale-driven construction chemical operations with integrated supply chains. Sika AG and ARDEX GmbH occupy positions in specialty mortar and substrate preparation systems. LATICRETE International, Inc. represents the North American high-performance segment, while Pidilite Industries Limited anchors the Asia-Pacific formulation specialist archetype with distribution infrastructure across Indian tier-two and tier-three cities.
| Leading Market Players |
|---|
| Bostik S.A.S. |
| Saint-Gobain Weber |
| MAPEI S.p.A. |
| Fosroc International Limited |
| Henkel AG & Co. KGaA |
| ARDEX GmbH |
| LATICRETE International, Inc. |
| Pidilite Industries Limited |
| Sika AG |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for redispersible polymer powders translate directly into margin compression for cementitious adhesive producers when clinker prices spike, binding pricing power to upstream chemical concentration in the Yangtze River Delta and Gujarat industrial corridors.
Pricing Analysis
GB 30982 standards under China's MEE dictate the pricing tier structure by mandating water-based acrylic reformulations that separate premium low-VOC systems from conventional solvent-containing grades. Price differentiation hinges on certification grade against EN 12004 and ANSI A118 protocols plus volume scale for project contractors. Cost compression in standard thin-set mortar is intensifying because Portland cement faces EU ETS carbon pricing pressure. DIY enthusiasts through home improvement retail channels exhibit highest price sensitivity, while swimming pool contractors accept premium positioning for submerged epoxy systems.
Supply Chain Analysis
China and Germany anchor polymer additive manufacturing, with Zhejiang and North Rhine-Westphalia plants feeding redispersible powder and silane-modified polymer production. Bisphenol-A and amine hardener supply chains draw from Northeast Asian petrochemical complexes, while clinker sourcing concentrates in China, India, and Germany. Single-source vulnerability around epoxy raw materials creates geographic concentration risk for high-performance adhesive producers. Distribution runs through construction chemical distributors, flooring consultant-led procurement packages, and home improvement retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tile and stone adhesive market builds defensive moats through regulatory entrenchment: REACH, GB standards, and EPA enforcement create formulation compliance barriers that lock in incumbent positions and delay new entrant timelines.
For Market Incumbents: Consolidate backward integration into redispersible polymer powders to offset Portland cement volatility under EU ETS pressure. Expand certified installer training networks in India's western states and the UAE to capture flooring consultant-led procurement consolidation. Defend against emerging Asia-Pacific formulation specialists by deepening captive supply of hydrophobic polymer additives for exterior facade applications. For New Entrants and Emerging Players: ANSI A118 certification fast-tracks unlock specification access for large-format porcelain installations in Texas and Florida hospitality fit-outs. Target residential pool renovation segments in Mediterranean climates with waterborne urethane hybrid systems under REACH substitution mandates. Pursue white-label partnerships with Indian tier-two distributors to bypass Pidilite's dealer network density. For Investors and Strategic Acquirers: Carve-out targets emerge from European construction chemical conglomerates divesting non-core adhesive portfolios under EU Green Deal consolidation pressure. Five-to-ten-year viability hinges on Environmental Product Declaration verification and circular material content credentials. Monitor BIS certification enforcement in India as an inflection indicator for imported polymer additive market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Additives | Captive supply of redispersible powders insulates margins from clinker volatility under EU ETS. |
| Certified Installer Network Expansion | Flooring consultants in UAE and Saudi Arabia bundle adhesive specification with moisture mitigation scope. |
| Water-Based Acrylic Reformulation | GB 30982 compliance opens premium positioning in Shanghai and Guangzhou commercial flooring. |
| Regional Production Investment | Mumbai-Pune blending facilities serve Gujarat and Maharashtra rapid-setting adhesive demand. |
| Environmental Product Declaration Verification | EU Green Deal procurement mandates reward manufacturers with verified lifecycle data. |
Research Methodology
The analysis maps thin-set mortar, epoxy adhesive, mastic, and urethane segments, each validated through plant managers at cementitious blending facilities, procurement leads at commercial flooring contractors, distribution channel partners in Indian tier-two cities, and technical R&D directors at polymer additive suppliers. Primary interview insights triangulate against customs and trade data, construction chemical association reports, SEC 10-K filings, and BIS certification databases. Bottom-up volume builds from regional project pipelines and substrate material specifications cross-check against top-down construction spending forecasts.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions model formulation chemistry, application setting, end-user channel, and substrate material type. CAGRs derive from adhesive consumption per square meter of installed tile, large-format porcelain specification penetration, and regional construction cycle timing. Industry-specific forecast inputs include clinker price indices, redispersible powder capacity utilization, and flooring consultant procurement consolidation rates.
The analysis sits within stated boundaries; outcomes outside sustained commercial construction activity, stable polymer additive supply chains, or continued regulatory tightening on VOC emissions would require recalibration. Forecasts reflect documented assumptions about installer certification expansion and water-based system adoption curves. Recalibration cycles align with material shifts in GB standards enforcement, REACH substitution mandates, and EU ETS carbon price trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Global Epoxy Tooling Board Market