
 Grignard Reagents Market | 2026-2036
Grignard Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Grignard Reagents Market Outlook
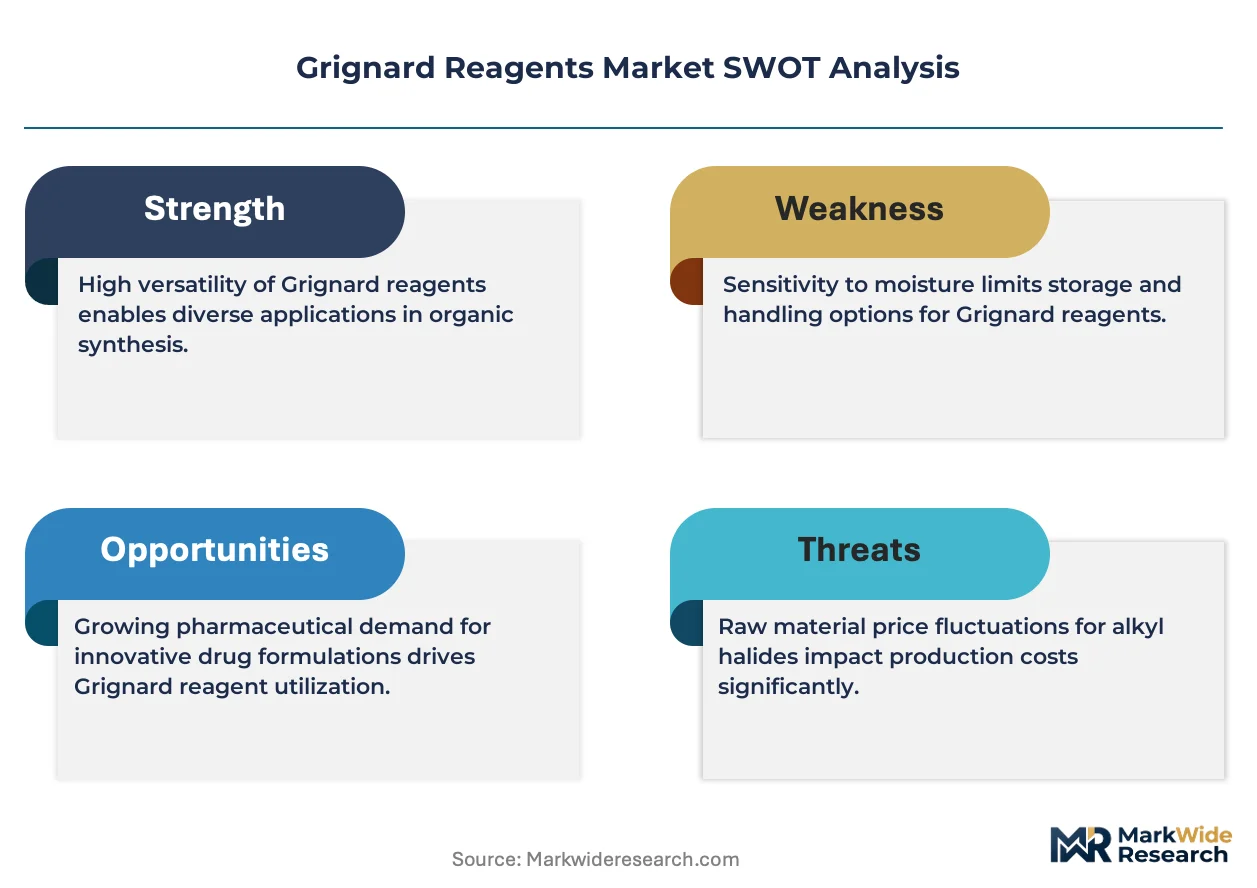
The capital-intensity gap between integrated producers and merchant suppliers is collapsing as continuous-flow organometallic synthesis reduces batch-scale barriers. Merck KGaA leverages its pharmaceutical-grade solvent infrastructure to sustain captive Grignard output for internal API pipelines. Albemarle Corporation anchors North American bromine-derived Grignard supply through backward integration into elemental bromine extraction. FAR Chemical competes on custom aryl Grignard manufacturing for agrochemical innovators requiring non-catalog substitutions.
Grignard reagents are organomagnesium halides synthesized via magnesium insertion into carbon-halogen bonds, typically prepared in ethereal solvents under anhydrous conditions with functional group tolerance dictating substrate scope; their primary purpose is nucleophilic carbon-carbon bond formation in pharmaceutical and fine chemical synthesis. Alkyl Grignard reagents dominate tonnage demand for bulk pharmaceutical intermediate construction, while bimetallic Grignard variants command premium positioning in stereoselective catalysis where dual-metal cooperativity unlocks previously inaccessible molecular architectures. Industrial grade material anchors volume economics for commodity chemical manufacturers, though high purity grades capture disproportionate margin pools from peptide and oligonucleotide contract manufacturers facing tightening impurity specifications.
EPA enforcement of TSCA Section 5 premanufacture notifications shapes US market access for novel Grignard formulations, while REACH registration dossiers under ECHA jurisdiction govern European commercialization pathways for imported organomagnesium compounds. China's NMPA alignment with ICH Q3D elemental impurity guidelines is forcing reformulation of Grignard-derived APIs bound for regulated markets. Stakeholders must monitor regulatory divergence between FDA nitrosamine risk assessment frameworks and EMA revised specifications for metal catalyst residues in synthesized drug substances.
Market Dynamics
Continuous-flow organometallic synthesis is collapsing the capital-intensity gap between integrated producers and merchant suppliers, redistributing competitive advantage toward agile specialty manufacturers.
Growth Catalysts
- CDMO scaling:Pharmaceutical contract manufacturers are expanding complex molecule production pipelines, pulling demand for high-purity alkyl Grignard intermediates.
- REACH compliance:ECHA's tightened purity documentation requirements for cross-border shipments are favoring suppliers with established European regulatory dossiers.
- Stereoselective catalysis:Bimetallic Grignard variants are unlocking previously inaccessible molecular architectures in peptide and oligonucleotide synthesis.
Market Restraints
- Magnesium price volatility:Raw material cost swings compress margins for batch-scale producers lacking long-term supply contracts.
- German supply concentration:Production gravity around Frankfurt and Ludwigshafen creates geographic vulnerability to regional logistics disruptions.
- Substitution by organolithium reagents:Lithium-based alternatives are capturing select applications requiring higher nucleophilicity.
Strategic Opportunities
- Agrochemical custom synthesis:Non-catalog aryl Grignard manufacturing for crop science innovators represents underserved white space.
- ICH Q3D alignment:China's NMPA adoption of elemental impurity guidelines creates reformulation service demand for API exporters.
- Continuous-flow retrofitting:Modular reactor technology convergence with AI-driven process control enables distributed production models.
Industry Challenges
- Anhydrous handling expertise:Pyrophoric organometallic chemistry requires specialized technical talent pools that remain shallow outside established chemical corridors.
- TSCA Section 5 timelines:EPA premanufacture notification reviews for novel Grignard formulations extend commercialization cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grignard Reagents Market |
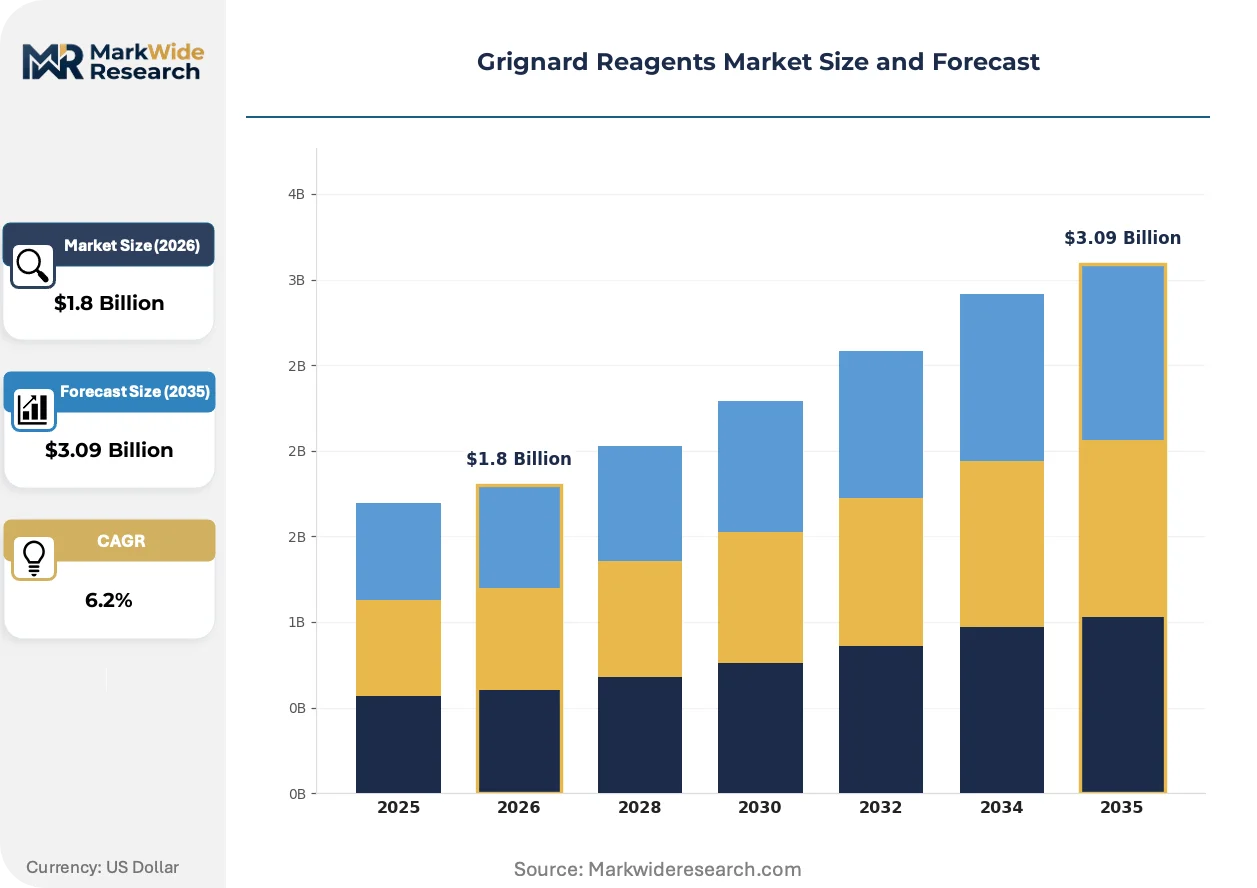
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Grignard Reagents, Aryl Grignard Reagents, Vinyl Grignard Reagents, Bimetallic Grignard Reagents Grade: Analytical Grade, Industrial Grade, Research Grade, High Purity Application: Synthesis, Catalysis, Pharmaceutical Intermediates, Organic Chemistry End User: Chemical Manufacturers, Pharmaceutical Companies, Academic Institutions, Research Laboratories |
| Companies Covered | HOKKO CHEMICAL INDUSTRY CO., LTD., FAR Chemical, Merck KGaA, PMC Group, Inc., Boulder Scientific Group, Albemarle Corporation, CHEMIUM srl, Neogen Chemicals Ltd, WeylChem International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grignard Reagents Market Strategic Shifts
Flow chemistry platforms are rewriting process economics while regulatory divergence between FDA and EMA frameworks forces dual-track compliance strategies.
Microreactor-based Grignard formation is supplanting traditional batch kettle operations in pharmaceutical intermediate manufacturing. CDMOs serving innovator drug companies are adopting continuous-flow systems at accelerating rates. This technology is supplanting legacy infrastructure investments, compressing breakeven thresholds for mid-scale producers.
EMA's revised specifications for metal catalyst residues in synthesized drug substances are diverging from FDA nitrosamine risk assessment frameworks. European peptide manufacturers must now maintain dual impurity testing protocols for export-bound versus domestic batches. High-purity grade suppliers with established EMA dossiers are capturing margin premiums from contract manufacturers facing retesting burdens.
Direct sourcing agreements between agrochemical innovators and specialty Grignard manufacturers are bypassing traditional distributor networks. Custom synthesis providers are disintermediating catalog chemical houses for non-standard aryl substitutions. This channel compression is most visible in Germany's specialty chemical corridor, where proximity enables just-in-time delivery models.
Grignard Reagents Market Segmentation
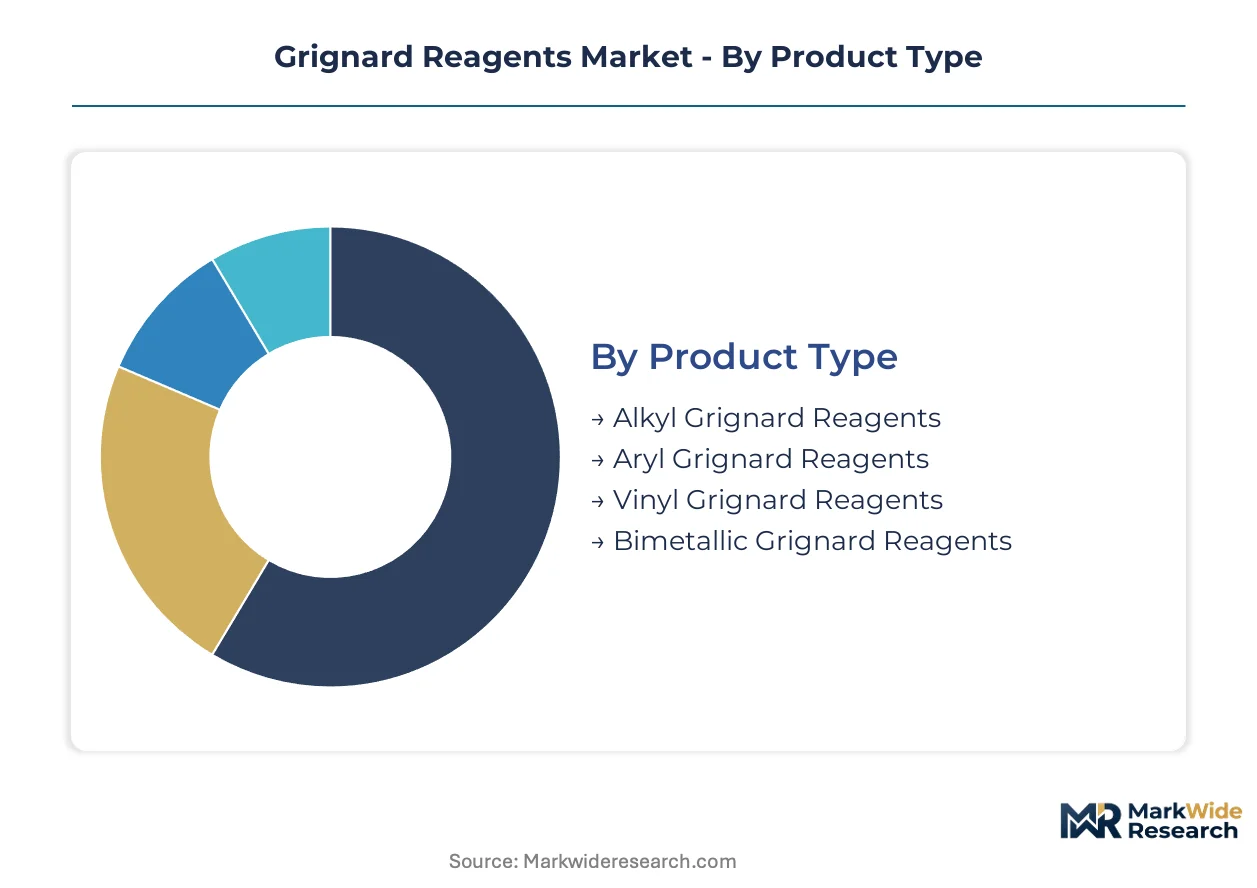
Grignard reagents fragment across four distinct axes that reshape procurement patterns and margin structures. Product type and grade specifications determine regulatory compliance burdens, while application and end-user splits dictate channel strategies and technical service intensity.
Product Type:
Domestic consumption patterns diverge sharply from export-led demand across these four chemistries, with alkyl variants serving commodity pharmaceutical flows while bimetallic grades target specialized stereoselective applications.
- Alkyl Grignard Reagents:These magnesium alkyl halides constitute the workhorse chemistry for carbon-carbon bond formation in bulk pharmaceutical intermediate construction. Demand concentrates in Germany's Frankfurt-Ludwigshafen corridor where CDMOs scale complex molecule production under REACH-compliant documentation protocols.
- Bimetallic Grignard Reagents:Dual-metal cooperativity architectures enable previously inaccessible stereoselective catalysis in peptide and oligonucleotide synthesis. Export-led demand from Swiss and Belgian contract manufacturers drives premium positioning as these reagents command specialized handling expertise and anhydrous logistics infrastructure.
- Aryl Grignard Reagents:Phenyl and substituted aryl magnesium halides serve agrochemical innovators requiring non-catalog substitutions for crop protection chemistry development.
- Vinyl Grignard Reagents:Alkenyl magnesium compounds support fine chemical synthesis with functional group tolerance constraints limiting substrate scope to specialized applications.
Alkyl Grignard reagents hold the largest share; momentum sits with bimetallic variants as stereoselective catalysis expands.
Grade:
Cost tier stratification separates captive pharmaceutical-grade production from merchant industrial supply, with purity specifications directly determining regulatory dossier complexity and cross-border shipment eligibility.
- High Purity:Sub-ppm impurity specifications serve peptide and oligonucleotide contract manufacturers facing tightening EMA metal catalyst residue limits. These grades capture disproportionate margin pools from European manufacturers maintaining dual testing protocols for export-bound versus domestic batches.
- Industrial Grade:Standard purity material anchors volume economics for commodity chemical manufacturers with less stringent functional group tolerance requirements. Batch-scale producers lacking long-term magnesium supply contracts face compressed margins from raw material price volatility.
- Analytical Grade:Certified reference materials support quality control laboratories and method validation workflows in regulated pharmaceutical environments.
- Research Grade:Small-batch production for academic discovery chemistry and early-stage pharmaceutical development programs with limited scale requirements.
Industrial grade dominates tonnage; high purity grades are gaining share fastest as impurity specifications tighten across regulated markets.
Application:
Customer type clustering shows synthesis and pharmaceutical intermediate applications pulling toward integrated producers with captive solvent infrastructure, while catalysis applications favor agile specialty manufacturers.
- Pharmaceutical Intermediates:CDMO scaling of complex molecule production pipelines drives demand for documented purity with established ECHA dossiers. Continuous-flow organometallic synthesis is redistributing competitive advantage toward mid-scale producers retrofitting modular reactor systems.
- Catalysis:Stereoselective applications in fine chemical manufacturing require bimetallic variants with dual-metal cooperativity. Technical service intensity favors suppliers with specialized organometallic chemistry expertise and anhydrous handling capabilities.
- Synthesis:General carbon-carbon bond formation across pharmaceutical and agrochemical value chains with functional group tolerance dictating substrate scope selection.
- Organic Chemistry:Discovery-phase applications in academic and industrial research settings with limited scale and high formulation diversity requirements.
Pharmaceutical intermediates command the greatest value concentration; catalysis applications show the steepest expansion trajectory as stereoselective demand intensifies.
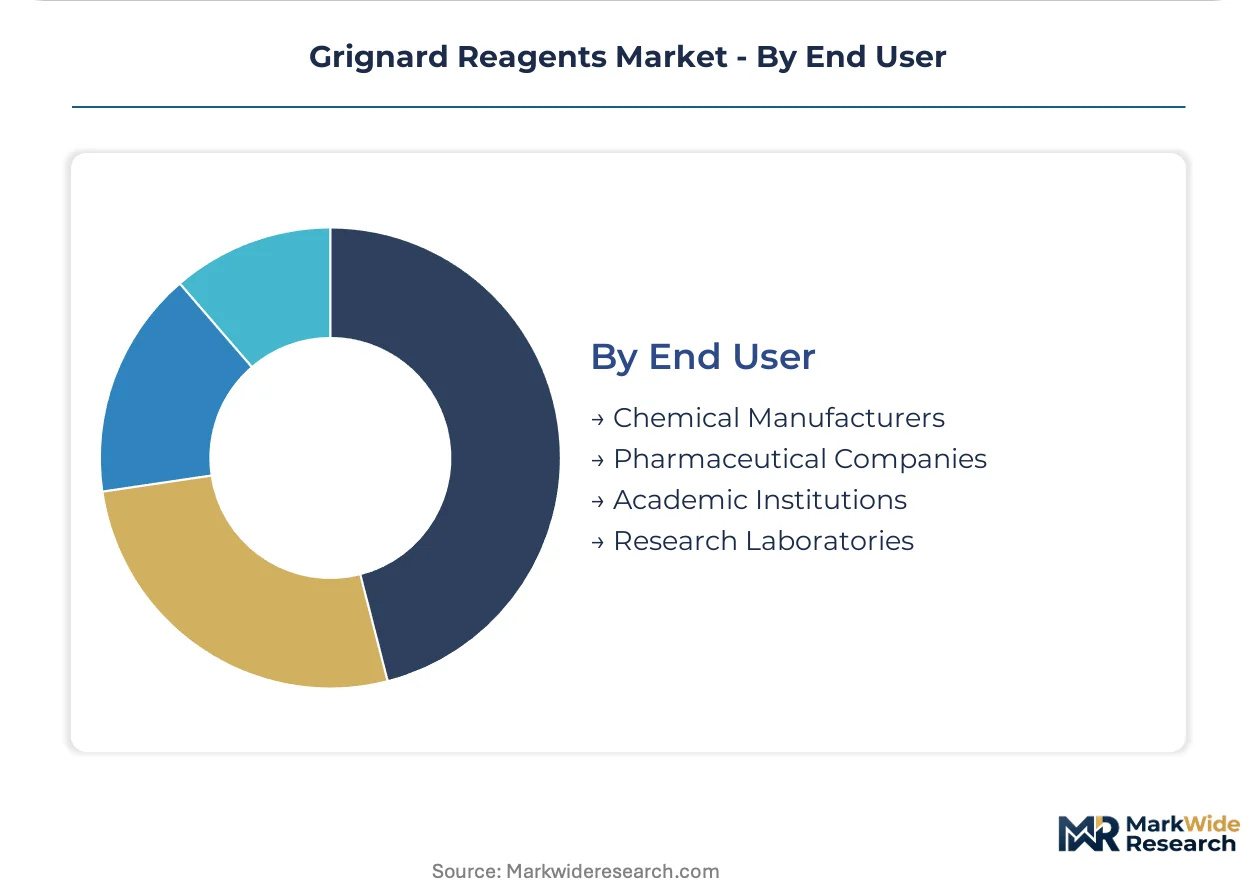
End User:
Supply concentration patterns reveal chemical manufacturers and pharmaceutical companies consolidating procurement around established European regulatory dossiers, while academic and research segments fragment across catalog distributors.
- Chemical Manufacturers:Commodity and specialty chemical producers with captive Grignard requirements or merchant supply dependencies. Continuous-flow retrofitting enables distributed production models compressing breakeven thresholds for mid-scale operations.
- Pharmaceutical Companies:Innovator drug companies and their CDMO partners requiring high-purity grades with ICH Q3D elemental impurity alignment for regulated market access.
- Research Laboratories:Industrial R&D facilities with custom synthesis requirements and non-standard aryl substitution needs bypassing traditional distributor networks.
- Academic Institutions:University chemistry departments with training and discovery mandates, price-sensitive procurement, and limited anhydrous handling infrastructure.
Chemical manufacturers represent the largest demand pool; pharmaceutical companies are expanding most quickly as CDMO outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grignard reagent consumption patterns diverge sharply by geography: European pharmaceutical corridors prioritize REACH-documented high-purity grades, while Asian manufacturing hubs absorb industrial-grade tonnage for agrochemical intermediate construction.
Germany
CDMO scaling of complex molecule production pulls documented alkyl Grignard intermediates into the Frankfurt-Ludwigshafen specialty chemical corridor. ECHA's tightened purity documentation requirements for cross-border shipments favor suppliers with established REACH registration dossiers. Continuous-flow retrofitting of modular reactor systems is redistributing competitive advantage toward mid-scale producers in Hesse and Baden-Württemberg.
United States
Agrochemical innovators requiring non-catalog aryl substitutions drive custom synthesis demand bypassing traditional distributor networks. EPA enforcement of TSCA Section 5 premanufacture notifications extends commercialization cycles for novel Grignard formulations by 12-18 months. Albemarle Corporation anchors bromine-derived supply through backward integration into elemental bromine extraction operations.
China
NMPA alignment with ICH Q3D elemental impurity guidelines forces reformulation of Grignard-derived APIs bound for regulated export markets. The country's national pharmaceutical regulator is tightening metal catalyst residue specifications for synthesized drug substances. Yangtze River Delta contract manufacturers are absorbing disproportionate retesting burdens for European-bound versus domestic batches.
Switzerland
Swissmedic oversight of peptide and oligonucleotide manufacturing drives premium positioning for bimetallic Grignard variants with dual-metal cooperativity. Export-led demand from Basel-area contract manufacturers commands specialized handling expertise and anhydrous logistics infrastructure. High-purity grade suppliers capture margin premiums from manufacturers maintaining dual impurity testing protocols.
India
CDSCO pharmaceutical oversight is accelerating ICH Q3D compliance timelines for API exporters serving regulated markets. Maharashtra and Gujarat-based manufacturers are scaling merchant Grignard output for pharmaceutical intermediate construction. Domestic magnesium price volatility compresses margins for batch-scale producers lacking long-term raw material supply contracts.
Grignard Reagents Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with backward integration into elemental feedstocks separating captives from merchant suppliers. The capital-intensity gap between these tiers is collapsing as continuous-flow organometallic synthesis reduces batch-scale barriers. Three archetypes dominate: integrated chemical conglomerates with captive pharmaceutical-grade solvent infrastructure, bromine-backed specialists with upstream control over halogen feedstocks, and agile custom synthesis providers serving non-catalog agrochemical demand. Competitive moves center on continuous-flow retrofitting partnerships and regulatory dossier consolidation around established ECHA and FDA pathways.
Among integrated German chemical producers, Merck KGaA exemplifies the captive infrastructure archetype through pharmaceutical-grade solvent networks sustaining internal API pipelines. FAR Chemical occupies a position within the custom synthesis tier, representing specialists competing on non-catalog aryl Grignard manufacturing for agrochemical innovators. Albemarle Corporation anchors the halogen-integrated archetype among North American players, with its company name signaling bromine-derived supply chain positioning.
| Leading Market Players |
|---|
| HOKKO CHEMICAL INDUSTRY CO., LTD. |
| FAR Chemical |
| Merck KGaA |
| PMC Group, Inc. |
| Boulder Scientific Group |
| Albemarle Corporation |
| CHEMIUM srl |
| Neogen Chemicals Ltd |
| WeylChem International GmbH |
| Others |
Value Chain & Pricing Dynamics
Organolithium substitution in high-nucleophilicity applications is simultaneously redrawing supply geography toward lithium-rich salt brine regions and compressing pricing power for traditional magnesium-based producers in established chemical corridors.
Pricing Analysis
After-sales technical service contracts for anhydrous handling and on-site process support drive lifetime value more than commodity reagent sales alone. Three-tier pricing structure across high-purity, industrial, and research grades separates peptide manufacturers facing EMA metal residue limits from agrochemical bulk consumers. Cost compression in industrial-grade alkyl variants is intensifying as Chinese merchant producers scale continuous-flow output. Research laboratories exhibit highest price sensitivity due to budget-constrained procurement, while Swiss peptide contract manufacturers absorb premium pricing for documented bimetallic grades.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and constrained refrigerated container availability on Asia-Europe trade lanes are elevating landed costs for anhydrous ether solvents critical to Grignard stability. Production gravity centers on Germany, China, and the United States, with the Frankfurt-Ludwigshafen corridor hosting the densest specialty chemical infrastructure. Magnesium ingot and anhydrous ether solvents constitute the core input dependencies. Single-source vulnerability to German supply concentration creates structural risk during regional logistics disruptions. Distribution runs through direct sourcing agreements between agrochemical innovators and custom synthesis providers, bypassing traditional catalog chemical houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow organometallic synthesis constitutes a high-growth disruption, with ECHA's tightened REACH documentation requirements accelerating technology substitution toward agile producers capable of rapid regulatory dossier adaptation.
For Market Incumbents: Secure backward integration into elemental magnesium or bromine feedstocks to buffer raw material price volatility compressing batch-scale margins. Consolidate regulatory dossier advantages by expanding ECHA registration coverage ahead of competitor filings, as REACH compliance documentation increasingly determines cross-border shipment eligibility against emerging Chinese merchant suppliers. For New Entrants and Emerging Players: Lead with continuous-flow retrofitting partnerships serving mid-scale CDMOs in Hesse and Baden-Württemberg seeking distributed production models. Agrochemical custom synthesis for non-catalog aryl substitutions represents the most penetrable white space, with direct sourcing relationships bypassing traditional distributor networks offering the clearest go-to-market path. For Investors and Strategic Acquirers: Capital is best deployed toward continuous-flow technology enablers and regulatory dossier consolidators with established ECHA pathways. Long-term viability over the next decade favors producers combining modular reactor infrastructure with proven anhydrous handling expertise. Watch for inflection signals in EPA TSCA Section 5 premanufacture notification timelines, as accelerated review pathways would signal regulatory acceptance of novel Grignard formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Retrofitting | Modular reactor adoption by German CDMOs collapses breakeven thresholds for mid-scale alkyl Grignard production. |
| Backward Integration into Bromine | Upstream control over elemental halogen feedstocks anchors supply security for aryl Grignard variants in North American markets. |
| REACH Dossier Consolidation | Established ECHA registration pathways capture margin premiums from contract manufacturers facing dual testing protocols. |
| Direct Sourcing Agreements | Channel compression with agrochemical innovators bypasses catalog chemical houses for non-standard substitution requirements. |
| ICH Q3D Alignment Services | Reformulation expertise for API exporters serving regulated markets addresses NMPA's tightened metal residue specifications. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CDMO procurement directors, plant managers at German specialty chemical producers, regulatory affairs leads navigating REACH compliance, and technical R&D directors overseeing organometallic synthesis. Secondary validation drew from ECHA registration dossiers, customs trade data for organomagnesium compound shipments, SEC filings of listed chemical producers, and Cefic sector reports. Bottom-up volume estimates from individual production facilities were triangulated against top-down demand aggregation across pharmaceutical and agrochemical end-use segments.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type chemistry, grade purity tier, application intensity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume movements adjusted for technology substitution effects. Forecast inputs incorporated magnesium price volatility patterns, CDMO outsourcing acceleration rates, and continuous-flow adoption curves in European pharmaceutical corridors.
The analysis sits within stated boundaries; outcomes outside sustained EMA-FDA regulatory divergence or abrupt magnesium supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding REACH enforcement intensity and ICH Q3D adoption timelines in Asian export markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Enzyme Substrates Market