
 Core Plate Varnishes Market | 2026-2036
Core Plate Varnishes Market Size, Share, and Industry Trends Forecast 2026-2036
Core Plate Varnishes Market Analysis
Market Context
The EU Green Deal is hardening emissions benchmarks for industrial coatings, compelling varnish producers to accelerate low-VOC formulations. AXALTA extends its technology leadership in solvent-borne insulating systems across European transformer OEMs. Beckers Group anchors its position through backward integration into resin synthesis, securing supply continuity for heat-resistant grades. JOHN C. DOLPH COMPANY specializes in impregnating varnishes for North American motor rebuilders, sustaining decades of application-specific expertise.
Technical Definition and Segment Structure
Core plate varnishes are thermosetting resin systems, typically alkyd-, epoxy-, or polyester-based, applied to laminated electrical steel cores to reduce eddy current losses and prevent interlaminar corrosion in transformers, motors, and generators. Electrical insulating varnish dominates product type demand due to its indispensability in medium-voltage transformer stacks, where dielectric integrity determines equipment lifespan. Powder formulations are gaining traction among OEMs seeking to eliminate solvent recovery infrastructure and reduce curing energy. Repair shops represent a concentrated margin pool within end users, as emergency refurbishment cycles command premium pricing and expedited delivery.
Regulatory Framework and Outlook
REACH in Europe, EPA air quality standards in the United States, and China's GB standards on industrial coatings collectively constrain permissible solvent content and mandate hazard communication protocols. These frameworks elevate compliance costs for smaller compounders while creating technical barriers that favor established laboratories with certified testing capabilities. Stakeholders must monitor evolving substance restriction lists and pre-qualify alternative chemistries before existing formulations face sunset clauses.
Market Dynamics
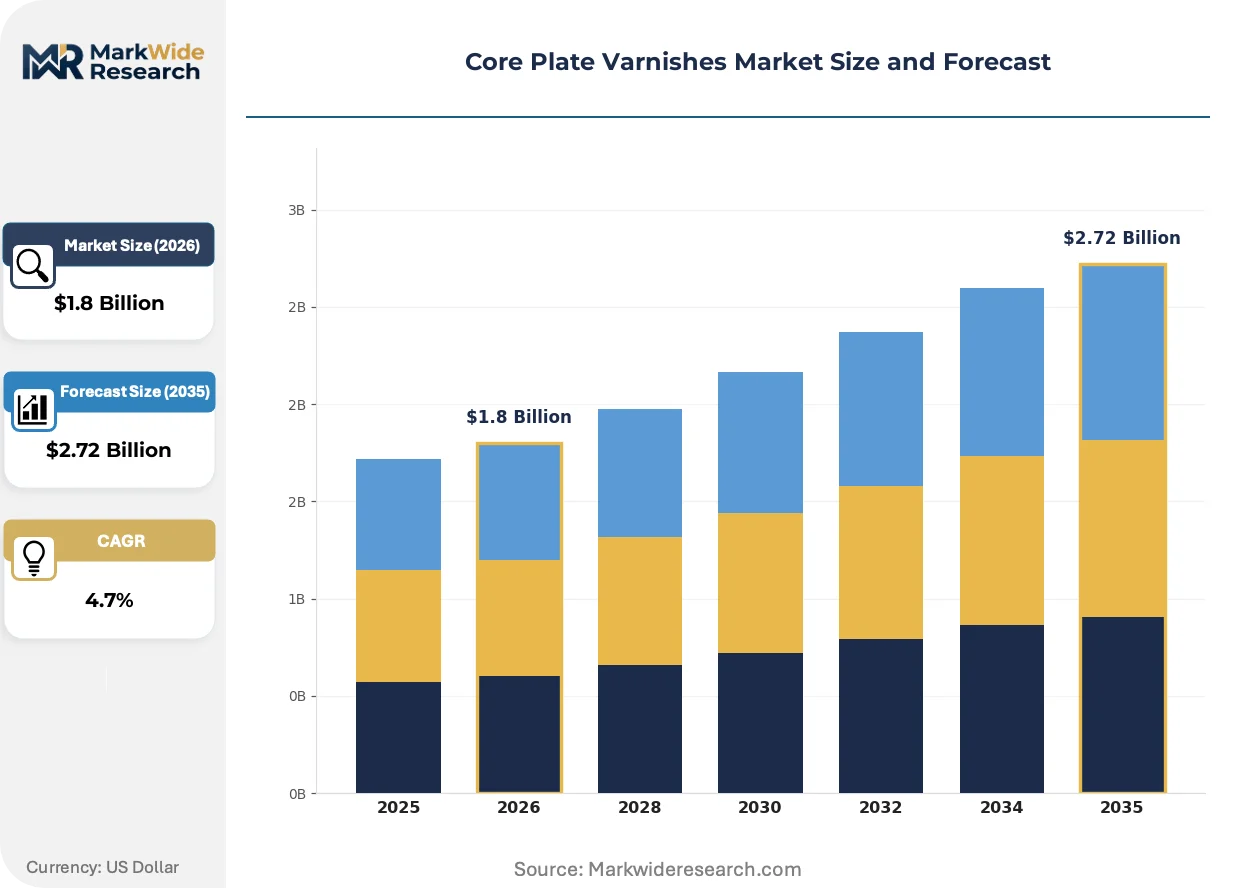
Transformer refurbishment cycles across India's power sector are compressing replacement timelines, while REACH solvent restrictions in Europe force simultaneous reformulation investments. These dual pressures reshape capacity allocation and R&D prioritization for varnish compounders serving electrical steel laminators.
Growth Catalysts
- Transformer Refurbishment Mandates:India's Central Electricity Authority directives on distribution network upgrades accelerate demand for re-insulation materials. State utilities in Maharashtra and Gujarat commission emergency core stack rebuilds.
- REACH VOC Threshold Tightening:ECHA's progressive volatile organic compound limits compel solvent-free varnish adoption. German and French OEMs pre-qualify waterborne and powder systems for medium-voltage equipment.
- High-Efficiency Motor Manufacturing:China's dual carbon goals drive IE4 and IE5 motor production. Domestic OEMs in Jiangsu and Zhejiang provinces scale captive varnish consumption for laminated rotor cores.
Market Restraints
- Specialty Resin Supply Concentration:Heat-resistant polyester and epoxy intermediates concentrate among Japanese and German chemical suppliers. Geopolitical friction elevates procurement risk for non-integrated compounders.
- Substrate Substitution Threat:Amorphous metal ribbons displace grain-oriented electrical steel in select distribution transformer designs. Core plate varnish relevance diminishes where lamination counts drop.
- Energy-Curing Equipment Capex:UV and electron-beam curing systems require seven-figure capital commitments. Smaller motor repair shops defer powder varnish adoption despite operational savings.
Strategic Opportunities
- Southeast Asia Grid Expansion:Vietnam and Indonesia transmission buildouts lack established varnish supply chains. First-mover compounders secure offtake agreements with emerging transformer OEMs.
- Solvent-Free System Convergence:Powder coating technology merges with vacuum pressure impregnation processes. Hybrid systems eliminate solvent recovery while maintaining impregnation depth.
- US IRA Manufacturing Credits:Domestic content bonuses for electrical equipment incentivize reshoring of varnish production. Texas and Ohio motor plants seek qualified local suppliers.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in thermosetting resin design for electrical applications concentrates among retiring specialists. Knowledge transfer gaps threaten innovation continuity.
- Multi-Jurisdiction Certification Lag:UL, VDE, and BIS testing sequences for new chemistries extend eighteen to thirty months. Reformulation windows compress against regulatory sunset clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Core Plate Varnishes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Insulating Varnish, Heat-resistant Varnish, Corrosion-resistant Varnish, Water-resistant Varnish Application: Transformers, Electric Motors, Generators, Coils Form: Liquid, Powder, Film, Paste End User: Manufacturers, Service Providers, Repair Shops, OEMs |
| Companies Covered | AXALTA, SSAB AB, Helios Group, Mäder, Beckers Group, Rembrandtin Lack GmbH, TOYO INK, JOHN C. DOLPH COMPANY, ALTANA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Core Plate Varnishes Market Emerging Trajectories
Active material science programs are collapsing the performance gap between solvent-borne heritage systems and emerging low-emission alternatives. Three developmental trajectories dominate competitive positioning.
Nano-modified epoxy dispersions are integrating sub-micron ceramic fillers to enhance thermal conductivity without sacrificing dielectric strength. Tier-one transformer OEMs in Germany and Japan pilot these systems for high-load density applications. The technology is integrating into qualification protocols that previously excluded waterborne candidates.
EPA air quality standards for industrial surface coating operations tighten permissible hazardous air pollutant emissions from electrical equipment finishing. US-based motor manufacturers face consent decree timelines that accelerate solvent reduction investments. Medium-voltage transformer rebuilders in the Midwest retrofit spray booths and thermal oxidizers to maintain operating permits.
Buyer consolidation among Chinese electric motor OEMs concentrates procurement authority with engineering teams that specify varnish systems directly. Distributor influence erodes as annual framework agreements replace spot purchasing. This pattern is most visible in Jiangsu province, where three domestic motor groups account for majority share of high-efficiency unit output.
Core Plate Varnishes Market Segmentation
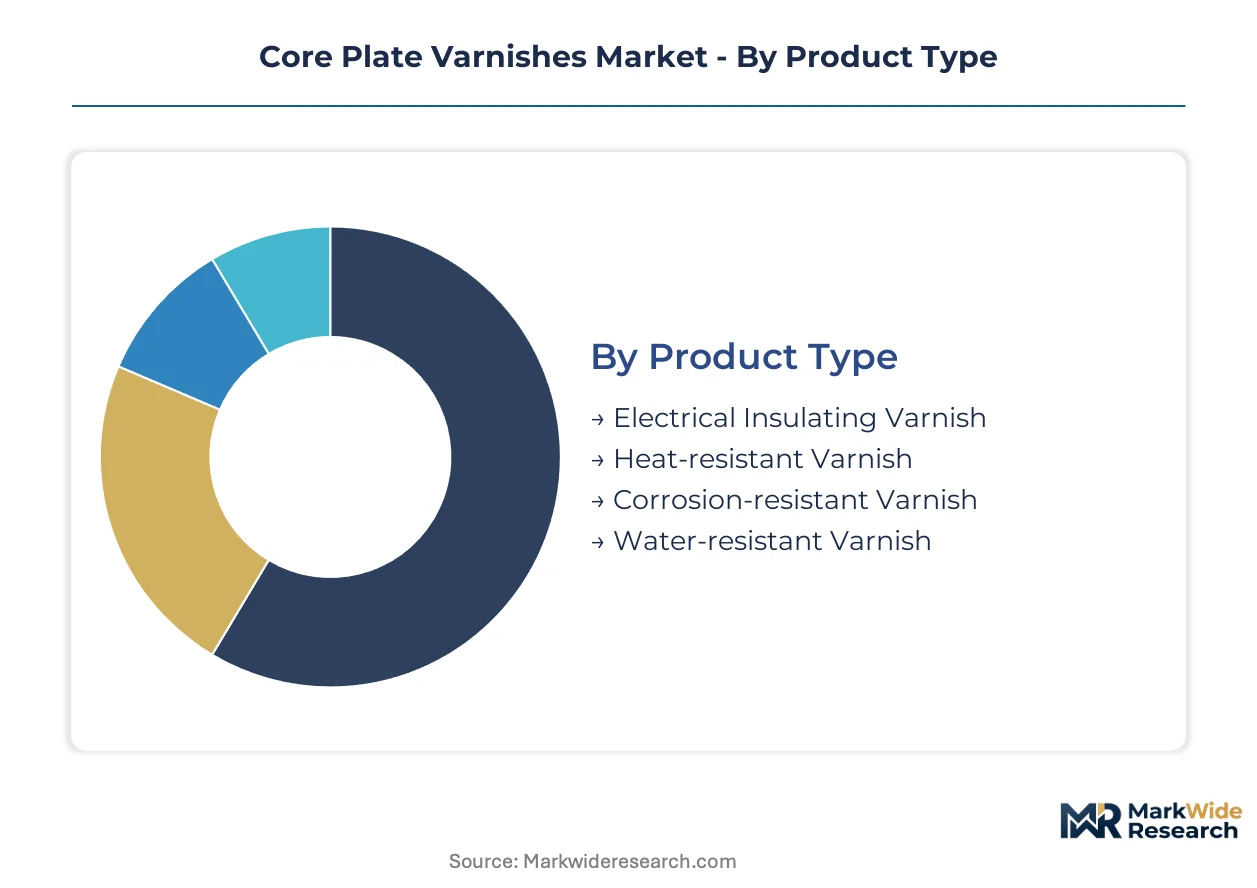
Segmentation in core plate varnishes reveals how reformulation investments and curing technology choices divide procurement budgets across transformer OEMs, motor manufacturers, and aftermarket service networks. Upgrade cycles for medium-voltage equipment and solvent-free system transitions create divergent demand profiles by product chemistry and physical form.
Product Type:
Replacement timelines for laminated core stacks drive specification divergence, with refurbishment cycles favoring proven chemistries while new equipment procurement opens doors for emerging formulations.
- Electrical Insulating Varnish:Alkyd-epoxy hybrid systems dominate medium-voltage transformer manufacturing, delivering dielectric strength above 20 kV/mm for interlaminar insulation. Demand concentrates with German and Japanese transformer OEMs qualifying these systems for 400 kV grid infrastructure, though REACH VOC thresholds are forcing accelerated waterborne development programs.
- Heat-resistant Varnish:Silicone-modified polyester formulations withstand continuous operating temperatures above 180°C in traction motor applications. Chinese high-efficiency motor clusters in Jiangsu province specify these grades for IE4 and IE5 laminated rotor cores, where thermal cycling resistance determines warranty terms.
- Corrosion-resistant Varnish:Epoxy-phenolic systems protect electrical steel in coastal transformer installations and humid environments.
- Water-resistant Varnish:Polyurethane-modified alkyds serve submersible pump motors and marine generator applications with intermittent immersion exposure.
Volume placements concentrate in Electrical Insulating Varnish; the faster expansion belongs to Heat-resistant Varnish.
Application:
End-use equipment specifications determine curing method compatibility and film thickness requirements, with power transmission assets demanding deeper impregnation than rotating machinery.
- Transformers:Distribution and power transformer cores require vacuum pressure impregnation with solvent-borne or emerging powder systems to achieve complete lamination penetration. India's state utilities in Maharashtra and Gujarat commission emergency core stack rebuilds under CEA refurbishment directives, sustaining demand for fast-curing alkyd formulations.
- Electric Motors:Stator and rotor laminations in industrial and appliance motors use dip or spray-applied varnishes with lower viscosity requirements than transformer grades. China's domestic OEMs scale captive consumption for laminated cores as dual carbon goals accelerate IE4 and IE5 production lines.
- Generators:Turbo-generator stator cores in utility-scale power plants specify premium thermal class systems with extended service life guarantees.
- Coils:Wound field coils and armature windings in DC motors and specialty equipment use precision-applied varnishes with controlled penetration depth.
Procurement volume tilts toward Transformers; Electric Motors are climbing the fastest on efficiency regulation tailwinds.
Form:
Physical state selection hinges on capital equipment availability and environmental compliance posture, with powder systems requiring dedicated infrastructure but eliminating solvent recovery costs.
- Liquid:Solvent-borne and waterborne systems retain dominance in repair shop environments and OEM dip-tank operations where existing infrastructure cannot accommodate powder conversion. German and French transformer OEMs pre-qualify waterborne liquid systems for medium-voltage equipment under tightening ECHA thresholds.
- Powder:Thermosetting epoxy powders eliminate VOC emissions and reduce curing energy by 30-40% versus solvent systems, but require electrostatic spray booths and convection ovens. US motor manufacturers facing EPA consent decree timelines accelerate powder investments to maintain operating permits.
- Film:Pre-cured adhesive films serve niche applications in automated lamination stacking for high-volume motor production.
- Paste:High-viscosity compounds fill gaps and repair damaged core edges in field service applications.
Liquid formulations still command the largest placement base; powder systems are gaining share fastest on regulatory compliance economics.
End User:
Customer type shapes pricing tolerance and technical service requirements, with emergency refurbishment commanding premiums over scheduled OEM procurement.
- Repair Shops:Independent motor and transformer rebuilders purchase small-batch solvent-borne varnishes with expedited delivery terms. Emergency refurbishment cycles in North America command premium pricing and technical support intensity that sustains specialized compounders like JOHN C. DOLPH COMPANY.
- Manufacturers:Captive production facilities for electrical steel laminators consume bulk volumes with annual framework agreements replacing spot purchasing. Buyer consolidation among Chinese motor OEMs concentrates procurement authority with engineering teams specifying systems directly.
- Service Providers:Utility maintenance contractors and industrial service companies stock multiple varnish grades for diverse equipment portfolios.
- OEMs:Original equipment manufacturers for transformers, motors, and generators integrate varnish selection into product design and warranty engineering.
Manufacturers represent the largest volume placement segment; repair shops deliver the steepest expansion trajectory on aging installed base refurbishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German and Japanese chemical clusters while consumption gravitates toward transformer refurbishment sites in India and high-efficiency motor factories in China. This geographic asymmetry shapes trade flows and regional formulation strategies.
United States
Domestic motor manufacturing in Ohio and Texas drives solvent-free varnish adoption under EPA air quality consent decree timelines. IRA manufacturing credits incentivize reshoring of electrical equipment supply chains. Midwest transformer rebuilders retrofit spray infrastructure to maintain operating permits.
Germany
REACH VOC thresholds compel waterborne and powder system pre-qualification among transformer OEMs serving 400 kV grid infrastructure. Bavarian and North Rhine-Westphalian chemical clusters anchor resin synthesis for heat-resistant grades. ECHA substance restrictions accelerate reformulation cycles.
China
Jiangsu and Zhejiang motor manufacturing clusters scale captive varnish consumption for IE4 and IE5 laminated rotor cores under dual carbon goals. GB standards on industrial coatings constrain permissible solvent content. Domestic OEM procurement consolidation concentrates specification authority with engineering teams.
India
CEA refurbishment directives compress transformer replacement timelines across Maharashtra and Gujarat state utilities. Emergency core stack rebuilds sustain demand for fast-curing alkyd formulations. BIS certification requirements extend testing sequences for new chemistries.
Japan
Heat-resistant polyester and epoxy intermediate supply concentrates among domestic chemical suppliers serving METI efficiency standards. Tokyo and Osaka-based transformer OEMs pilot nano-modified epoxy dispersions for high-load density applications. JIS qualification protocols integrate emerging waterborne candidates.
Core Plate Varnishes Market Vendor Landscape
The competitive structure tilts toward integrated resin compounders with certified testing capabilities. Three tiers distinguish the field: global coating specialists with backward integration into resin synthesis, regional specialists serving motor rebuilders with application-specific expertise, and Asian chemical conglomerates leveraging captive raw material positions. Dominant competitive moves include strategic partnerships with transformer OEMs for pre-qualification programs and geographic expansion into Southeast Asian grid buildouts.
Among European integrated specialists, Beckers Group and Rembrandtin Lack GmbH occupy positions emphasizing supply continuity for heat-resistant grades. AXALTA represents the technology leadership archetype in solvent-borne insulating systems. JOHN C. DOLPH COMPANY exemplifies the regional specialist model, anchoring decades of expertise serving North American motor rebuilders with expedited delivery and technical support intensity.
| Leading Market Players |
|---|
| AXALTA |
| SSAB AB |
| Helios Group |
| Mäder |
| Beckers Group |
| Rembrandtin Lack GmbH |
| TOYO INK |
| JOHN C. DOLPH COMPANY |
| ALTANA |
| Others |
Supply Flow & Price Mechanics
Chinese electric motor OEM procurement consolidation concentrates specification authority with engineering teams that negotiate annual framework agreements, anchoring contract-based long-term offtake pricing with volume-scaled discounts for captive varnish consumption.
Pricing Analysis
Margin tightening in solvent-borne heritage tiers reflects REACH VOC threshold compliance costs and reformulation R&D amortization. Three-tier pricing structure across premium certified grades, standard industrial formulations, and economy repair-shop volumes stratifies procurement budgets. Price differentiation centers on UL/VDE certification tier and after-sales technical support intensity. Smaller motor repair shops exhibit highest price sensitivity, while German transformer OEMs serving 400 kV infrastructure prioritize dielectric performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated Chinese motor manufacturers and Indian state utilities, while distributor networks serve fragmented North American repair shops. Raw material supply concentrates in German and Japanese chemical clusters for heat-resistant polyester intermediates, with Chinese domestic suppliers scaling alkyd resin capacity. Specialty epoxy hardeners and silicone modifiers draw from concentrated Japanese and German sources. Single-source vulnerability in heat-resistant grade intermediates elevates procurement risk for non-integrated compounders. Distribution runs through regional chemical distributors with technical service capabilities for formulation guidance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH substance restrictions and ECHA VOC thresholds erect technical barriers that favor established laboratories with certified testing capabilities over undercapitalized entrants.
For Market Incumbents: Lock in transformer OEM pre-qualification partnerships before regulatory sunset clauses force reformulation cycles. Deepen backward integration into resin synthesis to secure supply continuity for heat-resistant grades amid Japanese and German intermediate concentration. Anchor capacity in Texas and Ohio to capture IRA domestic content bonuses for electrical equipment reshoring.
For New Entrants and Emerging Players: Independent motor repair shops in North America represent an underserved buyer archetype with premium pricing tolerance for expedited delivery and application-specific technical support. Southeast Asian grid expansion in Vietnam and Indonesia offers white-space opportunity where established varnish supply chains remain underdeveloped. Enter through direct technical sales teams rather than distributor relationships to demonstrate formulation expertise.
For Investors and Strategic Acquirers: The window for entry favors mid-cap compounders with certified UL/VDE testing capabilities and existing transformer OEM relationships. Long-term viability rests on regulatory compliance moats deepening as REACH substance restrictions proliferate. Monitor ECHA substance restriction list updates and pre-qualification timelines for early signals of competitive displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Beckers Group secures supply continuity for heat-resistant polyester grades amid intermediate concentration. |
| Waterborne System Pre-Qualification | German transformer OEMs pilot emerging formulations under tightening ECHA VOC thresholds for medium-voltage equipment. |
| Southeast Asian Geographic Expansion | First-mover compounders secure offtake agreements with emerging transformer OEMs in Vietnam and Indonesia. |
| Powder Coating Infrastructure Investment | US motor manufacturers facing EPA consent decree timelines retrofit facilities to maintain operating permits. |
| Repair Shop Technical Service Intensity | JOHN C. DOLPH COMPANY sustains decades of expertise serving North American motor rebuilders with expedited delivery. |
Methodological Framework
Multi-period observation of transformer refurbishment cycle compression, REACH reformulation timelines, and motor efficiency regulation adoption anchored the trend analysis, supplemented by interviews with varnish formulation chemists, transformer OEM procurement directors, motor manufacturing plant engineers, and electrical steel laminator technical sales managers. Secondary validation drew from ECHA substance restriction databases, BIS certification testing protocols, customs trade data for epoxy resin intermediates, and SEC filings from integrated coating specialists. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry, curing technology, and end-user segments.
Input-output matrices mapped resin intermediate supply through formulation compounding to downstream OEM and aftermarket consumption, with segmentation across product type, application equipment, physical form, and end-user archetype. CAGRs derived from regression analysis of historical placement volumes against regulatory milestone timing and infrastructure investment cycles. Forecast inputs incorporated IE4/IE5 motor production scaling under China's dual carbon goals and India's CEA refurbishment directive implementation pace.
Revisions become necessary when REACH substance restrictions accelerate beyond modeled timelines or amorphous metal ribbon substitution displaces laminated electrical steel in distribution transformer designs faster than anticipated. Practitioners should monitor ECHA restriction list consultations and transformer OEM pilot program outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Middle-East Paints and Coatings Additives Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Iran Paints and Coatings Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
India Automotive OEM Coatings Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market