
 Global Hexane Market | 2026-2036
Global Hexane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hexane Market Foresight
Multi-source procurement among hexane buyers is pivoting toward long-term offtake agreements with integrated refiners. Exxon Mobil Corporation leverages its Gulf Coast cracking complexes to sustain captive n-hexane yields with minimal third-party feedstock exposure. Shell plc anchors European supply through its Pernis refinery solvent trains, while Sinopec dominates domestic distribution across China's eastern provinces.
Hexane denotes a straight-chain alkane hydrocarbon with six carbon atoms, typically refined to purities between 95% and 99% for commercial solvent applications through fractional distillation of naphtha streams. Its primary industrial purpose centers on lipid extraction from oilseeds and as a non-polar reaction medium in polymerization processes. Industrial Grade hexane occupies the largest volume share due to bulk consumption in edible oil mills across Asia, whereas Pharmaceutical Grade commands premium pricing supported by stringent residual solvent limits under ICH Q3C guidelines. Oil Extraction applications lead absolute demand, though Cleaning Agent formulations for electronics manufacturing represent a faster-growing niche with tighter purity thresholds.
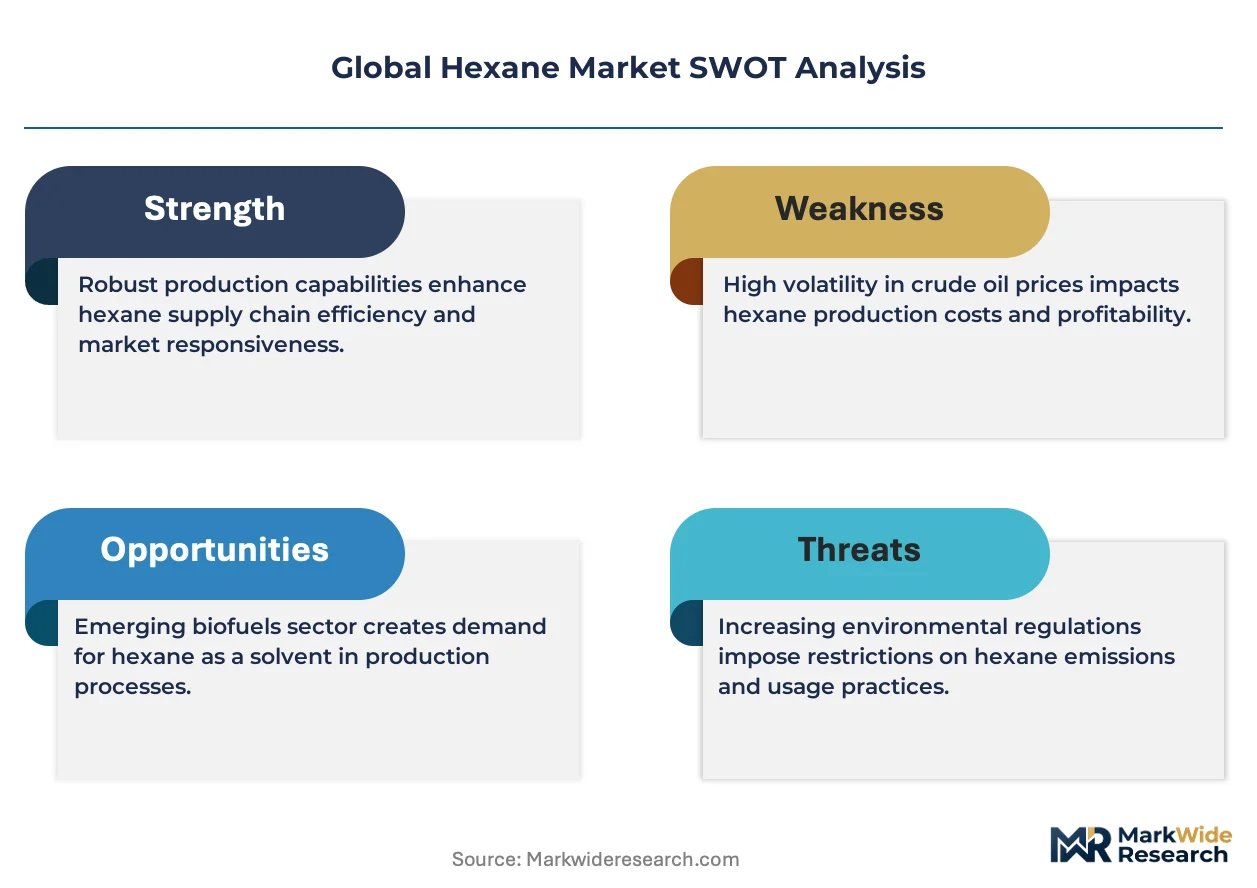
EPA hazardous air pollutant standards under NESHAP and REACH Annex XVII restrictions on n-hexane workplace exposure are forcing reformulation investments and vapor recovery upgrades across production facilities. China's MEE enforces GB standards on volatile organic compound emissions from solvent operations, tightening market access for non-compliant imports. Stakeholders must monitor regulatory divergence between emission-control jurisdictions and process-safety regimes to anticipate cost pass-through structures and relocation of refining capacity.
Market Dynamics
Integrated refining-solvent operations in East Asian petrochemical clusters are compressing feedstock costs and forcing standalone hexane producers into defensive consolidation or long-term offtake dependency.
Growth Catalysts
- REACH Annex XVII workplace exposure limits:Tighter n-hexane handling protocols across European extraction facilities are accelerating vapor recovery system upgrades and creating captive demand for higher-purity solvent grades.
- Edible oil processing expansion:Capacity additions at soybean and palm oil refineries in India and China are pulling additional hexane volumes into solvent extraction circuits.
- Supercritical CO2 hybrid systems:Food-grade processors are blending conventional hexane extraction with carbon dioxide technology to meet residual solvent thresholds under ICH Q3C guidelines.
Market Restraints
- Naphtha feedstock volatility:Crude oil price swings directly transmit to hexane production economics, squeezing margin stability for non-integrated producers lacking captive cracking capacity.
- Substitution by isopropanol and ethanol:Electronics cleaning applications are migrating toward alcohol-based solvents to satisfy EPA NESHAP hazardous air pollutant restrictions.
- Supply concentration around Shanghai and Ulsan:Overreliance on Korean and Chinese integrated refiners exposes buyers to regional logistics disruptions and concentrated pricing power.
Strategic Opportunities
- Pharmaceutical-grade certification:Residual solvent compliance under ICH Q3C is opening premium pricing tiers for producers capable of sub-ppm impurity control.
- GB standards alignment for VOC emissions:China's MEE enforcement creates first-mover advantage for foreign suppliers with pre-certified low-emission solvent formulations.
- Electronics manufacturing clusters:Semiconductor fabrication facilities in Taiwan and South Korea are expanding ultra-high-purity hexane consumption for wafer cleaning protocols.
Industry Challenges
- Fractional distillation technician shortage:Specialized expertise in naphtha cut optimization is aging out of the workforce faster than training programs replenish talent pipelines.
- Dual REACH-EPA compliance documentation:Exporters face divergent testing protocols for European ECHA registration versus EPA hazardous substance reporting, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hexane Market |
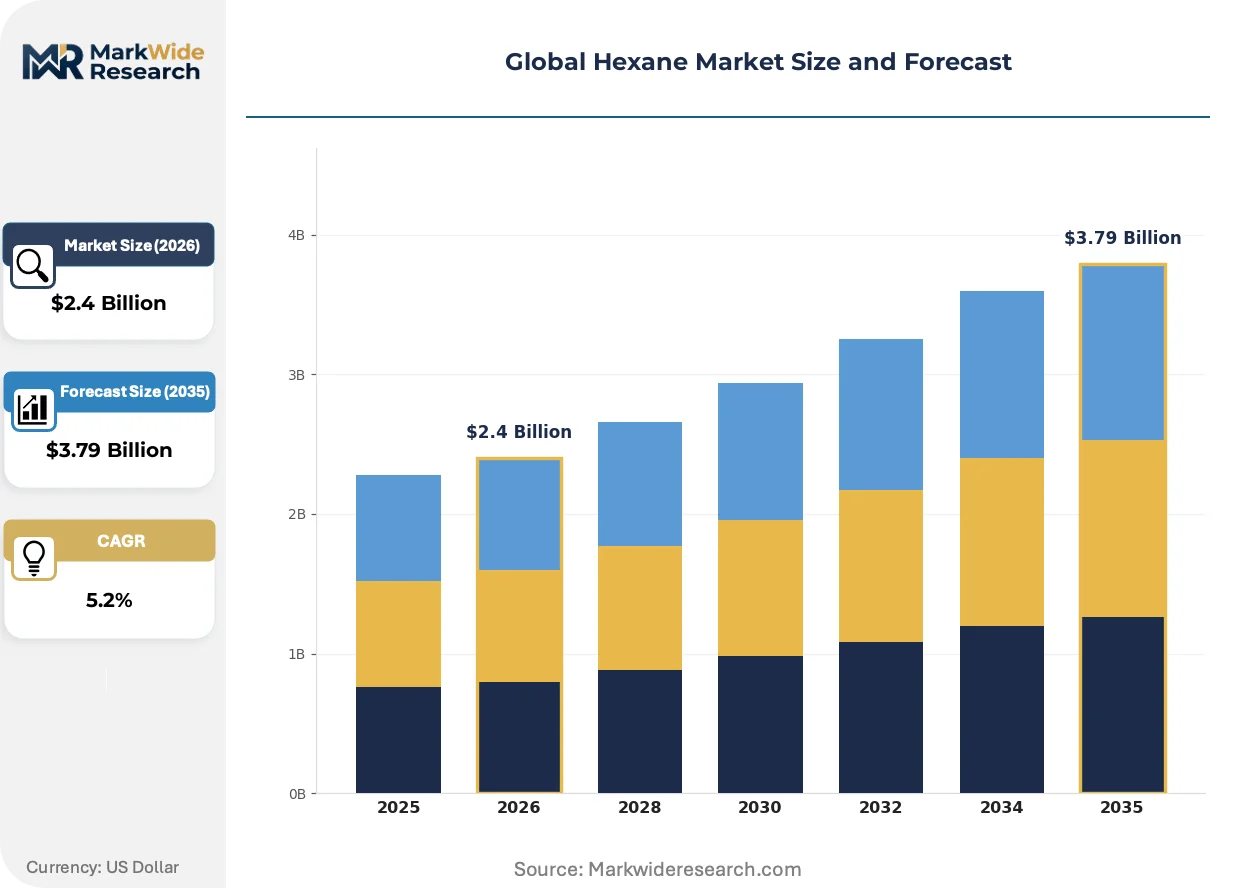
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Technical Grade, Pharmaceutical Grade Application: Oil Extraction, Chemical Solvent, Cleaning Agent, Laboratory Reagent, Adhesive Manufacturing End User Industry: Paints & Coatings, Cosmetics & Personal Care, Agriculture Chemicals, Printing Inks Packaging Type: Drums, Containers, Bulk Tankers, ISO Tanks |
| Companies Covered | Exxon Mobil Corporation, Shell plc, China Petrochemical Corporation (Sinopec), Chevron Phillips Chemical Company, Junyuan Petroleum Group, Bharat Petroleum Corporation Limited, TotalEnergies SE, Phillips 66, Rompetrol Rafinare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hexane Market Shifts & Advancements
Hexane production and application protocols are undergoing systematic revision as regulatory thresholds tighten and end-users demand traceability from refinery to extraction floor.
Molecular sieve adsorption technology is rewriting purity economics for mid-scale refiners. This separation method strips aromatic contaminants below 50 ppm without energy-intensive redistillation. Pharmaceutical and electronics-grade buyers in Japan and Germany are specifying sieve-treated hexane in procurement contracts. The technology is compressing the traditional premium commanded by large integrated producers with advanced solvent trains.
EPA NESHAP residual risk review for the organic chemical manufacturing sector is tightening permissible n-hexane emission limits at production and consumption sites. American solvent extraction facilities face retrofit deadlines for closed-loop vapor recovery systems. Oilseed processors in the US Midwest are accelerating capital deployment to preempt enforcement actions and avoid operational shutdowns.
Long-term offtake contracting is displacing spot market purchasing among large edible oil multinationals. Buyers in India and Brazil are locking in five-year supply agreements with integrated refiners to secure volume certainty against naphtha volatility. This behavior is concentrating procurement relationships and marginalizing traders and smaller distributors who lack backward integration into refining assets.
Global Hexane Market Segmentation
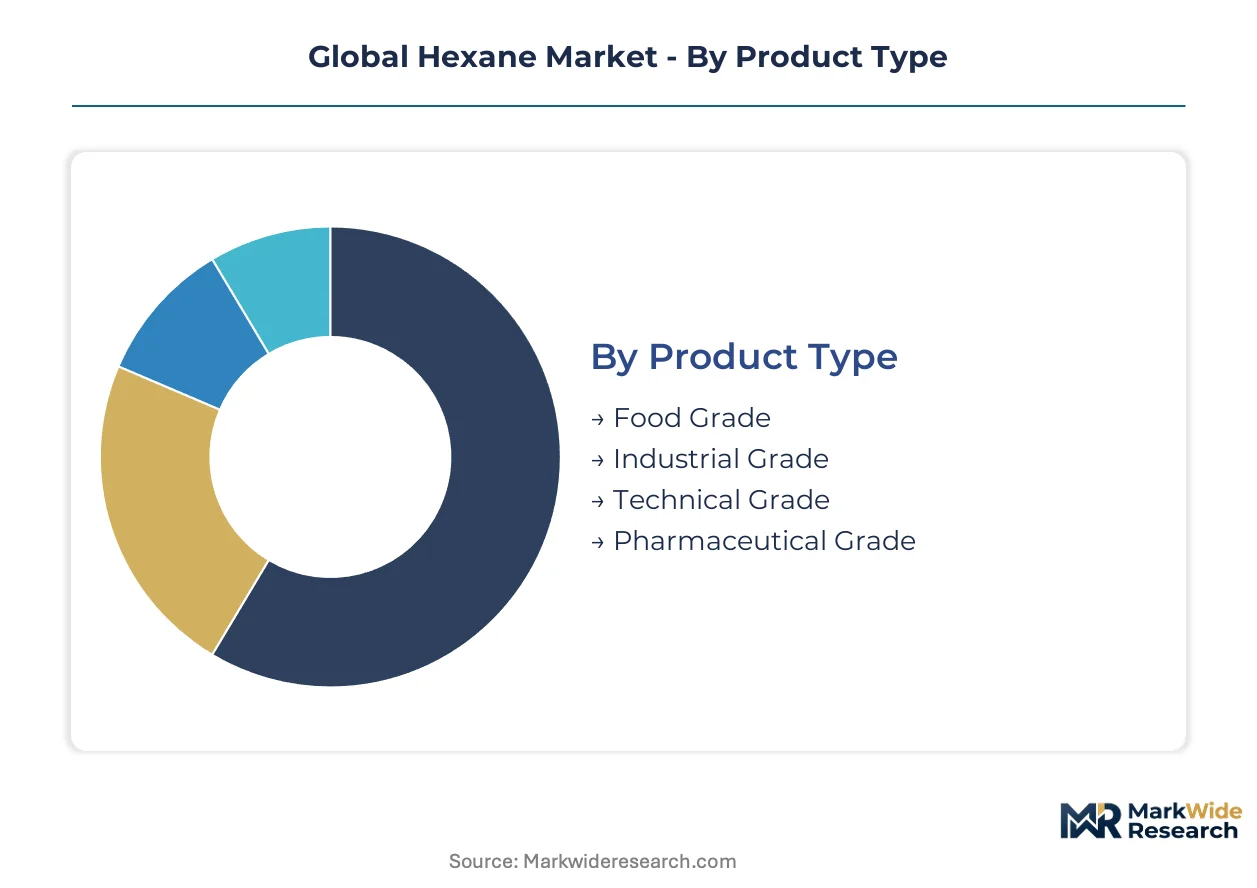
Hexane procurement decisions pivot on purity thresholds, regulatory exposure, and handling economics. Buyers calibrate grade selection against residual solvent limits, extraction efficiency requirements, and vapor recovery compliance costs. Understanding segment boundaries clarifies where margin concentrates and where substitution risks emerge.
Product Type:
Purchasing managers weigh certification costs against end-use liability exposure when selecting hexane grades.
- Industrial Grade:Refined to 95-99% n-hexane purity through fractional distillation of naphtha streams. Edible oil mills across India and China consume this grade in bulk solvent extraction circuits where ICH Q3C residual limits do not apply. Naphtha feedstock volatility directly compresses margins for non-integrated producers supplying this segment.
- Pharmaceutical Grade:Sub-ppm impurity specifications under ICH Q3C guidelines command premium pricing tiers. FDA and EMA inspections of active pharmaceutical ingredient facilities drive demand for certified batches with full chain-of-custody documentation. Molecular sieve adsorption technology is eroding the traditional premium held by large integrated producers.
- Food Grade:Meets FSSAI and FDA direct food contact standards for edible oil processing where minimal residual carryover is tolerated. Processors in Brazil and Argentina specify this grade for export-bound soybean oil.
- Technical Grade:Lower purity specifications serve adhesive formulation and general industrial cleaning where solvent recovery is uneconomical. Price-sensitive buyers in Southeast Asian manufacturing clusters dominate offtake.
Volume sits with Industrial Grade; growth tilts toward Pharmaceutical Grade.
Application:
End-users select solvents based on polarity matching, evaporation rate, and regulatory emission profiles.
- Oil Extraction:Hexane's non-polar characteristics enable efficient lipid recovery from soybeans, rapeseed, and palm kernels. Supercritical CO2 hybrid systems are penetrating food-grade processing to meet tightening residual solvent thresholds.
- Cleaning Agent:Ultra-high-purity specifications serve semiconductor wafer cleaning protocols in Taiwan and South Korean fabrication facilities. EPA NESHAP hazardous air pollutant restrictions are accelerating alcohol substitution in electronics manufacturing.
- Chemical Solvent:Polymerization reaction medium applications in synthetic rubber production favor hexane's narrow boiling range and low reactivity.
- Laboratory Reagent:Chromatography and analytical chemistry applications require certified batch consistency and low UV absorbance.
- Adhesive Manufacturing:Solvent-based adhesive formulations consume technical grade hexane for viscosity control and open-time management.
Absolute consumption clusters in Oil Extraction; Cleaning Agent applications are climbing the fastest.
End User Industry:
Industry-specific formulation standards and VOC emission regulations reshape solvent selection priorities.
- Agriculture Chemicals:Pesticide formulation and tank-mix applications depend on hexane as a carrier solvent for lipophilic active ingredients. China's MEE GB standards on VOC emissions are forcing reformulation toward lower-emission alternatives.
- Paints & Coatings:Industrial maintenance coatings and wood finishes utilize hexane for fast-drying solvent systems. REACH Annex XVII workplace exposure limits are accelerating waterborne technology substitution across European manufacturing.
- Cosmetics & Personal Care:Fragrance extraction and personal care solvent applications face tightening residual solvent scrutiny under EU Cosmetics Regulation.
- Printing Inks:Gravure and flexographic ink formulations employ hexane for rapid substrate penetration and drying.
Procurement volume concentrates in Agriculture Chemicals; Paints & Coatings faces the steepest substitution pressure.
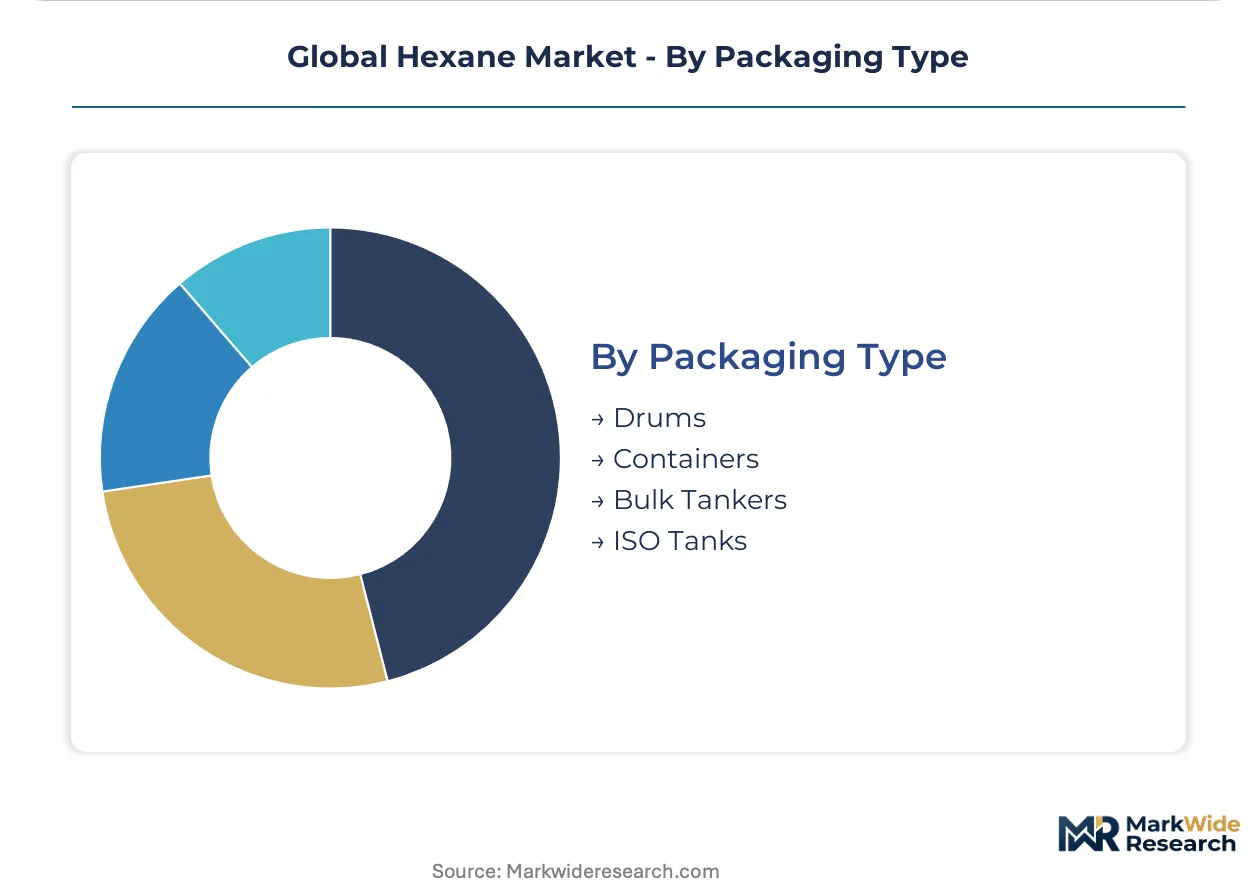
Packaging Type:
Logistics economics and inventory turnover rates determine packaging selection across the supply chain.
- Bulk Tankers:Dedicated rail and road tanker deliveries serve integrated oilseed crushing facilities with continuous solvent extraction operations. Long-term offtake agreements increasingly specify dedicated fleet arrangements.
- ISO Tanks:Intermodal containerization enables cost-efficient international shipment for mid-scale processors lacking direct refinery access. Port congestion at Shanghai and Ulsan creates scheduling volatility.
- Drums:200-liter steel drums serve small-batch chemical synthesis and laboratory applications requiring frequent grade changes.
- Containers:Intermediate bulk containers bridge drum and tanker economics for regional distributors serving fragmented end-user bases.
Shipment value concentrates in Bulk Tankers; ISO Tank utilization is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naphtha cracking complexes along the Gulf Coast anchor United States hexane supply, while East Asian petrochemical corridors concentrate integrated refining-solvent capacity. Demand clusters trace edible oil processing expansion and electronics manufacturing density.
United States
Midwest soybean crushing facilities and Gulf Coast petrochemical corridors drive hexane consumption for oil extraction and polymerization media. EPA NESHAP hazardous air pollutant standards mandate closed-loop vapor recovery retrofits at solvent extraction sites. Houston-area integrated refiners leverage captive naphtha feedstock to stabilize supply for domestic edible oil processors.
China
Vegetable oil refineries in Shandong and Jiangsu provinces pull substantial hexane volumes into solvent extraction circuits. MEE enforcement of GB standards on volatile organic compound emissions tightens market access for non-compliant imports. Shanghai petrochemical clusters host integrated refining-solvent operations achieving feedstock cost advantages over standalone producers.
India
Soybean and palm oil processing capacity additions in Gujarat and Maharashtra strengthen hexane offtake from domestic refiners. FSSAI regulations on residual solvent limits in edible oils push processors toward certified food-grade hexane specifications. Reliance Industries and Indian Oil Corporation anchor supply through western corridor refining complexes.
Germany
Pharmaceutical and specialty chemical manufacturers in North Rhine-Westphalia and Bavaria consume high-purity hexane for active pharmaceutical ingredient synthesis. REACH Annex XVII workplace exposure limits accelerate vapor recovery investments across extraction facilities. BASF and Evonik anchor demand through Ludwigshafen and Marl chemical parks.
South Korea
Semiconductor fabrication facilities in Gyeonggi Province and Ulsan petrochemical complexes drive ultra-high-purity hexane consumption for wafer cleaning protocols. MFDS pharmaceutical manufacturing standards align with ICH Q3C residual solvent guidelines for imported solvents. Ulsan refining-solvent integration compresses logistics costs for electronics-grade supply.
Global Hexane Market Competitive Landscape
Long-term offtake contracting dominates the current landscape as edible oil multinationals lock in supply certainty against naphtha volatility. The vendor base compresses around three structural tiers: integrated petrochemical majors with captive cracking capacity, regional refiners dependent on merchant naphtha, and specialty distributors serving fragmented end-users. Strategic archetypes include backward-integrated supply anchors, purity-certified specialists, and logistics-optimized traders. Competitive moves center on refinery-solvent train integration and five-year supply agreement proliferation.
Among Gulf Coast-anchored petrochemical majors, Exxon Mobil Corporation exemplifies the integrated supply archetype through captive naphtha cracking. Shell plc occupies a parallel position in European solvent markets via Rotterdam-area refining infrastructure. China Petrochemical Corporation represents the state-integrated model dominating domestic distribution across eastern provinces. These three anchors illustrate how feedstock control, geographic clustering, and regulatory compliance capabilities stratify competitive position.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Shell plc |
| China Petrochemical Corporation (Sinopec) |
| Chevron Phillips Chemical Company |
| Junyuan Petroleum Group |
| Bharat Petroleum Corporation Limited |
| TotalEnergies SE |
| Phillips 66 |
| Rompetrol Rafinare |
| Others |
Supply & Pricing Matrix
Naphtha price indices on the Singapore and Rotterdam exchanges cascade through hexane supply chains into three distinct pricing tiers: pharmaceutical-grade certification commands premium spreads, industrial-grade tracks feedstock volatility, and technical-grade absorbs margin compression from substitution pressures.
Pricing Analysis
Certification-bundled versus unbundled service contracts differentiate hexane procurement economics. Three-tier pricing structure across pharmaceutical, industrial, and technical grades separates buyers by residual solvent liability exposure. Price differentiation hinges on ICH Q3C compliance documentation and captive refinery access. Cost compression in industrial-grade hexane is intensifying because naphtha volatility transmits directly to non-integrated producers. Small-batch laboratory buyers exhibit highest price sensitivity; semiconductor fabs show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Korean and Chinese integrated refiners dominating ultra-high-purity electronics-grade supply. Geographic concentration centers on the Ulsan petrochemical corridor, Shanghai refining clusters, and Gulf Coast cracking complexes. Feedstock dependencies draw from naphtha streams, natural gas liquids, and refinery off-gas cuts. Tariff exposure on solvent imports into India and Brazil threatens margin structures for merchant traders. Distribution runs through dedicated bulk tanker fleets under long-term offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hexane supply consolidation is accelerating as naphtha volatility and regulatory compliance costs force standalone producers toward acquisition or offtake dependency.
For Market Incumbents: Deepen backward integration into naphtha cracking capacity at Gulf Coast and East Asian hubs to neutralize feedstock exposure. Expand pharmaceutical-grade certification infrastructure to capture ICH Q3C premium tiers before molecular sieve technology erodes large-producer advantages. Shell plc and Sinopec already anchor this positioning.
For New Entrants and Emerging Players: Direct-to-processor digital procurement platforms offer white-space entry around mid-scale edible oil mills in Brazil and Southeast Asia. Target food-grade hexane segments where FSSAI and FDA certification barriers remain surmountable. Lead with ISO tank logistics optimization against congested Shanghai and Ulsan port schedules.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional refiners with solvent train assets in India and Eastern Europe facing naphtha margin squeeze. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than scale alone. Watch EPA NESHAP enforcement timelines as inflection signal for US Midwest retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | Captive feedstock supply at Exxon Mobil's Baytown complex eliminates third-party price exposure. |
| Pharmaceutical-Grade Certification Investment | ICH Q3C compliance opens premium pricing tiers for active pharmaceutical ingredient solvent supply. |
| Long-Term Offtake Agreement Proliferation | Five-year supply locks between Indian oilseed processors and domestic refiners displace spot market liquidity. |
| Vapor Recovery System Retrofit | Closed-loop installation at EPA NESHAP-regulated Midwest extraction facilities preempts enforcement shutdowns. |
| Molecular Sieve Adsorption Deployment | Mid-scale refiners in Japan and Germany strip aromatics below 50 ppm without energy-intensive redistillation. |
Research Methodology
Trade databases, refinery capacity registries, and customs export records formed the secondary backbone for volume calibration. Primary interviews with solvent extraction plant managers, edible oil procurement directors, pharmaceutical regulatory affairs leads, and petrochemical distribution channel partners validated grade-level demand segmentation. Bottom-up triangulation against top-down naphtha consumption models anchored supply-side estimates.
Historical trendline analysis of naphtha-to-hexane yield ratios and refinery operating rate correlations informed the projection framework. Segmentation dimensions spanned purity grade tier, end-use application, packaging format, and regional production hub clustering. CAGRs were derived from elasticity-adjusted consumption models incorporating edible oil processing capacity expansion and electronics manufacturing density indices.
Inputs from ECHA registration filings and EPA compliance disclosure databases were available through the study window; gaps in real-time refinery operating rate data introduce uncertainty bands around short-term supply estimates. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution technology penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Chloroacetophenone Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market