
 Hydrofluoroether Market | 2026-2036
Hydrofluoroether Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrofluoroether Market Outlook
Specialty chemical distribution through regional technical-service networks is reconfiguring how hydrofluoroether formulations reach end users. 3M leverages its fluorochemical R&D infrastructure to sustain formulation leadership in high-purity electronics grades. Daikin Industries anchors fluoropolymer-derived supply chains across Asian manufacturing corridors. Solvay differentiates through vertical integration into fluorinated feedstock production, controlling cost positions at multiple specification tiers.
Hydrofluoroethers are fluorinated organic compounds characterized by ether linkages between perfluorinated alkyl groups and hydrogen-bearing alkyl groups, typically exhibiting boiling points between 50°C and 100°C and near-zero ozone-depletion potential. These properties position them as precision cleaning solvents and heat-transfer fluids in electronics fabrication where residue-free evaporation and material compatibility are critical. The product-type dimension shows HFE-143 and HFE-245 occupying mature volume positions in industrial cleaning, while HFE-134 leads specification growth for semiconductor wafer processing. Application-level analysis reveals electronics as the dominant margin pool, with aerospace representing a faster-growing but smaller segment driven by avionics cleaning protocols.
The EPA SNAP program and EU F-Gas Regulation constrain higher-GWP alternatives, directly expanding addressable demand for hydrofluoroethers in regulated jurisdictions. China's MEE enforces national fluorinated-gas emission standards that tighten manufacturing-process requirements and favor lower-GWP solvent adoption. Stakeholders must monitor evolving national inventory thresholds and snap-down schedules to align product-registration timelines with regional compliance deadlines.
Market Dynamics
Semiconductor fabrication expansion in Taiwan and South Korea is pulling hydrofluoroether procurement into long-term supply contracts with purity specifications that exceed historical industrial cleaning standards.
Growth Catalysts
- EPA SNAP phaseout schedules:The United States program accelerates solvent replacement timelines for electronics manufacturers seeking lower-GWP alternatives for precision cleaning operations.
- Wafer processing intensity:Advanced node production below 7nm requires multiple cleaning cycles per wafer, multiplying solvent consumption per unit of chip output.
- East Asian cluster concentration:Fabrication facilities in Hsinchu and Pyeongtaek concentrate demand pull for high-purity HFE-134 formulations.
Market Restraints
- Fluorinated feedstock concentration:Precursor chemical production concentrates in Chinese and Japanese chemical corridors, exposing formulations to input cost volatility.
- EU F-Gas quota mechanics:The regulation's phase-down schedule creates supply uncertainty for higher-GWP intermediates still used in some HFE synthesis routes.
- Aqueous cleaning substitution:Water-based megasonic systems displace solvent cleaning in less demanding wafer preparation steps.
Strategic Opportunities
- Avionics maintenance protocols:Aerospace OEMs in France and Germany are specifying HFE solvents for sensitive electronic component cleaning where residue tolerance approaches zero.
- India's semiconductor subsidy schemes:The PLI scheme and designated fabrication zones in Gujarat create virgin demand territories without incumbent supplier relationships.
- Heat-transfer fluid diversification:Immersion cooling for data centers converges with existing HFE thermal properties, opening adjacent volume pools beyond cleaning applications.
Industry Challenges
- Ultra-high-purity certification timelines:Semiconductor fabs require 12-18 month qualification cycles for new solvent sources, freezing supplier switches.
- Fluorochemical engineering talent scarcity:Formulation chemists with perfluorinated compound expertise concentrate at established producers, constraining new entrant R&D capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrofluoroether Market |
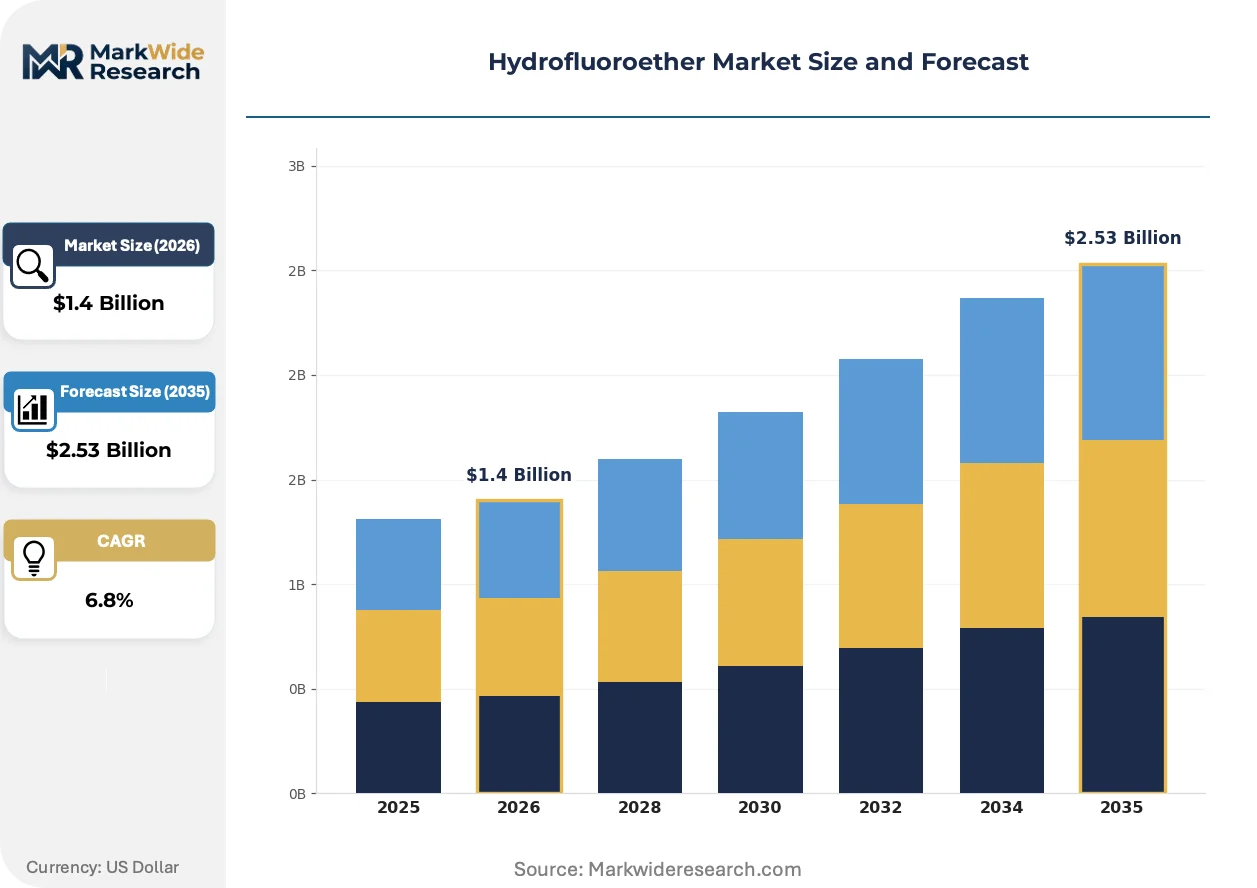
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HFE-134, HFE-125, HFE-143, HFE-245 Application: Aerospace, Electronics, HVAC, Industrial Cleaning Delivery Mode: Bulk Supply, Canisters, Aerosol Packs, Custom Solutions End User: Manufacturing, Automotive, Pharmaceuticals, Research Laboratories |
| Companies Covered | Sicong Chemical, Huaxia Shenzhou New Material, 3M, Daikin Industries, Solvay, AGC, Juhua Group, Hexafluo, Tianhe Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrofluoroether Market Strategic Shifts
Process virtualization and regulatory compression are restructuring how hydrofluoroether formulations reach specification-sensitive end users. Three developments dominate the transformation trajectory.
Closed-loop solvent recovery systems are virtualizing traditional single-use consumption models in Taiwanese and South Korean fabs. Samsung and TSMC supplier networks now mandate on-site reclamation infrastructure for volume contracts. This technology compression is reducing net solvent demand per wafer processed while raising purity requirements for make-up volumes.
The EU F-Gas Regulation's 2024-2030 phase-down trajectory is forcing reformulation investments across fluorinated solvent portfolios. Industrial consequence includes accelerated R&D timelines for lower-GWP HFE variants with identical evaporation profiles. Semiconductor cleaning applications in Germany and the Netherlands face the tightest substitution deadlines, driving early adoption of next-generation ether structures.
Direct technical service relationships are displacing traditional distribution intermediaries in precision cleaning procurement. Formulators now embed field engineers at major fabs in Japan and the United States to co-develop application-specific blends. This channel restructuring concentrates margin capture with producers capable of supporting on-site formulation tuning.
Hydrofluoroether Market Segmentation
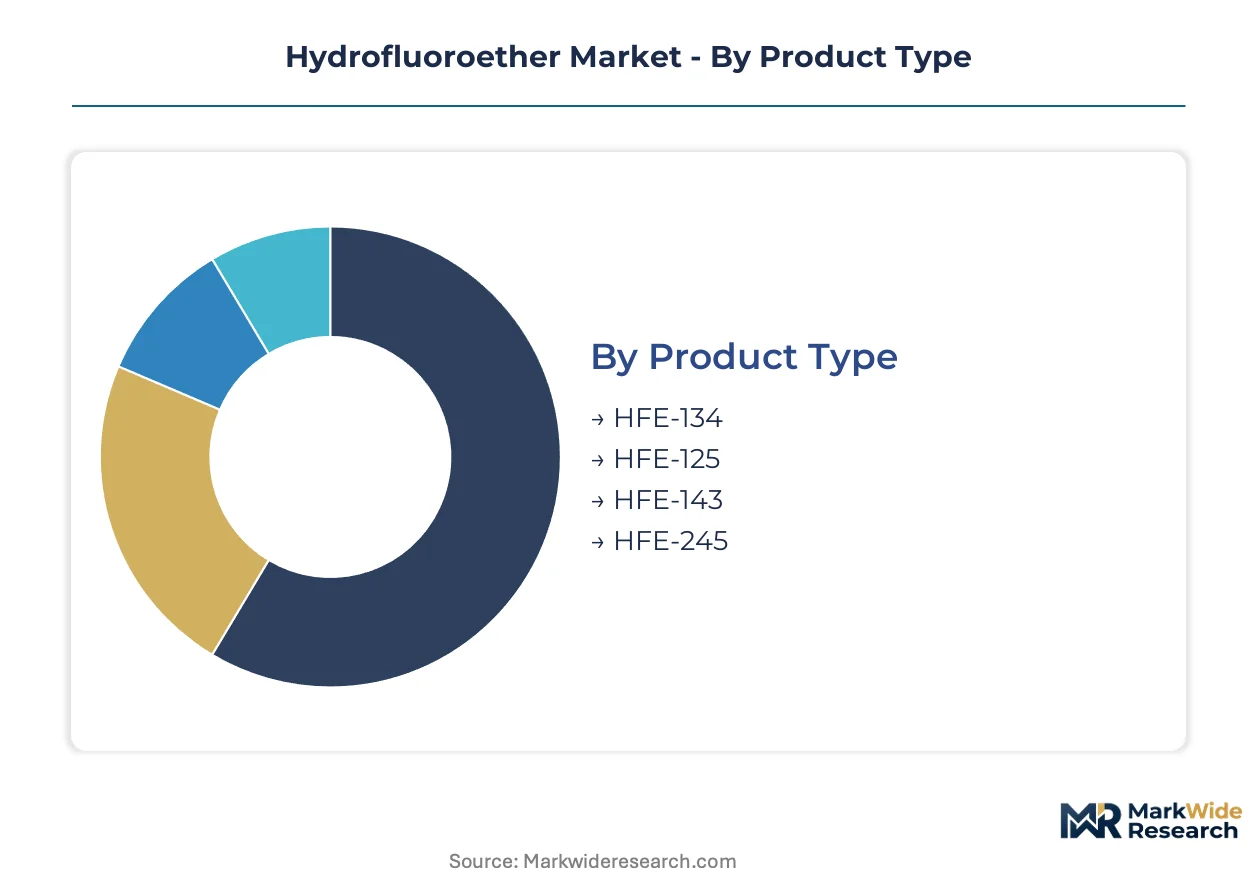
Segmentation in hydrofluoroethers reflects divergent purity specifications and service intensity requirements across electronics fabrication, aerospace maintenance, and industrial cleaning protocols. Each dimension shapes procurement patterns, formulation customization, and supplier relationship structures differently.
Product Type:
After-sales-service intensity varies sharply across ether variants, with semiconductor-grade formulations demanding on-site technical support and reclamation infrastructure that commodity industrial grades do not require.
- HFE-134:This fluorinated ether carries a trifluoromethyl group with a hydrogen terminus, delivering the residue-free evaporation profile that TSMC and Samsung wafer fabs specify for sub-7nm node cleaning. Procurement concentrates in Hsinchu and Pyeongtaek manufacturing corridors where purity certification cycles exceed twelve months.
- HFE-245:The pentafluoroethyl structure provides intermediate boiling points suited to multi-step cleaning sequences in German and Dutch semiconductor facilities facing EU F-Gas phase-down deadlines. Demand pulls toward lower-GWP reformulations with identical evaporation characteristics.
- HFE-125:This shorter-chain variant serves precision electronics cleaning where faster drying times outweigh absolute purity requirements.
- HFE-143:Mature industrial cleaning applications in Japanese automotive component manufacturing favor this cost-optimized ether for degreasing operations.
By volume, HFE-245 leads established industrial applications. By growth pace, HFE-134 is climbing the fastest on semiconductor fabrication expansion.
Application:
Margin structures diverge according to residue tolerance thresholds and regulatory substitution pressure, with aerospace and electronics commanding premium pricing over commodity industrial uses.
- Electronics:Wafer cleaning, photoresist stripping, and post-etch residue removal in Taiwanese and South Korean fabs define the highest-purity specification tier. Multiple cleaning cycles per advanced-node wafer multiply consumption intensity per chip output.
- Aerospace:Avionics maintenance protocols in France and Germany specify near-zero residue tolerance for sensitive electronic component cleaning. OEM qualification processes mirror semiconductor timelines, freezing supplier relationships for extended periods.
- Industrial Cleaning:Metal degreasing and precision parts washing in automotive supply chains represent the volume base with lower service intensity requirements.
- HVAC:Heat-transfer fluid applications in data center immersion cooling converge with existing HFE thermal properties, opening adjacent demand pools beyond cleaning.
Electronics captures the dominant revenue share. Aerospace generates the steepest expansion trajectory on avionics cleaning protocol upgrades.
Delivery Mode:
Packaging configurations align with consumption scale and contamination risk, from bulk tanker deliveries to fabs through portable canisters for maintenance operations.
- Custom Solutions:On-site blending and reclamation services bundled with technical field support dominate Taiwanese and South Korean semiconductor procurement. Samsung supplier networks mandate closed-loop recovery infrastructure.
- Bulk Supply:Tanker and tote deliveries serve high-volume electronics manufacturers with dedicated storage and handling systems.
- Canisters:Portable containers support aerospace maintenance operations and research laboratory applications requiring flexibility.
- Aerosol Packs:Pressurized dispensers target precision spot-cleaning in electronics repair and pharmaceutical equipment maintenance.
Custom solutions command the highest service premium. Bulk supply moves the greatest physical volume.
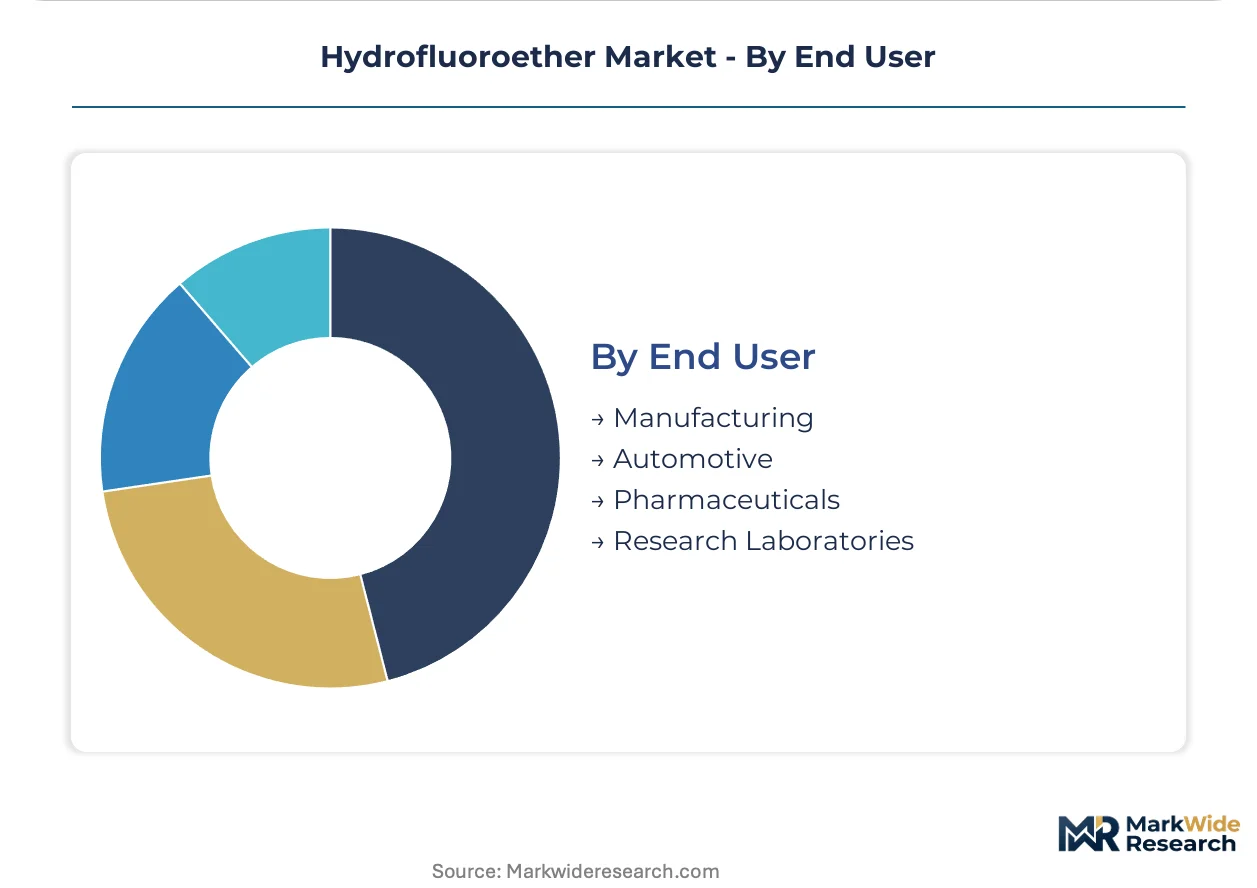
End User:
End-use concentration determines formulation complexity, with semiconductor manufacturing and pharmaceutical processing imposing the strictest purity and documentation requirements.
- Manufacturing:Electronics fabrication facilities in Taiwan, South Korea, and Japan concentrate demand for ultra-high-purity grades with full supply-chain traceability.
- Pharmaceuticals:Sterile equipment cleaning and API synthesis support operations require validated processes with regulatory documentation packages.
- Automotive:Electric vehicle battery component cleaning and fuel system maintenance represent emerging specification territory.
- Research Laboratories:Analytical chemistry and materials science applications demand small-batch flexibility with technical consultation.
Manufacturing absorbs the largest volume share. Pharmaceuticals is gaining share fastest on process validation requirements tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwanese and South Korean procurement corridors, while European buyers absorb compliance-driven premiums under tightening phase-down schedules. The United States anchors North American solvent specification work through federal substitution mandates. Regional divergence reflects varying regulatory compression timelines and semiconductor fabrication intensity.
Taiwan
TSMC's Hsinchu and Tainan facilities drive HFE-134 procurement volumes for sub-7nm wafer cleaning protocols. The EPA SNAP program influences Taiwanese suppliers serving US-bound electronics exports. Kaohsiung industrial zones host reclamation infrastructure mandated by Samsung and TSMC supplier networks.
South Korea
Samsung and SK Hynix fabs in Pyeongtaek and Yongin multiply solvent consumption through advanced-node production cycles. The country's national fluorinated-gas emission standards align with EU F-Gas trajectory, accelerating lower-GWP adoption. Busan-Ulsan chemical corridors concentrate domestic HFE formulation capacity.
United States
Intel's Arizona and Oregon fabrication sites specify high-purity grades for domestic semiconductor manufacturing expansion. The EPA SNAP program's phaseout schedules redirect electronics manufacturers toward hydrofluoroether alternatives. Texas Instruments' Dallas-area operations anchor Southwest demand for precision cleaning solvents.
Germany
Infineon and Bosch semiconductor facilities in Dresden and Reutlingen face EU F-Gas Regulation's tightest substitution deadlines through 2030. The country's national implementation of REACH and F-Gas quotas constrains higher-GWP intermediate availability. Bavarian chemical clusters supply reformulated lower-GWP ether variants to Dutch and French fabs.
China
Domestic semiconductor projects in Shanghai and Beijing pull HFE procurement as import substitution policies advance. The MEE enforces national fluorinated-gas emission standards tightening manufacturing-process requirements. Yangtze River Delta chemical producers expand captive feedstock capacity for HFE synthesis.
Hydrofluoroether Market Competitive Environment
Integrated fluorochemical conglomerates and regional formulation specialists split the market along purity-tier and service-intensity vectors. The structure concentrates margin capture with players controlling perfluorinated feedstock supply and field-engineering deployment. Three archetypes dominate: captive-feedstock producers, precision-formulation specialists, and technical-service integrators. Competitive moves center on backward integration into fluorinated precursors and on-site reclamation infrastructure partnerships.
Among integrated fluorochemical producers, 3M, Daikin Industries, and Solvay occupy positions defined by captive R&D infrastructure and regional technical-service networks. These players exemplify the archetype combining feedstock control with fab-embedded engineering support. Chinese specialists including Sicong Chemical and Huaxia Shenzhou New Material represent regional formulation capacity serving domestic electronics manufacturing expansion. AGC and Juhua Group anchor positions spanning fluoropolymer-derived supply chains and industrial-grade ether production.
| Leading Market Players |
|---|
| Sicong Chemical |
| Huaxia Shenzhou New Material |
| 3M |
| Daikin Industries |
| Solvay |
| AGC |
| Juhua Group |
| Hexafluo |
| Tianhe Chemicals |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese fluorinated feedstock corridors determines both the three-tier pricing spread across semiconductor-grade and industrial formulations and the geographic shape of supplier networks. Tariff exposure between the United States and China compounds input cost volatility, compressing margins for non-integrated formulators while amplifying premium capture for captive-feedstock producers.
Pricing Analysis
Configured-to-order pricing for HFE-134 semiconductor grades commands substantial premiums over standard HFE-245 industrial formulations. Three-tier pricing structure across premium, standard, and economy levels separates fab-qualified ultra-high-purity blends from commodity metal-degreasing ethers. Pricing pressure stems from aqueous megasonic substitution in less demanding wafer steps, eroding mid-tier solvent margins. Electronics manufacturers in Taiwan and South Korea exhibit lowest price sensitivity due to residue tolerance requirements, while automotive component cleaners in Japan absorb highest sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for North American electronics manufacturers. Feedstock production concentrates in Chinese and Japanese chemical corridors, with HFE synthesis capacity clustering in Busan-Ulsan and Yangtze River Delta zones. Raw material dependencies span tetrafluoroethylene precursors, hydrogen fluoride, and specialized catalyst systems. Distribution runs through regional technical-service networks embedding field engineers at major fabs rather than traditional chemical distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. The EU F-Gas Regulation and EPA SNAP program create certification barriers that freeze supplier relationships for 12-18 month qualification cycles.
For Market Incumbents: Entrench position through backward integration into fluorinated precursor production in Chinese and Japanese chemical corridors. Expand captive feedstock capacity to offset tariff exposure and input cost volatility. Deepen fab-embedded technical service teams at TSMC and Samsung supplier networks to raise switching costs for rival formulators.
For New Entrants and Emerging Players: Build out reclamation infrastructure partnerships with India's Gujarat semiconductor zones under PLI scheme subsidies. Target pharmaceutical equipment cleaning as the most penetrable segment, where process validation requirements lag semiconductor timelines. Pursue co-development agreements with domestic chemical producers in Shanghai and Beijing to circumvent incumbent feedstock control.
For Investors and Strategic Acquirers: Regional formulation specialists with existing fab-qualification status and technical-service deployment capability represent the priority acquisition archetype. Long-term viability hinges on exposure to advanced-node semiconductor expansion rather than industrial cleaning commoditization. Watch for EU F-Gas quota mechanics tightening faster than scheduled as the inflection signal for accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Feedstock | Captive precursor supply insulates 3M and Daikin from Chinese tariff exposure. |
| On-Site Reclamation Infrastructure Deployment | Samsung supplier networks now mandate closed-loop recovery systems at Taiwanese fabs. |
| Lower-GWP Reformulation Investment | German and Dutch semiconductor facilities face EU F-Gas substitution deadlines through 2030. |
| Technical Service Team Expansion | Field engineers at TSMC and Intel sites co-develop application-specific HFE blends. |
| India Market Entry Partnership | Gujarat fabrication zones under PLI scheme create virgin demand territories without incumbent relationships. |
Study Parameters
A spread of perspectives from fluorochemical plant managers, semiconductor procurement leads at TSMC and Samsung, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary interview insights combined with secondary validation from customs and trade data, SEC 10-K filings, and ACC industry reports. Bottom-up demand modeling across ether variants triangulated with top-down fluorinated solvent market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions spanned grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from wafer processing intensity trends and regulatory substitution schedules. Industry-specific inputs included advanced-node cleaning cycle multipliers and EU F-Gas phase-down trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed chemical producers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Benzylamine Market
Solvents
Acetone Market
Solvents
Global Bio Solvents Market
Solvents
Ketene Market
Solvents
Green Solvents Market
Solvents
Solvent Green 7 Market
Solvents
2-Phenylethanol Market
Solvents
Global Glycol Market
Solvents
Hydrophobic Solvents Market
Solvents
C2 Chlorinated Solvents Market
Solvents
Saudi Arabia Methanol Market
Solvents
Reactive Diluents Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Xylene Market