
 N-Pentyl Chloride Market | 2026-2036
N-Pentyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
N-Pentyl Chloride Market Analytics
Pharmaceutical-grade specification tiers is redrawing competitive boundaries in the N-Pentyl Chloride landscape. Sigma Aldrich leverages its reagent-grade certification network to sustain premium positioning in analytical laboratories across North America and Europe. BASF SE anchors industrial-grade volume supply through captive chlorination assets at its Ludwigshafen complex. Hangzhou Dayang Chemicals competes on cost-optimized material for agrochemical intermediate buyers in East Asia.
N-Pentyl chloride, also known as 1-chloropentane, is a straight-chain alkyl halide with the molecular formula C5H11Cl and a boiling point of approximately 108 degrees Celsius, manufactured primarily via free-radical chlorination of n-pentane or through hydrohalogenation of pentene precursors. The compound serves as a foundational alkylating agent and solvent intermediate across pharmaceutical synthesis, agrochemical formulation, and specialty polymer production. Reagent-grade product type commands the strongest margin pool due to purity certification requirements for analytical and pharmaceutical applications, while chemical intermediates application leads absolute volume consumption across the solvent and agrochemical channels. Pharmaceutical companies end-user segment shows the fastest structural expansion as contract manufacturers in India and China integrate n-pentyl chloride into antihistamine and sedative synthesis pathways.
REACH registration requirements in Europe, EPA toxic substance control provisions in the United States, and China's MEE hazardous chemical inventory rules collectively elevate compliance costs for non-integrated suppliers seeking cross-border market access. BASF SE and CABB Chemicals navigate this framework through pre-registered substance portfolios and audited supply chain documentation that smaller competitors struggle to replicate. Stakeholders must monitor evolving purity thresholds in pharmaceutical-grade specifications and assess backward integration into n-pentane feedstock as a decisive capability differentiator.
Market Dynamics
Pharmaceutical-grade purity certification is compressing supplier margins while elevating entry barriers, as contract manufacturers in India and Germany now mandate reagent-grade documentation for every batch entering active pharmaceutical ingredient synthesis.
Growth Catalysts
- REACH substance registration:Pre-registered portfolios in Europe accelerate market access for compliant suppliers while excluding smaller competitors lacking ECHA documentation infrastructure.
- Agrochemical intermediate demand:East Asian formulators of herbicide and fungicide precursors consume industrial-grade material at expanding volumes.
- Free-radical chlorination process refinement:Yield improvements in n-pentane feedstock conversion are lowering unit costs for integrated producers.
Market Restraints
- Feedstock volatility:N-pentane pricing fluctuations tied to crude oil movements compress margin predictability for non-integrated chlorination operators.
- Substitution pressure from brominated analogs:1-bromopentane offers superior reactivity in certain alkylation reactions, threatening volume in solvent applications.
- China MEE hazardous chemical inventory:Cross-border shipment documentation requirements create compliance friction for importers lacking domestic legal representation.
Strategic Opportunities
- CDSCO pharmaceutical manufacturing incentives:India's production-linked incentive scheme for drug intermediates attracts contract manufacturing investment requiring certified alkyl halide supply.
- Specialty polymer nucleophilic substitution:Pentyl side-chain incorporation into high-performance thermoplastics represents an emerging specification tier.
- Direct-to-laboratory distribution:E-procurement platforms bypass traditional chemical distributor markups for reagent-grade buyers in analytical segments.
Industry Challenges
- Analytical chemist scarcity:Pharmaceutical manufacturers struggle to staff quality control laboratories capable of validating impurity profiles to pharmacopeial standards.
- Multi-jurisdiction certification timelines:Simultaneous REACH, EPA TSCA, and China MEE registrations extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Pentyl Chloride Market |
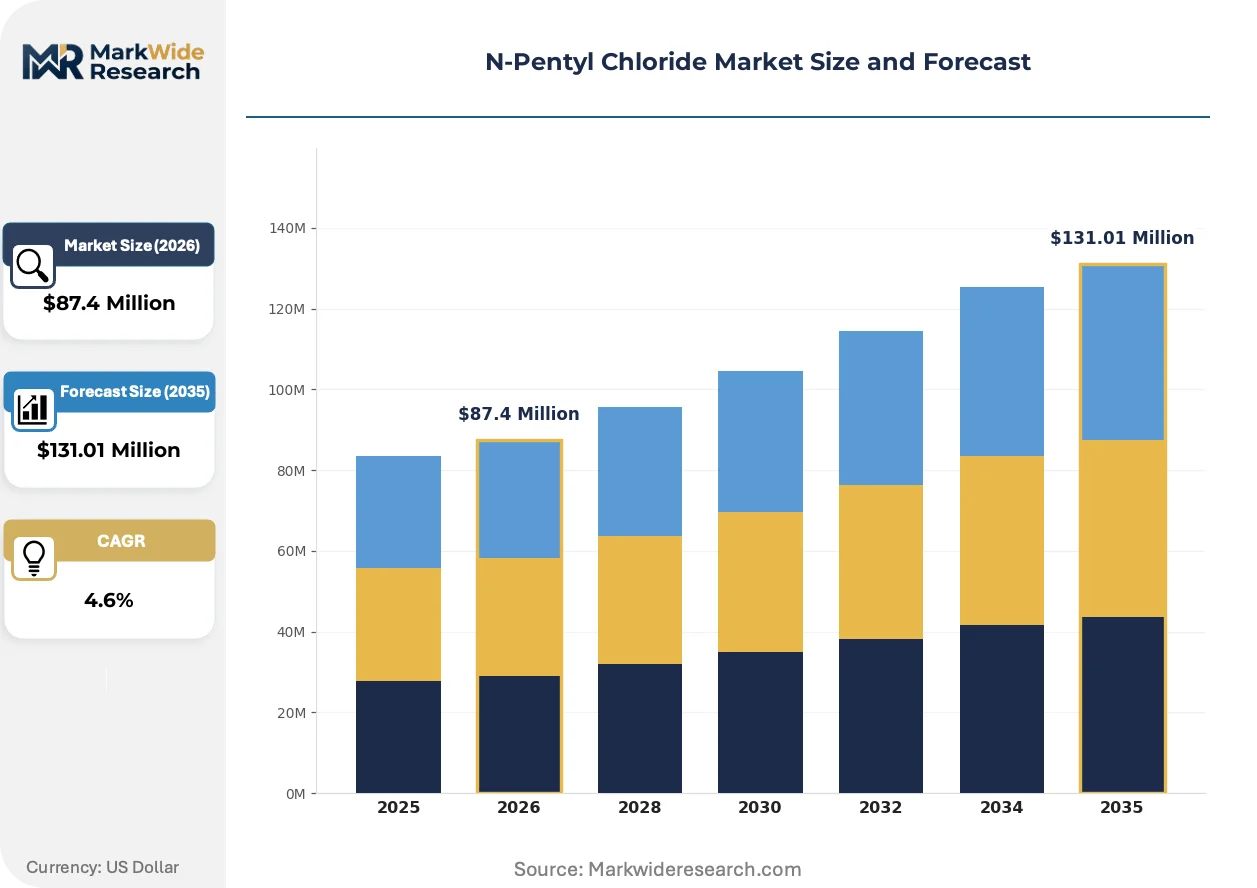
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $131.01 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Pharmaceutical Grade, Others Application: Solvent, Chemical Intermediates, Pharmaceuticals, Agrochemicals End User: Chemicals Industry, Pharmaceutical Companies, Agricultural Sector, Research Labs Packaging Type: Drums, Bottles, Bulk Containers, Other Packaging |
| Companies Covered | Parchem, J & K Scientific, Sigma Aldrich, Hangzhou Dayang Chemicals, Conier Chem & Pharma, Mainchem, CDH Fine Chemicals, BASF SE, CABB Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Pentyl Chloride Market Evolving Landscape
Continuous flow chlorination reactor designs are compressing batch processing economics while regulatory data requirements are forcing documentation infrastructure investments across the supply base.
Membrane-based separation technology for hydrogen chloride recovery is supplanting traditional aqueous scrubbing systems in chlorination facilities. Pharmaceutical contract manufacturers in Germany and Switzerland are specifying this technology in supplier audits. The shift is enabling zero-liquid-discharge compliance while reducing wastewater treatment capital intensity.
REACH authorization list expansion for CMR substances is tightening handling requirements for chlorinated alkyl chain intermediates. Industrial users must now maintain exposure monitoring records and substitution analysis documentation. The specialty chemical segment is responding by segregating pharmaceutical-grade production lines from industrial-grade assets.
Specification-driven supplier consolidation is concentrating procurement decisions among fewer qualified vendors. Large pharmaceutical buyers in India now mandate on-site GMP audits before contract award, displacing spot-market purchasing. This behavioral shift is most pronounced in Gujarat and Maharashtra, where API synthesis clusters have formalized preferred supplier programs.
N-Pentyl Chloride Market Segmentation
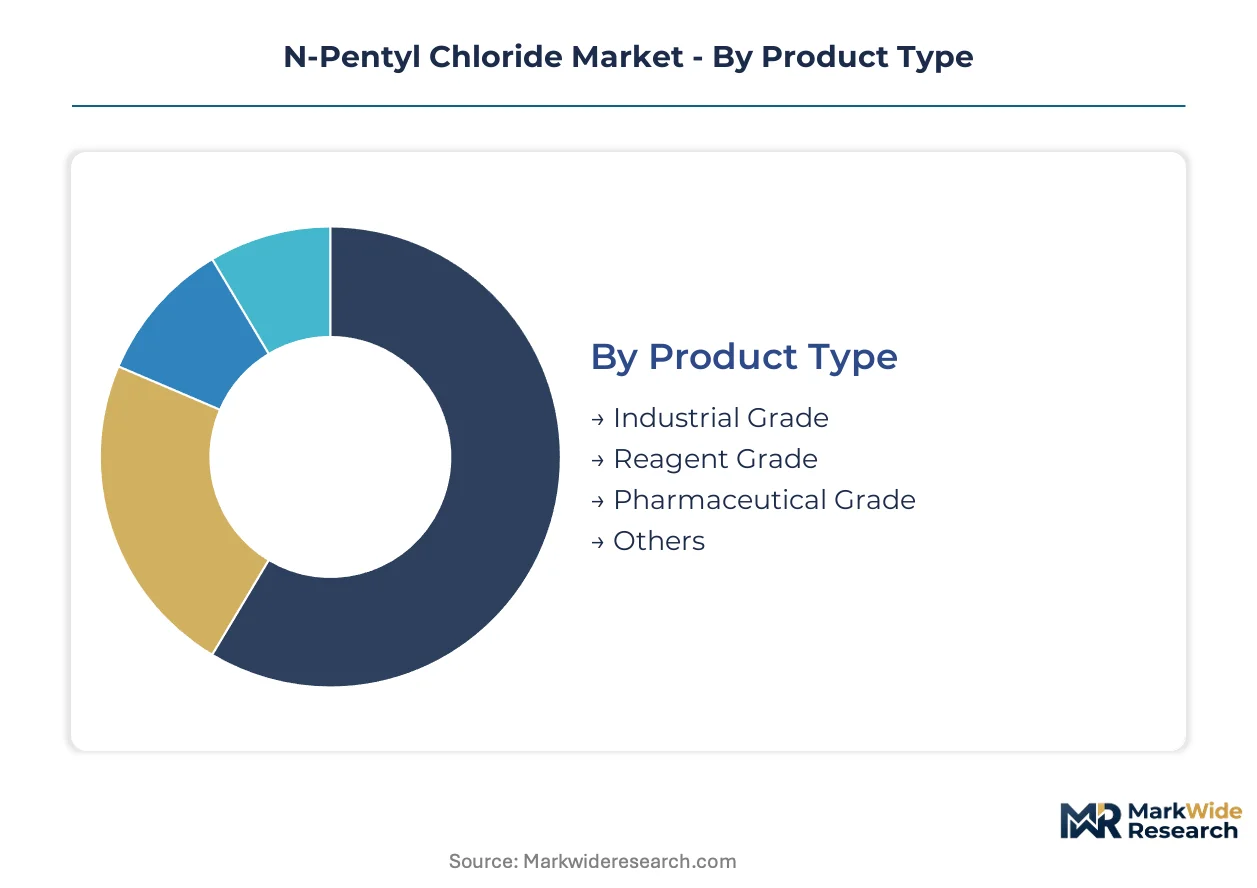
Grade certification tiers and end-use purity requirements fragment the N-Pentyl Chloride landscape into distinct margin pools. Pharmaceutical-grade specifications command premium positioning while industrial-grade volumes anchor baseline profitability.
Product Type:
Reagent-grade material captures the deepest margin pools due to analytical certification overhead, while pharmaceutical-grade purity thresholds are compressing supplier economics through documentation requirements.
- Industrial Grade:Standard chlorination output serves agrochemical intermediate and bulk solvent buyers without purity certification overhead. Demand clusters in Gujarat's specialty chemical corridor and Shanghai's petrochemical zones where formulators prioritize unit cost over trace impurity control.
- Reagent Grade:Sub-0.1% impurity specifications with batch-level analytical documentation support pharmaceutical synthesis and analytical laboratory applications. German and Indian contract manufacturers now mandate this tier for API precursor supply, elevating documentation infrastructure requirements for qualified vendors.
- Pharmaceutical Grade:Pharmacopeial-compliant material with validated impurity profiles and GMP manufacturing records. CDSCO audit requirements in India and EMA standards in Europe restrict qualified supply to pre-registered producers with dedicated production lines.
- Others:Custom-blended specifications for electronics cleaning and specialty polymer nucleophilic substitution applications.
Industrial Grade holds installed capacity. Reagent Grade is rotating up the share rankings.
Application:
Volume concentration favors chemical intermediates, though pharmaceutical synthesis is climbing fastest on purity-premium economics.
- Solvent:Alkylation reactions and extraction processes consume industrial-grade material in agrochemical formulation. Substitution pressure from 1-bromopentane in high-reactivity applications constrains expansion in specialty solvent channels.
- Chemical Intermediates:Largest absolute consumption channel, feeding herbicide precursor synthesis and specialty polymer side-chain incorporation. East Asian formulators in Jiangsu and Zhejiang provinces drive procurement volumes through captive chlorination partnerships.
- Pharmaceuticals:Antihistamine and sedative synthesis pathways in Indian API clusters require reagent-grade certification. Maharashtra and Gujarat contract manufacturers are formalizing preferred supplier programs with on-site GMP audit mandates.
- Agrochemicals:Fungicide and herbicide active ingredient precursors consume industrial-grade volumes through seasonal procurement cycles tied to planting calendars.
Chemical Intermediates holds installed capacity. Pharmaceuticals is climbing the fastest.
End User:
Procurement sophistication varies sharply across buyer categories, with pharmaceutical companies imposing the most stringent qualification protocols.
- Chemicals Industry:Integrated chlor-alkali producers and specialty chemical formulators purchase industrial-grade material for captive intermediate production. Rhine-Ruhr industrial region buyers leverage backward integration into n-pentane feedstock to compress delivered costs.
- Pharmaceutical Companies:Contract manufacturers and API synthesis facilities mandate reagent-grade or pharmaceutical-grade material with complete batch documentation. E-procurement platforms are displacing traditional distributor relationships for qualified laboratory supply.
- Agricultural Sector:Formulators of crop protection chemicals source industrial-grade material through seasonal tender processes with limited specification stringency.
- Research Labs:Analytical laboratories and academic institutions purchase reagent-grade material in small-lot quantities through distributor channels, prioritizing certification reliability over unit cost.
Chemicals Industry holds installed capacity. Pharmaceutical Companies is gaining share fastest.
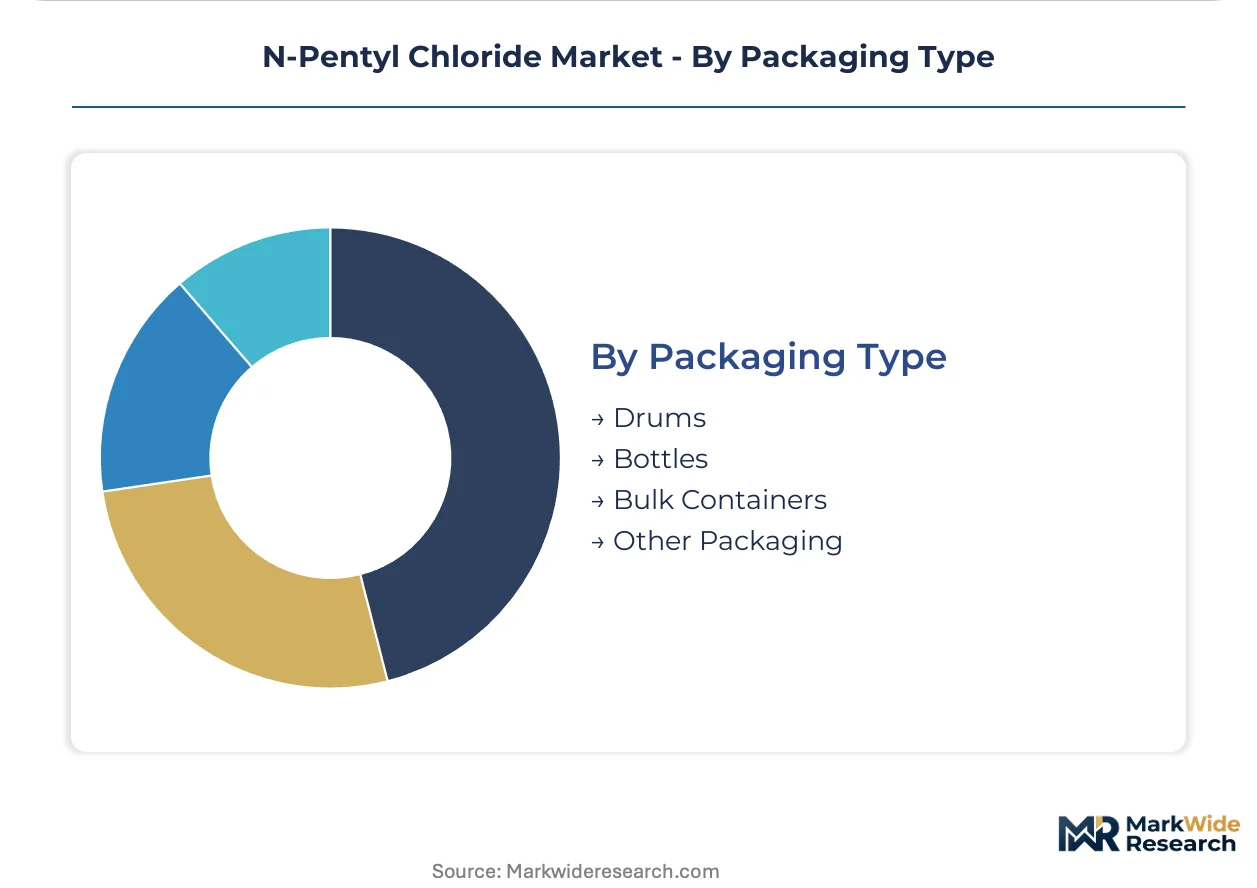
Packaging Type:
Packaging economics align with shipment scale and end-user handling infrastructure, with bulk formats dominating industrial procurement.
- Drums:Standard 200-liter steel drums serve mid-scale chemical intermediate producers and regional formulators requiring manageable batch traceability. Drum reconditioning programs in Germany and India reduce per-shipment packaging costs for repeat buyers.
- Bottles:Amber glass and fluoropolymer bottles protect reagent-grade material from moisture and light degradation for laboratory and pharmaceutical synthesis applications. Sigma Aldrich's direct-to-laboratory distribution network prioritizes this format for North American and European analytical segments.
- Bulk Containers:ISO tank containers and flexitanks support high-volume industrial-grade shipments to integrated agrochemical producers. Zero-liquid-discharge chlorination facilities in Switzerland and Germany specify bulk receipt to minimize handling contamination risk.
- Other Packaging:Custom-sized containers and disposable bag-in-box systems for specialized pharmaceutical manufacturing environments with cleanroom requirements.
Bulk Containers holds installed capacity. Bottles is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward net outflows from integrated chlor-alkali producers in Germany and China, while India and the United States absorb specialty-grade imports for pharmaceutical synthesis clusters.
China
East Asian agrochemical formulators in Jiangsu and Zhejiang provinces drive industrial-grade consumption through captive chlorination partnerships. MEE hazardous chemical inventory rules impose cross-border documentation requirements that favor domestic producers with established legal representation. Shanghai's petrochemical zones concentrate reagent-grade output for export to Indian API manufacturers.
Germany
Rhine-Ruhr industrial region buyers leverage backward integration into n-pentane feedstock to compress delivered costs for chemical intermediate production. REACH substance registration requirements accelerate market access for compliant suppliers while excluding smaller competitors lacking ECHA documentation infrastructure. BASF SE's Ludwigshafen complex anchors European supply through captive chlorination assets.
India
CDSCO pharmaceutical manufacturing incentives attract contract manufacturing investment requiring certified alkyl halide supply in Maharashtra and Gujarat. API synthesis clusters in Ahmedabad and Mumbai have formalized preferred supplier programs with on-site GMP audit mandates. Reagent-grade imports from European producers fill domestic capacity gaps for antihistamine and sedative synthesis pathways.
United States
EPA toxic substance control provisions elevate compliance costs for non-integrated suppliers seeking market access for pharmaceutical-grade material. Gulf Coast petrochemical infrastructure supports industrial-grade production for agrochemical intermediate buyers. Sigma Aldrich's North American distribution network prioritizes direct-to-laboratory channels for analytical segments.
Switzerland
Pharmaceutical contract manufacturers in Basel specify membrane-based hydrogen chloride recovery technology in supplier audits. Zero-liquid-discharge compliance requirements favor bulk container receipts to minimize handling contamination risk. Swissmedic standards restrict qualified supply to pre-registered producers with dedicated pharmaceutical-grade production lines.
N-Pentyl Chloride Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and specialty reagent distributors rather than fragmented commodity producers. The vendor base stratifies across three tiers: multinational chlor-alkali operators with captive feedstock, reagent-grade specialists with certification infrastructure, and regional chemical traders serving industrial-grade spot markets. Dominant competitive moves include backward integration into n-pentane supply and strategic partnerships with pharmaceutical contract manufacturers seeking audit-ready documentation.
Among Germany-based chemical conglomerates, BASF SE and CABB Chemicals occupy positions anchored by pre-registered substance portfolios and audited supply chain documentation. Sigma Aldrich exemplifies the reagent-grade specialist archetype through its certification network for analytical laboratories. Hangzhou Dayang Chemicals represents the cost-optimized regional producer tier serving East Asian agrochemical intermediate buyers.
| Leading Market Players |
|---|
| Parchem |
| J & K Scientific |
| Sigma Aldrich |
| Hangzhou Dayang Chemicals |
| Conier Chem & Pharma |
| Mainchem |
| CDH Fine Chemicals |
| BASF SE |
| CABB Chemicals |
| Others |
Value Network & Pricing Analysis
1-bromopentane substitution pressure in high-reactivity alkylation applications simultaneously redraws supply geography toward bromine-rich production zones and compresses pricing economics for chlorinated alternatives in solvent channels. This substitution dynamic forces n-pentyl chloride suppliers to defend position through certification differentiation rather than commodity cost parity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the analysis window. Three-tier pricing structure across reagent-grade, pharmaceutical-grade, and industrial-grade levels separates Sigma Aldrich's analytical certification premium from BASF SE's volume-driven chemical intermediate supply. Price differentiation rests on REACH documentation completeness and GMP audit readiness rather than unit production cost alone. Cost compression in industrial-grade tiers is intensifying because East Asian agrochemical formulators prioritize feedstock conversion yield over impurity profile precision.
Supply Chain Analysis
Inventory cycles compress to seasonal patterns tied to Northern Hemisphere planting calendars for agrochemical intermediates and quarterly API production schedules for pharmaceutical-grade material. Supply concentrates in Germany, China, and India, with captive chlorination assets at Ludwigshafen and Shanghai petrochemical zones feeding downstream formulators. Raw material dependencies center on n-pentane feedstock from crude oil refining, chlorine from chlor-alkali electrolysis, and hydrogen chloride recovery systems. Single-source vulnerability around REACH-registered European producers threatens supply continuity for Indian API manufacturers lacking qualified domestic alternatives. Distribution runs through ISO tank containers for industrial-grade bulk shipments and direct-to-laboratory channels for reagent-grade bottles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The n-pentyl chloride market sits at a cyclical recovery phase driven by CDSCO production-linked incentive uptake in Indian pharmaceutical manufacturing. Contract manufacturing investment in Maharashtra and Gujarat clusters signals demand inflection for certified alkyl halide supply.
For Market Incumbents: Fortify documentation infrastructure against REACH authorization list expansion for CMR substances. Invest in membrane-based hydrogen chloride recovery technology to meet Swissmedic and EMA supplier audit requirements. Backward integration into n-pentane feedstock compresses delivered cost exposure to crude oil volatility. Defend reagent-grade margin pools by segregating pharmaceutical-grade production lines from industrial-grade assets. For New Entrants and Emerging Players: Direct-to-laboratory e-procurement platform under-service creates entry opportunity where Sigma Aldrich's distributor markups alienate price-sensitive analytical segments. Target research lab buyers in North American academic institutions with amber glass bottle packaging and sub-0.1% impurity certification. White-space concentration sits in specialty polymer nucleophilic substitution applications requiring custom-blended pentyl side-chain specifications. Go-to-market leverage centers on bypassing traditional chemical distributor networks through digital procurement channels. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors pre-registered substance portfolios with audited supply chain documentation. Long-term viability over the mid-decade horizon rests on regulatory compliance infrastructure rather than commodity scale economics. Acquisition target archetype: regional chlor-alkali operators with captive n-pentane supply and incomplete REACH registration portfolios ripe for compliance investment. Signal to watch is CDSCO on-site GMP audit mandate formalization across Gujarat API synthesis clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive n-pentane supply from Ludwigshafen refining complexes insulates BASF SE from feedstock volatility. |
| Green Manufacturing Transition | Membrane-based hydrogen chloride recovery enables zero-liquid-discharge compliance at Swiss chlorination facilities. |
| Long-term Supply Agreement | Preferred supplier programs with Maharashtra contract manufacturers lock in reagent-grade volume commitments. |
| Capacity Expansion | Dedicated pharmaceutical-grade production lines in Ahmedabad address CDSCO audit requirement gaps. |
| Joint Venture | East Asian captive chlorination partnerships in Jiangsu province secure industrial-grade offtake for agrochemical formulators. |
Research Methodology
The analysis maps reagent-grade certification tiers, pharmaceutical-grade purity thresholds, and industrial-grade volume channels, each validated through procurement directors at API synthesis facilities. Primary interviews with plant managers at chlor-alkali complexes, regulatory affairs leads at REACH-registered suppliers, and distribution channel partners in Gujarat specialty chemical corridors combined with secondary validation. Secondary sources include ECHA registration databases, CDSCO manufacturing incentive disclosures, customs trade data for alkyl halide shipments, and SEC filings from integrated chemical conglomerates. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. The analytical framework segments by grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from regression analysis of historical capacity utilization and forward-looking contract manufacturing investment patterns. Industry-specific forecast inputs include seasonal agrochemical procurement cycles and pharmaceutical GMP audit pipeline queues.
Underlying assumptions cover sustained CDSCO incentive uptake, stable crude oil-n-pentane price correlation, and REACH authorization timeline adherence, with deviation risk concentrated in substitution acceleration toward brominated analogs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Wax Dispersion Market
Solvents
Dihydromyrcene Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
Industrial Solvents Market
Solvents
Epoxy Thinner Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
North America Toluene Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Global Solvent Dyes Market
Solvents
Diethanolamine (DEA) Market
Solvents
Benzene Market
Solvents
Glycerol Market
Solvents
Potassium Formate Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Pharmaceutical Solvent Market