
 Organic Solvents Market | 2026-2036
Organic Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Solvents Market Intelligence
The traditional high-volume, low-specification buyer base is collapsing as demand shifts toward specialized pharmaceutical and electronics applications requiring higher purity solvents. BASF SE leverages its extensive product portfolio to serve diverse end-user requirements across multiple grades. Dow Inc. sustains its market position through large-scale production of foundational alcohol and aromatic solvents. Solvay S.A. specializes in high-performance solvents for niche chemical processing and advanced material sectors.
Organic solvents are carbon-based chemical compounds engineered to dissolve, suspend, or extract other materials without chemically reacting with them. Their primary industrial function is to act as a medium for chemical reactions or as a carrier in formulations like paints and inks. Alcohols and aromatics constitute the largest volume segments due to their widespread use in coatings and cleaners. The pharmaceutical grade category, however, is expanding rapidly and commands higher margins due to stringent purity and testing requirements.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) impose strict limits on volatile organic compound (VOC) emissions. In China, the Ministry of Ecology and Environment (MEE) enforces regulations that are pushing manufacturers toward greener, less toxic solvent alternatives. Navigating this complex compliance landscape while managing raw material volatility will determine competitive success for solvent producers and formulators.
Market Dynamics
The central tension in the organic solvents market is the divergence between high-volume, low-margin commodity segments and the expanding, high-specification demands from regulated industries like pharmaceuticals and electronics, driven by global standards from ECHA and the EPA.
Growth Catalysts
- Pharmaceutical Sector Expansion:The growing production of active pharmaceutical ingredients (APIs) and complex drug formulations requires increasing volumes of high-purity solvents, which serve as reaction media and purification agents.
- Industrialization in China:China's continued dominance in manufacturing, particularly in coatings, electronics, and construction, sustains massive baseline demand for foundational solvents like alcohols, ketones, and aromatics.
- Bio-Based Solvent Development:Regulatory frameworks like the EU Green Deal and consumer demand for sustainable products are accelerating research and commercialization of solvents derived from renewable feedstocks like corn and sugarcane.
Market Restraints
- Petrochemical Feedstock Volatility:The price and availability of key raw materials like ethylene, propylene, and benzene are directly tied to volatile crude oil and natural gas markets, creating unpredictable production costs.
- Stringent VOC Regulations:Rules from bodies like the US Environmental Protection Agency (EPA) and China's MEE impose strict limits on volatile organic compound (VOC) emissions, increasing compliance costs and restricting the use of certain solvents.
- Threat from Water-Based Systems:The development of high-performance water-based coatings, inks, and adhesives presents a direct substitution threat, eroding market share for organic solvents in major applications.
Strategic Opportunities
- Battery Electrolyte Formulations:The rapid expansion of the electric vehicle industry creates a significant opportunity for high-purity solvents used in the formulation of lithium-ion battery electrolytes, a high-value, specialized application.
- Solvent Recovery and Recycling:Establishing closed-loop recycling systems for industrial solvents offers a new service model that reduces customer waste disposal costs and lessens dependency on virgin raw materials.
- Manufacturing Growth in Southeast Asia:As industrial production expands in countries like Vietnam and Indonesia, demand for solvents in paints, textiles, and electronics manufacturing is set to increase significantly.
Industry Challenges
- Navigating Divergent Global Regulations:Managing compliance across the distinct and evolving regulatory frameworks of ECHA in Europe, the EPA in the United States, and the MEE in China requires substantial dedicated expertise and resources.
- Capital for Bio-Based Transition:Shifting production from petrochemical to bio-based feedstocks demands significant capital investment in new biorefinery assets and the development of resilient agricultural supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Solvents Market |
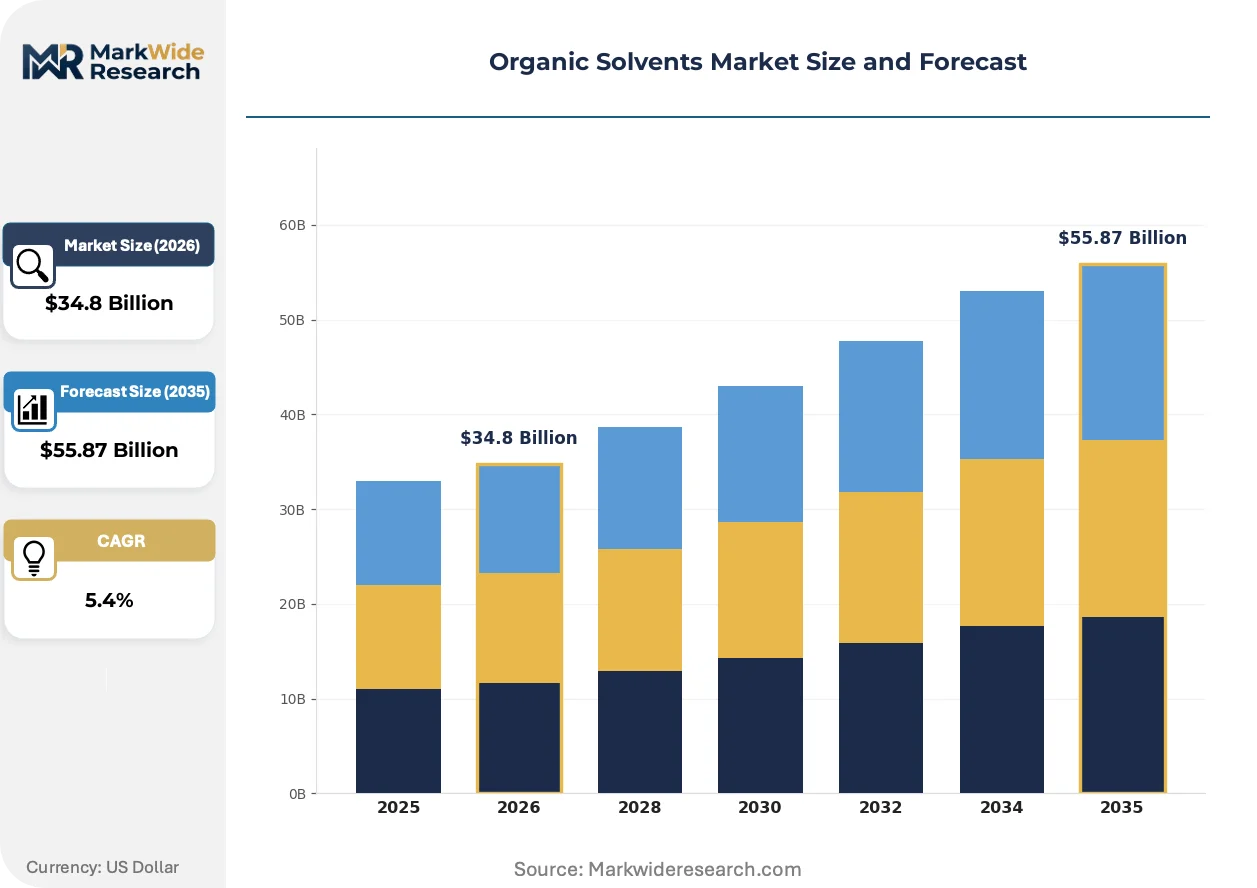
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $55.87 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Aromatic, Aliphatic, Chlorinated, Alcohols Grade: Industrial, Laboratory, Reagent, Pharmaceutical Application: Paints, Coatings, Adhesives, Cleaners End User: Manufacturing, Automotive, Chemical, Pharmaceuticals |
| Companies Covered | Exxon Mobil Corporation, INEOS Group, BASF SE, Solvay S.A., Arkema Group, LyondellBasell Industries Holdings B.V., Shell plc, Eastman Chemical Company, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Solvents Market Strategic Shifts & Innovations
Innovation is driven by the dual pressures of stringent environmental regulations and the exacting performance requirements of advanced manufacturing. This is pushing development toward greener chemical profiles and higher purity grades, fundamentally altering product value propositions away from simple volume.
Bio-based solvents, derived from renewable sources like corn, sugarcane, or cellulosic biomass, function as sustainable alternatives to their petrochemical counterparts. End-use industries such as paints, coatings, and personal care are accelerating their adoption to meet corporate sustainability goals. This shift toward renewable feedstocks is decomposing the traditional, petroleum-based value chain and its inherent price volatility.
Regulatory scrutiny from bodies like the European Chemicals Agency (ECHA) under the REACH framework is continuously evaluating the safety profiles of established solvents. This process forces formulators to find substitutes for any substances reclassified as having high concern, such as certain glycols or chlorinated solvents. The industrial cleaning and chemical synthesis sectors are most affected, driving a constant cycle of reformulation.
Performance-based specifications are replacing traditional, volume-centric procurement, especially in high-technology sectors. Buyers in the semiconductor and pharmaceutical industries now demand solvents certified to specific purity levels with extensive quality documentation, disrupting the standard commodity sales model. This trend is most visible in advanced industrial economies like Germany, Japan, and South Korea, where process integrity is paramount.
Organic Solvents Market Segmentation
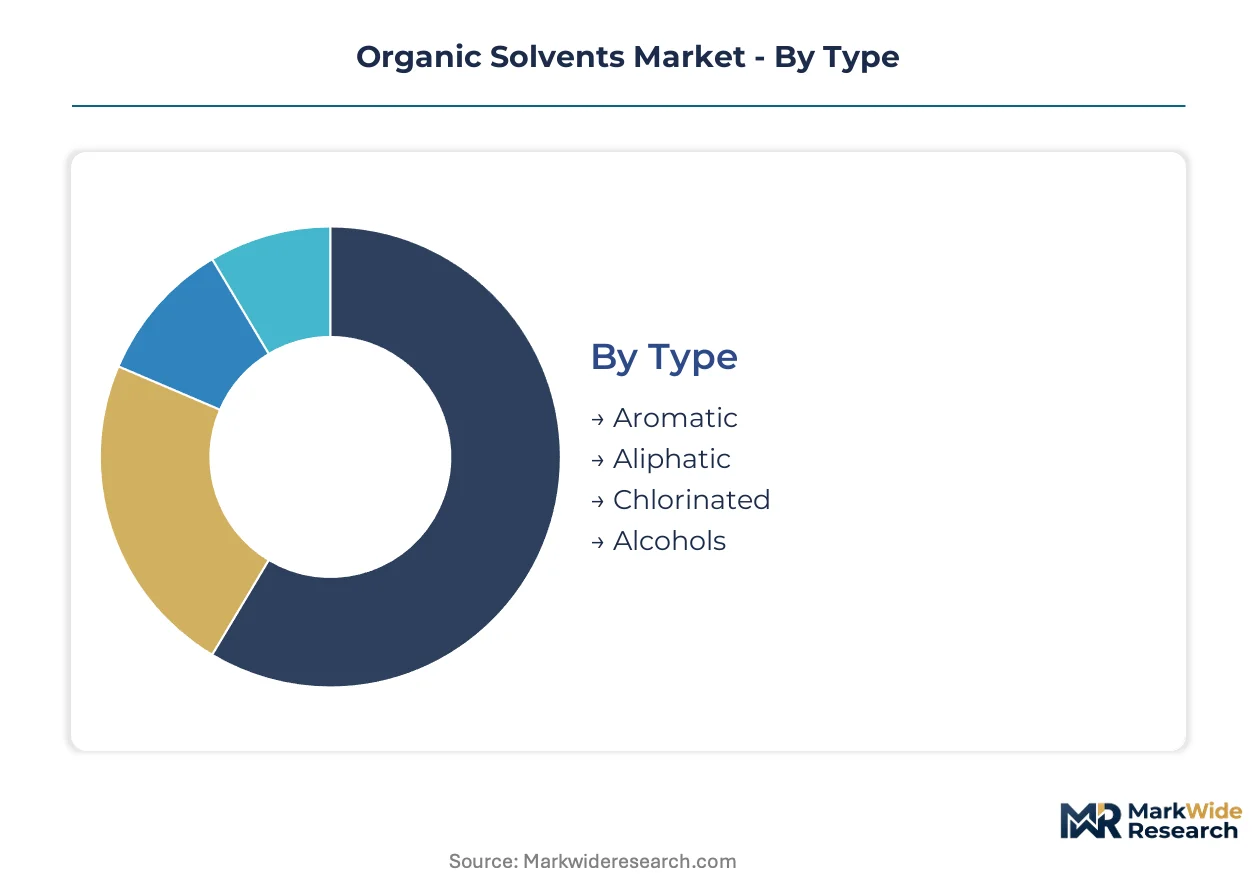
The organic solvents market exhibits nuanced demand patterns across various product types, grades, applications, and end-user industries. Understanding these distinctions clarifies the diverse performance requirements and regulatory compliance challenges faced by producers. This granular view reveals where value is created and captured within the supply chain.
Type:
Demand for specific solvent types exhibits varied geographic concentrations, with some types primarily serving domestic industries and others supporting export-oriented manufacturing.
- Alcohols:These compounds, such as ethanol and isopropanol, are foundational solvents characterized by their ability to dissolve a wide range of organic substances. Their widespread use in coatings and cleaners drives consistent, high-volume demand across global manufacturing hubs like China and India.
- Aromatic:Comprising compounds like toluene and xylene, aromatic solvents are known for their high solvency power and are extensively used in paints, inks, and chemical synthesis. Industrial manufacturing bases in Southeast Asia and Europe rely on these for diverse formulation needs.
- Aliphatic:These include mineral spirits and hexane, offering good solvency for oils, greases, and waxes in applications like degreasing and dry cleaning.
- Chlorinated:Solvents like perchloroethylene and trichloroethylene are potent degreasing agents, though their use is increasingly restricted by environmental regulations in regions like the European Union.
Alcohols commands the established base. The steepest expansion runs through Aromatics.
Grade:
The margin profiles for organic solvents vary significantly by their purity and intended end-use, directly impacting pricing strategies.
- Pharmaceutical:These solvents meet extremely high purity standards, often requiring specific certifications and minimal impurities for use in Active Pharmaceutical Ingredient (API) synthesis and drug formulation. The pharmaceutical sector in Germany and the United States drives substantial demand for these specialized grades.
- Industrial:This grade represents the largest volume segment, used in general manufacturing processes, cleaning, and as carriers in various formulations. Its primary demand stems from the automotive and construction industries in China.
- Laboratory:Solvents for laboratory use are characterized by defined purity levels suitable for analytical testing, research, and educational purposes.
- Reagent:Reagent grades are used as chemical reactants or in specific chemical synthesis processes, requiring consistent composition and reactivity.
Procurement patterns for various grades reflect distinct customer requirements, from bulk industrial purchases to specialized orders for high-purity materials.
Application:
Applications for organic solvents are distinguished by their consumption volumes, with some sectors requiring massive quantities for formulation processes.
- Paints:Organic solvents serve as critical components in paint formulations, controlling viscosity, drying time, and film formation for both industrial and architectural coatings. The construction boom in India and Indonesia sustains high solvent demand.
- Coatings:Solvents are essential for dissolving resins and additives in various protective and decorative coatings, including automotive finishes and industrial protective layers. Robust manufacturing in Japan and South Korea drives consistent demand.
- Adhesives:Solvents are employed in adhesive formulations to dissolve polymers, control application properties, and facilitate drying.
- Cleaners:Organic solvents are widely used in both industrial and household cleaning products for their ability to dissolve grease, oils, and other contaminants.
The maturity of solvent applications ranges from long-established uses in traditional manufacturing to newer formulations driven by performance demands.
End User:
Supply chain configurations for organic solvents are often tailored to the specific needs and procurement scales of their end-user industries.
- Pharmaceuticals:This sector requires high-purity solvents for drug synthesis, extraction, and purification, with stringent quality control and regulatory compliance. The expanding biotech industry in the United States drives specialized solvent demand.
- Manufacturing:This broad category includes diverse industries such as textiles, printing, and electronics, all relying on solvents for cleaning, degreasing, and as carriers in production processes. China's vast industrial base creates significant baseline demand.
- Chemical:The chemical industry utilizes solvents as reaction media, extractants, and purification agents in the production of various chemicals.
- Automotive:Solvents are crucial in the automotive sector for paints, coatings, degreasing, and cleaning applications during vehicle production and maintenance.
The cost structures for end-users are influenced by the specification requirements and scale of solvent consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The significant trade flow of petrochemical-derived solvents from major producers to Asia's industrial manufacturing centers dictates regional demand dynamics. Regulatory frameworks from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) significantly influence product formulation and market access.
China
China's massive industrial base sustains high demand for foundational solvents across coatings and electronics manufacturing. The Ministry of Ecology and Environment (MEE) enforces strict regulations pushing for greener alternatives. Industrial clusters in the Yangtze River Delta continue to drive substantial solvent consumption for diverse manufacturing processes.
United States
The expanding pharmaceutical sector in the United States requires increasing volumes of high-purity solvents for API synthesis. The US Environmental Protection Agency (EPA) mandates stringent VOC emission limits, influencing product formulation. Biotech hubs like those in Boston and San Francisco drive demand for specialized laboratory and pharmaceutical grades.
Germany
Germany's advanced chemical and pharmaceutical industries generate consistent demand for specialized organic solvents. The European Chemicals Agency (ECHA) and REACH framework impose strict safety evaluations for solvent use. Chemical parks in regions like North Rhine-Westphalia are central to high-performance solvent production and consumption.
India
India's burgeoning construction and automotive sectors fuel substantial demand for solvents in paints and coatings formulations. The country's environmental regulations are evolving, encouraging adoption of less toxic alternatives. Manufacturing zones around Mumbai and Chennai exhibit significant solvent uptake for industrial applications.
Vietnam
Industrial expansion in Vietnam, particularly in textiles and electronics, is increasing the need for various organic solvents. The government is implementing policies to promote sustainable industrial development and reduce environmental impact. Manufacturing centers near Ho Chi Minh City are experiencing rising solvent consumption for export-oriented production.
Organic Solvents Market Key Industry Players
Player mix skews toward large, integrated chemical companies alongside specialized niche producers, creating a tiered market structure. This market features high-volume commodity suppliers serving broad industrial needs and providers of high-purity, specialized grades for regulated sectors. Strategic archetypes include diversified global chemical giants, focused high-performance solvent specialists, and agile bio-based innovators. Companies engage in significant capacity expansion to meet baseline demand and actively pursue technology licensing to develop greener, compliant formulations.
Within the diversified chemical giants archetype, BASF SE leverages its extensive product portfolio to serve diverse end-user requirements across multiple grades, from industrial to pharmaceutical. Dow Inc. occupies a similar position, sustaining its market standing through large-scale production of foundational alcohol and aromatic solvents for widespread industrial use and numerous applications. Solvay S.A. represents the high-performance specialist, focusing on niche chemical processing and advanced material sectors with specialized solvent offerings that meet stringent performance criteria and purity standards.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| INEOS Group |
| BASF SE |
| Solvay S.A. |
| Arkema Group |
| LyondellBasell Industries Holdings B.V. |
| Shell plc |
| Eastman Chemical Company |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Six-month lead times for critical petrochemical feedstocks directly impact organic solvent pricing, creating volatility for buyers and influencing inventory strategies across the supply chain.
Pricing Analysis
The pricing gap between established petrochemical solvents and emerging bio-based alternatives reflects varying production costs and regulatory incentives. Commodity spot pricing dominates for industrial grades, while contract-based long-term offtake secures high-purity pharmaceutical grades. Purity certification and volume scale drive price differentiation. Pricing pressure stems from petrochemical feedstock volatility, impacting basic alcohol and aromatic solvents. Industrial manufacturing buyers in China are highly price-sensitive, whereas pharmaceutical companies prioritize purity.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume industrial solvents, while strategic stockpiles secure specialized pharmaceutical grades. China, the US, and Germany concentrate significant solvent production. The supply chain relies on critical petrochemical inputs like ethylene, propylene, and benzene. Regulatory restrictions on volatile organic compound emissions pose a structural risk, forcing reformulation. Distribution runs through a mix of large chemical distributors and direct sales to major industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic solvents market is poised for a cyclical recovery, driven by renewed global industrial manufacturing activity. Strategic recommendations focus on adapting to evolving regulatory landscapes and specialized demand.
For Market Incumbents: Consolidate production capacity in key regions like China to leverage scale economies and counter margin pressure from commodity segments. Incumbents should invest in R&D for advanced bio-based alternatives, mitigating the threat from stringent VOC regulations. Deepen vertical integration into specialized purification technologies to serve the high-purity pharmaceutical sector. Control over raw material sourcing provides a competitive advantage.
For New Entrants and Emerging Players: Certification fast-track for novel bio-based solvents offers a market entry point for new players. Target niche applications in advanced material sectors requiring unique performance profiles, especially in regions with evolving regulatory frameworks. Focus on providing customized formulations for electronics manufacturing in Southeast Asia. A lean go-to-market strategy emphasizing technical support can differentiate offerings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across bio-based solvent production, signaling long-term investment opportunities. Long-term viability hinges on the transition to sustainable feedstocks and high-purity segments. Acquisition targets include specialized producers of pharmaceutical-grade solvents or bio-refinery technology providers. The signal to watch is the adoption rate of bio-based solvents in major end-use industries, indicating market acceptance and scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meet baseline demand in industrial manufacturing hubs like China and India. |
| Green Manufacturing Transition | Align with stringent environmental regulations from ECHA and the EPA. |
| Long-term Supply Agreement | Secure stable feedstock access amidst petrochemical market volatility. |
| Joint Venture | Accelerate bio-based solvent development and commercialization efforts. |
| Regulatory Approval Pathway | Expedite market access for specialized pharmaceutical and electronics grades. |
Research Approach
Desk research of trade publications, corporate filings, and regulatory agency reports preceded structured interviews with R&D directors, procurement managers, and environmental compliance officers. This primary research was validated against secondary data from industry associations and customs records. A rigorous bottom-up and top-down triangulation approach ensured data consistency across all market segments.
Variance decomposition identified key drivers impacting market growth across the modeling period, including regulatory shifts and technological advancements. Segmentation dimensions like type, grade, application, end-user industry, and regional regulatory frameworks were modeled. Compound annual growth rates were derived from historical trends and forecast assumptions. API production volumes and electric vehicle battery manufacturing forecasts served as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of stable crude oil prices and consistent regulatory enforcement; material deviation would warrant model refresh. Significant geopolitical events or rapid shifts in bio-based feedstock availability pose key risk factors. Revision becomes warranted when major policy changes from ECHA or EPA cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Benzene Market
Solvents
Toluene Derivatives Market
Solvents
Diethanolamine (DEA) Market
Solvents
Ketone-Based Solvents Market
Solvents
6-Xylenol Market
Solvents
Trifluoroethanol Market
Solvents
Ethoxydiglycol Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Potassium Formate Market
Solvents
Tetraethyl Benzene Market
Solvents
Crotonaldehyde Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Global Furfural Solvent Market
Solvents
Oxygenated Solvents Market
Solvents
Hexylene Glycol Market
Solvents
Nitroglycerin Market