
 North America N-Hexane Market | 2026-2036
North America N-Hexane Market Size, Share, and Industry Trends Forecast 2026-2036
North America N-Hexane Market Intelligence
Aftermarket solvent recovery and recycling revenue is tilting toward integrated petrochemical operators with captive distillation networks. ExxonMobil Corporation leverages its Gulf Coast refining footprint to supply high-purity hexane streams directly to food processing customers. Shell plc anchors its position through backward integration into cracker operations, ensuring feedstock cost stability. Chevron Corporation competes by specializing in low-aromatic solvent grades that meet stringent pharmaceutical extraction protocols.
N-hexane is a straight-chain aliphatic hydrocarbon with six carbon atoms, typically produced via crude oil fractionation and subsequent catalytic reforming or molecular sieve separation, yielding a colorless liquid with a boiling point of approximately 69 degrees Celsius that functions primarily as a non-polar solvent and reaction medium in industrial processes. Solvent grade dominates volume throughput due to its entrenched role in vegetable oil extraction across North American processing plants. Extractants application is expanding fastest as biofuel producers adopt hexane for lipid recovery from algae and waste oil feedstocks. Laboratory grade commands premium pricing owing to ultra-low impurity specifications required by pharmaceutical quality control protocols.
EPA NESHAP standards mandate vapor recovery and emission controls at solvent extraction facilities, pushing processors toward closed-loop systems that sustain demand for higher-purity hexane with lower evaporation loss. OSHA permissible exposure limits influence workplace handling protocols and personal protective equipment requirements across hexane-handling operations. FDA food contact substance regulations govern residual solvent levels in extracted edible oils, directly shaping product specification requirements for food-grade hexane suppliers. Stakeholders must monitor evolving state-level air quality regulations in California and Texas, where regional authorities are tightening volatile organic compound restrictions that could reshape permissible end-use applications and equipment upgrade timelines.
Market Dynamics
EPA NESHAP vapor recovery mandates are compressing operating margins at solvent extraction facilities while simultaneously filtering demand toward higher-purity hexane grades that minimize evaporative losses. This regulatory pressure is restructuring supplier-processor relationships across the Gulf Coast petrochemical corridor.
Growth Catalysts
- Solvent-grade demand from edible oil extraction:Soybean and canola processing facilities across the US Midwest and Canadian Prairies require consistent hexane supply for lipid recovery operations. Food-grade specifications tighten residual solvent tolerances.
- EPA NESHAP compliance upgrades:Closed-loop vapor recovery system installations at extraction plants sustain demand for low-volatility hexane formulations. Equipment retrofits extend contract durations with certified suppliers.
- Biofuel lipid recovery expansion:Algae cultivation and waste oil processing operations in Texas and Louisiana adopt hexane-based extractant protocols. Pilot-scale facilities transition to commercial throughput.
Market Restraints
- Crude oil feedstock volatility:Naphtha cracking margins fluctuate with West Texas Intermediate pricing, compressing hexane producer spreads during upstream cost spikes.
- Gulf Coast supply concentration:Over 70 percent of North American hexane refining capacity clusters in Texas and Louisiana, exposing buyers to hurricane disruption and pipeline constraint risks.
- Supercritical CO2 substitution:Premium edible oil processors in California trial carbon dioxide extraction systems to eliminate solvent residues entirely, threatening hexane volume at the quality tier.
Strategic Opportunities
- Canadian oilseed processing expansion:Saskatchewan and Manitoba canola crush capacity additions create incremental hexane demand from facilities seeking supply security beyond domestic refining.
- Pharmaceutical-grade specification premiums:Ultra-low aromatic hexane for active pharmaceutical ingredient crystallization commands pricing multiples over standard solvent grades.
- Integrated solvent recovery services:On-site distillation and recycling contracts at multi-plant food processors convert single-sale chemical supply into recurring revenue streams.
Industry Challenges
- Process safety engineer scarcity:Gulf Coast petrochemical operators compete for talent capable of managing hexane handling protocols under OSHA permissible exposure limits.
- Closed-loop system capex burdens:EPA-mandated vapor recovery installations require 18-24 month payback periods that strain mid-scale extraction facility balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America N-Hexane Market |
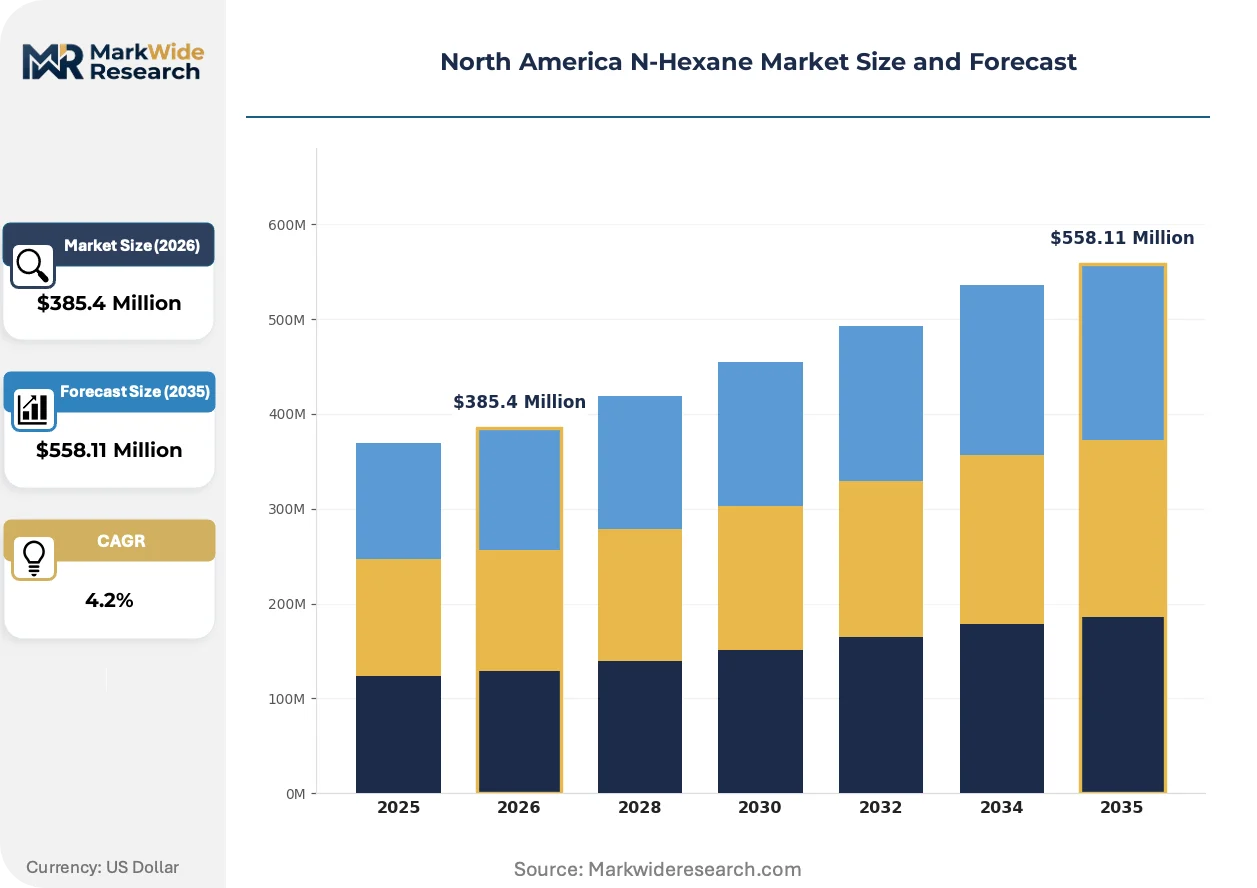
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Grade, Laboratory Grade, Industrial Grade, Technical Grade Application: Adhesives, Coatings, Extractants, Chemical Intermediates End User: Pharmaceuticals, Food Processing, Petrochemicals, Agriculture Distribution Channel: Direct Sales, Distributors, Online Retailers, Chemical Suppliers |
| Companies Covered | Phillips 66, Sumitomo Chemical, ExxonMobil Corporation, Rompetrol Rafinare, GFS Chemicals, Chevron Corporation, Phillips Chemical Company, DHC Solvent Chemie, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America N-Hexane Market Strategic Shifts & Innovations
Molecular sieve separation advances and regulatory compliance automation are compressing product differentiation windows while opening premium tiers for certified low-aromatic grades. Process intensification and digital monitoring reshape competitive positioning.
Membrane separation technology for hexane purification is hybridizing traditional fractional distillation with selective permeation modules. Specialty chemical producers in Texas adopt hybrid units to achieve sub-50 ppm aromatic specifications without multiple distillation columns. This convergence compresses capital requirements for pharmaceutical-grade certification while fragmenting the supplier base between integrated refiners and technology-licensed mid-scale operators.
EPA NESHAP residual risk reviews tighten maximum achievable control technology standards for solvent extraction facilities. Processors face 36-month compliance timelines for enhanced vapor capture and leak detection systems. Food-grade hexane specifications harden correspondingly, as residual solvent testing protocols under FDA food contact substance regulations extend to downstream oil refiners.
Specification-driven procurement now dominates hexane purchasing at multi-plant edible oil processors. Buyers consolidate vendor lists to three certified suppliers per region, replacing spot-market purchasing with annual framework agreements tied to purity certification and delivery reliability metrics. This concentration is most visible across Iowa and Illinois soybean processing corridors, where integrated crushers prioritize supply security over unit cost minimization.
North America N-Hexane Market Segmentation
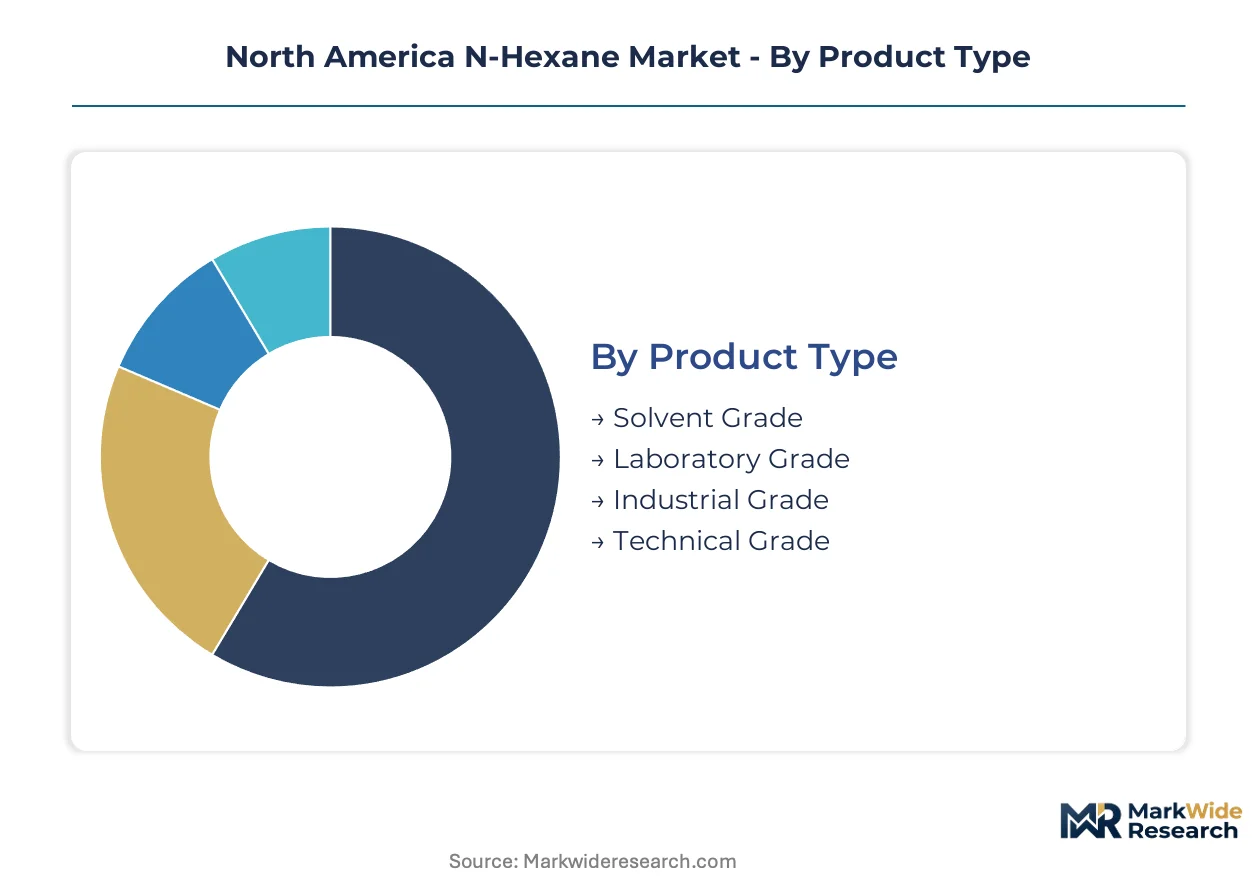
N-Hexane segmentation in North America reflects divergent purity requirements across extraction chemistry and regulatory compliance tiers. Product grade specifications directly determine allowable end-use applications under FDA food contact and EPA NESHAP frameworks.
Product Type:
Solvent-grade formulations turn inventory fastest through edible oil extraction contracts, while laboratory-grade batches sit longer due to certification protocols and smaller order quantities.
- Solvent Grade:Colorless liquid with 60-70% n-hexane content and controlled aromatic levels below 500 ppm, optimized for lipid recovery operations. Soybean processors across Iowa and Illinois consume the largest volumes under annual framework agreements with Gulf Coast refiners. EPA NESHAP vapor recovery mandates favor low-volatility solvent-grade formulations that minimize evaporative losses in closed-loop systems.
- Laboratory Grade:Ultra-purified to 95%+ n-hexane with sub-50 ppm aromatic specifications and comprehensive batch certification documentation. Pharmaceutical quality control laboratories in New Jersey and Massachusetts command premium pricing for residual solvent testing and active ingredient crystallization protocols.
- Industrial Grade:Blended hydrocarbon streams with 50-60% n-hexane content for non-critical cleaning and degreasing applications.
- Technical Grade:Intermediate purity tier serving adhesive formulation and general chemical synthesis where food-contact certification is not required.
Solvent grade dominates installed base. Laboratory grade is where expansion concentrates.
Application:
Cost tier stratification separates commodity extraction chemistry from specialty formulation applications requiring certification premiums.
- Extractants:Primary demand driver deploying hexane's non-polar solubility parameters for vegetable oil and biofuel lipid recovery. Canola crush facilities in Saskatchewan and Manitoba represent the fastest-expanding customer segment as Canadian oilseed processing capacity adds solvent extraction trains.
- Chemical Intermediates:Feedstock for hexene production and polymerization catalyst activation within Texas and Louisiana petrochemical complexes. Gulf Coast crackers consume captive hexane streams for downstream olefin manufacturing.
- Adhesives:Solvent carrier for rubber-based and hot-melt adhesive formulations in packaging and construction applications.
- Coatings:Diluent and viscosity modifier in industrial paint and varnish systems where evaporation rate control matters.
Extractants command volume leadership. Chemical intermediates capture margin expansion.
End User:
Customer-type concentration patterns show food processors driving procurement standardization while pharmaceutical buyers fragment across quality tiers.
- Food Processing:Integrated soybean and canola crushers operating solvent extraction facilities under FDA food contact substance regulations. Multi-plant operators in the US Midwest consolidate vendor lists to three certified suppliers per region, prioritizing delivery reliability over unit cost.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers and contract testing laboratories requiring ultra-low aromatic grades. FDA residual solvent testing protocols under ICH Q3C guidance dictate hexane specification thresholds for drug substance certification.
- Petrochemicals:Integrated refiners and olefin producers consuming hexane as chemical intermediate feedstock within Gulf Coast manufacturing complexes.
- Agriculture:Pesticide formulation and crop oil concentrate blending operations in California's Central Valley.
Food processing anchors volume throughput. Pharmaceuticals generate specification premiums.
Distribution Channel:
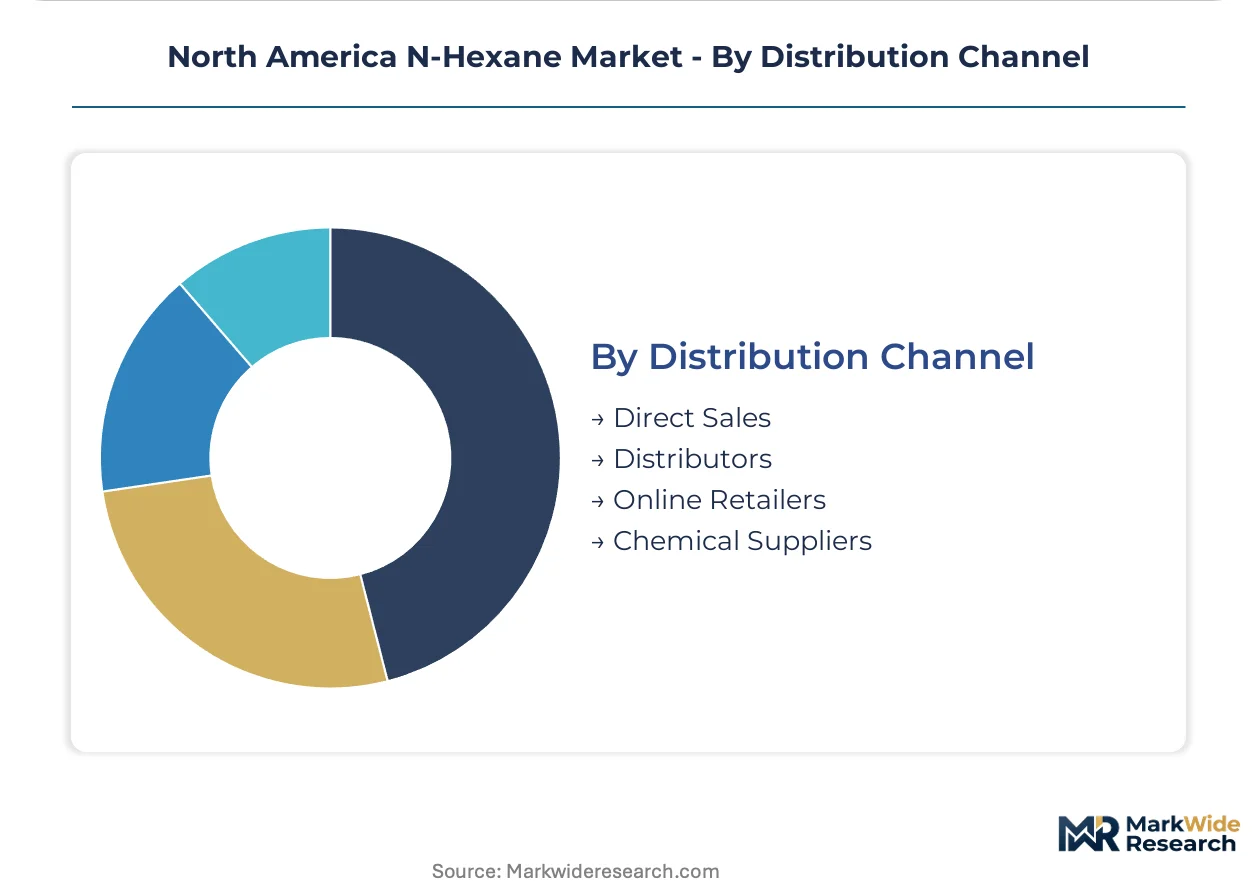
Supply concentration geography dictates channel selection, with Gulf Coast proximity enabling direct refiner relationships while inland processors rely on distributor networks.
- Direct Sales:Refiner-to-producer relationships for high-volume solvent-grade contracts at soybean processing facilities. ExxonMobil and Shell leverage Gulf Coast refining footprints to supply food processing customers without intermediary markup.
- Distributors:Regional chemical distributors serving mid-scale extraction facilities and specialty formulation customers lacking tank-car receiving infrastructure.
- Chemical Suppliers:Integrated distributors with blending and repackaging capabilities for laboratory-grade and technical-grade tiering.
- Online Retailers:Small-package fulfillment for research laboratories and pilot-scale operations requiring rapid delivery of certified grades.
Direct sales capture bulk volume. Distributors enable geographic reach expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hexane consumption patterns diverge sharply across North America. The United States dominates solvent-grade volume through Gulf Coast petrochemical infrastructure, while Canada concentrates demand in Prairie oilseed processing corridors. Mexico's emerging biofuel sector adopts hexane extractants at pilot scale.
United States
Texas and Louisiana host over 70 percent of regional refining capacity, with ExxonMobil and Shell operating integrated naphtha cracking complexes. EPA NESHAP vapor recovery mandates drive closed-loop system adoption at soybean processing facilities. The Iowa-Illinois corridor anchors food-grade solvent demand through multi-plant crushing operations.
Canada
Saskatchewan and Manitoba canola crush capacity expansions create incremental hexane demand from facilities seeking supply security. Health Canada and PMRA residue limits align with FDA food contact substance standards for cross-border oilseed trade. Edmonton and Regina processing clusters consolidate vendor relationships with three certified suppliers per region.
Mexico
Biofuel lipid recovery from algae cultivation trials in Baja California and Sonora introduces hexane extractant protocols at pilot scale. Mexican environmental regulators tighten volatile organic compound restrictions in industrial zones. Tamaulipas petrochemical complexes evaluate captive hexane production for downstream olefin manufacturing.
North America N-Hexane Market Key Industry Players
Capability concentration sits with integrated refiners commanding Gulf Coast infrastructure; scale advantage sits with mid-scale operators licensed for pharmaceutical-grade certification. The market structures around three tiers: captive petrochemical producers, specialty solvent distributors, and technology-licensed purification specialists. Consolidation pressure favors backward integration into cracker operations and hybrid membrane-distillation licensing arrangements.
Within the integrated refiner tier, ExxonMobil Corporation and Shell plc anchor supply relationships through direct sales to food processing customers. Chevron Corporation occupies a position in low-aromatic specialty grades. These three exemplify competitive positioning through infrastructure control rather than product differentiation alone.
| Leading Market Players |
|---|
| Phillips 66 |
| Sumitomo Chemical |
| ExxonMobil Corporation |
| Rompetrol Rafinare |
| GFS Chemicals |
| Chevron Corporation |
| Phillips Chemical Company |
| DHC Solvent Chemie |
| Shell plc |
| Others |
Cost & Logistics Intelligence
Overcapacity signals in Gulf Coast naphtha cracking are compressing producer spreads and forcing integrated refiners toward long-term offtake structures that lock in hexane volume commitments from food processors. This utilization dynamic simultaneously erodes spot-market liquidity and strengthens pricing power for certified low-aromatic grades that command specification premiums under EPA NESHAP frameworks.
Pricing Analysis
Long-term offtake agreements dominate hexane procurement at multi-plant edible oil processors, replacing spot purchasing with annual framework contracts tied to purity certification and delivery reliability metrics. Price differentiation separates pharmaceutical-grade specifications with sub-50 ppm aromatic content from standard solvent grades, with certification level and volume scale as primary tiering drivers. Pricing pressure stems from crude oil feedstock volatility compressing naphtha cracking margins during upstream cost spikes. Mid-scale extraction facilities exhibit highest price sensitivity due to capex burdens from EPA-mandated vapor recovery installations, while integrated petrochemical operators with captive distillation networks demonstrate lowest sensitivity.
Supply Chain Analysis
Upstream feedstock supply draws from naphtha streams produced via crude oil fractionation at Texas and Louisiana refining complexes, with catalytic reforming and molecular sieve separation yielding hexane cuts. Raw material dependencies center on West Texas Intermediate pricing, natural gas for process heat, and specialized zeolite membranes for pharmaceutical-grade purification. Single-source vulnerability concentrates risk in the Gulf Coast corridor where hurricane disruption and pipeline constraints threaten supply continuity. Distribution runs through direct refiner-to-producer relationships for high-volume solvent-grade contracts, supplemented by regional chemical distributors serving mid-scale facilities lacking tank-car infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as specification-driven procurement at food processors consolidates vendor lists while creating niches for technology-licensed mid-scale operators capable of hybrid membrane-distillation purification. EPA NESHAP residual risk reviews and FDA food contact substance regulations are splintering demand into certified grade tiers that favor specialized players over commodity suppliers.
For Market Incumbents: Pre-empt supercritical CO2 substitution threats by investing in closed-loop vapor recovery service contracts that convert single-sale chemical supply into recurring revenue streams at multi-plant processors. Backward integration into cracker operations secures feedstock cost stability against naphtha margin volatility, while pharmaceutical-grade certification investments capture pricing multiples from active ingredient crystallization demand. For New Entrants and Emerging Players: Establish a beachhead in Canadian Prairie oilseed processing corridors where Saskatchewan and Manitoba canola crush capacity expansions create incremental hexane demand beyond domestic refining supply. Target laboratory-grade distribution through chemical suppliers with blending and repackaging capabilities, leveraging online retailer channels for rapid small-package fulfillment to research laboratories. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade purification as hybrid membrane-distillation licensing arrangements replace traditional multi-column distillation. Long-term viability favors technology-licensed mid-scale operators with sub-50 ppm aromatic certification capabilities over commodity solvent distributors. Acquisition target archetype: regional distributors with captive tank-car fleets and FDA food contact substance compliance infrastructure. Signal to watch: EPA NESHAP maximum achievable control technology standard revisions accelerating closed-loop system adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Operations | ExxonMobil and Shell anchor feedstock cost stability through Gulf Coast naphtha cracking control. |
| Hybrid Membrane-Distillation Licensing | Texas specialty producers achieve pharmaceutical-grade certification without capital-intensive column arrays. |
| Long-term Supply Agreement Expansion | Iowa-Illinois soybean processors consolidate vendor lists to three certified suppliers per region. |
| Integrated Solvent Recovery Services | On-site distillation contracts at multi-plant food processors convert chemical sales to recurring revenue. |
| Pharmaceutical-Grade Certification Investment | New Jersey and Massachusetts laboratories command premium pricing for ultra-low aromatic specifications. |
Research Approach
Cross-validation between primary interviews with plant managers at Gulf Coast petrochemical complexes and secondary validation through customs/trade data and SEC 10-K filings anchors the qualitative findings. Stakeholder roles engaged include procurement leads at downstream edible oil processors, distribution channel partners, technical R&D directors, and regulatory compliance officers. Secondary sources span American Chemistry Council reports, EPA NESHAP enforcement databases, and FDA food contact substance notification records. Bottom-up capacity utilization modeling triangulates against top-down demand aggregation from oilseed processing throughput statistics.
Calibration against historical naphtha cracking margin cycles and vegetable oil extraction capacity expansions informs the projection framework across the analysis window. Segmentation dimensions modeled include product grade tier, end-use application, and regional production hub concentration. CAGRs derive from regression analysis of hexane demand intensity per unit of oilseed crush capacity, incorporating biofuel lipid recovery adoption curves and pharmaceutical-grade specification penetration rates.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories or EPA enforcement intensity would shift the trajectory. Forecasts reflect assumptions regarding NESHAP compliance timelines and Canadian oilseed processing buildout schedules. Cross-checking against EIA petrochemical feedstock consumption data and Health Canada residue limit harmonization announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
North America Potassium Formate Market