
 Multilayer Ceramic Capacitor Market | 2026-2036
Multilayer Ceramic Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Multilayer Ceramic Capacitor Market Intelligence
A transition toward multi-source procurement strategies by automotive and industrial equipment manufacturers is rebalancing supplier power in the market. Murata Manufacturing Co., Ltd. leverages its scale and advanced material science to lead in high-capacitance products for 5G infrastructure. TDK Corporation specializes in miniaturized components for consumer electronics and automotive infotainment systems. YAGEO Group competes through a broad product portfolio and a strong presence in the distribution channel.
A multilayer ceramic capacitor is a passive electronic component constructed from alternating layers of conductive metal electrodes and dielectric ceramic material. Its primary function is to store electrical energy, filter signals, and decouple power in electronic circuits for stable device operation. Among product types, X7R capacitors dominate due to stable performance across a wide temperature range, making them suitable for automotive systems. The consumer electronics application segment exhibits high volume, but the automotive segment commands higher margins for high-reliability components.
Compliance with the EU's RoHS directive, which restricts hazardous substances, and REACH regulations on chemical usage are mandatory for market access in Europe. In the United States, automotive-grade components must adhere to specific AEC-Q200 stress test qualification standards, ensuring reliability. Future investment decisions hinge on balancing the high capital cost of advanced manufacturing capacity against the volatility of demand in the consumer electronics sector.
Market Dynamics
The market's central dynamic is the divergence between high-volume, cost-sensitive consumer electronics and high-margin, reliability-focused automotive and industrial applications. This split influences everything from capital investment in manufacturing capacity to material science research and development priorities.
Growth Catalysts
- 5G Infrastructure Expansion:The global rollout of 5G telecommunications networks necessitates high-frequency, high-capacitance MLCCs for base stations and other infrastructure, creating a significant demand driver for advanced products.
- Automotive Electrification:The proliferation of electric vehicle powertrains and advanced driver-assistance systems (ADAS) directly increases the per-vehicle content of high-reliability MLCCs, particularly stable X7R-type capacitors.
- Component Miniaturization:Continuous pressure from consumer electronics manufacturers to reduce the size and weight of devices like smartphones and wearables fuels innovation in ultra-small case size capacitors.
Market Restraints
- Raw Material Price Volatility:The cost and availability of key materials, especially precious metals like palladium used for electrodes in certain MLCC types, introduce significant margin pressure and supply chain uncertainty.
- Technical Scaling Limits:Pushing for higher capacitance in ever-smaller footprints encounters physical limitations in dielectric material thickness and integrity, increasing manufacturing complexity and defect rates for leading-edge nodes.
- Supply Base Concentration:High-performance and automotive-grade MLCC manufacturing is heavily concentrated in Japan and South Korea, creating potential bottleneck risks and reducing the bargaining power of buyers during periods of high demand.
Strategic Opportunities
- Medical Device Applications:The growing market for implantable and wearable medical electronics opens a new, high-margin opportunity for components that offer exceptional reliability and biocompatibility.
- Industrial IoT and Automation:Expanding use of sensors and control modules in factory automation and industrial IoT (IIoT) systems provides a long-term growth avenue for robust, industrial-grade MLCCs.
- Base Metal Electrode (BME) Technology:Further development of BME capacitors using nickel and copper electrodes presents an opportunity to reduce dependence on volatile palladium, lowering costs for a wide range of applications.
Industry Challenges
- High Capital Expenditure:Building and equipping new fabrication plants to produce next-generation, miniaturized MLCCs requires substantial upfront investment, posing a significant barrier to entry and expansion.
- Stringent Qualification Cycles:Meeting the AEC-Q200 stress testing qualification for automotive-grade components involves long and costly validation processes, slowing the introduction of new products into this lucrative segment.
- Demand Cyclicality:The market remains exposed to the volatile demand cycles of the consumer electronics sector, complicating capacity planning and investment decisions for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multilayer Ceramic Capacitor Market |
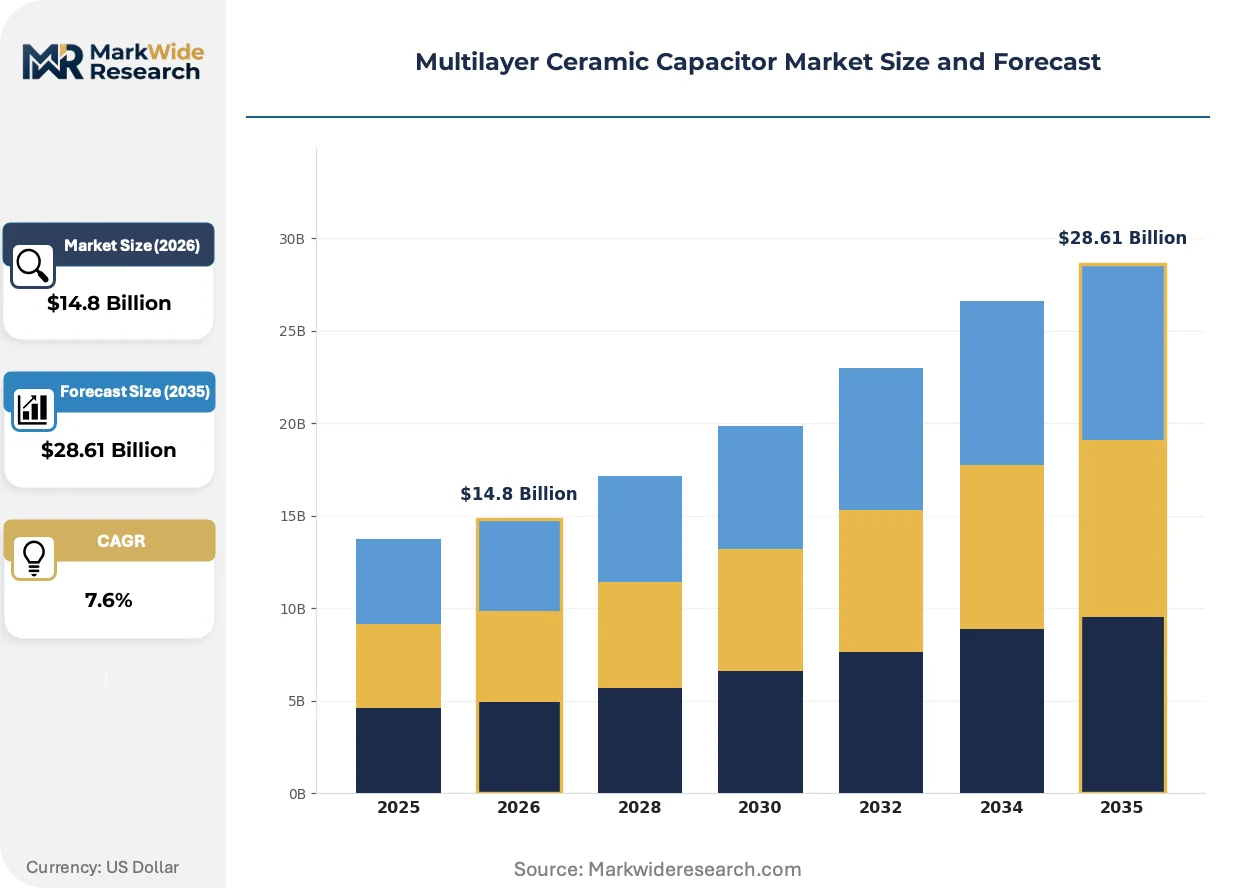
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X7R, C0G, X5R, Y5V, Z5U, Others Application: Consumer Electronics, Telecommunication Equipment, Industrial Equipment, Aerospace & Defense, Automotive Systems, LED Lighting End User: OEMs, Contract Manufacturers, Electronic Assemblers, System Integrators Technology: Sputtering, Tape Casting, Screening, Laser Drilling, Electrode Printing |
| Companies Covered | TAIYO YUDEN CO., LTD., KYOCERA Corporation, Murata Manufacturing Co., Ltd., Vishay Intertechnology, Inc, Walsin Technology Corporation, SAMSUNG ELECTRO-MECHANICS, TDK Corporation, Future Electronics, YAGEO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multilayer Ceramic Capacitor Market Strategic Shifts & Innovations
Product development is increasingly defined by a dual-track approach. One track focuses on extreme miniaturization for consumer applications, while the other prioritizes thermal and electrical stability for the demanding automotive and industrial sectors, driving material science advancements.
Advanced dielectric ceramic formulations and precision stacking technologies are key to increasing capacitance density. The automotive and 5G infrastructure sectors are the primary adopters of these high-performance components. This advancement is automating the production of complex, high-layer-count capacitors, improving manufacturing yields and consistency for parts that previously required extensive process tuning.
The global enforcement of automotive reliability standards, notably the AEC-Q200 stress test qualification, is a significant regulatory trend. This standard mandates rigorous testing for passive components, compelling manufacturers to establish separate, highly controlled production lines for automotive-grade MLCCs. The automotive segment is most affected, as compliance is non-negotiable for Tier-1 supplier contracts.
A notable behavioral shift involves OEMs in the automotive and industrial equipment fields adopting multi-source procurement policies. This move away from single-supplier relationships is a direct response to previous supply chain disruptions and component shortages. The trend is most pronounced in North American and European manufacturing hubs, where supply chain resilience has become a core strategic imperative.
Multilayer Ceramic Capacitor Market Segmentation
Market segmentation clarifies the diverse needs and technical specifications driving demand within the multilayer ceramic capacitor industry. Understanding these distinct segments allows manufacturers to tailor product development, allocate capital investments, and optimize supply chain strategies for specific end-use requirements.
Product Type:
Multilayer ceramic capacitor specifications delineate performance characteristics crucial for diverse applications.
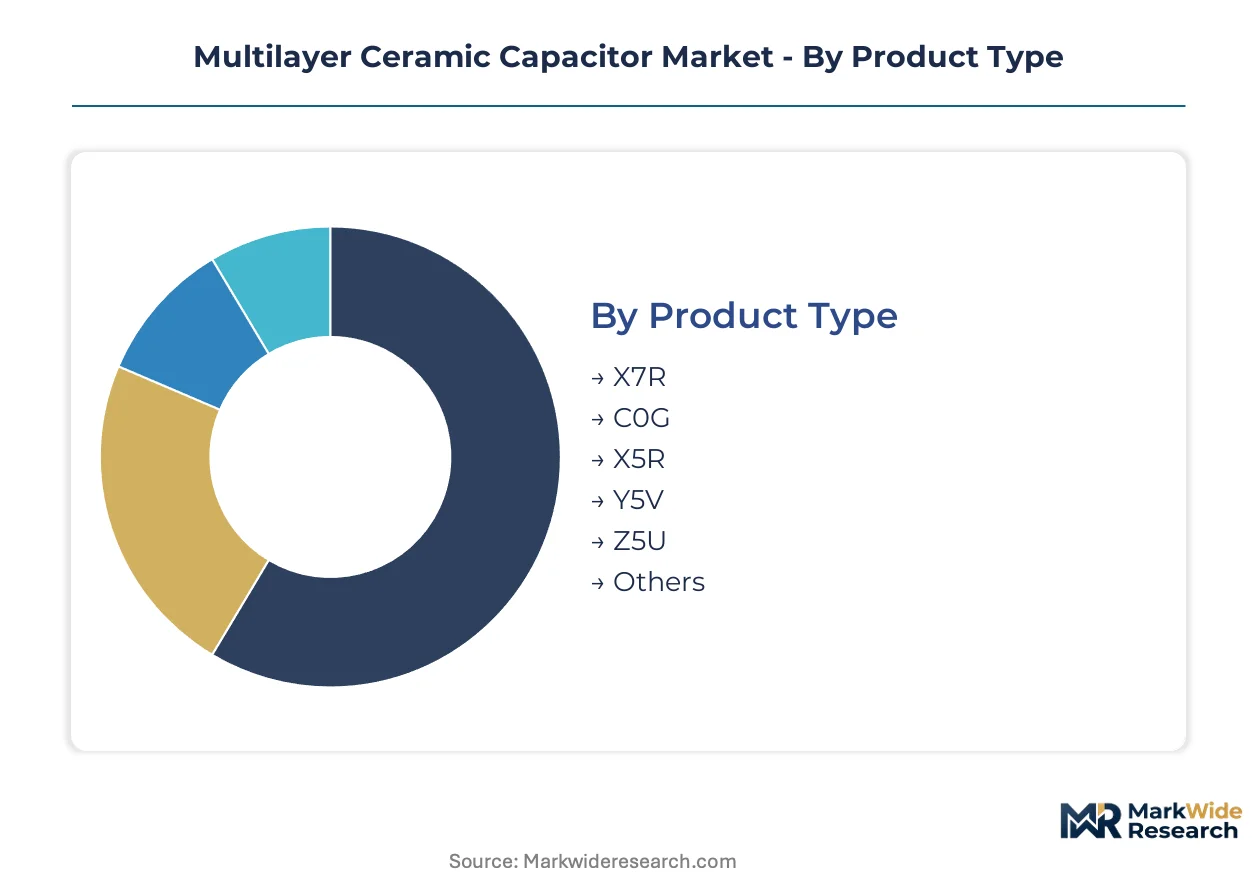
- X7R:These capacitors utilize a ceramic dielectric material providing stable performance across a wide temperature range, typically from -55°C to +125°C, with capacitance variation within ±15%. Demand for X7R capacitors is concentrated in automotive systems, where their reliability is critical for electric vehicle powertrains and ADAS.
- C0G:C0G capacitors feature a ceramic dielectric with highly stable electrical properties, exhibiting minimal capacitance change (±30 ppm/°C) over a broad temperature range and low dielectric loss. Telecommunication equipment and high-precision industrial sensors increasingly adopt C0G types for their superior stability and accuracy.
- X5R:X5R capacitors offer a balance of capacitance density and temperature stability, suitable for general-purpose applications.
- Y5V:Y5V types provide high capacitance values in a small footprint but exhibit significant capacitance variation with temperature and voltage.
- Z5U:Z5U capacitors offer high volumetric efficiency but are limited to narrow temperature ranges and show substantial capacitance drift.
- Others:This segment includes specialized MLCCs, such as ultra-high Q capacitors for RF applications and high-voltage types for power supplies.
X7R leads on scale; C0G leads on momentum.
Application:
Market applications dictate both performance requirements and volume demand for MLCCs.
- Automotive Systems:This segment encompasses MLCCs used in electric vehicle powertrains, advanced driver-assistance systems (ADAS), infotainment units, and engine control units. Automotive applications command higher margins due to stringent reliability standards like AEC-Q200 stress test qualification.
- Consumer Electronics:MLCCs are integral to smartphones, laptops, wearables, and other personal electronic devices, driving significant volume demand. Continuous pressure for miniaturization in consumer electronics fuels innovation in ultra-small case size capacitors.
- Telecommunication Equipment:This segment includes MLCCs for 5G base stations, networking infrastructure, and communication modules, requiring high-frequency and high-capacitance components.
- Industrial Equipment:MLCCs find use in factory automation, robotics, power supplies, and control systems, demanding robust and long-life components.
- Aerospace & Defense:High-reliability and radiation-hardened MLCCs are critical for avionics, satellite systems, and military communication devices.
- LED Lighting:MLCCs are employed in LED drivers and power circuits for stable operation and flicker reduction in various lighting solutions.
Automotive Systems command significant value; Consumer Electronics drive high volume.
End User:
Different end-user types engage with MLCC suppliers at various points in the electronics manufacturing supply chain.
- OEMs:Original Equipment Manufacturers directly integrate MLCCs into their final products, influencing design specifications and procurement decisions. Automotive and industrial OEMs increasingly adopt multi-source procurement policies.
- Contract Manufacturers:These firms produce electronic assemblies and sub-systems for OEMs, requiring large volumes of diverse MLCC types. Contract manufacturers prioritize cost-effectiveness and consistent supply for their production lines.
- Electronic Assemblers:Electronic assemblers perform specialized tasks like surface-mount technology (SMT) component placement for various industries.
- System Integrators:These entities combine different electronic components and sub-systems to create complete solutions for clients.
OEMs exert direct procurement influence; Contract Manufacturers facilitate large-scale integration.
Technology:
MLCC manufacturing processes vary in complexity and precision, impacting component characteristics and cost.
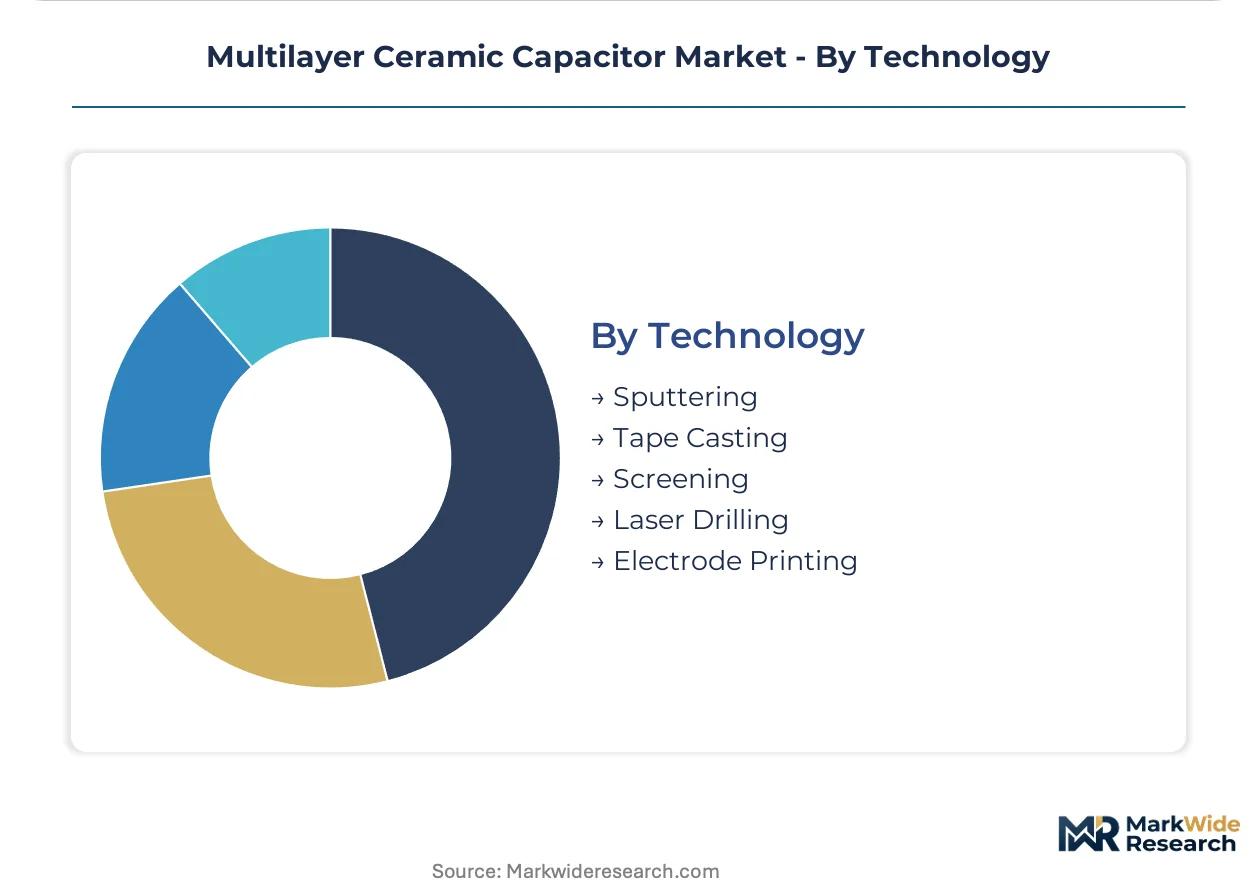
- Tape Casting:This traditional method involves casting ceramic slurry into thin sheets, which are then stacked with electrode layers. Tape casting remains a dominant method for high-volume MLCC production across various product types.
- Sputtering:Sputtering is a thin-film deposition technique used to create ultra-thin dielectric and electrode layers, enabling higher capacitance in smaller footprints. Advanced sputtering techniques are critical for developing high-performance MLCCs for 5G infrastructure.
- Screening:Screening is a common method for applying electrode patterns onto ceramic layers, particularly in multi-layer structures.
- Laser Drilling:Laser drilling creates precise vias and patterns in ceramic substrates for advanced MLCC designs.
- Electrode Printing:This technology involves printing conductive electrode patterns directly onto ceramic layers, offering flexibility in design.
Tape Casting remains a foundational method; Sputtering offers advanced material deposition capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's advanced material science capabilities anchor the global production of high-performance multilayer ceramic capacitors. Automotive electrification and 5G infrastructure expansion drive demand across key manufacturing and consumption centers. These regional dynamics shape investment flows and technological advancements for MLCC suppliers.
Japan
Japanese manufacturers lead in developing high-capacitance MLCCs for 5G base stations and precision automotive applications. The Ministry of Economy, Trade and Industry (METI) supports R&D initiatives for advanced electronic materials. Tokyo and Osaka remain critical hubs for MLCC research, development, and high-volume production facilities.
South Korea
South Korea is a major hub for miniaturized MLCCs, catering to the country's robust consumer electronics and automotive industries. The government's support for semiconductor and display manufacturing indirectly boosts MLCC innovation. Suwon and Cheonan host significant production facilities and R&D centers for advanced component development.
United States
Demand for high-reliability MLCCs in the United States stems from its large automotive, aerospace, and defense sectors. Compliance with AEC-Q200 standards is mandatory for automotive-grade components in this market. Silicon Valley and Detroit are key demand centers, driving innovation for specialized industrial and electric vehicle applications.
Germany
Germany's automotive industry generates substantial demand for stable X7R capacitors used in electric vehicles and advanced driver-assistance systems. REACH regulations and RoHS directives govern chemical usage and hazardous substances for market access in Europe. Munich and Stuttgart represent major automotive manufacturing clusters and drive MLCC integration.
China
China's rapid 5G network rollout and expanding electric vehicle production create immense demand for both high-end and general-purpose MLCCs. GB standards dictate product quality and safety for electronic components within the country. The Yangtze River Delta region, including cities like Shanghai and Suzhou, hosts extensive electronics manufacturing and assembly operations.
Multilayer Ceramic Capacitor Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche applications like medical devices and industrial IoT. The market structure exhibits a tiered consolidation, with a few large players dominating high-performance segments. Strategic archetypes include integrated material science specialists, broad-portfolio providers, and miniaturization-focused innovators. Dominant competitive moves involve continuous capital investment in advanced manufacturing capacity and strategic partnerships to secure raw material supply.
Within the integrated material science tier, Murata Manufacturing Co., Ltd. and TDK Corporation exemplify leadership in high-capacitance and miniaturized components, respectively. YAGEO Group, a Taiwan-based Co., Ltd., occupies a position as a broad-portfolio provider with a strong distribution channel presence. These firms anchor significant market share through their technological expertise and extensive product offerings across diverse applications.
| Leading Market Players |
|---|
| TAIYO YUDEN CO., LTD. |
| KYOCERA Corporation |
| Murata Manufacturing Co., Ltd. |
| Vishay Intertechnology, Inc |
| Walsin Technology Corporation |
| SAMSUNG ELECTRO-MECHANICS |
| TDK Corporation |
| Future Electronics |
| YAGEO Group |
| Others |
Cost & Logistics Intelligence
Automotive OEMs' multi-source procurement strategies reshape MLCC supply dynamics, compelling manufacturers to diversify capacity. This influences per-unit pricing for high-reliability components, aiming to mitigate supply chain risks.
Pricing Analysis
Raw material cost fluctuations, particularly for palladium, often lead to direct pass-through mechanisms in MLCC pricing. The dominant pricing model is a per-unit transactional structure, frequently secured through contract-based long-term offtake agreements for critical components. Price differentiation stems from AEC-Q200 certification levels and manufacturer brand premiums, such as those commanded by Murata. Pricing softness reflects volatility in raw material costs, while consumer electronics buyers exhibit the highest price sensitivity compared to automotive customers.
Supply Chain Analysis
Reverse logistics are minimal in the MLCC market due to the low value-to-volume ratio of individual components and the high cost of testing used parts. Geographic supply concentration for high-performance MLCCs centers heavily in Japan and South Korea. The industry draws from key raw materials like palladium and specialized dielectric ceramic formulations. Single-source vulnerability for advanced components presents a significant supply chain risk. Distribution runs through a combination of direct sales to large OEMs and a network of electronic component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MLCC market acts as a regulatory compounder, with AEC-Q200 stress test qualification in the United States driving demand for high-reliability components. This standard elevates entry barriers and reinforces product quality across the automotive segment.
For Market Incumbents:Anticipate continued raw material price volatility by deepening vertical integration into key material sourcing. Incumbents should prioritize continuous capital investment in advanced manufacturing capacity, particularly for high-capacitance components, to counter technical scaling limits. Investing in material science R&D for next-generation dielectric formulations and maintaining stringent AEC-Q200 certification standards will defend market share against emerging entrants.
For New Entrants and Emerging Players:REACH regulations in Europe open a window for new entrants focusing on compliant and specialized material solutions. Target high-margin white spaces like medical device applications or industrial IoT, where exceptional reliability and specific certifications are paramount. Focusing on Base Metal Electrode (BME) technology offers a cost-competitive entry point, particularly for specialized industrial applications. A go-to-market strategy should emphasize robust performance verification and application-specific engineering support.
For Investors and Strategic Acquirers:Asymmetric upside sits with mid-cap specialists possessing proprietary material science or advanced manufacturing capabilities. The long-term viability of the MLCC market, driven by automotive electrification and 5G infrastructure, supports strategic investments over the next decade. Target acquisition profiles include firms specializing in advanced dielectric ceramic formulations or Base Metal Electrode (BME) technology. Monitor the increasing adoption rate of BME capacitors in automotive-grade applications for inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Japan/South Korea | Secures supply for high-performance automotive and 5G segments. |
| Advanced Dielectric R&D | Increases capacitance density and thermal stability for next-gen MLCCs. |
| BME Technology Investment | Reduces dependence on volatile precious metals, lowering production costs. |
| AEC-Q200 Certification Pursuit | Unlocks higher-margin opportunities within the demanding automotive sector. |
| Multi-Source Material Procurement | Mitigates supply chain risks from raw material price volatility. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, validating market dynamics. Primary insights came from MLCC product managers, automotive engineers, and material scientists. Secondary validation utilized corporate annual reports, industry association publications, and trade statistics from Japan's METI. This approach ensured robust bottom-up and top-down triangulation of market figures.
Segment-weighting formed the core analytical framework, modeling market evolution across the analysis window. Dimensions included product types (X7R, C0G), applications (automotive, consumer electronics), end-users, and regional manufacturing capacity. Compound Annual Growth Rates derived from historical trends and projected demand drivers. Electric vehicle production forecasts and 5G infrastructure deployment rates were vital inputs.
Revisions become necessary when significant raw material supply disruptions or geopolitical shifts affecting trade materialize. Forecasts reflect assumptions based on current market structures and technological trajectories. Practitioners should monitor global economic stability and material science breakthroughs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market