
 Discrete Diodes Market | 2026-2036
Discrete Diodes Market Size, Share, and Industry Trends Forecast 2026-2036
Discrete Diodes Market Analysis
Automotive OEMs is reorganizing demand patterns away from traditional consumer electronics buyers as electric vehicle production scales. Infineon Technologies AG anchors its position through captive silicon carbide substrate capacity and power module integration. Vishay Intertechnology specializes in high-reliability rectifier diodes for industrial and aerospace qualification tiers. ROHM Semiconductor leads wide-bandgap device development with vertically controlled GaN epitaxy operations in Japan.
Discrete diodes are two-terminal semiconductor devices that permit current flow in one direction while blocking reverse voltage, typically fabricated from silicon, gallium arsenide, or wide-bandgap materials with breakdown ratings from sub-volt Zener levels to kilovolt rectifier classes. Their primary purpose spans AC-DC conversion, voltage clamping, signal demodulation, and circuit protection across electronic systems. Schottky diodes capture margin pools in high-frequency switching applications where low forward voltage drop determines system efficiency. Silicon carbide diodes represent the fastest-growing technology segment as 800V automotive architectures displace silicon super-junction alternatives in onboard chargers and traction inverters.
The US EPA and NHTSA coordinate emissions and fuel economy standards that indirectly mandate higher-efficiency power electronics in vehicle electrification programs. REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor packaging materials while CE marking governs electromagnetic compatibility for industrial diode modules. The EU AI Act and emerging product digital passport requirements under CSRD will reshape traceability obligations across diode supply chains. Stakeholders must monitor how evolving carbon border adjustments and semiconductor subsidy eligibility criteria in the US, EU, and China reshape cost-competitive sourcing for substrate and foundry capacity.
Market Dynamics
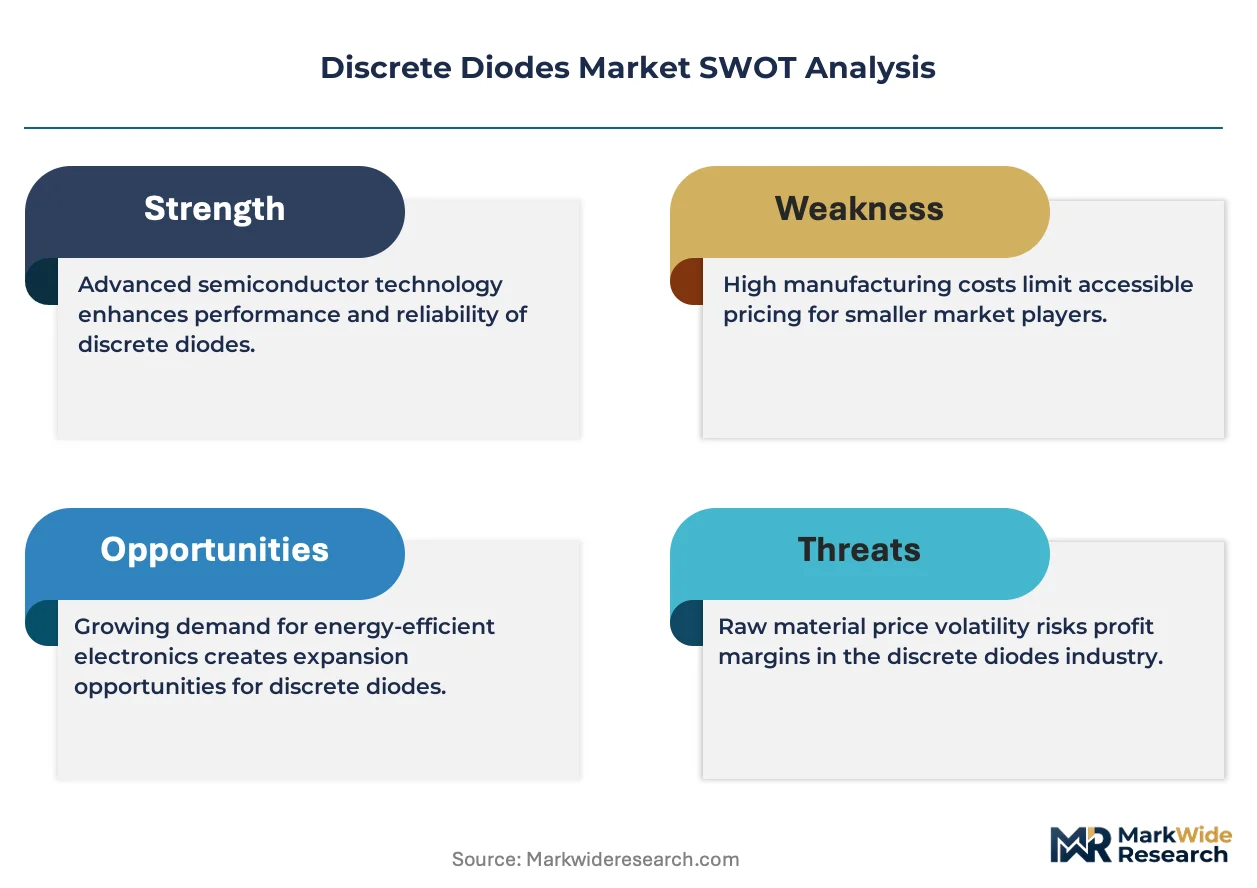
Automotive electrification is compressing qualification timelines for wide-bandgap discrete diodes while fragmenting procurement authority between OEM powertrain divisions and tier-one module suppliers.
Growth Catalysts
- China's dual carbon goals:GB standards for energy efficiency are accelerating domestic substitution of silicon carbide devices across industrial motor drives and renewable energy inverters.
- 800V automotive architectures:Electric vehicle platforms are mandating silicon carbide diodes for onboard chargers and traction inverters, pulling demand from silicon super-junction alternatives.
- East Asian manufacturing concentration:Semiconductor fabrication clusters spanning Japan, South Korea, and Taiwan provide captive substrate access and packaging integration for high-volume diode production.
Market Restraints
- Silicon carbide substrate scarcity:Limited 6-inch and emerging 8-inch wafer supply concentrates among Japanese and US material suppliers, constraining diode output expansion.
- REACH and RoHS compliance friction:European hazardous substance restrictions in semiconductor packaging materials extend qualification cycles and disqualify legacy lead-frame chemistries.
- Technical limitation in thermal management:Wide-bandgap diodes operating above 175°C require silver-sintering and advanced ceramic substrates that inflate module costs versus silicon alternatives.
Strategic Opportunities
- Underpenetrated renewable energy storage:Grid-scale battery inverters in India and Southeast Asia present diode demand as domestic solar installation accelerates under national clean energy mandates.
- EU AI Act traceability requirements:Product digital passport obligations under CSRD will reshape supply chain documentation, favoring diode suppliers with embedded serialization and blockchain verification.
- GaN-SiC technology convergence:Hybrid power modules combining gallium nitride switches with silicon carbide diodes are opening new topologies in high-frequency DC-DC converters for data center power supplies.
Industry Challenges
- Wide-bandgap device engineering talent scarcity:Specialized epitaxy and defect characterization expertise concentrates among Japanese and US research institutions, constraining foundry expansion.
- AEC-Q101 certification timeline compression:Automotive qualification protocols requiring 1,000-hour high-temperature reverse bias testing create 18-24 month product introduction cycles that lag vehicle platform development.
- Legacy silicon diode inventory absorption:Tier-two distributors and contract manufacturers face write-down pressure as OEMs enforce technology roadmaps excluding standard rectifiers from new designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Discrete Diodes Market |
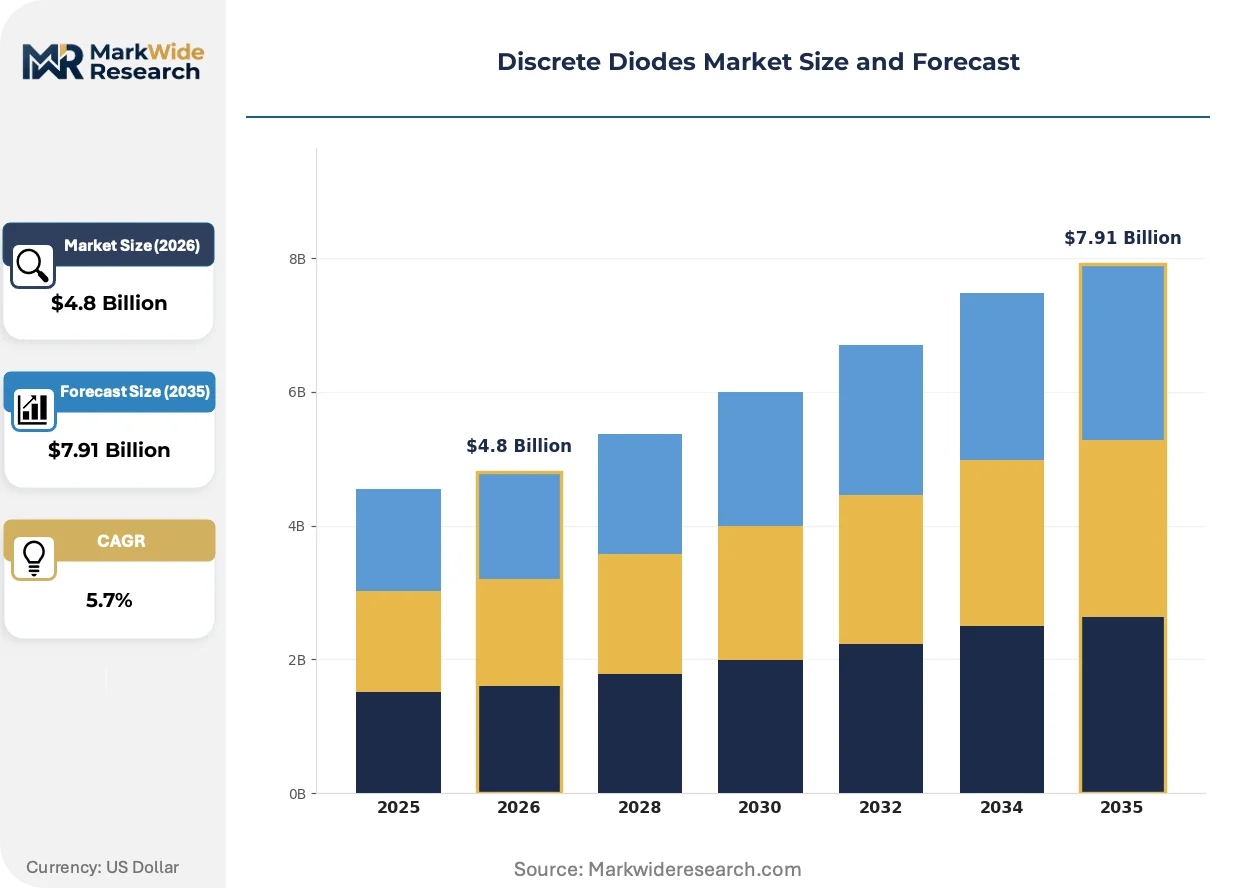
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Diodes, Zener Diodes, Schottky Diodes, Rectifier Diodes Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Equipment Technology: Silicon Diodes, Gallium Nitride Diodes, Silicon Carbide Diodes, Organic Diodes End User: OEMs, Aftermarket Providers, Distributors, Retailers |
| Companies Covered | Vishay Intertechnology, NXP Semiconductors, Infineon Technologies AG, ROHM Semiconductor, Toshiba Electronic Devices & Storage Corporation, STMicroelectronics, ON Semiconductor, Texas Instruments, Diodes Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Discrete Diodes Market Emerging Trajectories
Silicon carbide diode technology is compressing form factors while elevating thermal performance, forcing packaging roadmaps and procurement specifications to synchronize around material constraints rather than silicon legacy.
Gallium nitride Schottky barrier diodes is miniaturizing into sub-millimeter chip-scale packages for smartphone fast-charging adapters and laptop power bricks. Consumer electronics OEMs in Taiwan and South Korea are qualifying these devices for 65W-140W USB-C applications. The shift is compressing magnetic component sizes and enabling foldable plug geometries that silicon alternatives cannot support thermally.
The US EPA and NHTSA coordinated emissions standards are indirectly mandating higher-efficiency power electronics through vehicle electrification program requirements. Tier-one automotive suppliers must now document diode efficiency contributions to overall powertrain energy recovery. This regulatory pressure is disqualifying standard recovery rectifiers from traction inverter designs and accelerating silicon carbide qualification.
Automotive OEMs are consolidating diode procurement under powertrain division authority rather than distributed commodity purchasing. Tier-one module suppliers in Germany and Japan are responding with co-development contracts specifying diode electrical and thermal performance jointly. This behavioral shift is most visible in 800V platform programs where diode selection occurs 36 months ahead of production versus 18 months under legacy silicon programs.
Discrete Diodes Market Segmentation
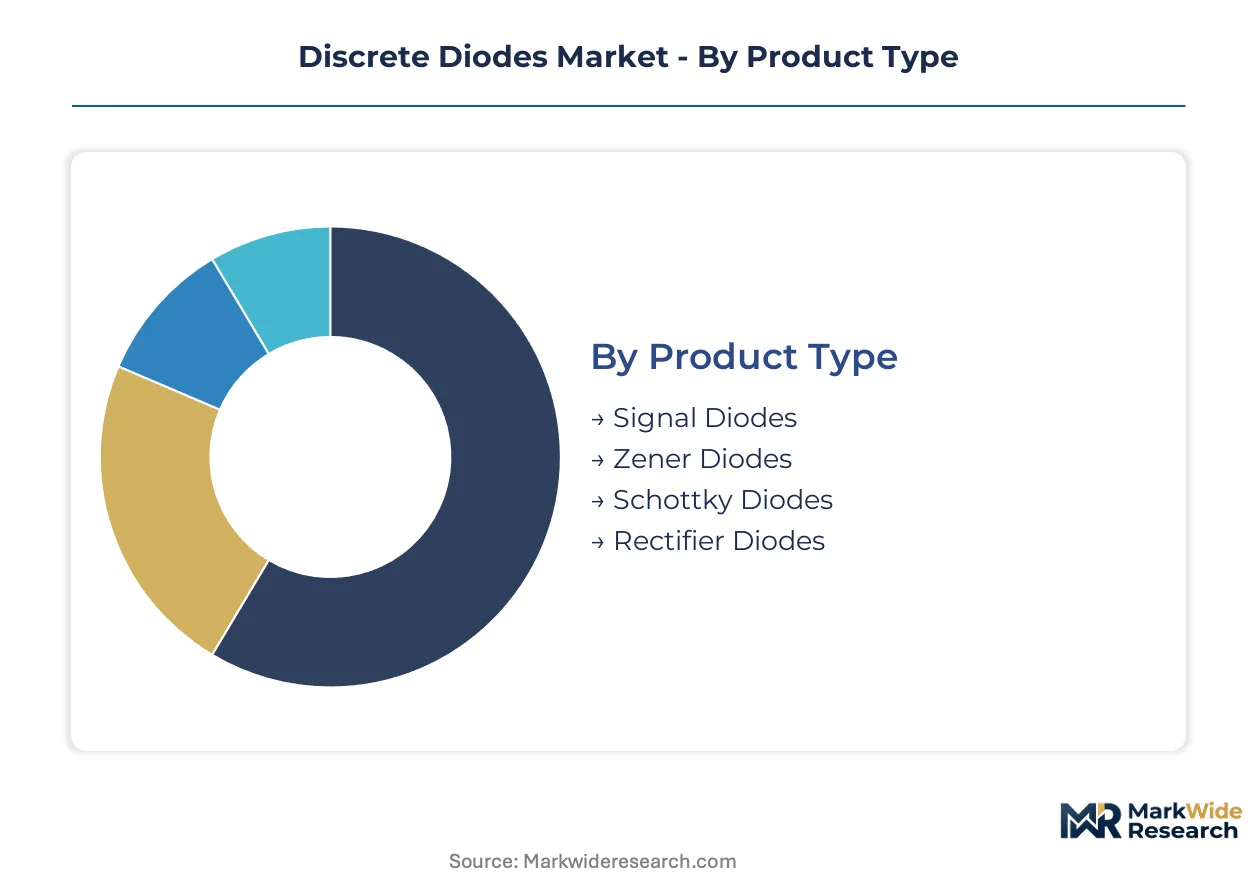
Discrete diode procurement patterns diverge sharply across end-use verticals, with automotive powertrain specifications now overriding consumer electronics volume economics. Technology substitution pressures and qualification tier requirements reshape how suppliers allocate wafer capacity and packaging resources across segment boundaries.
Product Type:
Schottky and rectifier variants face the most intense substitution pressure as wide-bandgap alternatives capture high-efficiency sockets, while signal and Zener diodes defend legacy positions through cost minimization and established qualification databases.
- Schottky Diodes:Metal-semiconductor junction devices deliver sub-0.5V forward voltage drop for high-frequency switching applications. Data center power supplies in Taiwan and South Korea specify these for 48V rail conversion where magnetic component size reduction justifies premium pricing over silicon alternatives.
- Rectifier Diodes:Silicon p-n junction devices handle AC-DC conversion across industrial motor drives and grid-tied inverters. China's GB standards for motor efficiency are accelerating displacement of standard recovery rectifiers by silicon carbide alternatives in variable frequency drives above 75kW.
- Signal Diodes:Small-signal switching devices for RF and logic isolation in consumer electronics assemblies. Japanese OEMs specify these for smartphone antenna tuning circuits where package size and parasitic capacitance dominate selection criteria.
- Zener Diodes:Reverse-bias voltage reference and clamping devices with tight tolerance bands. Industrial automation suppliers in Germany source these for PLC input protection modules requiring AEC-Q101-grade reliability.
Rectifier diodes retain volume leadership across industrial and consumer installations; Schottky variants hold the steepest expansion curve in data center and telecommunications rectification.
Application:
Automotive electronics commands the highest qualification tier and longest product lifecycles, while consumer electronics volumes concentrate in East Asian contract manufacturing clusters with compressed development cycles.
- Automotive Electronics:Onboard chargers, traction inverters, and DC-DC converters specify wide-bandgap diodes for 800V architectures. Tier-one module suppliers in Germany and Japan now require 36-month advance diode qualification versus 18 months under legacy silicon programs.
- Consumer Electronics:Smartphone fast-charging adapters and laptop power bricks drive miniaturization demands. Taiwanese and South Korean OEMs qualify gallium nitride Schottky barrier diodes for 65W-140W USB-C applications where foldable plug geometries require thermal performance silicon cannot match.
- Telecommunications:Base station power amplifiers and optical transceivers specify high-frequency switching diodes. 5G infrastructure deployment in Japan and South Korea is pulling demand for low-capacitance signal diodes in massive MIMO antenna arrays.
- Industrial Equipment:Motor drives, welding equipment, and uninterruptible power supplies require high-current rectification. India's renewable energy mandates are expanding diode demand for grid-scale solar inverters and battery energy storage systems.
Consumer electronics maintains shipment volume dominance; automotive electronics generates the fastest share gain as electrification programs scale.
Technology:
Silicon carbide and gallium nitride technologies are climbing the cost-performance curve fastest, while silicon diodes defend massive replacement markets and organic diodes remain confined to experimental flexible electronics.
- Silicon Carbide Diodes:Wide-bandgap devices with 10x higher breakdown field strength than silicon, enabling thinner drift layers and reduced switching losses. 800V electric vehicle platforms in Germany, Japan, and the United States specify these for onboard chargers and traction inverters.
- Gallium Nitride Diodes:Heterostructure devices with superior electron mobility for megahertz-frequency switching. South Korean consumer electronics OEMs integrate these into smartphone adapters where magnetic component miniaturization enables foldable plug designs.
- Silicon Diodes:Mature p-n junction technology with lowest unit cost and broadest supplier base. Legacy industrial motor drives and consumer appliances in China and Southeast Asia continue specification for standard recovery and fast recovery variants.
- Organic Diodes:Carbon-based semiconductor devices for flexible and printable electronics applications. Japanese research consortia pilot these for wearable health monitors and curved display backplanes where mechanical compliance outweighs performance limitations.
Silicon diodes retain absolute volume leadership across replacement and cost-sensitive new designs; silicon carbide technology captures the steepest expansion trajectory in automotive and renewable energy power conversion.
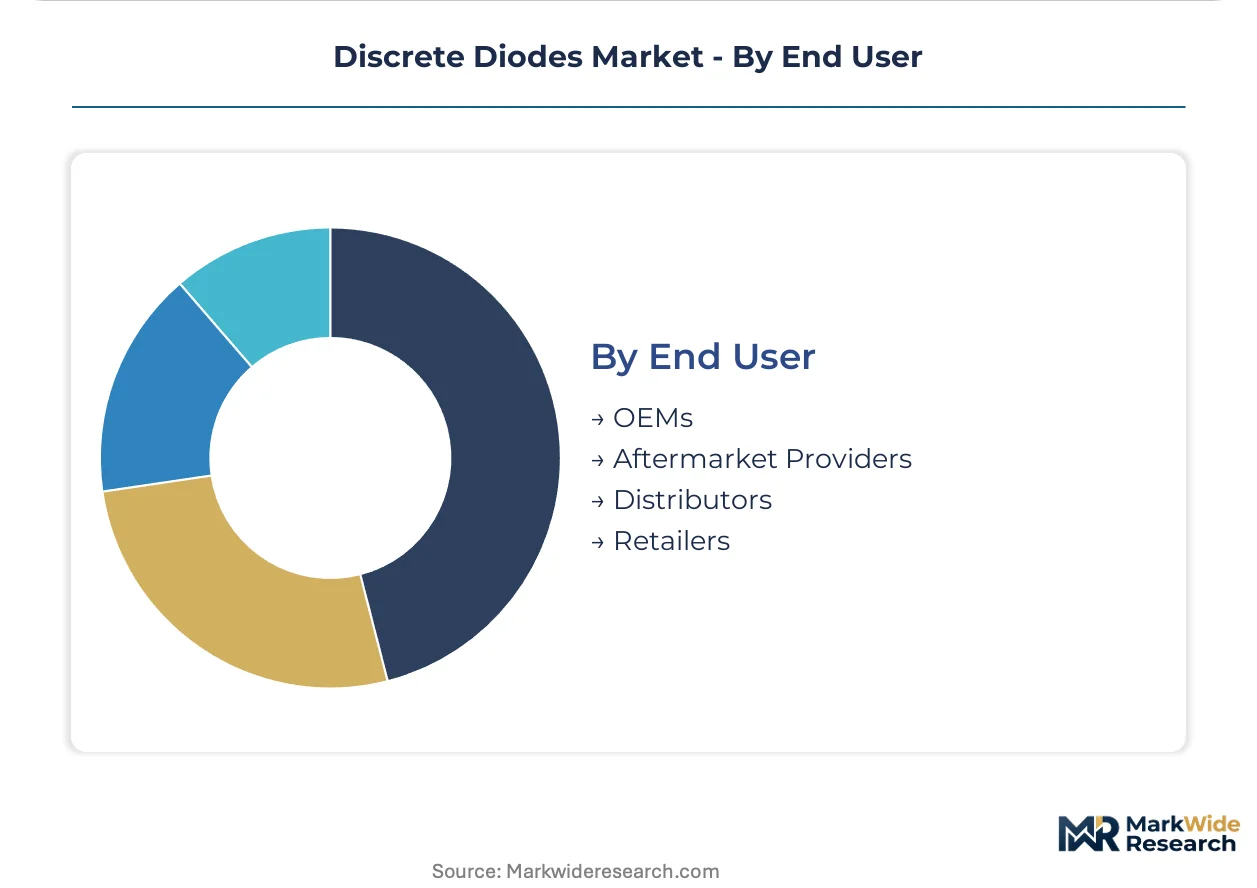
End User:
OEMs consolidate procurement authority under powertrain and product divisions, while aftermarket providers and distributors face margin compression from technology roadmap enforcement and inventory obsolescence risks.
- OEMs:Original equipment manufacturers in automotive, consumer electronics, and industrial sectors specify diodes at platform design inception. German and Japanese automotive OEMs now mandate silicon carbide diode qualification 36 months ahead of production start.
- Distributors:Authorized and independent channels manage inventory and technical support for mid-volume customers. Tier-two distributors face write-down pressure as OEMs enforce roadmaps excluding standard rectifiers from new designs.
- Aftermarket Providers:Replacement part suppliers service legacy equipment with established silicon diode specifications. Industrial maintenance organizations in the United States and Europe source these for motor drive refurbishment where wide-bandgap retrofit economics remain unfavorable.
- Retailers:Consumer-facing channels for discrete component sales to hobbyists and small-scale manufacturers. Online platforms in China and India aggregate demand for standard diode assortments in kit and bulk packaging formats.
OEMs concentrate value capture through early design involvement; distributors defend position through inventory availability and application engineering support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yokohama-Yokkaichi industrial corridor anchors Japan's silicon carbide substrate fabrication, underwriting East Asian supply security for automotive-grade discrete diodes. This infrastructure asset positions the archipelago as a critical node in wide-bandgap semiconductor logistics.
China
Domestic electric vehicle production exceeding six million units annually pulls silicon carbide diode demand through BYD and NIO supply chains. MIIT's GB standards for motor efficiency mandate wide-bandgap adoption in industrial drives above 75kW. The Yangtze River Delta cluster around Shanghai concentrates epitaxy capacity expansion as local foundries scale 6-inch SiC wafer output.
Germany
BMW and Volkswagen 800V platform programs compress diode qualification timelines to 36 months ahead of production start. KBA type-approval protocols for electromagnetic compatibility govern power module integration standards. Bavaria's Munich-Ingolstadt corridor hosts tier-one module suppliers co-developing diode specifications directly with OEM powertrain divisions.
United States
Tesla's Nevada Gigafactory and Rivian's Illinois operations specify silicon carbide diodes for traction inverters at volume scale. EPA-NHTSA coordinated emissions standards indirectly mandate higher-efficiency power electronics through vehicle electrification mandates. The Research Triangle Park in North Carolina anchors wide-bandgap device engineering talent pools for defect characterization expertise.
South Korea
Hyundai-Kia's E-GMP platform and Samsung SDI battery integration drive diode demand for onboard chargers at 800V architecture. MFDS certification frameworks for automotive electronics govern reliability testing protocols. The Seoul Capital Area concentrates gallium nitride Schottky barrier diode qualification for smartphone fast-charging adapters in 65W-140W USB-C applications.
Japan
Toyota's solid-state battery roadmap and Subaru's electric crossover programs specify silicon carbide diodes for next-generation powertrains. METI's semiconductor subsidy programs under the Economic Security Promotion Act fund domestic SiC substrate capacity expansion. The Kyushu region's Kumamoto prefecture hosts ROHM Semiconductor's vertically controlled GaN epitaxy operations serving consumer electronics OEMs.
Discrete Diodes Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and substrate supply dimensions, creating a tiered structure where scale advantages clash with niche qualification expertise. The vendor base concentrates among integrated device manufacturers with captive wafer capacity and fabless specialists relying on foundry partnerships. Three archetypes dominate: diversified conglomerates with materials-to-modules vertical control, discrete component pure-plays emphasizing reliability certifications, and wide-bandgap technology specialists with epitaxy operations. Capacity expansion and strategic co-development contracts with automotive OEMs represent the dominant competitive moves reshaping procurement relationships.
Among European-integrated device manufacturers, Infineon Technologies AG anchors the premium tier through captive silicon carbide substrate production in Villach. Vishay Intertechnology exemplifies the high-reliability pure-play archetype with industrial and aerospace qualification focus. ROHM Semiconductor occupies a distinct position within Japanese wide-bandgap specialists through vertically controlled gallium nitride epitaxy operations. These three entities represent contrasting strategic postures: backward integration into materials, certification-tier specialization, and upstream control over compound semiconductor growth processes.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| NXP Semiconductors |
| Infineon Technologies AG |
| ROHM Semiconductor |
| Toshiba Electronic Devices & Storage Corporation |
| STMicroelectronics |
| ON Semiconductor |
| Texas Instruments |
| Diodes Incorporated |
| Others |
Supply Flow & Price Mechanics
Six-inch silicon carbide wafer utilization rates above 85 percent in Japanese and Taiwanese foundries create asymmetric pricing power for substrate suppliers, compressing margins for diode packagers while elevating entry barriers for second-tier module integrators. This scale concentration forces automotive OEMs into 36-month qualification contracts that lock volume commitments against spot-market volatility, while consumer electronics buyers absorb premium pricing for gallium nitride Schottky devices where magnetic miniaturization justifies cost.
Pricing Analysis
Three-tier pricing structure across AEC-Q101 automotive, industrial-grade, and consumer-tier certification levels separates qualification-intensive powertrain sockets from commodity replacement markets. Price differentiation hinges on thermal cycling test duration and substrate defect density grades, with automotive contracts commanding 40-60 percent premiums over industrial equivalents. Cost compression in consumer-grade silicon rectifiers is intensifying because Chinese foundries are absorbing legacy 8-inch silicon capacity into price-competitive export bundles. Tier-two distributors and contract manufacturers exhibit highest price sensitivity, while German and Japanese automotive OEMs prioritize qualification timeline certainty over unit cost negotiation.
Supply Chain Analysis
Strategic stockpiling of silicon carbide substrates among Japanese and German tier-one module suppliers contrasts with just-in-time inventory practices in Taiwanese consumer electronics contract manufacturers. Geographic supply concentration centers on Japan for SiC substrate fabrication, Taiwan for gallium nitride epitaxy, and China for silicon diode packaging integration. Raw material dependencies include high-purity silicon carbide powder from US and Japanese chemical suppliers, silver-sintering pastes for thermal interface layers, and ceramic substrate materials from Kyocera and CoorsTek operations. Single-source vulnerability concentrates in 6-inch SiC wafer supply from Wolfspeed and Showa Denko facilities. Distribution runs through authorized distributors for automotive qualification support, with spot-market brokers handling surplus consumer-grade inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Discrete diode procurement is consolidating around 800V automotive platform ecosystems where interoperability specifications between onboard chargers and traction inverters lock suppliers into multi-year co-development cycles, transforming component supply into embedded system partnerships.
For Market Incumbents: Compound defensive moats by securing captive silicon carbide substrate capacity through long-term offtake agreements with Japanese material suppliers, while accelerating AEC-Q101 qualification database expansion to disqualify emerging wide-bandgap entrants from automotive sockets. Vertical integration into silver-sintering packaging processes addresses thermal management limitations that threaten silicon carbide diode reliability above 175°C operating junctions. For New Entrants and Emerging Players: Anchor in India's grid-scale solar inverter and battery energy storage system markets where domestic content requirements under national clean energy mandates create procurement preferences for local diode assemblers. Target industrial motor drive refurbishment segments above 75kW where GB standard compliance in Chinese manufacturing exports creates pull-through demand for silicon carbide retrofit modules. Pursue qualification partnerships with German tier-one module suppliers seeking second-source diode options for 800V platform risk mitigation. For Investors and Strategic Acquirers: Fabless wide-bandgap design houses with proven GaN epitaxy process IP and existing automotive qualification timelines represent the most defensible acquisition archetype for portfolio exposure to electrification-driven demand inflection. Long-term viability hinges on substrate supply contract duration and foundry partnership exclusivity terms rather than device performance specifications alone. Watch for silicon carbide substrate spot price volatility crossing 20 percent quarterly swings as the inflection signal for supply-constrained margin expansion opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Substrate Capacity Expansion | Infineon's Villach facility eliminates foundry dependency for automotive-grade diode supply security. |
| AEC-Q101 Qualification Database Investment | Vishay's aerospace reliability heritage transfers to automotive 1000-hour HTRB test requirements. |
| GaN-SiC Hybrid Module Co-Development | ROHM's epitaxy operations enable data center DC-DC converter topology innovation with Samsung. |
| Silver-Sintering Packaging Process Integration | Advanced ceramic substrate bonding addresses 175°C+ thermal management cost inflation in traction inverters. |
| India Solar Inverter Localization Partnership | Domestic content mandates under national renewable energy targets create captive demand for diode assemblers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, MIIT GB standard publications, and automotive OEM powertrain procurement disclosures. Primary interviews engaged semiconductor fabrication executives, tier-one module supplier procurement directors, and wide-bandgap device engineering specialists across Japan, Germany, and the United States. Secondary validation drew from EPA-NHTSA coordinated rulemaking documents, METI semiconductor subsidy program filings, and REACH/RoHS regulatory guidance from ECHA. Bottom-up segment sizing triangulated against top-down wafer capacity utilization data from Japanese and Taiwanese foundry disclosures.
Segmentation dimensions modeled include product type taxonomy, application vertical qualification tiers, technology material systems, and end-user procurement authority structures across the projection horizon. Analytical framework derived CAGRs through supply-side capacity expansion trajectories and demand-side platform adoption curves for 800V automotive architectures and renewable energy inverter deployments. Industry-specific forecast inputs incorporated silicon carbide substrate yield improvement assumptions and gallium nitride epitaxy defect density progression rates.
Material uncertainties — substrate supply disruptions, REACH packaging material restriction amendments, and automotive platform timeline accelerations — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained electrification policy coordination between EPA, NHTSA, and MIIT regulatory frameworks. Revision becomes warranted when silicon carbide substrate spot pricing volatility exceeds quarterly bandwidth thresholds or when AEC-Q101 qualification timelines compress below 24 months.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market