
 Pcs and Laptops MLCC Market | 2026-2036
Pcs and Laptops MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
Pcs and Laptops MLCC Market Insights
Automotive-grade reliability specifications are rotating into consumer PC and laptop designs as OEMs extend product lifecycles and warranty terms. Murata Manufacturing Co Ltd leverages its ceramic formulation expertise to supply high-voltage MLCCs for CPU VRM stages in premium notebooks. Samsung Electro-Mechanics anchors the Korean supply chain with captive tantalum capacitor production for gaming laptop motherboards. Taiyo Yuden Co Ltd specializes in ultra-small case-size components that enable thinner ultrabook form factors.
Multilayer ceramic capacitors for PCs and laptops are passive electronic components constructed from alternating layers of ceramic dielectric and metal electrodes, typically achieving capacitance values from picofarads to microfarads with voltage ratings up to 50V for consumer computing applications. These components stabilize DC power rails, filter high-frequency noise, and decouple transient loads from central processors and memory subsystems. Multilayer ceramic capacitors maintain dominant volume share across product types due to their superior frequency response and miniaturization trajectory, while OEM procurement channels command tighter qualification cycles than distributor or retailer segments. Passive component technology classifications attract the bulk of computing sector demand, though automotive-grade dielectric formulations are crossing into commercial-grade specifications as reliability benchmarks converge.
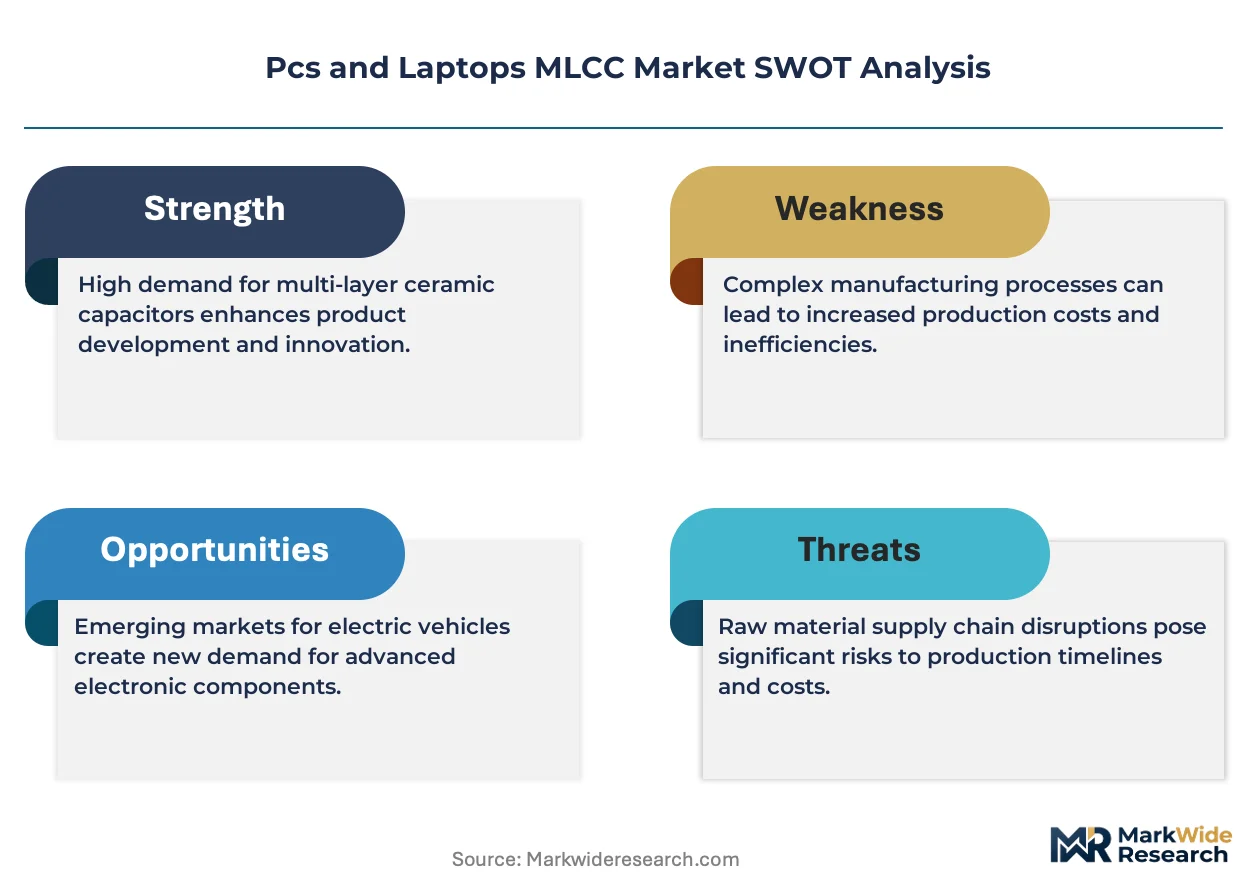
FCC electromagnetic compatibility mandates in the United States and EU RoHS substance restrictions in Europe constrain lead-free solder compatibility and halogen-free material selection across MLCC supply chains. China's GB standards for electronic component environmental labeling add compliance layers for ceramic raw material sourcing and electrode metallurgy. REACH registration requirements in Europe further govern nickel and tin electrode compositions used in high-volume consumer computing capacitors. Stakeholders must track how evolving dielectric material regulations and OEM sustainability scorecards reshape supplier qualification criteria and component substitution timelines.
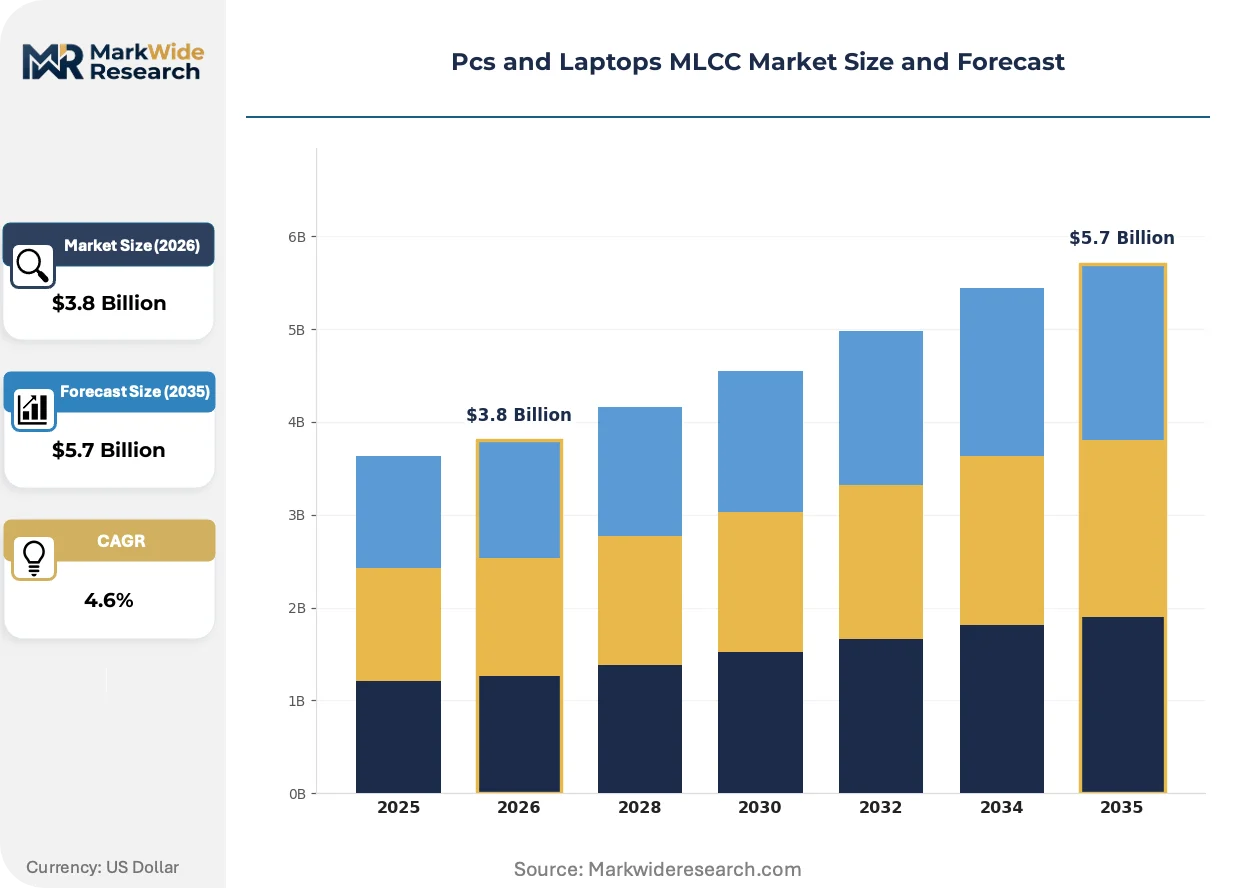
Market Dynamics
Discrete GPU power delivery requirements in gaming laptops are forcing MLCC suppliers to reconfigure dielectric formulations for higher capacitance density per square millimeter, compressing traditional ceramic layer geometries beyond established reliability thresholds.
Growth Catalysts
- High-capacitance MLCC arrays:Gaming laptop manufacturers are expanding procurement of these components to stabilize voltage rails under transient GPU loads, pulling dielectric technology toward automotive-grade specifications.
- China's NMPA-aligned environmental standards:Tightening material purity requirements for ceramic dielectrics are accelerating supplier qualification cycles and favoring vertically integrated ceramic powder processors.
- South Korea's semiconductor packaging corridor:Dedicated MLCC fabs operated by major suppliers for computing clients concentrate demand and enable just-in-time delivery to motherboard assembly lines.
Market Restraints
- Raw material concentration:High-purity barium titanate ceramic powder supply concentrates among Japanese and Chinese chemical processors, exposing MLCC manufacturers to input cost volatility and geographic supply risk.
- Dielectric thickness limitations:Sub-micron ceramic layer deposition yields degrade below 0.5 micrometers, capping capacitance density gains for standard consumer-grade voltage ratings.
- EU RoHS substance restrictions:Lead-free solder compatibility mandates constrain electrode metallurgy choices, eliminating certain high-conductivity alloys from high-frequency computing applications.
Strategic Opportunities
- India's electronics manufacturing incentives:PLI scheme subsidies for component localization create greenfield fab opportunities for MLCC suppliers targeting laptop assembly migration from coastal China.
- AI inferencing at the edge:Neural processing unit integration in premium notebooks demands ultra-stable power delivery, opening high-reliability dielectric specifications previously reserved for automotive.
- Direct OEM contracting:Bypassing distributor markups through long-term supply agreements with Dell, HP, and Lenovo procurement divisions captures margin and locks in volume commitments.
Industry Challenges
- Thin-film deposition talent scarcity:Process engineers skilled in atomic layer deposition for sub-micron dielectrics command premium compensation, constraining production ramp rates at new facilities.
- Automotive-grade certification timelines:AEC-Q200 qualification cycles extend 18-24 months, delaying cross-application technology transfer from consumer computing to adjacent high-reliability markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pcs and Laptops MLCC Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer Ceramic Capacitors, Tantalum Capacitors, Aluminum Electrolytic Capacitors, Film Capacitors End User: Manufacturers, OEMs, Distributors, Retailers Size: Small, Medium, Large, Extra Large Technology: Passive Components, Active Components, Automotive Grade, Commercial Grade |
| Companies Covered | Murata Manufacturing Co Ltd, TDK Corporation, Samsung Electro-Mechanics, Taiyo Yuden Co Ltd, Yageo Corporation, Vishay Intertechnology Inc, Kyocera AVX Components Corporation, Walsin Technology Corporation, Samwha Capacitor Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pcs and Laptops MLCC Market Trends and Innovations
Dielectric material science and procurement contracting models are simultaneously evolving, compressing supplier margins while enabling thinner laptop form factors and extended warranty coverage.
Ultra-small case-size MLCCs are fragmenting the traditional 0603 and 0402 component footprints into 0201 and 01005 dimensions. Ultrabook manufacturers are adopting these formats aggressively to reclaim PCB real estate for battery expansion. This dimensional compression is fragmenting supplier capabilities, separating vendors with precision thin-film expertise from legacy thick-film producers.
REACH registration requirements in Europe are tightening disclosure obligations for nickel and tin electrode compositions used in high-volume consumer computing capacitors. ECHA substance evaluations now demand full supply chain transparency for ceramic raw material sourcing. Notebook OEMs with European distribution footprints are responding by pre-qualifying halogen-free, full-disclosure dielectric formulations ahead of regulatory deadlines.
Computing OEMs are consolidating MLCC procurement through centralized commodity management teams rather than distributed motherboard design groups. This concentration transfers pricing leverage to volume buyers and compresses approved vendor lists to three-to-five strategic suppliers. The shift is most visible in Taiwan and South Korea, where ODMs like Quanta and Compal negotiate master supply agreements covering multiple laptop brand customers simultaneously.
Pcs and Laptops MLCC Market Segmentation
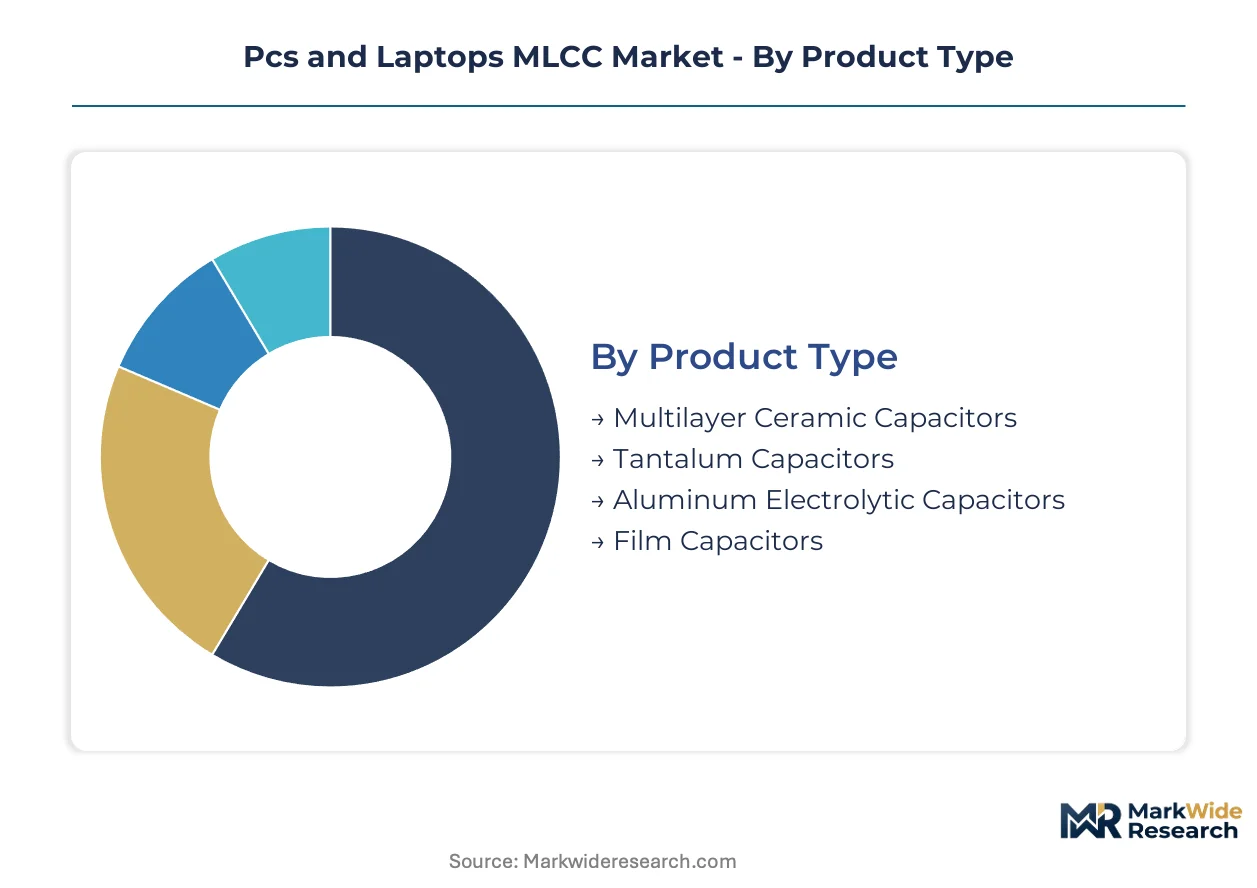
Component substitution pressures and procurement channel consolidation reshape how MLCC suppliers allocate capacity across dielectric formulations and case-size portfolios. Understanding segment-level demand drivers enables manufacturers to prioritize qualification investments and align production mix with motherboard design evolution.
Product Type:
Film capacitors and aluminum electrolytic variants exert substitution pressure on ceramic solutions in high-ripple current applications, though miniaturization trends favor MLCCs in space-constrained laptop motherboards.
- Multilayer Ceramic Capacitors:These components stack alternating ceramic dielectric and metal electrode layers to achieve picofarad-to-microfarad capacitance with voltage ratings up to 50V. Gaming laptop discrete GPU power delivery concentrates demand in South Korea's semiconductor packaging corridor, where Samsung Electro-Mechanics operates dedicated fabs for computing clients.
- Tantalum Capacitors:Constructed from porous tantalum anodes with manganese dioxide or polymer cathodes, these deliver high volumetric efficiency for bulk decoupling. Samsung Electro-Mechanics anchors Korean supply chains with captive tantalum production targeting gaming laptop motherboards requiring stable voltage rails under transient loads.
- Aluminum Electrolytic Capacitors:Rolled aluminum foil with electrolyte-soaked separators provides high capacitance at moderate cost for DC-link applications.
- Film Capacitors:Polypropylene or polyester dielectric films suit high-frequency filtering where low equivalent series resistance matters.
Multilayer Ceramic Capacitors retain volume leadership; Tantalum Capacitors hold the steepest expansion curve.
End User:
Procurement leverage concentrates with direct OEM contracting as centralized commodity management teams displace distributed motherboard design group purchasing.
- Manufacturers:Contract electronics manufacturers in Taiwan and South Korea negotiate master supply agreements covering multiple laptop brand customers simultaneously, transferring pricing leverage to volume buyers.
- OEMs:Dell, HP, and Lenovo procurement divisions drive long-term supply agreements that bypass distributor markups and compress approved vendor lists to three-to-five strategic suppliers.
- Distributors:Arrow Electronics and Avnet maintain inventory buffers for mid-tier ODMs lacking direct supplier relationships.
- Retailers:Aftermarket replacement demand channels command looser qualification cycles than production procurement.
OEMs dominate procurement value; Manufacturers capture the highest transaction velocity.
Size:
Dimensional compression toward 0201 and 01005 footprints fragments supplier capabilities between precision thin-film specialists and legacy thick-film producers.
- Small:0201 and 01005 case sizes enable ultrabook manufacturers to reclaim PCB real estate for battery expansion. Taiyo Yuden specializes in these ultra-small components that support thinner form factors in premium notebook designs.
- Medium:0402 and 0603 footprints remain standard for mainstream laptop motherboards where assembly yield and reworkability balance density requirements.
- Large:0805 and 1206 dimensions persist in power delivery stages requiring higher ripple current handling.
- Extra Large:Specialized footprints above 1210 serve bulk decoupling in discrete GPU voltage regulator modules.
Medium sizes retain volume leadership; Small sizes gain share fastest.
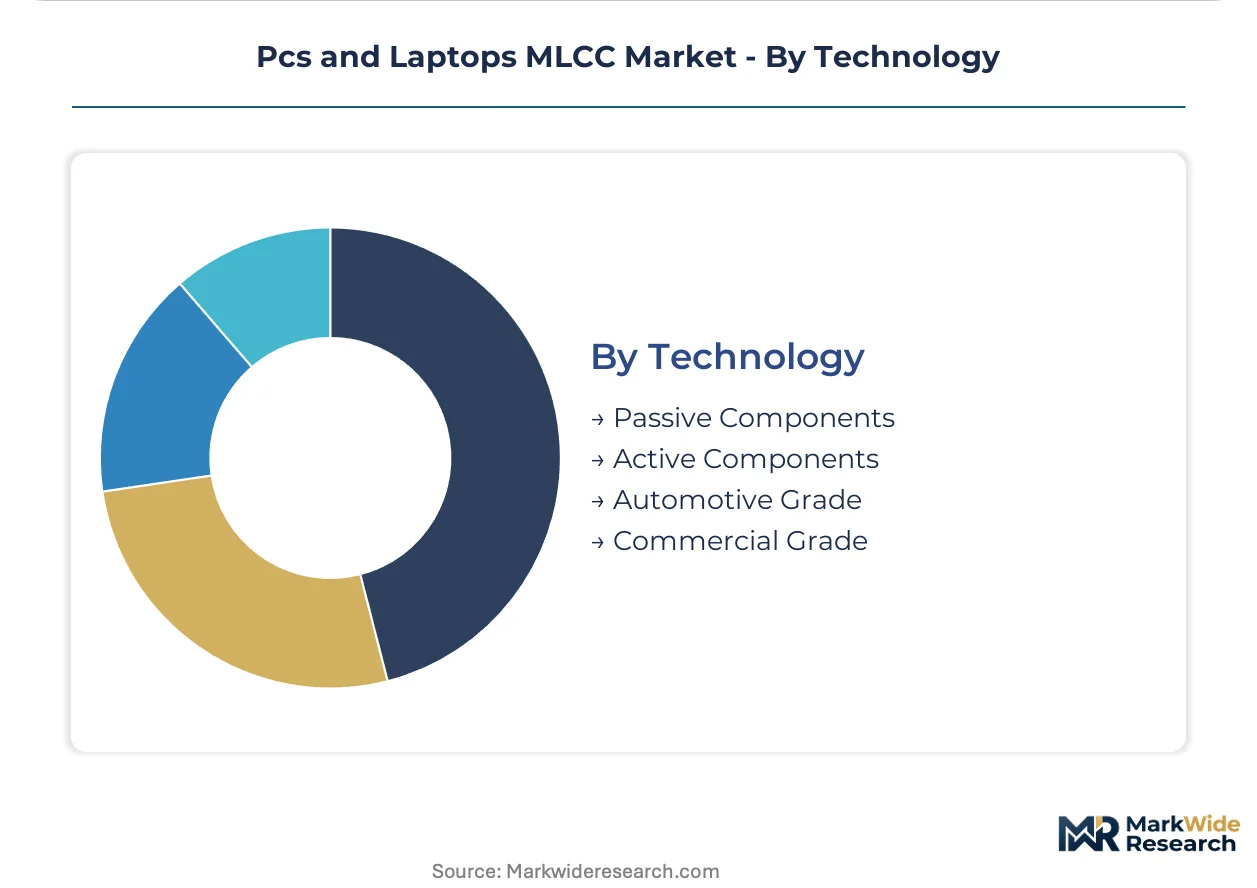
Technology:
Automotive-grade dielectric formulations are crossing into commercial-grade specifications as reliability benchmarks converge and OEMs extend product lifecycles.
- Passive Components:MLCCs, resistors, and inductors without semiconductor junctions constitute the dominant technology classification for computing sector demand.
- Active Components:Transistor-integrated capacitor arrays serve specialized voltage regulation functions in high-performance computing platforms.
- Automotive Grade:AEC-Q200 qualified dielectrics meet extended temperature and mechanical stress specifications. Murata Manufacturing leverages ceramic formulation expertise to supply high-voltage MLCCs for CPU VRM stages in premium notebooks requiring automotive-grade reliability.
- Commercial Grade:Standard temperature and voltage specifications serve cost-optimized consumer computing applications with shorter warranty terms.
Passive Components retain volume leadership; Automotive Grade holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for MLCCs in computing applications tilt toward net-import dependence in Western markets while East Asian economies maintain substantial trade surpluses in ceramic dielectric components. South Korea and Japan dominate outbound shipments of high-reliability capacitors for laptop motherboard assembly. China's NMPA-aligned environmental standards are reshaping regional sourcing patterns for ceramic raw materials.
South Korea
Samsung Electro-Mechanics anchors domestic demand through dedicated MLCC fabs serving gaming laptop discrete GPU power delivery requirements. The country's MFDS maintains alignment with international material purity standards for electronics manufacturing. Seoul Capital Area and Busan-Ulsan corridor concentrate motherboard assembly operations for Dell, HP, and Lenovo contract manufacturing.
Japan
Murata Manufacturing and Taiyo Yuden leverage ceramic formulation expertise to supply high-voltage MLCCs for premium notebook CPU VRM stages. METI industrial standards govern dielectric material specifications for consumer computing applications. Kansai/Osaka region hosts precision thin-film deposition facilities producing ultra-small 0201 and 01005 case-size components for ultrabook form factors.
China
Domestic laptop assembly migration toward inland provinces intensifies procurement of medium-case-size MLCCs for mainstream motherboard designs. NMPA-aligned environmental standards tighten material purity requirements for barium titanate ceramic powder processing. Yangtze River Delta and Pearl River Delta clusters concentrate ODM motherboard manufacturing for global PC brands.
United States
FCC electromagnetic compatibility mandates constrain lead-free solder compatibility for MLCC electrode metallurgy in devices sold domestically. EPA and OSHA frameworks govern chemical handling in electronics assembly operations. Pacific Northwest and Texas semiconductor corridors attract motherboard design centers though domestic MLCC fabrication remains limited.
Taiwan
Quanta and Compal negotiate master supply agreements covering multiple laptop brand customers through centralized commodity management teams. The country's national standards bureau aligns dielectric specifications with international computing industry requirements. Taipei-Hsinchu corridor concentrates ODM procurement leverage for global PC OEMs.
Pcs and Laptops MLCC Market Competitive Landscape
Concentration sits with diversified passive component conglomerates possessing captive ceramic powder processing capabilities. Japanese and South Korean suppliers command premium positioning through vertical integration into high-purity dielectric materials. Three archetypes define competitive positioning: integrated materials-to-components conglomerates, specialized high-frequency component fabricators, and scale-driven commodity producers. Capacity expansion in ultra-small case-size formats and strategic partnerships with Taiwan-based ODMs constitute dominant competitive moves.
Within the integrated conglomerate tier, Murata Manufacturing Co Ltd and TDK Corporation exemplify archetypes combining ceramic formulation expertise with global distribution reach. Samsung Electro-Mechanics anchors the Korean supply chain vector. Taiyo Yuden Co Ltd occupies a specialist position in dimensional compression technologies for premium notebook applications.
| Leading Market Players |
|---|
| Murata Manufacturing Co Ltd |
| TDK Corporation |
| Samsung Electro-Mechanics |
| Taiyo Yuden Co Ltd |
| Yageo Corporation |
| Vishay Intertechnology Inc |
| Kyocera AVX Components Corporation |
| Walsin Technology Corporation |
| Samwha Capacitor Group |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates above 85% at Japanese and South Korean MLCC fabs compress marginal cost curves and harden price floors for automotive-grade dielectric formulations crossing into consumer computing. This scale concentration grants integrated conglomerates pricing power over fragmented motherboard ODMs while forcing mid-tier suppliers toward commodity-grade commercial specifications.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure spanning premium AEC-Q200 qualified, standard commercial-grade, and economy unbranded tiers. Price differentiation rests on certification level and volume scale, with Dell, HP, and Lenovo procurement divisions extracting steepest discounts through consolidated master agreements. Cost compression in the economy tier is intensifying because Chinese domestic suppliers are expanding 0402 and 0603 case-size capacity for inland laptop assembly migration. Mid-tier ODMs lacking direct supplier relationships exhibit highest price sensitivity, while premium notebook OEMs prioritizing automotive-grade reliability show least sensitivity.
Supply Chain Analysis
Just-in-time inventory preferences dominate Taiwan and South Korea motherboard assembly corridors, though strategic stockpiling of high-purity barium titanate ceramic powder is emerging among Japanese suppliers hedging against China's NMPA-aligned environmental standard enforcement. Geographic supply concentrates in Japan, South Korea, and China, with raw material dependencies on high-purity barium titanate, nickel electrode metallurgy, and halogen-free epoxy coatings. Single-source vulnerability concentrates in Japanese ceramic powder processors controlling sub-micron dielectric formulations. Distribution runs through centralized commodity management teams at Quanta and Compal bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component-level warranty extension services and predictive failure analytics subscriptions are expanding faster than hardware shipment volumes, creating attach-rate opportunities for suppliers capable of integrating dielectric health monitoring into motherboard designs.
For Market Incumbents: Secure captive supply of high-purity barium titanate through backward integration or long-term offtake agreements with Japanese chemical processors, insulating against China's tightening material purity requirements. Deepen AEC-Q200 certification pipelines to defend against emerging Chinese suppliers offering commercial-grade alternatives at compressed margins. Prioritize ultra-small case-size capacity additions in the Kansai/Osaka corridor to serve ultrabook form factor compression. For New Entrants and Emerging Players: Lead with India's PLI scheme subsidies for component localization, targeting laptop assembly migration from coastal China toward greenfield fab opportunities in the subcontinent. The most penetrable segment sits in medium-case-size commercial-grade MLCCs for mainstream notebook motherboards where qualification cycles remain shorter than automotive-grade alternatives. Pursue direct OEM contracting bypassing established distributor relationships through volume guarantees and localized technical support. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision thin-film deposition specialists with atomic layer deposition capabilities for sub-micron dielectrics, as dimensional compression toward 0201 and 01005 footprints fragments supplier capabilities. Long-term viability over the next decade hinges on technology transfer from automotive-grade specifications into consumer computing reliability benchmarks. Watch for inflection when AI inferencing at the edge adoption in premium notebooks crosses threshold volumes demanding ultra-stable power delivery previously reserved for automotive applications.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Small Case-Size Capacity Expansion | Enables Taiyo Yuden and competitors to serve ultrabook battery expansion requirements through PCB real estate reclamation. |
| Automotive-Grade Certification Investment | Murata Manufacturing leverages AEC-Q200 qualification to supply high-voltage MLCCs for premium notebook CPU VRM stages. |
| Direct OEM Master Supply Agreements | Quanta and Compal negotiate centralized contracts covering multiple laptop brand customers simultaneously. |
| Backward Integration into Ceramic Powder | Samsung Electro-Mechanics and Japanese conglomerates secure high-purity barium titanate against supply volatility. |
| India PLI Scheme Localization | Greenfield fab opportunities target laptop assembly migration from coastal China with government subsidy support. |
Research Methodology
Initial hypotheses were tested against primary input from MLCC procurement managers at Taiwan-based ODMs, motherboard design engineers at global PC OEMs, and ceramic powder processing specialists, then refined through secondary validation. Primary interviews covered contract electronics manufacturing executives, passive component distributor inventory planners, and environmental compliance officers navigating REACH and RoHS requirements. Secondary sources included customs and trade data for MLCC shipments, SEC filings from diversified passive component conglomerates, and regulatory submissions to ECHA and China's NMPA. Bottom-up demand modeling across dielectric formulations and case-size segments was triangulated against top-down industry capacity estimates.
Variance decomposition across the projection horizon isolates volume drivers by technology classification, end-user procurement channel, and regional production cluster. The analytical framework models segmentation across product type, size dimension, technology grade, and end-user channel. CAGRs were derived from fitted growth curves calibrated to historical shipment data and forward-looking motherboard design win notifications. Industry-specific forecast inputs include gaming laptop discrete GPU power delivery requirements and AI edge inferencing integration timelines in premium notebooks.
The analysis sits within stated boundaries; outcomes outside sustained laptop shipment volumes or stable ceramic powder supply conditions would require recalibration. Forecasts reflect documented assumptions regarding dielectric thickness deposition yield improvements and OEM sustainability scorecard evolution. Revision becomes warranted when China's NMPA environmental enforcement crosses thresholds that fundamentally alter material purity cost structures or supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market