
 Fiber Splice Closure Market | 2026-2036
Fiber Splice Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Splice Closure Market Foresight
Skilled fiber technician availability is collapsing across mature telecom markets, forcing enclosure manufacturers toward pre-terminated and tool-less designs that reduce field labor. Fujikura leverages its splicing equipment ecosystem to bundle closure sales with fusion splicer placements. Corning sustains North American dominance through captive fiber-to-closure compatibility programs. Sumitomo Electric anchors Asian supply chains with vertically integrated polymer compounding for housing materials.
A fiber splice closure is a sealed protective housing that joins, stores, and organizes optical fiber cables at splice points, typically rated for IP68 ingress protection and temperature ranges from minus 40 to 65 degrees Celsius to ensure signal integrity in harsh environments. Horizontal closures dominate direct-buried trunk installations where cable count and ribbon fiber density drive specification, while dome variants capture aerial and pedestal applications where wind loading and space constraints favor compact geometries. Rack-mounted closures concentrate margin pools in data center interconnection zones where density and rapid reconfiguration justify premium pricing over outdoor buried alternatives.
The US FCC broadband equity programs and India's BIS certification requirements for telecom infrastructure are tightening enclosure performance standards, compelling manufacturers to validate thermal cycling and moisture resistance through accredited third-party testing. The EU F-Gas Regulation indirectly shapes material selection by restricting certain sealing compounds, pushing suppliers toward silicone and EPDM rubber alternatives. Stakeholders must monitor how national broadband subsidy disbursement timelines synchronize with OEM qualification cycles to avoid inventory mismatches.
Market Dynamics
Pre-terminated closure designs are compressing field labor requirements as technician scarcity intensifies across North American and European telecom markets, forcing manufacturers to engineer tool-less sealing mechanisms and modular fiber management systems that slash installation time.
Growth Catalysts
- China MIIT Gigabit Mandates:National infrastructure targets for gigabit city coverage are accelerating enclosure specifications with hardened IP68 ratings and expanded temperature tolerances for outdoor trunk deployments.
- India BharatNet Phase III:Rural fiber expansion programs are generating concentrated demand for dome-type closures optimized for aerial and pedestal installations in harsh monsoon environments.
- Ribbon Fiber Density Scaling:Mass fusion splicing adoption in data center interconnects is driving horizontal closure designs with 1728-fiber capacity and organized slack storage for rapid reconfiguration.
Market Restraints
- EPDM and Silicone Compound Costs:EU F-Gas Regulation restrictions on fluorinated sealing materials are elevating raw material expenses for gasket and O-ring production.
- Asian Polymer Supply Concentration:Vertically integrated housing material producers in East Asia control critical polymer compounding capacity, creating geographic supply vulnerability for Western OEMs.
- Mechanical Splice Substitution:Field-installable mechanical splices for temporary restoration are displacing permanent fusion splices in certain emergency repair scenarios, reducing closure attachment frequency.
Strategic Opportunities
- Indonesia Palapa Ring Extension:Archipelago submarine cable landing projects require marine-grade closures with pressure-rated sealing for tidal zone installations.
- US BEAD Program Alignment:Broadband Equity Access and Deployment subsidy timelines are creating qualification windows for closures meeting Buy America domestic content thresholds.
- AI-Driven Predictive Maintenance:Integration of fiber monitoring sensors within closure housings converges passive infrastructure with real-time performance analytics for proactive network management.
Industry Challenges
- Fusion Splicing Certification Bottlenecks:Field technician accreditation programs through Fiber Optic Association and manufacturer-specific tracks cannot scale to match deployment velocity.
- BIS Testing Queue Delays:Indian certification requirements for telecom infrastructure are extending product validation cycles by six to nine months, misaligning with project tender schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Splice Closure Market |
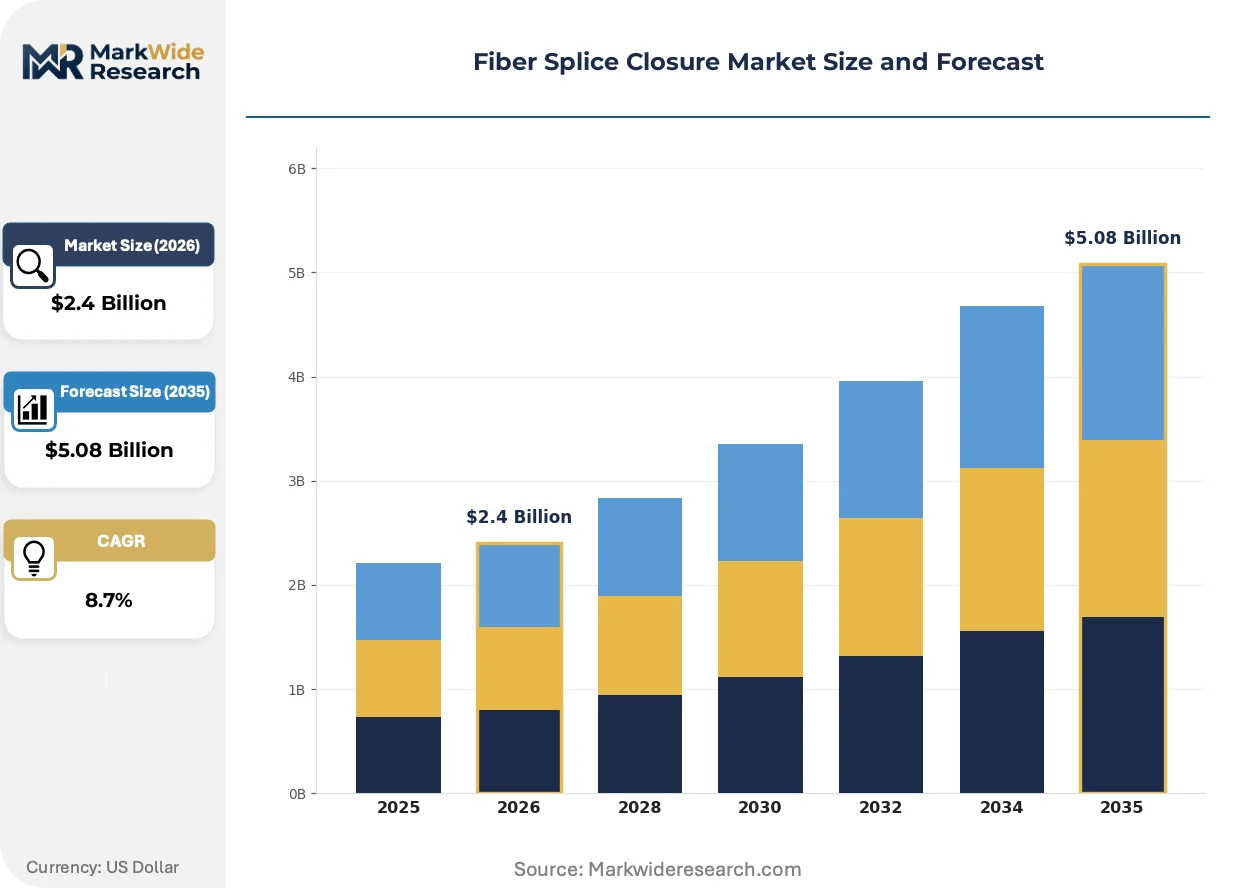
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Dome, Rack Installation Method: Direct Buried, Aerial, Indoor, Underground End User: Telecom Operators, Data Centers, Enterprises, ISPs Material: Plastic, Metal, Composite, Rubber |
| Companies Covered | Fujikura, Sumitomo Electric, CommScope, Fiberhome, ZTT Group, Corning, Furukawa Electric, New Sea Union Technology, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Splice Closure Market Shifts & Advancements
Tool-less mechanical sealing systems are displacing traditional heat-shrink and gel-based closure methods across outdoor fiber deployments. This shift compresses installation labor while elevating reliability expectations for buried and aerial infrastructure.
Push-pull latch mechanisms with dual-durometer gaskets is supplanting conventional bolted flange designs in direct-buried applications. Tier-one operators in Germany and Japan are specifying these configurations for trunk routes where re-entry frequency exceeds historical norms. The technology is compressing mean-time-to-repair metrics and reducing field truck rolls for routine maintenance access.
The EU F-Gas Regulation is restricting perfluorinated polymer use in sealing compounds, compelling formulation shifts toward silicone and hydrogenated nitrile alternatives. Closure manufacturers serving European utility and rail fiber networks are requalifying thermal cycling performance under revised material specifications. German and French rail infrastructure tenders now mandate documentation of fluorine-free gasket compositions.
Telecom procurement teams are consolidating vendor panels around integrated fiber-to-closure compatibility programs. North American operators are eliminating multi-source qualification overhead by specifying closures tested against captive cable geometries. This behavior concentrates specification authority with fiber producers who bundle enclosure recommendations with cable supply agreements.
Fiber Splice Closure Market Segmentation
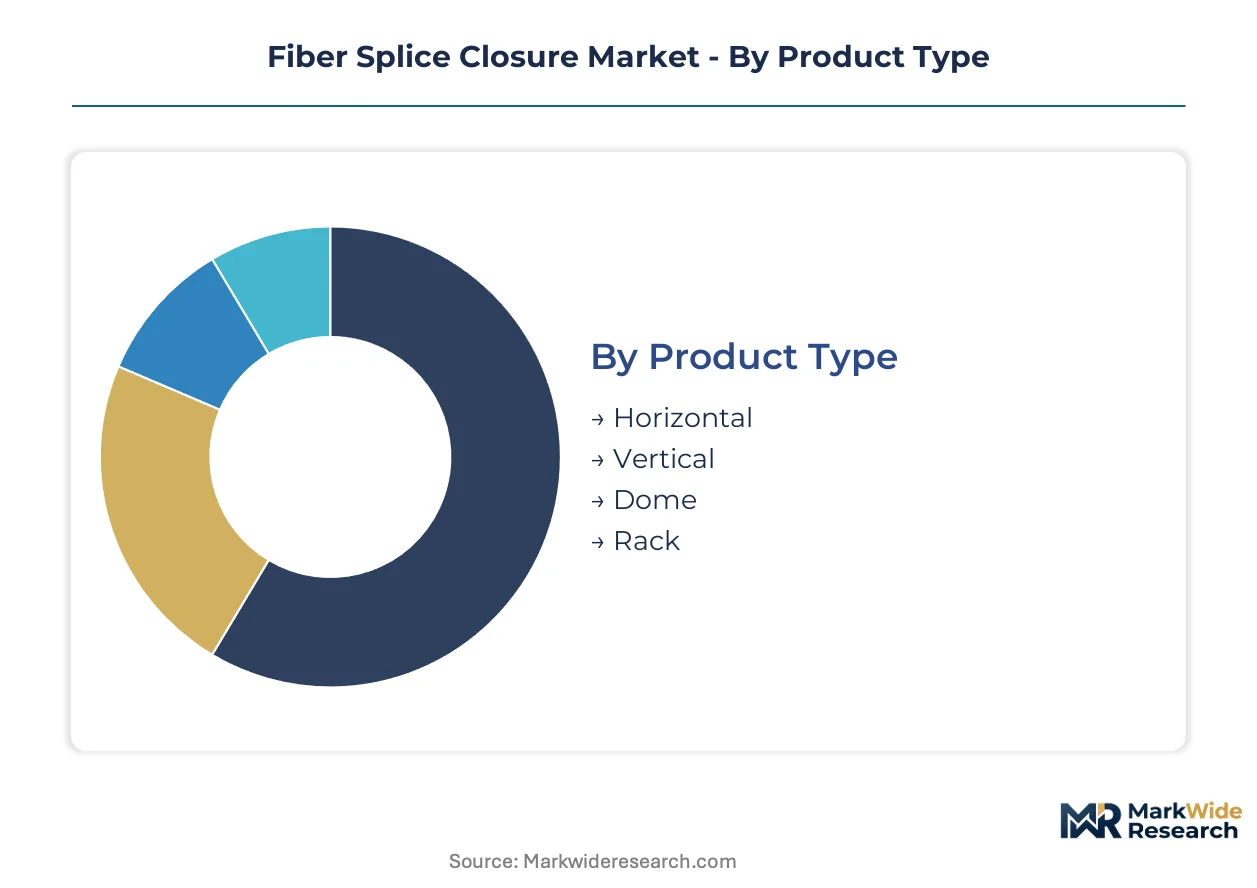
Enclosure geometry, deployment environment, and customer procurement power create distinct margin architectures across the fiber splice closure landscape. Manufacturers optimize housing designs and material formulations to capture value pools tied to specific installation constraints and end-user technical requirements.
Product Type:
Horizontal configurations command premium pricing in high-fiber-count trunk routes where ribbon density and organized slack storage justify elevated unit economics.
- Horizontal:Rectangular housings engineered for direct-buried ribbon fiber deployments accommodate 1728-fiber capacities with modular tray systems. Data center interconnect corridors in Germany and Japan specify these for rapid re-entry and mass fusion splicing workflows.
- Dome:Compact spherical geometries optimize wind loading profiles for aerial strand-mount and pedestal applications. India's BharatNet Phase III rural expansion drives demand for monsoon-hardened dome variants with IP68 sealing and expanded temperature tolerances.
- Vertical:Slim profile housings suit confined underground vault installations where footprint constraints limit horizontal expansion.
- Rack:19-inch mountable enclosures concentrate in data center cross-connect zones where density and tool-less access justify premium positioning over outdoor alternatives.
Horizontal closures hold installed capacity across long-haul trunk networks. Dome variants are rotating up the share rankings with accelerating aerial fiber deployments.
Installation Method:
Subsurface burial methods dominate volume flows while aerial techniques gain traction in cost-sensitive rural fiber overbuilds.
- Direct Buried:Trenched deployments with armored cable protection require hardened horizontal closures rated for soil pressure and rodent intrusion. China's MIIT gigabit city mandates specify these for municipal trunk infrastructure with 40-year service life requirements.
- Aerial:Strand-mounted dome closures reduce civil works expenditure in terrain-challenged geographies. Indonesian Palapa Ring extension projects specify marine-grade aerial variants for coastal tidal zone resilience.
- Indoor:Controlled-environment rack and wall-mount configurations serve central office and data center applications with lower IP ratings but higher density demands.
- Underground:Vault and handhole installations utilize vertical geometries where space constraints and flood risk shape specification priorities.
Direct buried maintains volume leadership in greenfield trunk construction. Aerial methods are climbing the fastest with accelerated rural subsidy programs.
End User:
Procurement scale and technical sophistication diverge sharply between carrier-grade operators and enterprise self-builds.
- Telecom Operators:Tier-one carriers consolidate vendor panels around integrated fiber-to-closure compatibility programs, bundling enclosure specifications with cable supply agreements. US BEAD program qualification windows favor operators with domestic content compliance capabilities.
- Data Centers:Hyperscale facilities prioritize rack-mounted density and rapid reconfiguration, accepting premium pricing for tool-less fiber management systems that compress technician touch time.
- Enterprises:Private network builds favor standardized dome and vertical configurations with shorter qualification cycles and lower minimum order quantities.
- ISPs:Competitive local exchange carriers optimize for total installed cost, driving specification toward pre-terminated solutions that reduce field labor dependency.
Telecom operators anchor procurement volume through multi-year framework agreements. Data centers are gaining share fastest with AI-driven infrastructure expansion.
Material:
Polymer formulation choices increasingly hinge on regulatory compliance rather than purely mechanical performance.
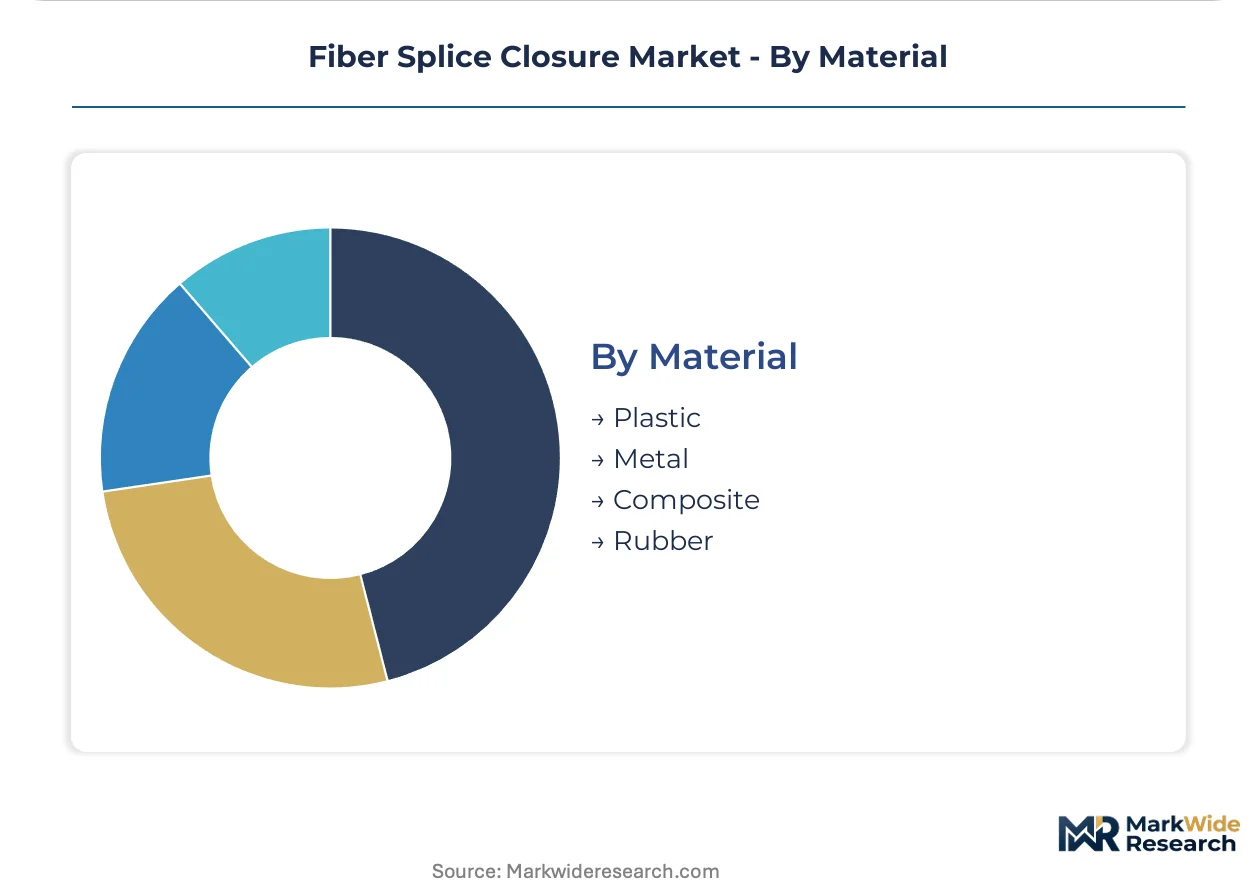
- Plastic:Glass-reinforced polypropylene and polycarbonate compounds dominate volume production, with East Asian suppliers controlling critical compounding capacity. EU F-Gas Regulation restrictions on fluorinated additives are forcing reformulation toward silicone-compatible base resins.
- Metal:Die-cast aluminum housings serve utility and rail fiber networks requiring electromagnetic shielding and vandal resistance. German and French rail tenders now mandate fluorine-free gasket documentation alongside metal enclosure specifications.
- Composite:Hybrid material systems combine polymer moldability with metal structural elements for specialized marine and industrial applications.
- Rubber:EPDM and hydrogenated nitrile sealing compounds have displaced perfluorinated alternatives under REACH-aligned regulatory pressure, elevating raw material cost structures.
Plastic formulations hold installed capacity across standard outdoor deployments. Metal enclosures are rotating up the share rankings with hardened infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys horizontal closures at massive scale for direct-buried trunk routes, while India favors dome geometries for aerial rural expansion. The United States concentrates procurement through BEAD subsidy windows demanding domestic content compliance.
China
MIIT gigabit city mandates accelerate hardened enclosure specifications across municipal fiber infrastructure. The regulator mandates IP68 ratings and 40-year service life for buried trunk deployments. Yangtze River Delta manufacturers supply polymer compounds to closure fabricators serving state-owned carrier procurement frameworks.
United States
FCC broadband equity programs concentrate demand through qualification windows tied to subsidy disbursement timelines. The BEAD program enforces Buy America domestic content thresholds for closure procurement. Texas and California anchor deployment volume through rural fiber overbuilds and data center corridor expansion.
India
BharatNet Phase III rural expansion drives dome-type closure demand for aerial and pedestal installations in monsoon-exposed geographies. BIS certification requirements extend product validation cycles by six to nine months. Maharashtra and Karnataka host procurement clusters where state-level fiber projects intersect with private 5G backhaul deployment.
Germany
Rail infrastructure tenders mandate fluorine-free gasket documentation under EU F-Gas Regulation compliance pressure. ECHA-aligned material restrictions push formulation shifts toward silicone sealing compounds. Bavaria and North Rhine-Westphalia concentrate utility fiber networks where die-cast aluminum enclosures serve electromagnetic shielding requirements.
Indonesia
Palapa Ring extension projects generate marine-grade closure demand for submarine cable landing zones in tidal environments. The national broadband initiative specifies pressure-rated sealing for archipelago geography. Java-based procurement clusters coordinate enclosure supply with coastal fiber route construction timelines.
Fiber Splice Closure Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling captive fiber-to-closure compatibility programs and polymer compounding capacity. The middle tier fragments across regional procurement frameworks and shorter qualification cycle products. Three archetypes dominate: vertically integrated cable-closure bundlers, standalone enclosure specialists, and splicing equipment ecosystem players. Competitive moves concentrate on vendor panel consolidation through integrated supply agreements and accelerated qualification cycles aligned with national broadband subsidy windows.
Among Japanese-origin integrated suppliers, Fujikura and Sumitomo Electric occupy positions where splicing equipment ecosystems anchor closure distribution. Corning exemplifies the North American bundler archetype through fiber-to-closure compatibility programs. Fiberhome represents Chinese state-linked procurement concentration serving MIIT-mandated infrastructure deployments.
| Leading Market Players |
|---|
| Fujikura |
| Sumitomo Electric |
| CommScope |
| Fiberhome |
| ZTT Group |
| Corning |
| Furukawa Electric |
| New Sea Union Technology |
| 3M |
| Others |
Supply & Pricing Matrix
Ninety-day polymer compound lead times from Yangtze River Delta suppliers compress OEM pricing power during subsidy-driven deployment windows, forcing Western manufacturers to absorb margin compression or risk disqualification from national broadband tenders. This inventory pressure intensifies where Buy America domestic content thresholds restrict sourcing flexibility.
Pricing Analysis
Long-term framework agreements dominate tier-one carrier procurement, with multi-year offtake structures bundling closure specifications with captive fiber supply. Price differentiation rests on IP68 certification grade and BIS validation status, with Indian infrastructure projects commanding premiums for accelerated qualification cycles. Cost compression in standard dome configurations intensifies as Chinese state-linked OEMs flood Southeast Asian markets. Competitive local exchange carriers exhibit highest price sensitivity, while hyperscale data centers accept premium positioning for tool-less rack-mounted density.
Supply Chain Analysis
Container availability fluctuations on Shanghai-Rotterdam and Shanghai-Los Angeles lanes elevate inbound logistics costs for European and North American closure fabricators sourcing polymer compounds. East Asian suppliers in China, South Korea, and Japan control critical glass-reinforced polypropylene compounding capacity. Raw material dependencies center on silicone sealing formulations, EPDM rubber alternatives, and die-cast aluminum feedstock. Single-source vulnerability concentrates where vertically integrated housing material producers dominate. Distribution runs through state-owned carrier procurement frameworks and hyperscale data center direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as national broadband subsidy disbursement timelines synchronize with telecom infrastructure upgrade cycles, creating concentrated demand windows.
For Market Incumbents: Secure vendor panel consolidation through integrated fiber-to-closure compatibility programs that bundle specifications with cable supply agreements. Deepen backward integration into polymer compounding to mitigate East Asian supply concentration risk. Invest in BIS pre-certification capacity to compress Indian validation cycles and align with BharatNet tender schedules.
For New Entrants and Emerging Players: Anchor in Indonesia's Palapa Ring extension corridors where marine-grade closure demand for submarine cable landing zones remains underserved by established bundlers. Target pressure-rated sealing specialization for tidal zone installations. Pursue qualification partnerships with archipelago fiber route developers ahead of coastal construction timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because fiber splice closures function as irreplaceable passive components with 40-year service life requirements embedded in carrier procurement standards. Acquisition targets should exhibit splicing equipment ecosystem integration or captive polymer formulation capabilities. Monitor BIS certification queue lengths as inflection indicator for Indian market access bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Tool-less Sealing Technology Launch | Compresses field labor requirements where Fiber Optic Association certification bottlenecks constrain technician supply. |
| Backward Integration into Polymer Compounding | Mitigates geographic supply vulnerability as EU F-Gas Regulation restricts fluorinated sealing material formulations. |
| BIS Pre-certification Investment | Aligns product validation cycles with BharatNet Phase III tender schedules in Maharashtra and Karnataka procurement clusters. |
| Marine-grade Closure Development | Captures Palapa Ring extension demand for pressure-rated sealing in Indonesian tidal zone installations. |
| AI Sensor Integration Partnership | Converges passive closure infrastructure with real-time fiber monitoring for predictive network management. |
Research Methodology
The analysis maps horizontal, dome, vertical, and rack enclosure configurations, each validated through fiber network planners, closure procurement managers, field technician supervisors, and polymer compound suppliers. Primary interviews with these stakeholders combined with secondary validation from MIIT infrastructure disclosures, FCC BEAD program documentation, BIS certification registries, and customs trade data. Bottom-up fiber count demand modeling and top-down infrastructure budget triangulation anchored volume estimates.
Consistency checks against carrier capex disclosures and national broadband subsidy allocation schedules validated projection outputs across the analysis window. Segmentation dimensions modeled include enclosure geometry, installation method, end-user procurement scale, and material formulation compliance tier. CAGRs derived from deployment velocity assumptions tied to gigabit city mandates and rural fiber expansion programs, with thermal cycling performance requirements and moisture resistance standards as industry-specific forecast inputs.
Material uncertainties — subsidy disbursement delays, certification queue extensions, polymer supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about technician training pipeline scaling and regulatory timeline adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market