
 Inductors, Cores and Beads Market | 2026-2036
Inductors, Cores and Beads Market Size, Share, and Industry Trends Forecast 2026-2036
Inductors, Cores and Beads Market Insights
The capital-intensity divergence between integrated ferrite producers and fabless inductor designers is collapsing as raw material volatility erodes margin buffers for asset-light competitors. TDK Corporation leverages captive ferrite mining and in-house powder metallurgy to sustain cost leadership across laminated core production. Murata Manufacturing anchors its position through monolithic integration of chip inductors with ceramic capacitor lines, while Vishay Intertechnology competes via broad catalog depth in wire-wound inductors for industrial power supplies.
Inductors, cores and beads constitute passive magnetic components that store energy in electromagnetic fields, with ferrite compositions typically specifying initial permeability between 500 and 15,000 depending on Mn-Zn or Ni-Zn chemistry, and serve primarily to filter noise, regulate current ripple, and manage electromagnetic interference in switched-mode power circuits. Wire-wound inductors retain the largest revenue pool in power supply applications where saturation current ratings above 50A command premium positioning, while chip inductors represent the fastest-expanding category as RF front-end module counts multiply in 5G handsets. Ferrite beads occupy a mature, high-volume segment where margin compression from commoditized SMD packages is offset by automotive-grade qualification premiums in motor control circuits.
Japan's METI enforces JIS C 2561 standards for power inductor thermal aging performance, while China's MIIT mandates GB/T certification for ferrite cores deployed in grid-tied inverters under dual carbon compliance timelines. The EU's RoHS and REACH frameworks restrict hexavalent chromium in electroplated termination coatings, forcing reformulation of iron powder core surface treatments. Stakeholders must monitor how automotive OEMs reconcile ISO 26262 functional safety requirements with emerging wide-bandgap semiconductor switching frequencies that redefine inductor core loss specifications.
Market Dynamics
Wide-bandgap semiconductors operating above 100 kHz are forcing ferrite core formulations to tolerate steeper flux density swings, collapsing the historical performance gap between Mn-Zn power ferrites and distributed gap iron powder cores in automotive DC-DC converters.
Growth Catalysts
- NEV Powertrain Electrification:China's MIIT dual carbon mandates require 40% NEV sales penetration by 2030, saturating onboard chargers and DC-DC stages with high-current inductors rated above 50A saturation current.
- 5G RF Front-End Proliferation:Multi-band MIMO architectures in handsets multiply chip inductor counts per device, with mmWave filters demanding sub-nH tolerance grades previously reserved for aerospace applications.
- REACH RoHS Reformulation:ECHA restrictions on hexavalent chromium in electroplated terminations force iron powder core suppliers to qualify alkaline tin-bismuth alternatives, creating first-mover premiums for qualified vendors.
Market Restraints
- Raw Material Concentration:High-purity iron oxide and manganese carbonate supply chains concentrate in Chinese state-owned mining consortia, exposing ferrite producers to export quota volatility and yuan-denominated pricing.
- Technical Saturation Limits:Mn-Zn ferrites exhibit core loss inflection above 80°C ambient in 150 kHz switching regimes, capping power density gains in sealed automotive engine-bay modules.
- Substitution by Integrated Magnetics:Gallium nitride power stages with embedded planar inductors displace discrete wire-wound components in sub-500W consumer adapters, compressing addressable volume in high-volume segments.
Strategic Opportunities
- India PLI Localization:India's production-linked incentive schemes for electronics manufacturing attract inductor packaging investments to serve domestic smartphone and inverter assembly.
- Grid-Scale Energy Storage:Utility battery inverters require nanocrystalline common-mode chokes with permeability stability across -40°C to 125°C, opening premium positioning for alloy tape-wound geometries.
- Automotive Functional Safety:ISO 26262 ASIL-D qualification for power inductors in steering and braking systems creates defensible margin tiers unavailable to industrial-grade competitors.
Industry Challenges
- Powder Metallurgy Talent Scarcity:Ferrite sintering process control requires expertise in atmosphere-controlled kilns and particle size distribution optimization that retiring Japanese engineers disproportionately hold.
- Automotive Qualification Timelines:AEC-Q200 stress testing demands 1,000-hour thermal aging validation that extends new product introduction cycles to 18-24 months, freezing design wins for incumbent qualified suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inductors, Cores and Beads Market |
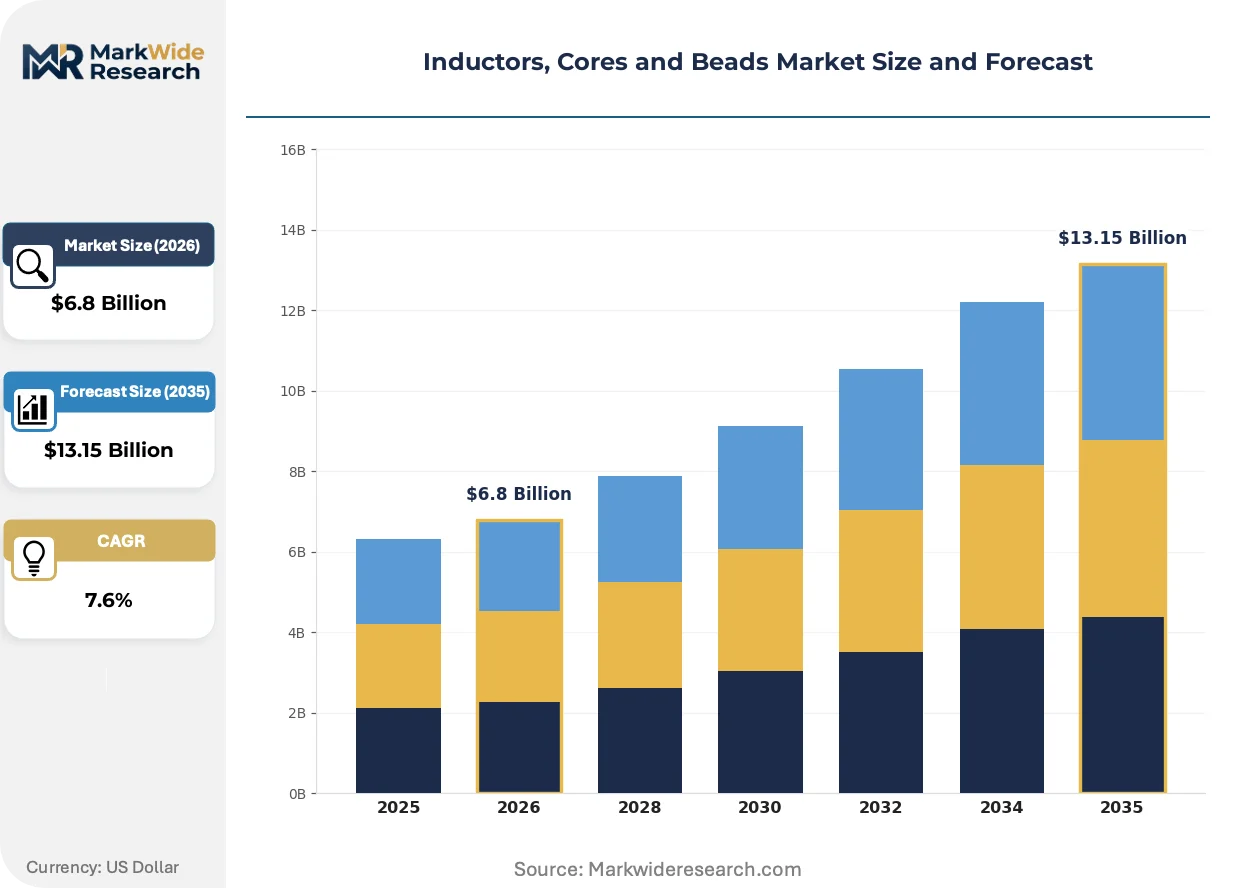
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire-Wound Inductors, Chip Inductors, Ferrite Beads, Laminated Cores Application: Power Supply, RF Applications, Audio Equipment, Motor Control End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Material: Ferrite, Iron Powders, Silicon Steel, Composite Materials |
| Companies Covered | TDK Corporation, Murata Manufacturing, Vishay Intertechnology, Taiyo Yuden, Panasonic Corporation, Delta Electronics, Chilisin Electronics, Coilcraft, TT Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inductors, Cores and Beads Market Trends and Innovations
Magnetic component architectures are fragmenting between high-frequency miniaturization for consumer electronics and thermal ruggedization for electrified powertrains, with no single material platform serving both extremes profitably.
Amorphous and nanocrystalline ribbon materials are bifurcating the common-mode choke market from ferrite dominance. These alloys deliver permeability above 80,000 with near-zero magnetostriction, enabling 50% volume reduction in EMI filters for 800V EV architectures. Tier-one automotive suppliers in Germany and Japan are qualifying tape-wound geometries for onboard chargers, compressing ferrite bead pricing in 10A+ filtering applications.
ECHA REACH Annex XVII amendments restricting nickel release rates in prolonged skin-contact devices are forcing wearable electronics manufacturers to specify nickel-zinc ferrites over manganese-zinc compositions in hearing aids and fitness bands. The substitution cascades through SMD bead procurement specifications at major EMS providers in Taiwan and South Korea, who now demand alloy composition certificates with every lot.
Consolidation among EMS providers is compressing inductor vendor counts per approved manufacturer list. Foxconn and Luxshare now mandate single-source qualification for magnetic components across entire product families, replacing the historical three-vendor redundancy model. This concentration is most visible in notebook power adapter procurement, where annual volume commitments exceeding 50 million units secure exclusive capacity allocation at top-tier ferrite houses.
Inductors, Cores and Beads Market Segmentation
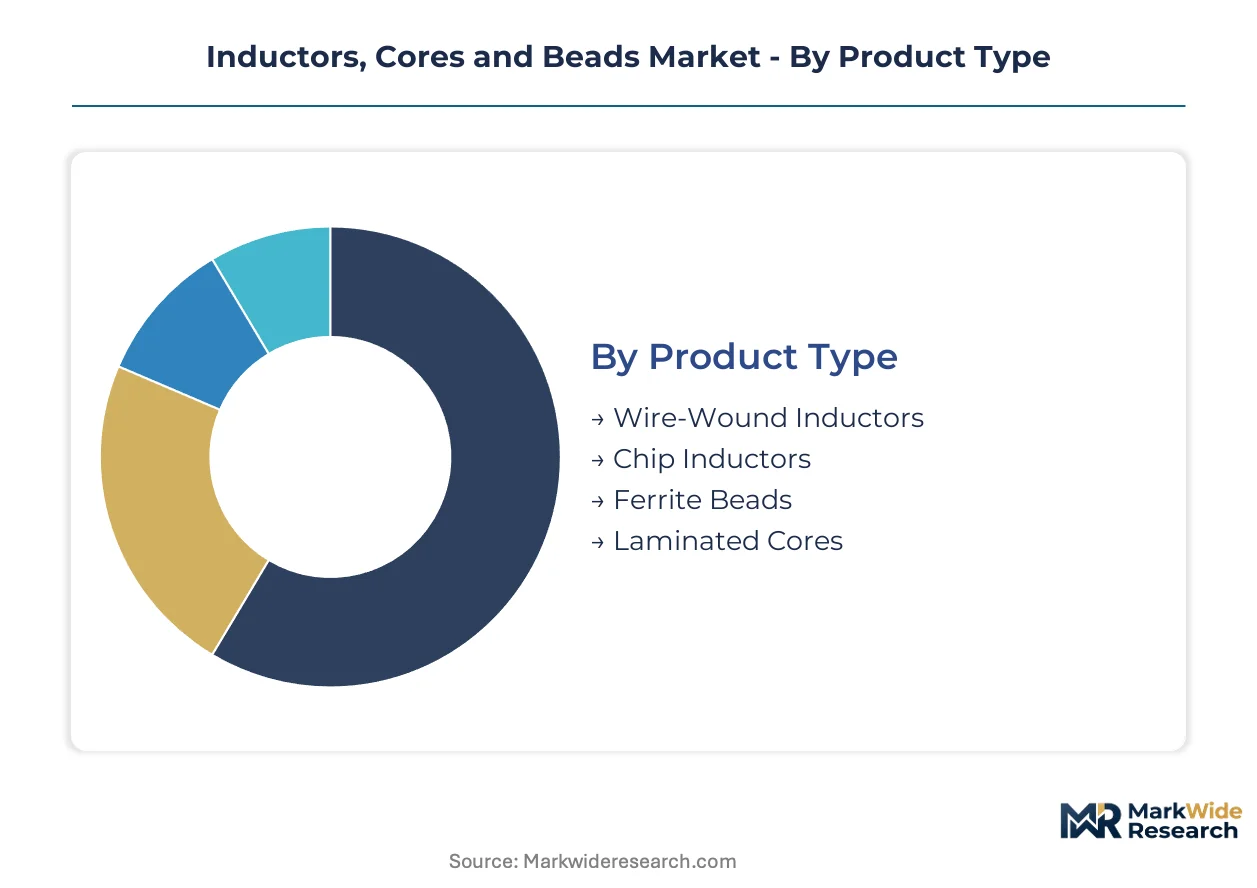
Magnetic component procurement channels diverge sharply between high-volume consumer electronics EMS providers and qualified automotive tier-one suppliers. Understanding which segments flow through which channels exposes margin structure and design-win vulnerability.
Product Type:
Wire-wound inductors move primarily through industrial distributors for power supply procurement, while chip inductors route directly to handset ODMs under consignment arrangements.
- Wire-Wound Inductors:Copper wire coil geometries wound around ferrite or iron powder cores achieve saturation current ratings above 50A. Demand concentrates in server power supplies for hyperscale data centers in Virginia and Frankfurt, where efficiency mandates above 80 PLUS Titanium drive premium specifications.
- Chip Inductors:Monolithic ceramic or ferrite-core surface-mount devices measure sub-millimeter footprints for RF filtering. Smartphone assembly in Dongguan and Chennai multiplies per-device counts as 5G MIMO architectures expand, tightening sub-nH tolerance supply.
- Ferrite Beads:Cylindrical or chip-form impedance elements suppress conducted EMI in motor leads and digital buses.
- Laminated Cores:Stacked silicon steel or nickel-iron tape constructions minimize eddy losses in grid-tied inverters and welding equipment.
By volume, ferrite beads lead. By growth pace, chip inductors are expanding most quickly.
Application:
Cost tier stratification separates commodity power supply magnetics from RF applications commanding aerospace-grade tolerance premiums.
- Power Supply:DC-DC converters and AC-DC adapters require inductors rated for continuous thermal operation above 125°C. Onboard charger modules in NEV powertrains absorb the fastest capacity expansion, with 800V architectures demanding nanocrystalline common-mode chokes.
- RF Applications:Matching networks and filter stages in base stations and handsets specify Q factors above 40 at 2.4 GHz. mmWave front-end modules in South Korean smartphone flagships now require thin-film inductor tolerances previously reserved for satellite hardware.
- Audio Equipment:Output filters and crossover networks in professional amplifiers and consumer soundbars.
- Motor Control:Current sensing and EMI suppression in industrial servo drives and appliance compressors.
Power supply applications dominate revenue contribution. RF applications gain share fastest as 5G infrastructure deployment accelerates.
End User:
Customer type determines qualification burden — automotive ASIL-D certification extends lead times 18-24 months versus 6-9 months for consumer electronics.
- Consumer Electronics:Notebook adapters, smartphones, and wearables drive high-volume, price-sensitive procurement. India's PLI schemes for electronics manufacturing attract inductor packaging investments to serve domestic smartphone assembly.
- Automotive:Steering, braking, and powertrain electrification mandate ISO 26262 functional safety compliance. China's MIIT dual carbon mandates saturate onboard chargers with high-current magnetics rated above 50A saturation.
- Telecommunications:Base station power amplifiers and optical transport equipment.
- Industrial Equipment:Welding systems, CNC drives, and solar inverters.
Consumer electronics leads in unit volume. Automotive climbs fastest as electrification penetrates powertrain architectures.
Material:
Supply concentration for high-purity iron oxide and manganese carbonate in Chinese state-owned mining consortia shapes material cost trajectories and geographic sourcing strategies.
- Ferrite:Mn-Zn compositions deliver permeability between 500-15,000 for power applications; Ni-Zn variants serve RF above 1 MHz. ECHA REACH restrictions on nickel release rates force substitution toward Ni-Zn in wearable devices with prolonged skin contact.
- Iron Powders:Distributed gap toroids and E-cores tolerate DC bias without saturation in PFC stages. Automotive DC-DC converters above 100 kHz switching collapse the historical performance gap against Mn-Zn ferrites.
- Silicon Steel:Grain-oriented laminations for 50/60 Hz transformers and grid infrastructure.
- Composite Materials:Amorphous and nanocrystalline ribbons with permeability above 80,000 for 800V EV EMI filters.
Ferrite dominates production volume. Composite materials expand most rapidly as 800V architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in East Asian ferrite supply chains diverges sharply from European automotive qualification premiums, with Japanese and South Korean producers commanding margin tiers unavailable to emerging packaging operations in Vietnam and Thailand.
China
MIIT dual carbon mandates and NEV sales targets drive ferrite core demand for onboard chargers and DC-DC converters. GB/T certification requirements for grid-tied inverters tighten efficiency standards under state carbon neutrality timelines. Manufacturing concentrates in Dongguan and Shenzhen clusters, where EMS providers consolidate vendor lists for smartphone adapter procurement.
Japan
METI enforces JIS C 2561 thermal aging standards for power inductors in automotive applications. Domestic automakers source high-current magnetics for 800V architectures from qualified tier-one suppliers. Production gravity sits in Nagoya and Osaka industrial corridors, where ferrite sintering expertise pools among retiring process engineers.
South Korea
mmWave 5G handset flagships multiply chip inductor counts per device, tightening sub-nH tolerance supply for RF front-end modules. MFDS oversees component reliability frameworks for wearable electronics with prolonged skin contact. Seoul-Incheon manufacturing corridors anchor packaging investments serving domestic smartphone ODMs.
Germany
ECHA REACH restrictions on hexavalent chromium in electroplated terminations force iron powder core reformulation for automotive DC-DC stages. KBA vehicle type-approval processes extend qualification timelines for powertrain magnetics. Bavarian automotive supplier clusters qualify nanocrystalline common-mode chokes for 800V onboard chargers.
India
PLI schemes for electronics manufacturing attract inductor packaging investments to serve domestic smartphone and solar inverter assembly. BIS certification requirements for ferrite cores in grid infrastructure shape procurement specifications. Tamil Nadu and Karnataka industrial corridors concentrate EMS operations for export-oriented consumer electronics.
Inductors, Cores and Beads Market Competitive Landscape
Concentration sits with integrated ferrite producers possessing captive raw material access and in-house powder metallurgy capabilities. Three structural archetypes populate the vendor landscape: mining-integrated Japanese conglomerates with backward ferrite ore control; fabless inductor designers reliant on outsourced core fabrication; and Korean-Chinese packaging specialists scaling SMD bead volumes for consumer EMS providers. Dominant competitive moves include capacity expansion in nanocrystalline ribbon production for EV EMI filters, and strategic partnerships between automotive tier-ones and qualified magnetic component suppliers to secure 18-24 month AEC-Q200 validation pipelines.
Among Japan-based integrated producers, TDK Corporation and Murata Manufacturing occupy positions defined by material sovereignty and monolithic component integration respectively. Vishay Intertechnology anchors a separate archetype as a broad-catalog industrial specialist. These three entities exemplify how geographic origin and corporate structure shape competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| TDK Corporation |
| Murata Manufacturing |
| Vishay Intertechnology |
| Taiyo Yuden |
| Panasonic Corporation |
| Delta Electronics |
| Chilisin Electronics |
| Coilcraft |
| TT Electronics |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between automotive tier-one suppliers and Japanese ferrite houses lock in both manganese carbonate supply access and price visibility across 18-24 month AEC-Q200 validation cycles. These contracts insulate qualified vendors from yuan-denominated raw material volatility while freezing out spot-market competitors from design wins in 800V onboard charger programs.
Pricing Analysis
Configured-to-order pricing for automotive-grade inductors commands spreads exceeding three standard-economy tiers against catalog wire-wound components. Price differentiation hinges on ISO 26262 ASIL-D certification tier and volume scale, with hyperscale data center procurement driving cost compression in 80 PLUS Titanium server power supplies. Pricing pressure stems from gallium nitride planar magnetics displacing discrete components in sub-500W consumer adapters. Consumer electronics EMS providers exhibit highest price sensitivity; automotive powertrain suppliers show lowest.
Supply Chain Analysis
Inventory buffers at Dongguan EMS clusters have compressed to six-week horizons as Foxconn and Luxshare consolidate vendor lists to single-source arrangements. Supply concentrates in China, Japan, and South Korea, with high-purity iron oxide and manganese carbonate drawing from Chinese state-owned mining consortia. Single-source vulnerability sits with ferrite sintering expertise pooled among retiring Japanese process engineers. Distribution runs through industrial distributors for power supply procurement and direct consignment to handset ODMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. AEC-Q200 qualification timelines create switching costs that freeze design wins for 18-24 months, insulating incumbent ferrite houses from price-based displacement.
For Market Incumbents: Secure captive manganese carbonate supply through backward integration into Chinese mining partnerships or long-term offtake with state-owned consortia. Add nanocrystalline ribbon capacity in Nagoya industrial corridors to defend against amorphous alloy substitution in 800V EV EMI filters. Certification investment in GB/T grid-tied inverter standards captures China's dual carbon procurement mandates. For New Entrants and Emerging Players: Post-sintering processing services for ferrite core surface treatment represent a service-layer gap where incumbents under-serve mid-tier automotive suppliers. Target India's PLI electronics manufacturing clusters for inductor packaging investments serving domestic smartphone and solar inverter assembly. Qualify alkaline tin-bismuth electroplating alternatives under ECHA REACH reformulation timelines as a first-mover go-to-market angle. For Investors and Strategic Acquirers: Fabless inductor designers with RF front-end module expertise in mmWave tolerance grades present the named acquisition target archetype. Long-term viability over the next decade rests on securing powder metallurgy talent pipelines as Japanese process engineers retire. Watch for MFDS nickel-release restrictions cascading through wearable electronics procurement specifications as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Nanocrystalline Ribbon | Tape-wound geometries for 800V EV architectures capture premium positioning in German automotive supplier clusters. |
| Backward Integration into Ferrite Ore | Captive manganese carbonate supply from Chinese state-owned consortia insulates margin buffers against yuan volatility. |
| AEC-Q200 Certification Investment | ASIL-D qualification for steering and braking systems creates defensible margin tiers unavailable to industrial-grade competitors. |
| Long-term Supply Agreement with EMS Consolidators | Exclusive capacity allocation at Foxconn and Luxshare replaces three-vendor redundancy with single-source security. |
| Geographic Expansion to India PLI Corridors | Tamil Nadu and Karnataka packaging investments serve domestic smartphone assembly under BIS certification requirements. |
Research Methodology
Desk research of ferrite industry trade publications, JIS C 2561 and GB/T regulatory filings, and SEC disclosures from magnetic component manufacturers preceded structured interviews with automotive tier-one procurement directors, powder metallurgy process engineers, EMS supply chain managers, and power electronics design leads. Secondary validation drew from MIIT NEV policy documents, ECHA REACH amendment drafts, and hyperscale data center efficiency certification databases. Bottom-up unit demand modeling triangulated against top-down market sizing across product type, material chemistry, and end-use application dimensions.
Variance decomposition across the projection horizon isolates volume drivers by segment saturation, pricing trajectory by certification tier, and technology substitution effects from wide-bandgap semiconductor adoption. Segmentation dimensions modeled include product architecture, material platform, application power rating, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to NEV powertrain electrification penetration and 5G handset RF front-end module proliferation. Industry-specific inputs incorporate ferrite core loss specifications at 150 kHz switching frequencies and nanocrystalline permeability stability across automotive temperature ranges.
Forecasts assume regulatory continuity in China's MIIT dual carbon mandates, Japan's METI thermal aging standards, and ECHA REACH electroplating restrictions; material policy shifts would require re-modeling supply concentration and qualification timeline assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Precision Chip Resistors Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market