
 Through Hole Resistor Market | 2026-2036
Through Hole Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Through Hole Resistor Market Analytics
Automotive electronics demand is shifting toward higher-wattage through hole resistors as electric vehicle inverters and onboard chargers proliferate. Vishay Intertechnology dominates high-reliability automotive grades through its bulk metal foil and wirewound portfolios. YAGEO sustains cost-competitive metal film production across Asian manufacturing hubs. Panasonic anchors industrial equipment supply chains with thick film resistors rated for extended temperature ranges.
A through hole resistor mounts via wire leads inserted into printed circuit board holes and soldered on the opposite side, typically offering power ratings from fractions of a watt to over 100 watts and tolerance levels down to 0.005 percent. Wirewound variants handle surge conditions in motor drives and power supplies where surface-mount alternatives fail. Metal film resistors capture precision instrumentation and audio applications due to low temperature coefficient and noise characteristics. Thick film products occupy high-volume consumer electronics where cost minimization overrides precision requirements.
RoHS and REACH in Europe restrict lead content and hazardous substances in electronic components, compelling reformulation of termination finishes and resistor coatings. China's GB standards and MIIT directives enforce similar substance controls while promoting domestic passive component production. FDA and FAA qualification pathways govern resistors in medical devices and avionics, creating segmented certification tiers that filter supplier participation. Stakeholders must monitor evolving automotive functional safety standards and material compliance deadlines to preserve market access across regulated end-use sectors.
Market Dynamics
Automotive electrification is forcing through hole resistor manufacturers to recalibrate power ratings and thermal management specifications as EV inverters and onboard chargers displace internal combustion architectures.
Growth Catalysts
- EV Powertrain Expansion:Electric vehicle motor controllers and DC-DC converters require wirewound resistors rated for surge tolerance beyond surface-mount capabilities.
- RoHS and REACH:European substance restrictions on lead and halogenated compounds are accelerating lead-free termination finish adoption across automotive supply chains.
- Industrial Automation:Motor drives and variable frequency drives in manufacturing hubs demand metal oxide film resistors for braking and snubber circuits.
Market Restraints
- Raw Material Volatility:Ceramic substrate and nickel-chrome alloy pricing fluctuations compress margin predictability for wirewound resistor producers.
- Supply Concentration:Precision metal film resistor manufacturing clusters heavily in East Asian foundries, creating geographic vulnerability to logistics disruptions.
- Surface-Mount Substitution:Miniaturized SMD resistors capture low-power consumer electronics, constraining through hole addressable market expansion.
Strategic Opportunities
- Medical Device Certification:FDA 510(k) and IEC 60601 pathways for patient-connected equipment create premium pricing tiers for high-reliability metal film resistors.
- Avionics Modernization:FAA DO-160 qualification requirements for environmental testing open specialized supply contracts for military and commercial aerospace programs.
- Renewable Energy Storage:Grid-scale battery management systems and solar inverters require high-wattage wirewound resistors for pre-charge and discharge circuits.
Industry Challenges
- Functional Safety Compliance:ISO 26262 automotive safety integrity level certification demands extensive documentation and testing cycles that extend product qualification timelines.
- Legacy Equipment Integration:Industrial retrofit projects require form-factor compatibility with decades-old PCB layouts, constraining design innovation for new resistor families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Through Hole Resistor Market |
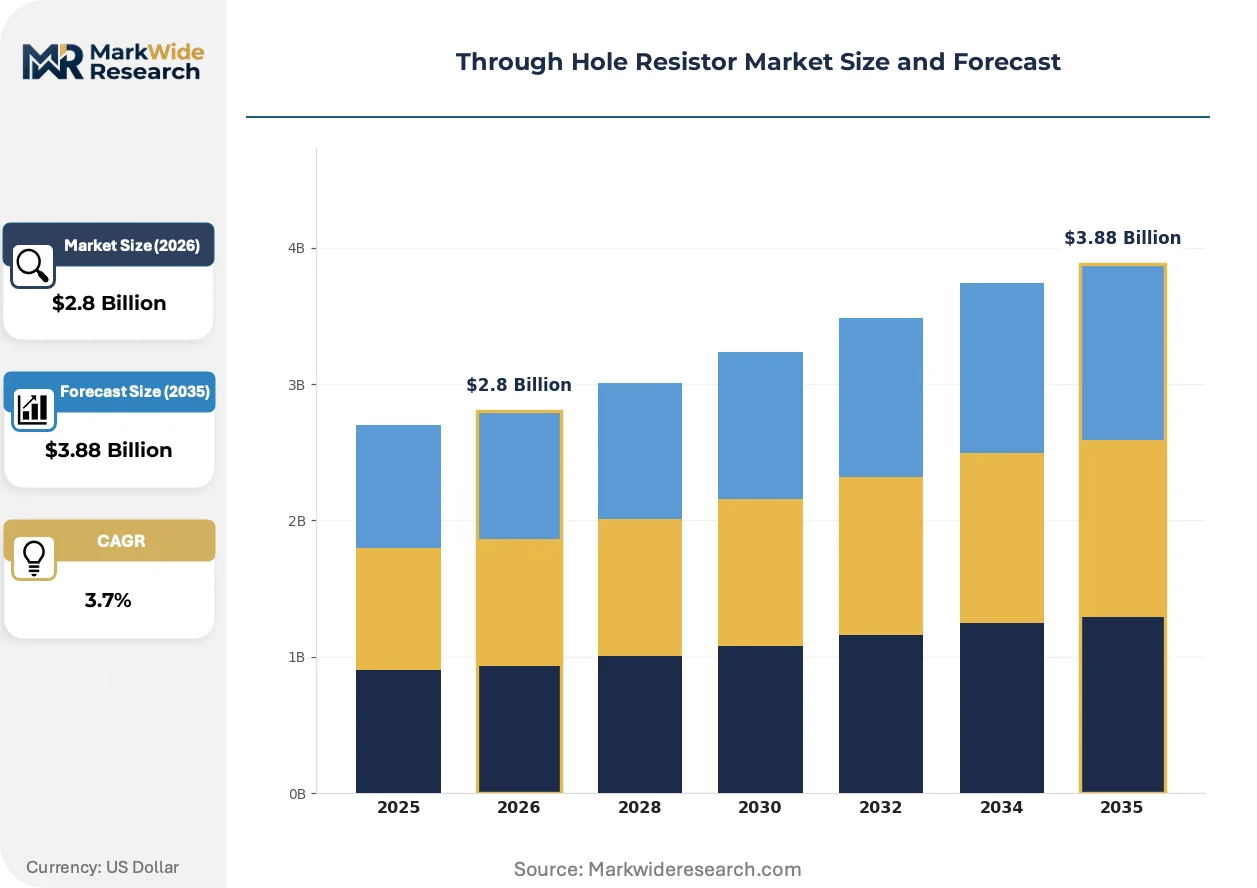
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Film, Metal Film, Wirewound, Thick Film Application: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications End User: OEMs, Aftermarket Providers, Distributors, Retailers Technology: Analog, Digital, Mixed-Signal, Power Management |
| Companies Covered | Vishay Intertechnology, YAGEO, Panasonic, Murata Manufacturing, TE Connectivity, ROHM, Bourns, KOA Speer Electronics, TT Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Through Hole Resistor Market Evolving Landscape
Material science advances and regulatory tightening are compressing traditional resistor manufacturing paradigms while opening specialized niches for precision and high-reliability grades.
Metal oxide film technology is integrating ceramic core substrates with laser-trimmed resistance elements to achieve temperature coefficients below 50 ppm per degree Celsius. Medical instrumentation and test equipment manufacturers are adopting these precision grades for signal conditioning circuits. The technology is integrating tighter tolerance bands into standard product lines, compressing the premium pricing gap between commercial and precision resistor categories.
REACH substance restrictions are forcing reformulation of resistor coatings and termination materials to eliminate hexavalent chromium and certain phthalate plasticizers. European component distributors now require full material disclosure documentation upstream from assembly houses. Automotive Tier 1 suppliers are responding by dual-sourcing lead-free resistor families qualified to AEC-Q200 stress test standards.
Consolidated procurement through electronics manufacturing service providers is displacing traditional distributor relationships for high-volume consumer and industrial applications. EMS giants in Taiwan and Mexico are negotiating direct supply agreements with resistor manufacturers, bypassing regional distribution layers. This concentration is most visible in consumer appliance manufacturing where specification standardization enables single-source contracts for thick film resistor families.
Through Hole Resistor Market Segmentation
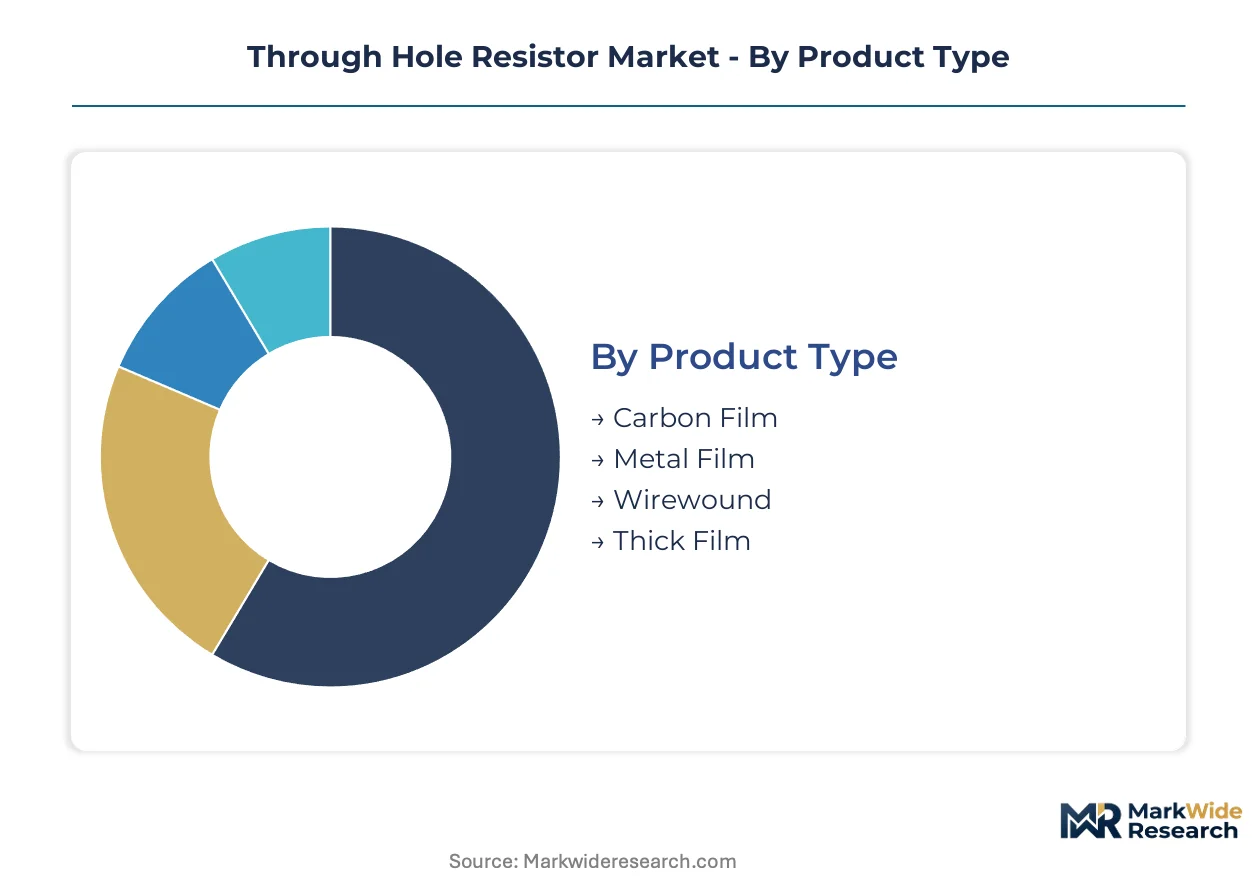
Through hole resistor procurement patterns diverge sharply across product architectures and end-use requirements. Equipment upgrade cycles and replacement demand in mature industrial installations create distinct volume concentrations that reshape supplier priorities.
Product Type:
Upgrade cycles in precision instrumentation and power electronics drive differential replacement demand across resistor technologies.
- Wirewound:Ceramic or fiberglass core wrapped with nickel-chrome or copper-nickel alloy wire delivers surge tolerance to 100x rated power for milliseconds. Demand concentrates in EV onboard chargers and industrial motor drives across Germany and China, where thermal cycling specifications exceed surface-mount capabilities.
- Metal Film:Vacuum-deposited nickel-chromium layer on ceramic substrate achieves temperature coefficients below 50 ppm/°C and tolerances to 0.1%. Medical device manufacturers in the United States and Switzerland specify these grades for patient-connected monitoring equipment requiring long-term stability.
- Carbon Film:Pyrolytic carbon deposition on ceramic rods serves cost-sensitive consumer applications with moderate precision requirements.
- Thick Film:Screen-printed resistive ink on alumina substrates dominates high-volume appliance controls where price minimization outweighs precision needs.
Volume placements concentrate in thick film for appliance manufacturing; the faster expansion belongs to wirewound for electrified transportation systems.
Application:
Cost tier differentiation separates specification-heavy automotive contracts from price-elastic consumer electronics procurement.
- Automotive:AEC-Q200 qualification mandates temperature cycling, moisture resistance, and board flex testing for powertrain electronics. Tier 1 suppliers in Germany and Japan specify wirewound resistors for DC-link discharge circuits in hybrid inverters.
- Industrial Equipment:Variable frequency drives and servo amplifiers require metal oxide film resistors for dynamic braking and snubber applications. Manufacturing hubs in China's Guangdong and Jiangsu provinces drive replacement volume for legacy CNC machinery.
- Consumer Electronics:Audio amplifiers and power supplies in cost-constrained markets favor carbon film and thick film families.
- Telecommunications:Base station power supplies and network infrastructure specify metal film grades for voltage reference circuits.
Contract values peak in automotive qualification programs; telecommunications infrastructure replacement is climbing the fastest.
End User:
Customer type determines whether procurement flows through consolidated EMS channels or fragmented distributor networks.
- OEMs:Direct specification authority over resistor families in automotive, medical, and aerospace platforms. Original equipment manufacturers in the United States and Germany maintain approved vendor lists with dual-source requirements for critical safety applications.
- Distributors:Arrow Electronics and Avnet maintain regional inventory positions for MRO procurement in industrial maintenance operations.
- Aftermarket Providers:Repair and refurbishment specialists source cross-reference equivalents for legacy industrial control systems.
- Retailers:Hobbyist and educational markets through catalog distributors represent minimal volume with high SKU fragmentation.
Procurement volume aggregates through OEM direct contracts; distributor channel expansion is gaining share fastest in industrial MRO segments.
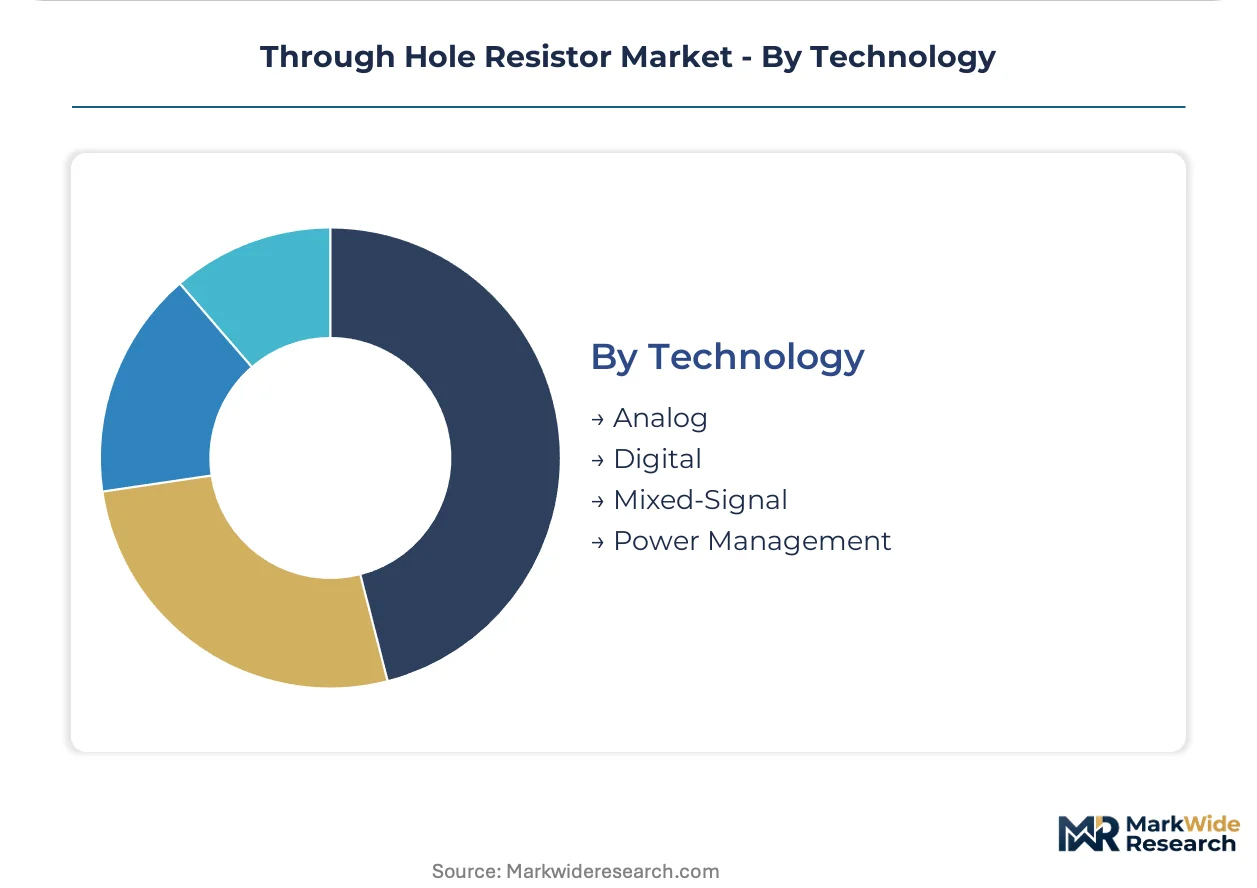
Technology:
Supply concentration in mixed-signal and power management applications reflects the intersection of precision requirements and thermal management complexity.
- Power Management:Current sensing, pre-charge, and discharge circuits in battery management systems and solar inverters. Renewable energy installers in China and the United States specify high-wattage wirewound resistors for grid-tied storage systems.
- Mixed-Signal:Data acquisition front-ends and ADC reference networks in test equipment and medical imaging. Precision metal film resistors with matched temperature tracking serve instrumentation manufacturers in Switzerland and Japan.
- Analog:Signal conditioning and filter networks in audio and industrial process control.
- Digital:Termination and pull-up applications with minimal precision requirements.
Design activity concentrates in power management for energy storage; mixed-signal instrumentation represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-designated passive component industrial zones concentrate wirewound resistor manufacturing for electric vehicle supply chains. Germany's high-reliability certification corridors anchor automotive-grade metal film production. The United States maintains precision instrumentation demand through FDA-regulated medical device clusters.
China
MIIT's dual carbon goals accelerate EV powertrain component localization across Jiangsu and Guangdong provinces. GB standards enforce RoHS-aligned substance restrictions on termination finishes. Suzhou and Shenzhen industrial parks host concentrated wirewound resistor fabrication for onboard charger and inverter applications.
Germany
AEC-Q200 qualification requirements from KBA drive Tier 1 automotive procurement of surge-tolerant resistors. REACH substance disclosure mandates reshape coating formulations across Bavarian manufacturing corridors. Stuttgart and Munich anchor high-reliability metal film production for DC-link discharge circuits in hybrid powertrains.
United States
FDA 510(k) pathways for patient-connected equipment sustain premium demand for precision metal film grades. FAA DO-160 environmental testing governs avionics resistor qualification for commercial aerospace programs. Greater Boston and Silicon Valley clusters concentrate medical instrumentation and test equipment design activity.
Japan
METI's industrial technology roadmaps prioritize passive component miniaturization for automotive electronics. JIS standards govern temperature coefficient specifications in precision resistor families. Nagoya and Osaka manufacturing belts supply metal oxide film products for industrial motor drive applications.
South Korea
MFDS medical device registration requirements parallel FDA pathways for export-oriented manufacturers. Domestic EV battery management systems drive wirewound resistor procurement for pre-charge circuits. Seoul Capital Area and Busan-Ulsan corridors concentrate electronics manufacturing service provider consolidation.
Through Hole Resistor Market Competitive Landscape
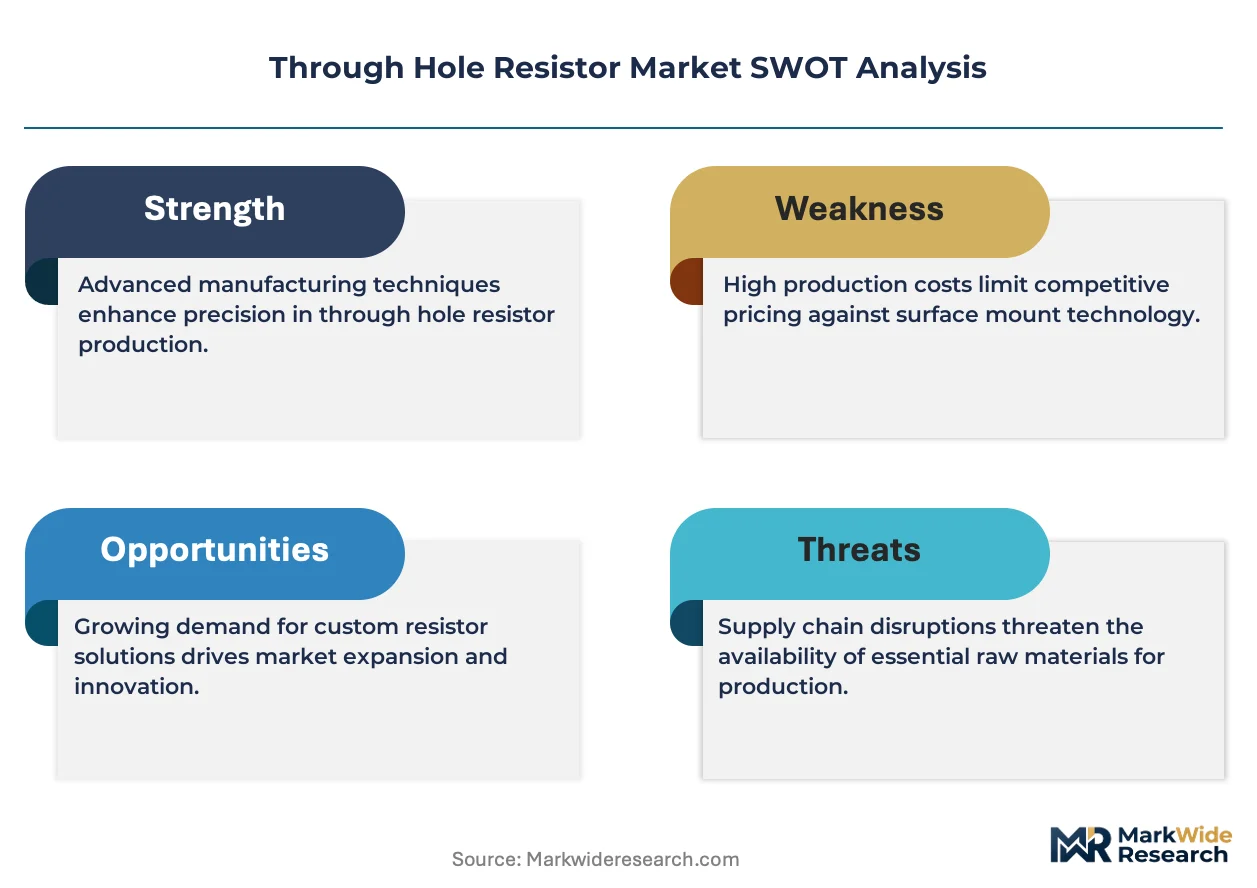
Top-tier vendors anchor high-reliability automotive and medical certifications, while mid-scale specialists occupy cost-optimized industrial segments. The vendor base stratifies across three archetypes: precision-grade specialists with AEC-Q200 and FDA qualification depth, high-volume thick film producers serving appliance manufacturing, and wirewound experts targeting power electronics. Consolidation pressure intensifies through EMS direct contracting and dual-source requirements from automotive OEMs. Geographic expansion into Mexico and Southeast Asia represents the dominant competitive maneuver alongside backward integration into ceramic substrate production.
Among North American and European precision specialists, Vishay Intertechnology and Bourns occupy positions within the high-reliability certification tier. YAGEO anchors the high-volume Asian manufacturing archetype. These three exemplify the structural divide between premium-grade qualification holders and scale-driven production platforms.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| YAGEO |
| Panasonic |
| Murata Manufacturing |
| TE Connectivity |
| ROHM |
| Bourns |
| KOA Speer Electronics |
| TT Electronics |
| Others |
Value Network & Pricing Analysis
Nickel-chrome alloy pricing volatility propagates through wirewound resistor manufacturing tiers, compressing margins at high-volume producers while precision-grade specialists pass material cost premiums to automotive OEMs under long-term AEC-Q200 contracts. Ceramic substrate costs and termination finish reformulations for RoHS compliance further stratify pricing power across the supply base.
Pricing Analysis
Lead-time-driven pricing separates automotive qualification programs from spot-market industrial procurement, with AEC-Q200-certified wirewound families commanding 30-40% premiums for guaranteed 8-week delivery against 20-week standard lead times. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA-tracked metal film grades capturing highest margins and thick film appliance components facing steepest cost compression. Price erosion runs through consumer electronics thick film tiers as EMS consolidators extract volume rebates. Industrial MRO buyers exhibit highest price sensitivity; medical device OEMs show lowest sensitivity due to patient-safety liability exposure.
Supply Chain Analysis
AEC-Q200 and FDA 510(k) qualification gating restricts supply base participation in premium tiers, filtering qualified suppliers to Vishay, Bourns, and KOA Speer for automotive and medical applications. Manufacturing concentrates in China, Germany, and Japan, with Jiangsu province hosting wirewound fabrication for EV powertrains and Bavaria anchoring high-reliability metal film production. Raw material dependencies encompass alumina ceramic substrates, nickel-chrome resistance wire, and lead-free termination alloys. Single-source vulnerability concentrates in precision metal film laser-trimming equipment held by Japanese vendors. Distribution runs through Arrow and Avnet for industrial MRO, while automotive Tier 1s negotiate direct manufacturer contracts bypassing distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Through hole resistor manufacturing is consolidating toward qualification-heavy automotive and medical tiers, with EMS direct contracting and dual-source mandates squeezing undifferentiated thick film producers from industrial and consumer segments.
For Market Incumbents: Anchor AEC-Q200 and FDA qualification depth as defensive moats against surface-mount substitution in power electronics. Extend backward integration into ceramic substrate production to secure margin control against alumina price volatility. Deepen captive supply of nickel-chrome alloy wire through foundry partnerships in Germany and Japan. Surface-mount encroachment on sub-2-watt applications threatens volume positions; respond with high-wattage wirewound specialization for EV inverters and grid storage systems. For New Entrants and Emerging Players: Aftermarket providers serving legacy industrial control refurbishment represent the most penetrable buyer archetype, with cross-reference equivalent sourcing fragmented across hundreds of regional distributors. Target medical device contract manufacturers in Greater Boston and Silicon Valley seeking second-source metal film suppliers for FDA 510(k) programs. Enter through private-label agreements with established distributors, leveraging existing qualification documentation rather than building certification infrastructure independently. For Investors and Strategic Acquirers: YAGEO's acquisition velocity in precision resistor specialists is the leading indicator that automotive electrification is consolidating supply base control before EV platform standardization locks in vendor relationships. Five-to-ten-year viability favors wirewound specialists with AEC-Q200 depth and ceramic substrate backward integration over thick film commodity producers exposed to EMS pricing power. Target acquisition archetype: mid-scale German or Japanese metal film manufacturers with FDA qualification pathways and dormant automotive certification. Watch for Tier 1 supplier dual-source announcements as inflection signals for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Certification Investment | Unlocks Tier 1 automotive procurement for EV inverter and onboard charger applications. |
| Ceramic Substrate Backward Integration | Captures margin from alumina supply and insulates against raw material price volatility. |
| Medical Device FDA 510(k) Pathway | Opens premium pricing tiers for patient-connected monitoring and diagnostic equipment. |
| EMS Direct Supply Agreement | Bypasses distributor layers and locks in volume commitments from appliance manufacturing giants. |
| Renewable Energy Storage Partnership | Positions wirewound resistors for pre-charge circuits in grid-scale battery management systems. |
Research Methodology
SEC 10-K filings, AEC-Q200 qualification databases, and customs trade records formed the secondary backbone, supplemented by FDA 510(k) submission tracking and REACH substance disclosure registries. Primary interviews with Tier 1 automotive procurement managers, EMS supply chain directors, and medical device biomedical engineers validated demand assumptions and pricing dynamics. Bottom-up resistor shipment analysis by product architecture triangulated against top-down electronics manufacturing value chain estimates across the analysis window.
Historical trendline analysis of automotive electronics content per vehicle and industrial automation capital expenditure patterns anchored the projection framework. Segmentation modeling covered product type, application end-use, technology deployment, and geographic production cluster dimensions. CAGRs derived from regression analysis of replacement demand cycles and EV powertrain penetration trajectories. Forecast inputs incorporated MIIT domestic production targets, KBA electrification mandates, and FDA medical device approval velocity.
Revisions become necessary when automotive platform standardization accelerates, REACH substance restrictions expand to additional coating chemistries, or EMS consolidator bankruptcy reshapes distribution channels. Forecasts reflect assumptions about AEC-Q200 qualification timelines and ceramic substrate supply continuity. A model refresh is warranted upon material change in EV inverter architecture specifications or FDA medical device reclassification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Precision Chip Resistors Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market