
 Chip Resistor Market | 2026-2036
Chip Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Resistor Market Intelligence
Component refurbishment and lifecycle extension services is rewriting margin allocation across the passive component value chain. Vishay Intertechnology leverages its broad thick-film portfolio to dominate industrial and automotive channels. Yageo Corporation anchors high-volume SMD supply through massive wafer-fab partnerships in Taiwan and mainland China. KOA Corporation specializes in precision thin-film devices for aerospace and medical instrumentation, competing on reliability metrics rather than unit cost.
A chip resistor is a passive electronic component fabricated on a ceramic substrate with deposited resistive material, typically measuring 0.4 mm × 0.2 mm to 6.4 mm × 3.2 mm in standard EIA case sizes, designed to limit current flow or divide voltage in printed circuit assemblies. Thick-film technology occupies the highest unit-volume tier across consumer electronics and telecommunications, while thin-film precision resistors command premium positioning in test equipment and military systems where temperature coefficients below 25 ppm/°C are mandatory. Wire-wound construction retains dominance in high-power industrial automation above 2 watts, though metal-oxide variants are displacing traditional cemented types in surge-resistant applications.
RoHS and REACH directives in Europe restrict cadmium and lead content in resistor terminations and glass passivation layers, compelling reformulation of thick-film pastes and electroplating chemistries. China's GB standards and dual carbon goals enforce energy-efficiency benchmarks in electronics manufacturing that elevate demand for low-thermal-coefficient precision components. Japan's METI circular-economy guidelines pressure OEM manufacturers and contract manufacturers to document material provenance across resistor supply chains. Stakeholders must monitor how evolving substance-restriction timelines in Brussels and Beijing reshape qualification requirements for automotive and aerospace electronics programs.
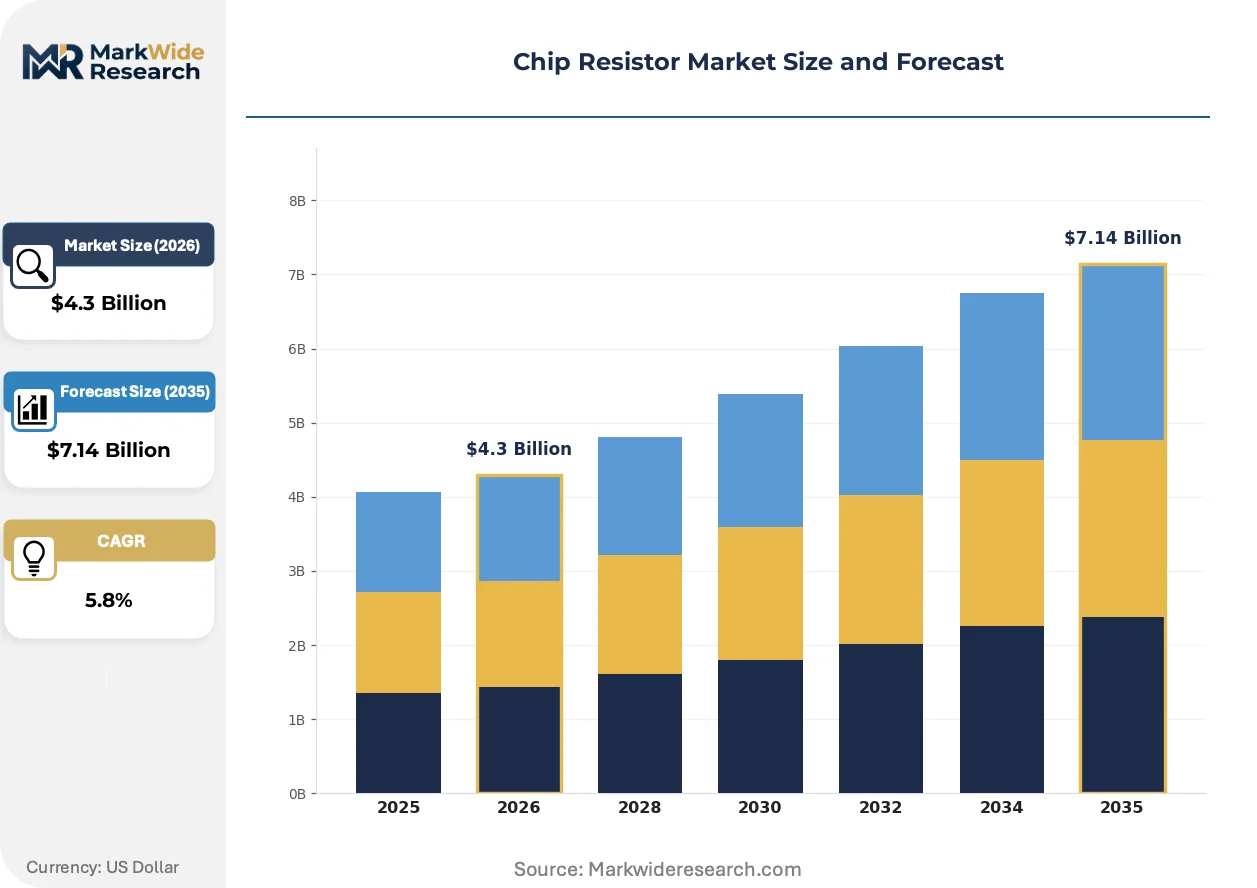
Market Dynamics
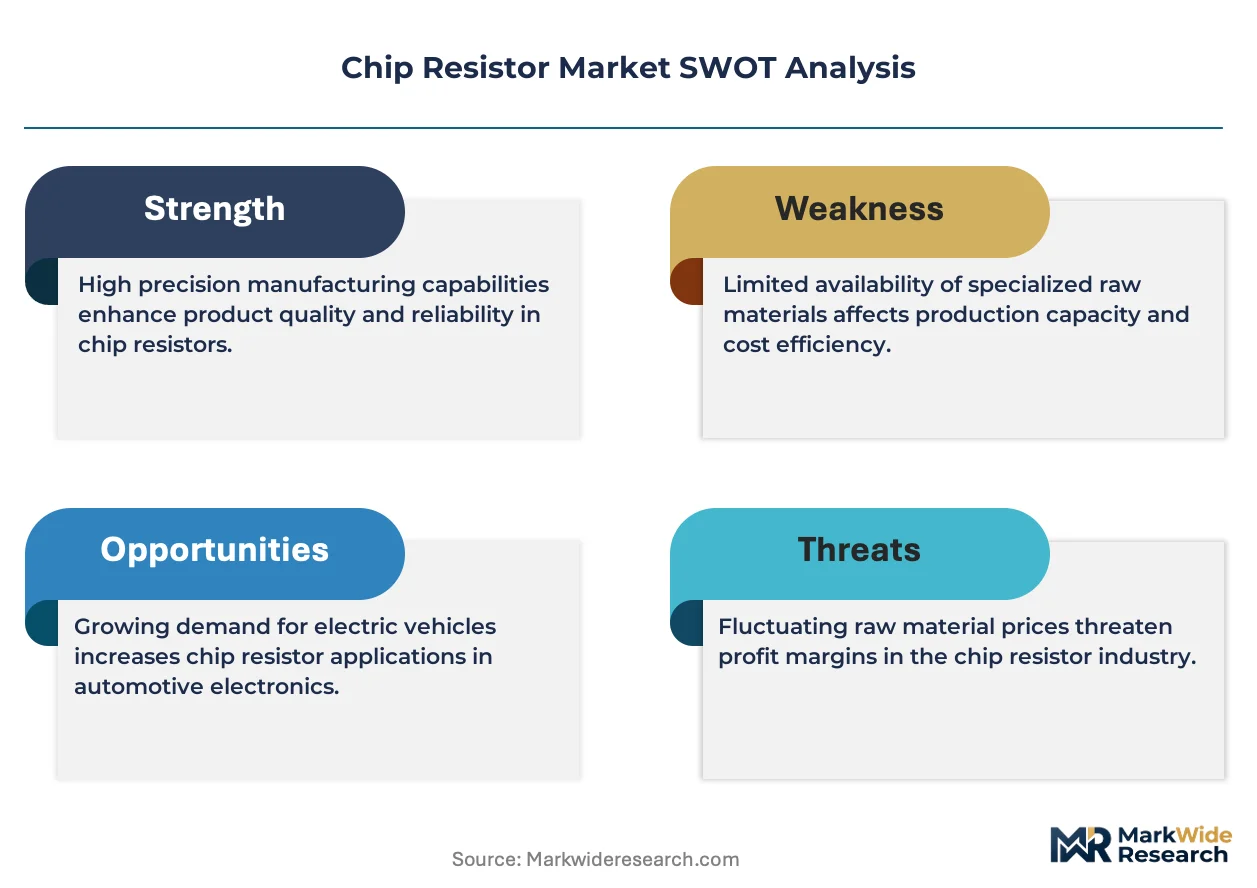
Automotive electrification is consolidating procurement power around tier-one power module suppliers, compressing resistor qualification cycles from 18 months to under 12 months while elevating thermal performance thresholds.
Growth Catalysts
- RoHS and REACH Directives:European substance restrictions on cadmium and lead terminations are accelerating reformulation of thick-film pastes, creating first-mover advantages for compliant suppliers in automotive electronics programs.
- Power Management Modules:Battery electric vehicle inverter systems are consuming precision current-sense resistors at 3-4x the rate of internal combustion counterparts, pulling volume into high-reliability automotive channels.
- East Asian Fabrication Clusters:Concentrated precision resistor capacity in China, South Korea, and Japan is enabling rapid scale-up for 5G base station deployments requiring tight tolerance matching.
Market Restraints
- Palladium and Ruthenium Price Volatility:Thick-film resistor paste formulations depend on platinum-group metals whose spot price swings compress gross margins unpredictably.
- Single-Source Ceramic Substrate Supply:High-purity alumina substrates for precision thin-film devices concentrate among Japanese suppliers, creating geographic concentration risk.
- Wire-Wound Power Limitations:Inductive parasitics in traditional wire-wound construction block adoption above 100 kHz switching frequencies, ceding ground to metal-oxide film alternatives.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are attracting resistor assembly investments to serve domestic telecom and automotive demand.
- Medical Wearables Miniaturization:Sub-millimeter 01005 case size resistors are penetrating continuous glucose monitors and hearing aids where board space constraints dominate design tradeoffs.
- Japan METI Circular Economy Guidelines:Material provenance documentation requirements are creating service revenue streams for supply chain audit and resistor refurbishment specialists.
Industry Challenges
- Thin-Film Deposition Technician Shortage:Sputtering and electron-beam evaporation expertise concentrates among aging workforces in Japan and Germany, constraining precision resistor capacity expansion.
- AEC-Q200 Qualification Timelines:Extended temperature cycling and humidity bias testing for automotive grade resistors extends new product introduction cycles, freezing out smaller suppliers lacking capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Resistor Market |
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $7.14 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thick Film, Thin Film, Metal Oxide, Metal Film, Wire Wound Technology: SMD, Leaded, High Power, Precision, Variable Application: Consumer Electronics, Telecommunications, Aerospace Electronics, Industrial Automation, Military Systems End User: OEM Manufacturers, Contract Manufacturers, System Integrators, Electronics Assemblers |
| Companies Covered | Vishay Intertechnology, Bourns, Yageo Corporation, ROHM Semiconductor, TE Connectivity, Panasonic Corporation, Stackpole Electronics, KOA Corporation, Samsung Electro-Mechanics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Resistor Market Strategic Shifts & Innovations
Resistor manufacturing is bifurcating between commodity scale and precision customization, with automation investments separating viable competitors from margin-squeezed assemblers.
Metal-oxide thin-film deposition is digitizing quality control through in-line spectroscopic monitoring that catches resistance drift during sputtering rather than post-process testing. Automotive inverter manufacturers are specifying these processes for 150°C ambient operation. The technology is digitizing yield optimization by enabling real-time paste composition adjustments that previously required batch rejection.
China's GB standards and dual carbon goals are mandating energy-efficiency benchmarks in electronics manufacturing that elevate demand for low-thermal-coefficient precision components. Domestic resistor producers must reformulate temperature coefficient specifications to maintain access to state-backed renewable energy projects. Industrial automation and grid-scale inverter suppliers are responding by qualifying domestic precision resistor sources ahead of import substitution timelines.
Aftermarket component refurbishment is unbundling from traditional distribution, with contract manufacturers now sourcing lifecycle-extended resistors through specialized channels rather than authorized distributors. Industrial maintenance and aerospace MRO segments are driving this behavioral shift where traceability documentation satisfies regulatory requirements. Germany and Japan exhibit the most pronounced channel fragmentation as circular-economy compliance costs reshape procurement evaluation criteria.
Chip Resistor Market Segmentation
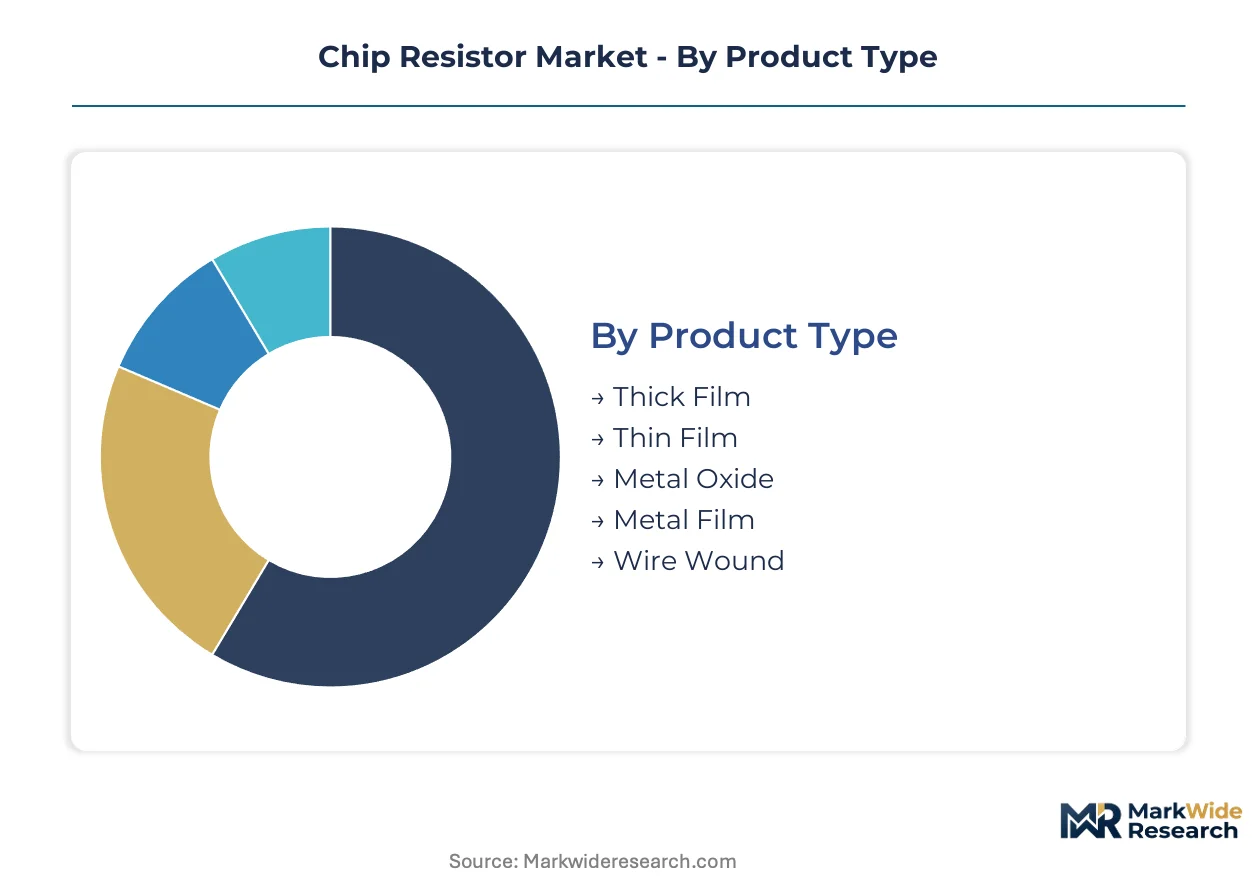
Chip resistor segmentation reveals stark divergence between commodity high-volume production and precision-grade qualification cycles. Product type and technology choices determine margin structures, inventory velocity, and customer lock-in intensity across automotive, aerospace, and industrial channels.
Product Type:
Thick-film resistors turn inventory fastest with 4-6 week production cycles, while thin-film precision devices require 12-18 month qualification timelines for aerospace and medical programs.
- Thick Film:Ceramic substrate construction with ruthenium-based resistive paste delivers 1% to 5% tolerance at lowest unit cost. Consumer electronics and telecommunications infrastructure in China and Taiwan absorb the highest volumes, though palladium price volatility compresses margins unpredictably.
- Thin Film:Sputtered nickel-chromium or tantalum nitride layers achieve temperature coefficients below 25 ppm/°C for precision measurement. Demand concentrates in German test equipment and Japanese medical instrumentation where AEC-Q200 and MIL-PRF-55342 qualification gates limit supplier pools.
- Metal Oxide:Tin oxide deposition tolerates surge currents and high-humidity environments for industrial motor drives.
- Metal Film:Nickel-chromium alloy on ceramic provides 0.1% precision at moderate cost for audio and instrumentation.
- Wire Wound:Resistive wire on ceramic core handles 2W to 100W loads in power supplies and braking systems.
Thick-film construction anchors the volume base while thin-film precision gains share at the steepest rate.
Technology:
Cost tiers separate automated surface-mount assembly from manual-insertion legacy systems, with power density requirements driving technology selection.
- SMD:Surface-mount devices dominate automated PCB assembly with case sizes from 01005 to 2512. Yageo and Walsin factories in Taiwan and mainland China ship billions of units monthly into smartphone and laptop supply chains.
- Leaded:Through-hole axial and radial formats persist in repair markets and high-voltage industrial equipment.
- High Power:Ceramic-housed and aluminum-encased designs dissipate 5W to 50W in EV charging infrastructure and solar inverters.
- Precision:Tight tolerance and low TCR specifications serve metrology and aerospace guidance systems.
- Variable:Trimmer and potentiometer configurations enable calibration adjustments in analog circuits.
SMD technology commands the dominant cost position while high-power variants climb fastest on electrification demand.
Application:
Customer procurement patterns split between high-mix low-volume aerospace programs and single-SKU automotive scale contracts.
- Consumer Electronics:Smartphones, tablets, and wearables consume 0402 and 0201 case sizes by the trillion-unit scale. Chinese EMS providers in Shenzhen and Dongguan drive specification convergence toward lowest-cost thick-film solutions.
- Telecommunications:5G base stations and optical transceivers demand tight tolerance matching for signal integrity. South Korean network equipment manufacturers qualify precision thin-film sources ahead of domestic deployment timelines.
- Aerospace Electronics:Satellites and avionics systems specify MIL-PRF-55342 qualified devices with full traceability documentation.
- Industrial Automation:Motor drives and PLCs balance cost against surge withstand capability.
- Military Systems:Radiation-hardened and high-reliability grades serve defense electronics with extended qualification cycles.
Consumer electronics sustains the volume foundation while telecommunications expands most quickly on infrastructure buildouts.
End User:
Procurement concentration varies from captive vertical integration to fragmented contract manufacturing networks.
- OEM Manufacturers:Tier-one automotive and industrial equipment producers negotiate direct supply agreements with KOA and Vishay for qualified component streams. Japanese automotive OEMs enforce PPAP documentation and statistical process control at resistor fabrication sites.
- Contract Manufacturers:Foxconn, Jabil, and Flex manage multi-source procurement across resistor specifications for electronics assembly programs.
- System Integrators:Industrial automation and energy storage packagers specify resistor arrays for current sensing and voltage division.
- Electronics Assemblers:Regional PCB shops and repair facilities source through distribution for prototype and maintenance volumes.
OEM manufacturers dominate procurement scale while contract manufacturers drive the steepest specification standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes chip resistors at industrial automation scale while Japan deploys them for precision instrumentation, creating a demand-mix differential that shapes regional supply chain configuration.
China
Domestic EV production and 5G infrastructure deployment consume thick-film resistors at massive volume. GB standards and dual carbon goals enforce energy-efficiency benchmarks that elevate demand for low-thermal-coefficient precision components. Shenzhen and Dongguan host dense EMS clusters where specification convergence drives toward lowest-cost thick-film solutions.
Japan
Satellite systems and medical instrumentation require MIL-PRF-55342 qualified thin-film devices with full traceability. METI circular-economy guidelines pressure OEMs and contract manufacturers to document material provenance across supply chains. Nagoya and Tokyo house precision fabrication facilities where sputtering expertise concentrates among specialized workforces.
South Korea
Network equipment manufacturers qualify precision thin-film sources ahead of domestic 5G deployment timelines. MFDS and national semiconductor strategies channel investment into passive component packaging capabilities. Seoul and Suwon anchor fabrication clusters serving memory module and display driver applications.
Germany
Industrial motor drives and automotive power electronics specify surge-resistant metal-oxide variants for factory automation. REACH and RoHS directives restrict cadmium and lead content in resistor terminations, compelling reformulation of thick-film pastes. Bavaria and Baden-Württemberg concentrate precision resistor distribution through specialized industrial channels.
United States
Defense electronics and aerospace MRO segments drive demand for radiation-hardened and high-reliability grades. FAA and DOD procurement standards enforce extended qualification cycles that limit supplier pools. Texas and California host system integrators specifying resistor arrays for current sensing in energy storage packaging.
Chip Resistor Market Key Industry Players
Capability concentration sits with precision specialists; scale advantage sits with high-volume fabricators. The market structures around three tiers: thick-film commodity suppliers serving consumer electronics, thin-film precision houses qualifying for aerospace and medical programs, and diversified passive component conglomerates spanning both domains. Dominant competitive moves include wafer-fab partnerships for capacity security and backward integration into ceramic substrate supply.
Among diversified passive component conglomerates, Vishay Intertechnology, Yageo Corporation, and KOA Corporation exemplify contrasting strategic positions. Vishay represents the broad-portfolio archetype spanning industrial and automotive qualification tiers. Yageo occupies a scale-driven position anchored through massive wafer-fab partnerships in Taiwan and mainland China. KOA sits within the precision-specialist tier, competing on reliability metrics rather than unit cost for aerospace and medical instrumentation applications.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| Bourns |
| Yageo Corporation |
| ROHM Semiconductor |
| TE Connectivity |
| Panasonic Corporation |
| Stackpole Electronics |
| KOA Corporation |
| Samsung Electro-Mechanics |
| Others |
Cost & Logistics Intelligence
Palladium and ruthenium price volatility in thick-film paste formulations compresses gross margins unpredictably while simultaneously forcing procurement managers toward long-term offtake contracts with Japanese and Taiwanese material suppliers. This commodity exposure widens pricing tier spreads between precision thin-film devices and commodity thick-film resistors, reshaping inventory strategies across automotive and industrial channels.
Pricing Analysis
Long-term offtake agreements dominate procurement for platinum-group metal pastes, insulating tier-one automotive suppliers from spot market swings that punish smaller contract manufacturers. Pricing stratifies across AEC-Q200 certified automotive grades, industrial standard tiers, and unqualified economy batches, with certification investment acting as the primary price differentiation driver. Cost compression in thick-film commodity tiers is intensifying because Chinese EMS providers drive specification convergence toward lowest-cost solutions. Contract manufacturers exhibit the highest price sensitivity, while aerospace OEMs purchasing MIL-PRF-55342 qualified devices demonstrate minimal elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for resistor distributors serving North American automotive programs. High-purity alumina substrates for precision thin-film devices concentrate among Japanese suppliers, while thick-film fabrication capacity clusters in Taiwan and mainland China. Raw material dependencies rest on platinum-group metals from South Africa and Russia, ruthenium from nickel mining byproducts, and ceramic powders from domestic Chinese sources. Single-source vulnerability in Japanese substrate supply creates geographic concentration risk that procurement teams mitigate through dual-qualification programs. Distribution runs through authorized franchised distributors for qualified automotive and aerospace grades, with independent brokers handling surplus and refurbishment channels for industrial maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chip resistor market sits at a platform-economics inflection where automotive electrification ecosystems are standardizing around tier-one power module suppliers, creating interoperability lock-in that favors incumbent qualification holders over new entrants.
For Market Incumbents: Pre-empt margin erosion in thick-film commodity tiers by securing captive supply of high-purity alumina substrates through backward integration into Japanese ceramic suppliers. Deepen sputtering technician training pipelines in Nagoya and Tokyo to constrain precision resistor capacity expansion by competitors. Certification investment in extended temperature cycling protocols serves as the priority defensive lever against emerging Chinese precision houses.
For New Entrants and Emerging Players: Establish a beachhead in medical wearables miniaturization where sub-millimeter 01005 case size demand outpaces qualified supply from incumbent precision specialists. Target India's PLI scheme incentives for semiconductor packaging to serve domestic telecom and automotive demand with lower qualification burden than AEC-Q200 tiers. A go-to-market angle emphasizing lifecycle extension documentation satisfies Japan METI circular-economy compliance requirements faster than incumbents can reconfigure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-specialist acquisition targets with MIL-PRF-55342 qualification gates and aging sputtering workforces. Long-term viability over the next decade hinges on positioning ahead of automotive inverter specification standardization. The signal to watch is tier-one power module supplier procurement consolidation around single-source resistor qualification streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Secures high-purity alumina supply from Japanese suppliers against geographic concentration risk. |
| AEC-Q200 Certification Investment | Qualifies resistor streams for automotive inverter programs with compressed 12-month qualification cycles. |
| Sputtering Technician Training Pipeline | Addresses thin-film deposition expertise scarcity among aging workforces in Japan and Germany. |
| India PLI Scheme Manufacturing Footprint | Captures domestic EV and telecom demand with lower regulatory burden than European REACH compliance. |
| Circular Economy Documentation Service | Creates recurring revenue from material provenance audits required by Japan METI guidelines. |
Research Approach
Initial hypotheses were tested against primary input from resistor fabrication plant managers, automotive Tier 1 procurement officers, EMS supply chain directors, and precision instrumentation R&D leads, then refined against secondary validation from SEC 10-K filings of passive component conglomerates, customs trade data for platinum-group metal imports, and AEC-Q200 qualification databases. Bottom-up unit volume estimates from case size shipment data triangulated against top-down market value projections derived from OEM component content analysis.
Demand-supply balance modeling across the analysis window incorporated segmentation dimensions of product type, technology platform, application vertical, and end-user procurement concentration. CAGRs were derived from regression analysis of historical volume trends against automotive electrification adoption curves and 5G infrastructure deployment schedules. Industry-specific forecast inputs included battery electric vehicle inverter resistor content multiples and palladium price elasticity coefficients in thick-film paste formulations.
Sensitivities concentrate around platinum-group metal spot price volatility, Japanese substrate supply disruptions, and automotive qualification timeline compression. Forecasts reflect documented assumptions regarding EV penetration rates and regulatory substance-restriction enforcement timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Precision Chip Resistors Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Germany MLCC Market