
 Passive Tunable Integrated Circuits Market | 2026-2036
Passive Tunable Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Tunable Integrated Circuits Market Analytics
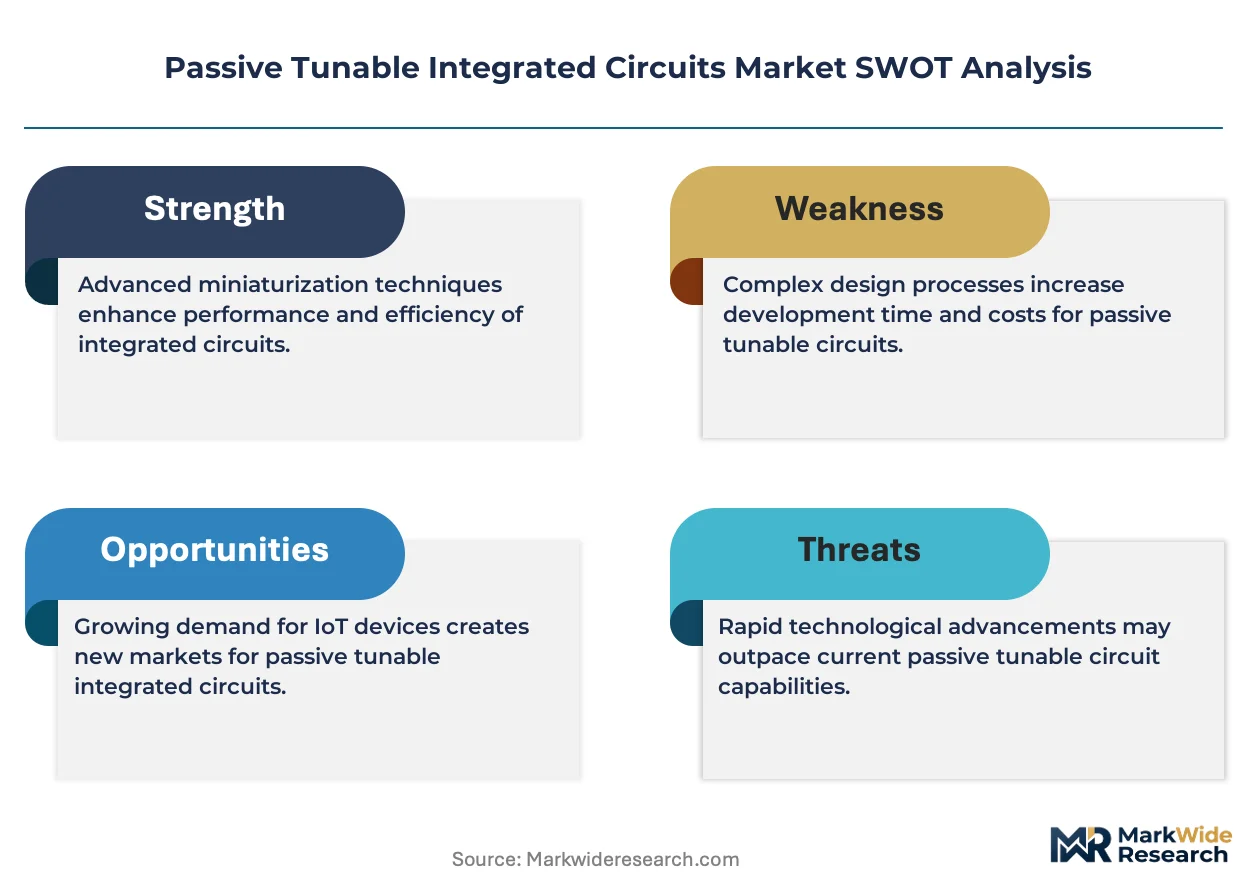
Project finance for foundry capacity is fragmenting competitive entry in passive tunable integrated circuits, allowing fabless designers to challenge capital-intensive incumbents without owning fabrication assets. Infineon Technologies leverages its captive manufacturing in RF resonators to sustain pricing power across European automotive programs. Texas Instruments anchors its position through deep backward integration into gallium arsenide substrate supply. Qualcomm differentiates by concentrating design resources on millimeter wave tunable filters for next-generation base station architectures.
Passive tunable integrated circuits are semiconductor devices that adjust impedance, frequency response, or phase characteristics through external control voltages or digital commands, typically fabricated on silicon-on-insulator or compound semiconductor substrates with thin-film barium strontium titanate or MEMS capacitor elements for precision tuning. These components enable dynamic reconfiguration of RF front ends, allowing single hardware platforms to cover multiple frequency bands without mechanical switching. RF technology leads volume shipments due to saturation in sub-6 GHz infrastructure, while millimeter wave technology captures the fastest expansion as 5G-Advanced deployments multiply antenna count per site. Filters command the largest margin pool among product types because process tolerances directly determine insertion loss and out-of-band rejection performance.
The FCC in the United States mandates electromagnetic interference compliance through Part 15 rules that constrain tunable circuit architectures and spurious emission profiles. ETSI harmonized standards in Europe enforce spectral efficiency thresholds that elevate technical barriers for non-compliant suppliers. China's MIIT imposes domestic certification protocols on base station components that foreign manufacturers must navigate through local testing laboratories. Stakeholders should monitor how spectrum reallocation proceedings in major economies reshape frequency band priorities and therefore tuning range requirements across their product portfolios.
Market Dynamics
Network densification for 5G-Advanced infrastructure is compressing design cycles for passive tunable integrated circuits while simultaneously fragmenting procurement authority across carrier procurement teams and original equipment manufacturers.
Growth Catalysts
- Sub-6 GHz spectrum exhaustion:Carrier aggregation requirements in urban markets are multiplying filter count per base station, directly expanding addressable component volume.
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon-based etching chemistries is accelerating adoption of dry-process barium strontium titanate deposition for environmental compliance.
- Silicon-on-insulator substrate maturation:Foundry yield improvements at 200mm and 300mm wafer formats are reducing unit economics for tunable capacitor arrays.
Market Restraints
- Compound semiconductor supply concentration:Gallium arsenide and indium phosphide substrate production clusters in East Asian foundries create single-source vulnerability for high-frequency designs.
- Thin-film process tolerance limits:Variation in barium strontium titanate stoichiometry directly degrades temperature stability, constraining automotive qualification timelines.
- REACH substance restrictions:Candidate list expansions for SVHCs complicate lead-free solder alternatives and electrode material selection.
Strategic Opportunities
- Open RAN disaggregation:Interface standardization by the O-RAN Alliance is creating entry points for specialized filter vendors into previously integrated radio unit supply chains.
- India production-linked incentives:PLI scheme disbursements for telecom equipment manufacturing are attracting module assembly investments that localize tuning component sourcing.
- Millimeter wave small cell densification:Street-level deployment in Japanese urban corridors is generating demand for temperature-compensated tunable filters with sub-1 dB insertion loss.
Industry Challenges
- RF-MEMS reliability qualification:Accelerated lifetime testing for mechanical switching elements extends product development schedules by 18-24 months.
- Multi-band tuning algorithm integration:Digital control interface standardization gaps between baseband processor vendors and filter suppliers complicate system-level optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Tunable Integrated Circuits Market |
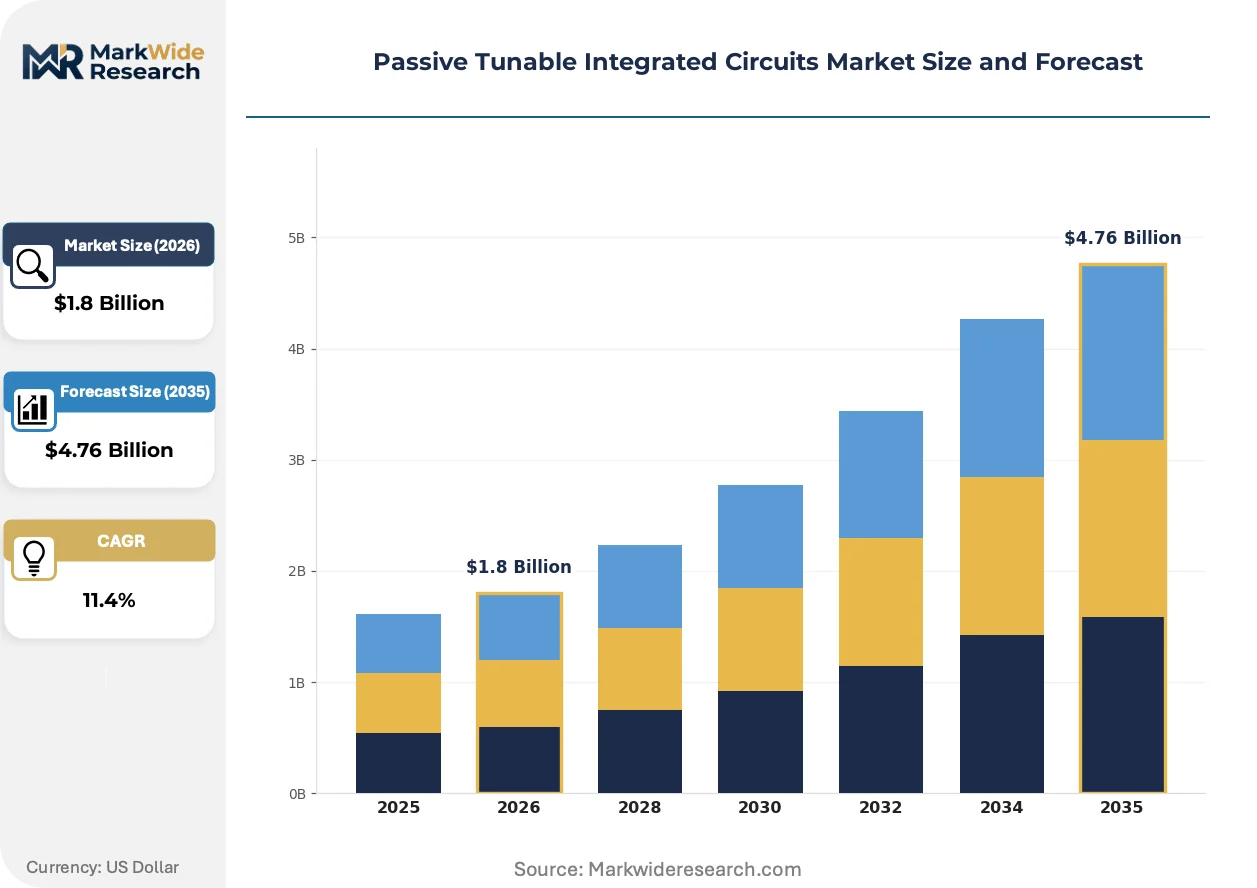
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resonators, Filters, Amplifiers, Mixers Technology: RF, Microwave, Millimeter Wave, Optical End User: Telecommunications, Aerospace, Consumer Electronics, Automotive Application: Data Transmission, Signal Processing, Frequency Synthesis, Network Switching |
| Companies Covered | Infineon Technologies, Renesas Electronics, Texas Instruments, Qualcomm, NXP Semiconductors, Analog Devices, STMicroelectronics, Microchip Technology, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Tunable Integrated Circuits Market Evolving Landscape
Material substitution and architectural simplification are converging to reduce part count in radio frequency front ends while elevating performance thresholds for linearity and power handling.
Thin-film barium strontium titanate on silicon substrates is rendering obsolete ceramic-based discrete tunable capacitors in sub-6 GHz infrastructure. Tier-one base station original equipment manufacturers are qualifying these integrated solutions for massive MIMO deployments. The shift eliminates wire-bond interconnects and reduces board area by 60%.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of photoresist and cleaning chemistries in European fabrication facilities. Process engineering teams are qualifying aqueous-based stripping alternatives. Automotive-qualified passive tunable integrated circuits face extended requalification timelines as material sets change.
Carrier procurement organizations are consolidating supplier panels and mandating multi-year fixed-price agreements with volume commitments. Equipment vendors are responding by dual-sourcing critical tuning components and investing in second-source qualification programs. This pattern is most pronounced in Chinese state-owned carrier procurement frameworks.
Passive Tunable Integrated Circuits Market Segmentation
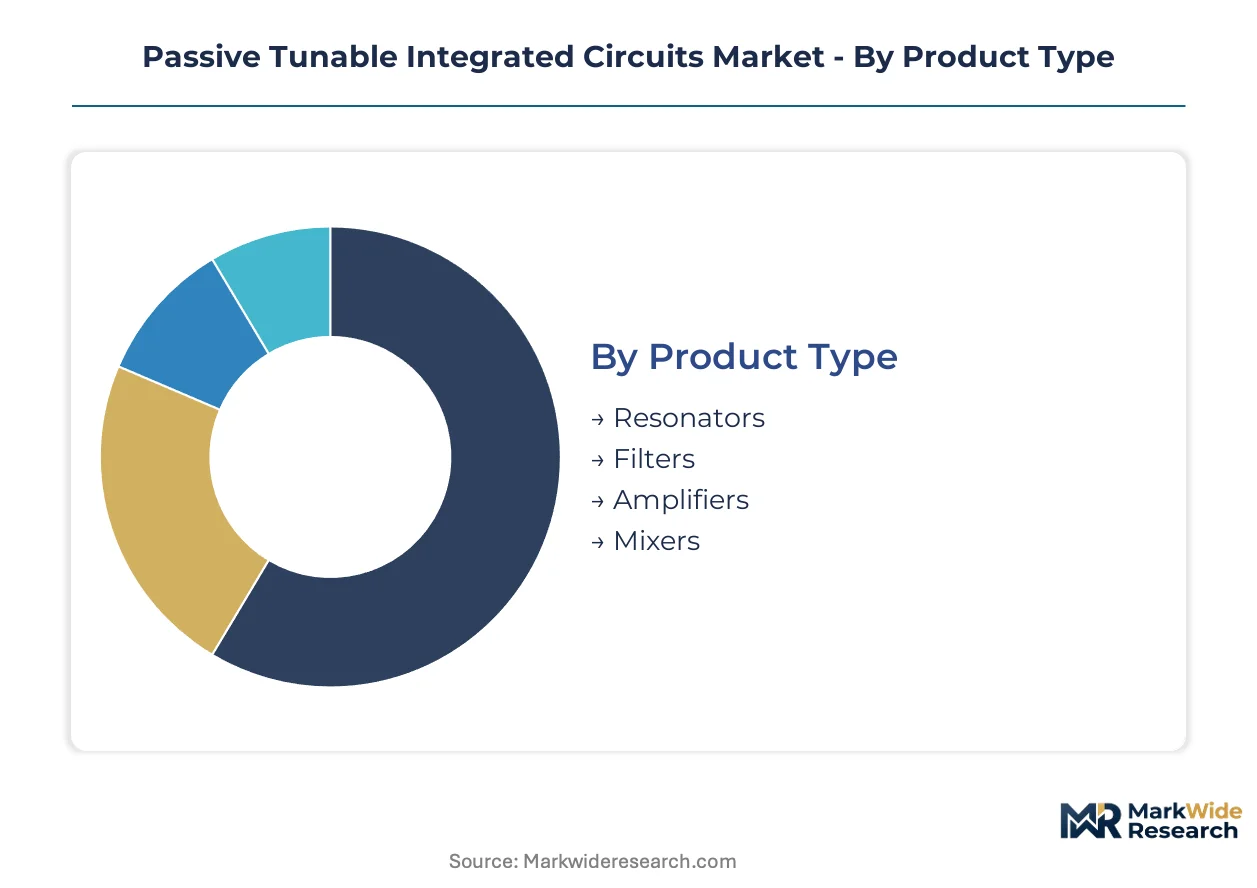
Segmentation in passive tunable integrated circuits reveals distinct service intensity profiles across product categories. Component complexity and failure modes dictate aftermarket support requirements, with RF front-end elements demanding more intensive calibration protocols than passive filtering stages.
Product Type:
After-sales service intensity varies sharply across product categories, with precision-tuned elements requiring field recalibration while simpler passive stages need only standard replacement protocols.
- Filters:Thin-film barium strontium titanate structures achieve sub-1 dB insertion loss in massive MIMO configurations. Demand concentrates in Chinese state-owned carrier procurement frameworks where multi-year fixed-price agreements mandate dual-source qualification programs.
- Resonators:RF resonators fabricated on gallium arsenide substrates anchor frequency stability in automotive radar modules. European automotive programs drive qualification timelines as REACH substance restrictions force reformulation of electrode materials.
- Amplifiers:Linear power stages require thermal management integration.
- Mixers:Frequency conversion elements serve heterodyne architectures.
Filters hold the largest share; momentum sits with resonators.
Technology:
Cost tier stratification separates mature silicon-on-insulator processes from compound semiconductor alternatives, with substrate material costs driving 3-5x differentiation between RF and millimeter wave implementations.
- RF:Silicon-on-insulator substrates at 200mm and 300mm wafer formats now yield production economics competitive with ceramic discrete alternatives. Sub-6 GHz infrastructure saturation across urban Japanese and South Korean markets sustains volume shipments.
- Millimeter Wave:Temperature-compensated architectures address street-level small cell densification in Japanese urban corridors. Antenna count multiplication per site under 5G-Advanced specifications generates steepest expansion trajectory across all technology tiers.
- Microwave:Intermediate frequency bands serve satellite backhaul links.
- Optical:Photonic integration enables tunable laser control.
RF technology dominates current procurement volumes; millimeter wave captures the fastest share gains.
End User:
Customer type fragmentation separates capital-intensive infrastructure deployers from high-volume consumer electronics manufacturers, with procurement authority diverging across carrier engineering teams and original equipment manufacturer supply chain functions.
- Telecommunications:Base station original equipment manufacturers qualify integrated solutions for massive MIMO deployments. China's MIIT domestic certification protocols require foreign suppliers to navigate local testing laboratories.
- Automotive:Radar module integration demands automotive-qualified temperature stability specifications. Barium strontium titanate stoichiometry variation constraints extend qualification timelines as material sets change under REACH directives.
- Aerospace:Satellite payloads require radiation-hardened tuning elements.
- Consumer Electronics:Smartphone RF front ends prioritize miniaturization.
Telecommunications commands the largest addressable base; automotive exhibits the most demanding qualification barriers.
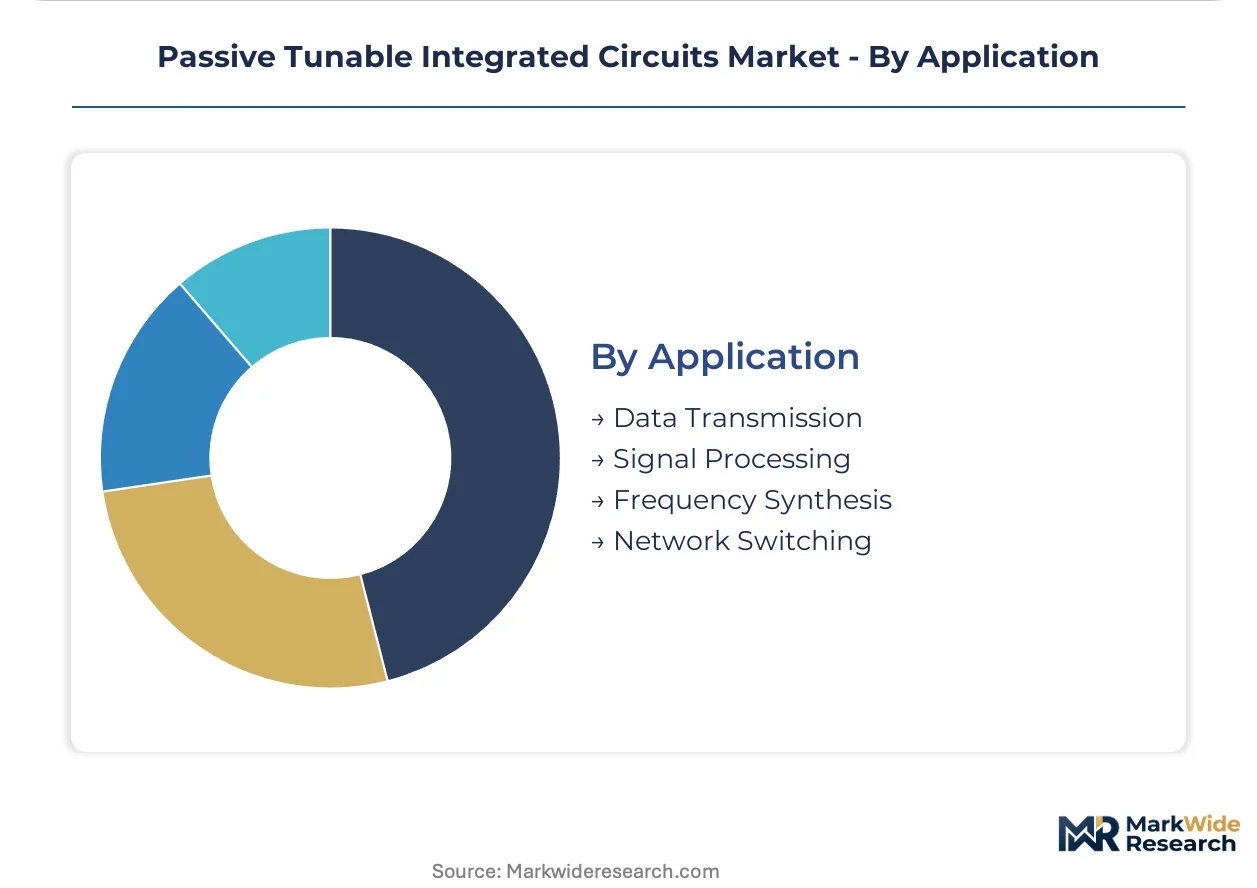
Application:
Application maturity curves separate established signal processing functions from emerging network switching architectures, with deployment timelines stretching from legacy 4G infrastructure through 5G-Advanced disaggregation.
- Data Transmission:Carrier aggregation requirements in urban markets multiply filter count per base station. FCC Part 15 electromagnetic interference compliance rules constrain tunable circuit architectures for equipment targeting United States deployment.
- Signal Processing:Digital control interface integration with baseband processors complicates system-level optimization. Multi-band tuning algorithm standardization gaps between processor vendors and filter suppliers fragment procurement coordination.
- Frequency Synthesis:Local oscillator chains require phase-locked loop integration.
- Network Switching:Open RAN disaggregation creates entry points for specialized vendors.
Data transmission anchors current revenue concentration; network switching emerges as the structural growth vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for telecom equipment manufacturing is attracting module assembly investments that localize tuning component sourcing. China's MIIT domestic certification protocols require foreign suppliers to navigate local testing laboratories. Germany's REACH substance restrictions force reformulation of electrode materials for automotive-qualified components.
China
Domestic base station deployment outpaces other national markets, concentrating demand for massive MIMO filter arrays. MIIT certification protocols mandate local testing laboratory navigation for foreign manufacturers. Shenzhen and Shanghai industrial clusters host qualification programs for thin-film barium strontium titanate deposition processes.
United States
Carrier densification for 5G-Advanced infrastructure multiplies antenna count per site in urban corridors. FCC Part 15 electromagnetic interference compliance rules constrain tunable circuit architectures for equipment targeting domestic deployment. Greater Boston and Austin semiconductor clusters sustain fabless design activity for RF front-end integration.
Germany
European automotive programs drive qualification timelines for radar module integration. ECHA REACH candidate list expansions for SVHCs complicate lead-free solder alternatives and electrode material selection. Bavaria and Baden-Württemberg host captive manufacturing operations for RF resonator production.
Japan
Street-level small cell densification in urban corridors generates demand for temperature-compensated tunable filters. METI industrial standards harmonize with ETSI spectral efficiency thresholds for base station component qualification. Tokyo-Osaka industrial corridor anchors millimeter wave technology development for 5G-Advanced specifications.
India
Production-linked incentive scheme disbursements for telecom equipment manufacturing attract module assembly investments. TRAI spectrum allocation proceedings reshape frequency band priorities for tuning range requirements. Karnataka and Tamil Nadu industrial corridors localize sourcing for filter and resonator components.
Passive Tunable Integrated Circuits Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: captive manufacturers with in-house substrate production, fabless designers leveraging foundry capacity fragmentation, and diversified semiconductor conglomerates with RF specialization. Competitive positioning depends on backward integration into gallium arsenide supply, millimeter wave design concentration, and automotive qualification timelines. Dominant moves include dual-source qualification programs and second-source partnerships with carrier procurement frameworks.
Among European captive manufacturers, Infineon Technologies exemplifies the integrated production archetype through RF resonator fabrication. Texas Instruments anchors the substrate-control tier with upstream integration into gallium arsenide supply. Qualcomm occupies the specialized design position, concentrating resources on millimeter wave tunable filters for base station architectures.
| Leading Market Players |
|---|
| Infineon Technologies |
| Renesas Electronics |
| Texas Instruments |
| Qualcomm |
| NXP Semiconductors |
| Analog Devices |
| STMicroelectronics |
| Microchip Technology |
| Broadcom |
| Others |
Value Network & Pricing Analysis
Overcapacity in 200mm silicon-on-insulator foundry capacity across Taiwan and South Korea compresses wafer pricing while simultaneously fragmenting bargaining power between fabless designers and captive manufacturers. This utilization dynamic forces tier-one base station original equipment manufacturers toward multi-year fixed-price agreements that lock in volume commitments against spot-market volatility.
Pricing Analysis
Certification level (automotive AEC-Q200 vs. commercial-grade) creates the primary spread between premium and standard tiers. Pricing stratifies across automotive-qualified, infrastructure-grade, and consumer-electronics tiers, with REACH-compliant material sets commanding premiums in European procurement frameworks. Cost compression in commercial-grade filters is intensifying because Chinese state-owned carriers consolidate supplier panels. Automotive radar module integrators exhibit least price sensitivity due to extended requalification timelines that deter supplier switching.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for gallium arsenide substrate sourcing. Production concentrates in Taiwan, South Korea, and Japan for compound semiconductor wafers, while China hosts thin-film barium strontium titanate deposition capacity. Raw material dependencies include high-purity gallium arsenide ingots, barium strontium titanate precursor chemicals, and photoresist formulations. Single-source vulnerability persists for 300mm silicon-on-insulator substrates. Distribution runs through tier-one module assemblers who qualify components for carrier-specific procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interface standardization by the O-RAN Alliance transforms this market into a platform-economics inflection, where interoperability protocols enable specialized filter vendors to displace integrated radio unit incumbents.
For Market Incumbents: Insulate automotive revenue streams by accelerating AEC-Q200 requalification timelines ahead of REACH substance restriction enforcement. Lock in multi-year fixed-price agreements with Chinese state-owned carriers before foundry capacity fragmentation erodes pricing power. Prioritize backward integration into gallium arsenide substrate supply to defend against East Asian single-source vulnerability. For New Entrants and Emerging Players: Pursue millimeter wave small cell opportunities in Japanese urban corridors where temperature-compensated filter demand outpaces established supplier capacity. Target India's production-linked incentive scheme disbursements for telecom equipment manufacturing to localize module assembly relationships. Lead with O-RAN Alliance compliance as a go-to-market wedge against integrated incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a compound semiconductor consolidation play because substrate control and automotive qualification timelines create durable moats. Acquisition targets should display captive gallium arsenide supply or established MIIT certification pathways for Chinese market access. Watch O-RAN Alliance procurement volume disclosures as the signal for disaggregation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive gallium arsenide production insulates margin structures against East Asian foundry concentration. |
| Automotive Qualification Acceleration | AEC-Q200 certification ahead of REACH enforcement secures radar module sockets in European programs. |
| O-RAN Alliance Compliance Investment | Interface standardization opens previously integrated radio unit supply chains to specialized vendors. |
| India PLI Scheme Localization | Module assembly investments in Karnataka and Tamil Nadu corridors anchor carrier procurement relationships. |
| Dual-Source Qualification Programs | Second-source partnerships satisfy Chinese state-owned carrier mandates and reduce supply interruption risk. |
Research Methodology
Desk research of SEC filings from RF semiconductor suppliers, ECHA REACH candidate list updates, and O-RAN Alliance technical specifications preceded structured interviews with base station procurement managers, fabless design house CTOs, automotive radar module integrators, and foundry operations directors. Secondary validation drew from MIIT certification protocol documents, FCC Part 15 rulemaking dockets, and carrier capex disclosure transcripts. Bottom-up component demand models triangulated against top-down infrastructure investment forecasts.
Assumptions held fixed include Open RAN disaggregation pace, REACH substance restriction timelines, and 5G-Advanced deployment cadence across the analysis window. Segmentation dimensions modeled encompass product type complexity, technology tier cost structure, end-user procurement authority, and application maturity curve position. CAGRs derived from wafer shipment run-rates, filter count per base station estimates, and substrate pricing trajectories. Industry-specific inputs incorporated carrier aggregation requirements and temperature stability specifications for automotive qualification.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or spectrum reallocation proceedings would shift the trajectory. Forecasts reflect these documented assumptions. Material shifts in EU F-Gas Regulation enforcement stringency or gallium arsenide export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market