
 Passive and Interconnecting Electronic Components Market | 2026-2036
Passive and Interconnecting Electronic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Passive and Interconnecting Electronic Components Market Intelligence
The rising complexity of automotive systems, particularly for electric vehicles and advanced driver-assistance systems, is recalibrating the market's historical dependence on the consumer electronics segment. Murata Manufacturing Co., Ltd. leverages its leadership in multilayer ceramic capacitors to serve this shift. TE Connectivity Ltd. specializes in high-reliability connectors designed for harsh automotive and industrial environments. Amphenol Corporation competes with a highly diversified portfolio of interconnect products across multiple end markets, including telecommunications and aerospace.
Passive and interconnecting electronic components are devices that do not generate energy but instead dissipate, store, or connect it within a circuit. These components, including resistors, capacitors, and connectors, are manufactured from materials like ceramics and polymers to control current, voltage, and signal integrity. Capacitors, particularly multilayer ceramic types, constitute a significant value segment due to their use in power supply decoupling. The automotive and telecommunications sectors represent the fastest-growing application areas, outpacing the more mature consumer electronics market.
Compliance with environmental regulations is a critical market-access requirement for component manufacturers. The European Union's RoHS directive restricts hazardous substances, while the REACH regulation governs chemical usage, impacting material selection. In parallel, China's GB standards dictate technical specifications for components sold within its borders. Stakeholders must now prioritize investment in material science and supply chain diversification to manage geopolitical risks and meet evolving performance demands.
Market Dynamics
The market's structural axis is tilting from consumer electronics toward high-reliability automotive and industrial sectors. This demand recalibration, driven by electric vehicle and 5G infrastructure builds, necessitates components with superior durability and thermal management capabilities.
Growth Catalysts
- 5G Network Deployment:The global rollout of 5G infrastructure requires a higher density of miniaturized passive components, particularly high-frequency capacitors and inductors, to manage signal integrity and power consumption in new devices.
- Automotive Electrification:The transition to electric vehicles and advanced driver-assistance systems dramatically increases the component count per vehicle for power management circuits, battery systems, and onboard chargers.
- National Semiconductor Policies:Government initiatives in countries like the United States and India are stimulating domestic electronics manufacturing, creating localized demand for passive components to support the broader semiconductor ecosystem.
Market Restraints
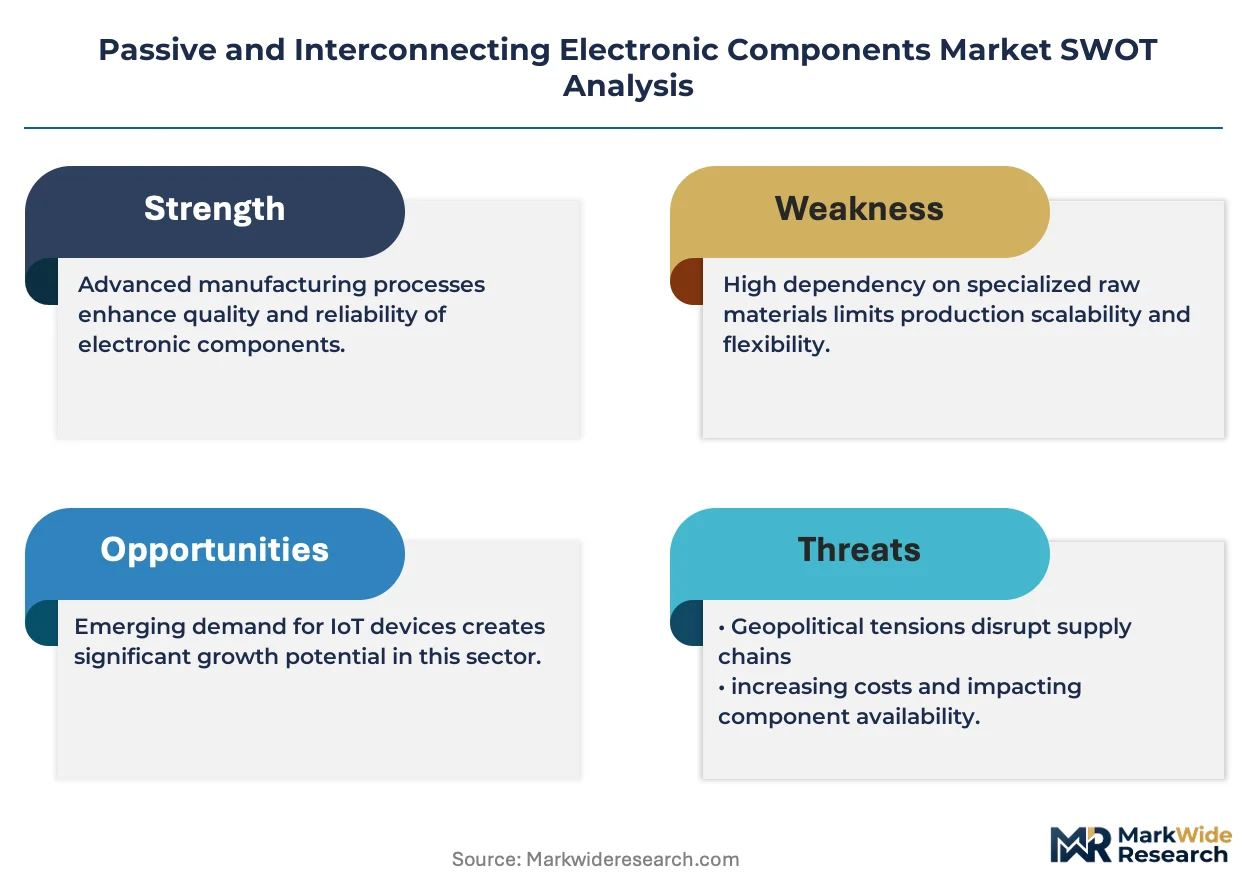
- Raw Material Volatility:Price fluctuations for key raw materials, including ceramic powders and specialized polymers, create margin pressure and complicate long-term cost planning for capacitor and connector manufacturers.
- Geopolitical Supply Risk:Heavy concentration of advanced component manufacturing and material processing in Taiwan and South Korea exposes the global supply chain to disruption from regional geopolitical tensions.
- Physical Miniaturization Limits:As components shrink, manufacturers face fundamental physical barriers related to heat dissipation and electrical leakage, which can impede performance gains in next-generation devices.
Strategic Opportunities
- Industrial IoT Expansion:The proliferation of connected sensors and actuators in factory automation and smart grid applications opens a new market for high-reliability, long-lifecycle interconnects and passive components.
- Energy Efficiency Mandates:Regulations like the EU Green Deal encourage the development of more efficient power supplies and converters, creating demand for advanced passive components that minimize energy loss.
- Power-over-Ethernet (PoE):The convergence of data and power delivery in commercial building infrastructure creates an opportunity for specialized connectors and magnetic components designed for higher power PoE standards.
Industry Challenges
- Regulatory Compliance Overhead:Manufacturers face significant operational burdens in tracking and complying with a divergent set of global regulations, such as the EU's RoHS and REACH alongside China's GB standards.
- Material Science Talent Scarcity:A shortage of engineers with expertise in advanced ceramics and polymer chemistry hampers the development of next-generation materials required for miniaturization and high-frequency performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive and Interconnecting Electronic Components Market |
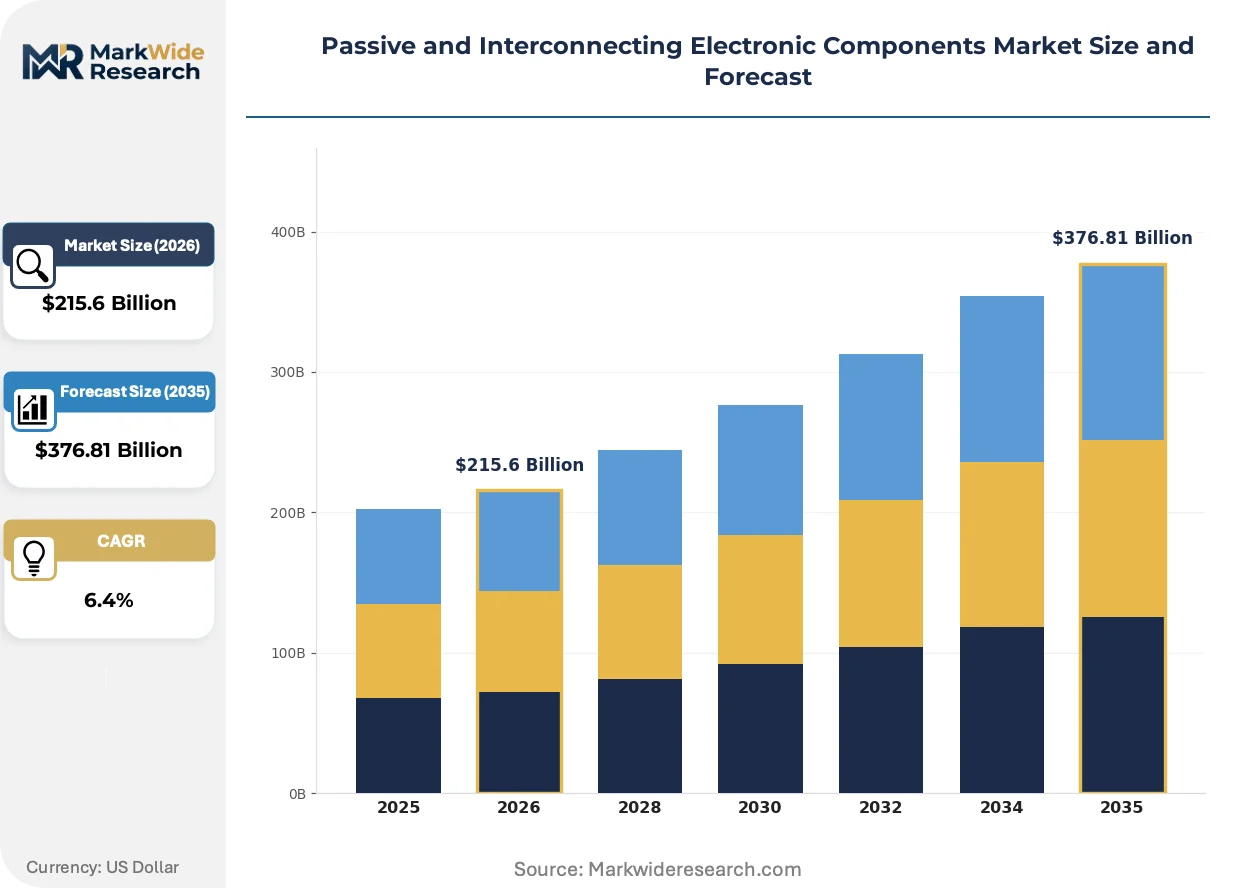
| Market Size in 2026 | $215.6 Billion |
| Market Size in 2035 | $376.81 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Resistors, Capacitors, Inductors, Connectors Material: Carbon, Ceramic, Metal, Polymer Application: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment End User: OEMs, Aftermarket Providers, Distributors, Retailers |
| Companies Covered | Murata Manufacturing Co., Ltd., TDK Corporation, TE Connectivity Ltd., AVX Corporation, Amphenol Corporation, Vishay Intertechnology, Inc., YAGEO Group, Samsung Electro-Mechanics, TAIYO YUDEN CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive and Interconnecting Electronic Components Market Strategic Shifts & Innovations
Material science breakthroughs are enabling new manufacturing processes to meet dual demands for miniaturization and high-reliability performance. This intersection redefines component design, especially for devices serving both 5G telecommunications and harsh automotive environments.
Low-temperature co-fired ceramic, or LTCC, technology allows for the creation of compact, multi-layered 3D circuit structures. The aerospace and telecommunications sectors are rapidly adopting it for radio frequency modules and integrated antenna systems. The technology's ability to embed passive components directly within a substrate is converging with system-in-package designs, enabling greater functional density.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure of supply chain environmental and social impacts. This regulation is forcing component manufacturers to implement robust traceability systems for raw materials like tantalum and cobalt. Automotive and industrial OEMs, who are most exposed to CSRD's scope, are now prioritizing suppliers with transparent and verifiable supply chain data.
Automotive and industrial original equipment manufacturers are shifting towards platform-based design for electronic subsystems. This model favors pre-validated component libraries over sourcing individual parts for each new project, disrupting traditional, relationship-based sales cycles. This trend is most pronounced in the electric vehicle sector, where standardization across multiple vehicle models is critical for achieving cost and scale efficiencies.
Passive and Interconnecting Electronic Components Market Segmentation
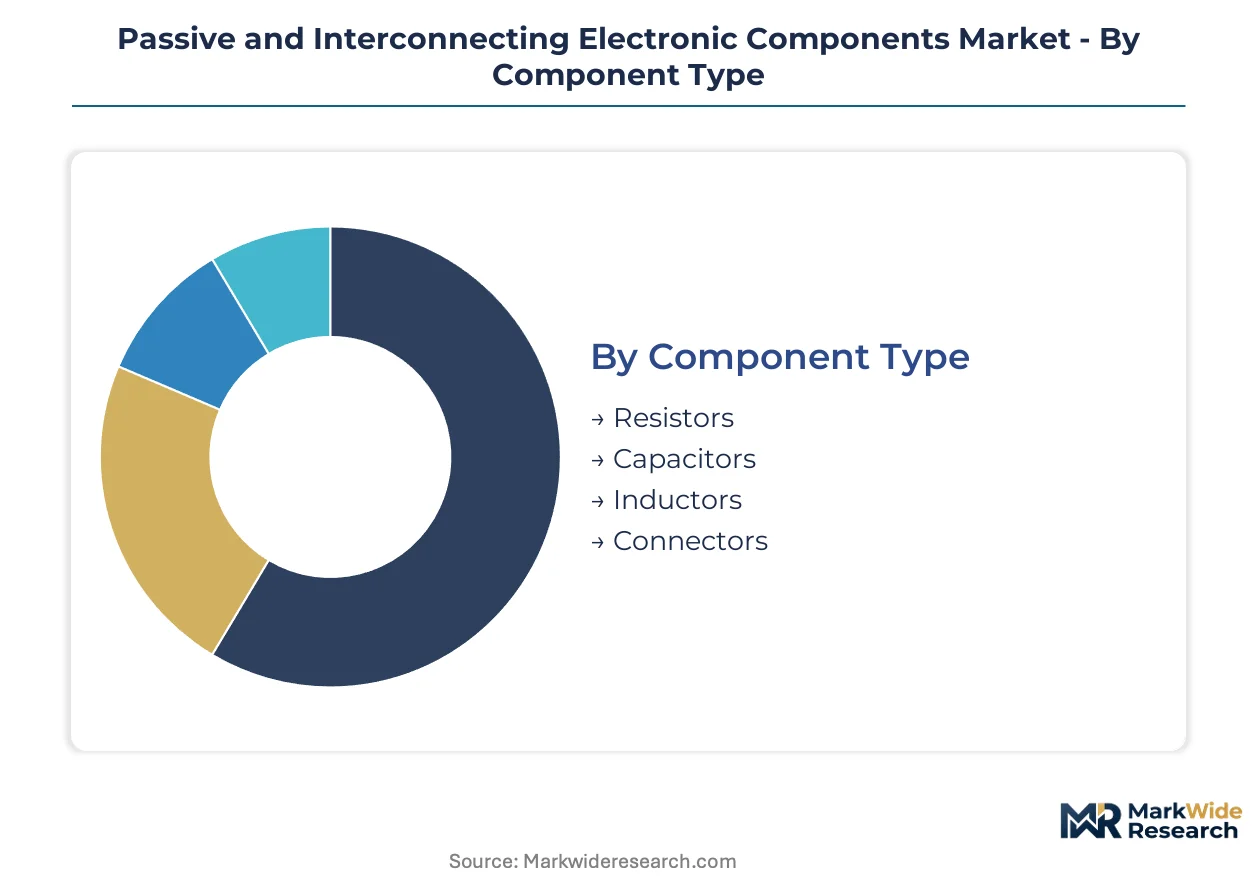
The market for passive and interconnecting electronic components is dissected across critical dimensions to illuminate demand patterns and supply dynamics. Understanding these segments reveals where technological investments are concentrated and which end-use sectors drive volume expansion. This granular analysis provides clarity on evolving market structures.
Component Type:
The component type segment reflects a spectrum from highly standardized parts to custom-engineered solutions, influencing production scales and supply chain complexity across the industry.
- Capacitors:These devices store electrical energy in an electric field, often using dielectric materials like ceramic or polymer. Multilayer ceramic capacitors (MLCCs) offer high capacitance in compact form factors. Demand concentrates in the automotive sector, particularly for electric vehicles, driven by the need for power supply decoupling and energy storage in high-voltage systems.
- Connectors:Connectors provide separable electrical and mechanical links between circuits, facilitating modularity and maintenance within electronic systems. They are manufactured from metal alloys and engineering polymers. The telecommunications sector, especially 5G infrastructure deployment, drives demand for high-frequency, high-reliability connectors that ensure signal integrity in complex network architectures.
- Resistors:These components regulate current flow, dissipating energy as heat, and are fundamental for circuit protection and signal conditioning in consumer electronics.
- Inductors:Inductors store energy in a magnetic field, often used for filtering, energy conversion, and impedance matching in power supply applications.
Most installed capacity flows through Capacitors. Expansion is steepest in Connectors.
Material:
The choice of material directly impacts component performance, manufacturing cost, and environmental compliance, establishing distinct cost tiers across the production landscape.
- Ceramic:Ceramic materials, such as barium titanate, form the dielectric layers in multilayer ceramic capacitors and substrates for high-frequency modules. They offer excellent dielectric properties and thermal stability. Automotive electrification and 5G network expansion are driving demand for advanced ceramic formulations, particularly for compact, high-temperature passive components.
- Metal:Metals like copper, brass, and various alloys are crucial for conductor paths, contacts, and shielding in connectors and inductors. Their electrical conductivity and mechanical properties are essential. Industrial IoT applications and harsh environment automotive systems necessitate high-purity metal components, ensuring long-term reliability and resistance to corrosion.
- Polymer:Polymers provide insulation, encapsulation, and structural support in various components, offering flexibility and lightweight properties for consumer devices.
- Carbon:Carbon-based materials are used in resistors and some conductive elements, prized for their stable resistive properties and cost-effectiveness.
The largest volume consumption is in Ceramic. Innovation is concentrated in Metal.
Application:
Application segments delineate the primary end-use sectors, reflecting diverse volume requirements and performance specifications for passive and interconnecting components.
- Automotive:This sector demands components engineered for extreme temperatures, vibration, and electromagnetic interference, supporting electric vehicle powertrains and advanced driver-assistance systems. Vehicle electrification dramatically increases the component count per car, driving demand for high-reliability capacitors, inductors, and connectors capable of handling higher power densities.
- Telecommunications:Components here must support high-frequency signal transmission and power delivery for 5G base stations, data centers, and user devices. Miniaturization is a critical design parameter. Global 5G network deployment drives significant demand for miniaturized, high-frequency passive components and specialized connectors to manage signal integrity and power efficiency.
- Consumer Electronics:This segment requires cost-effective, miniaturized components for smartphones, laptops, and wearables, prioritizing compact form factors and power efficiency.
- Industrial Equipment:Components for industrial applications need high durability and long lifecycles, supporting factory automation, power generation, and robust control systems.
The established market base resides in Consumer Electronics. New opportunities are concentrated in Automotive.
End User:
End user segments define the primary purchasers and integrators of electronic components, influencing sales channels, service requirements, and procurement strategies across the value chain.
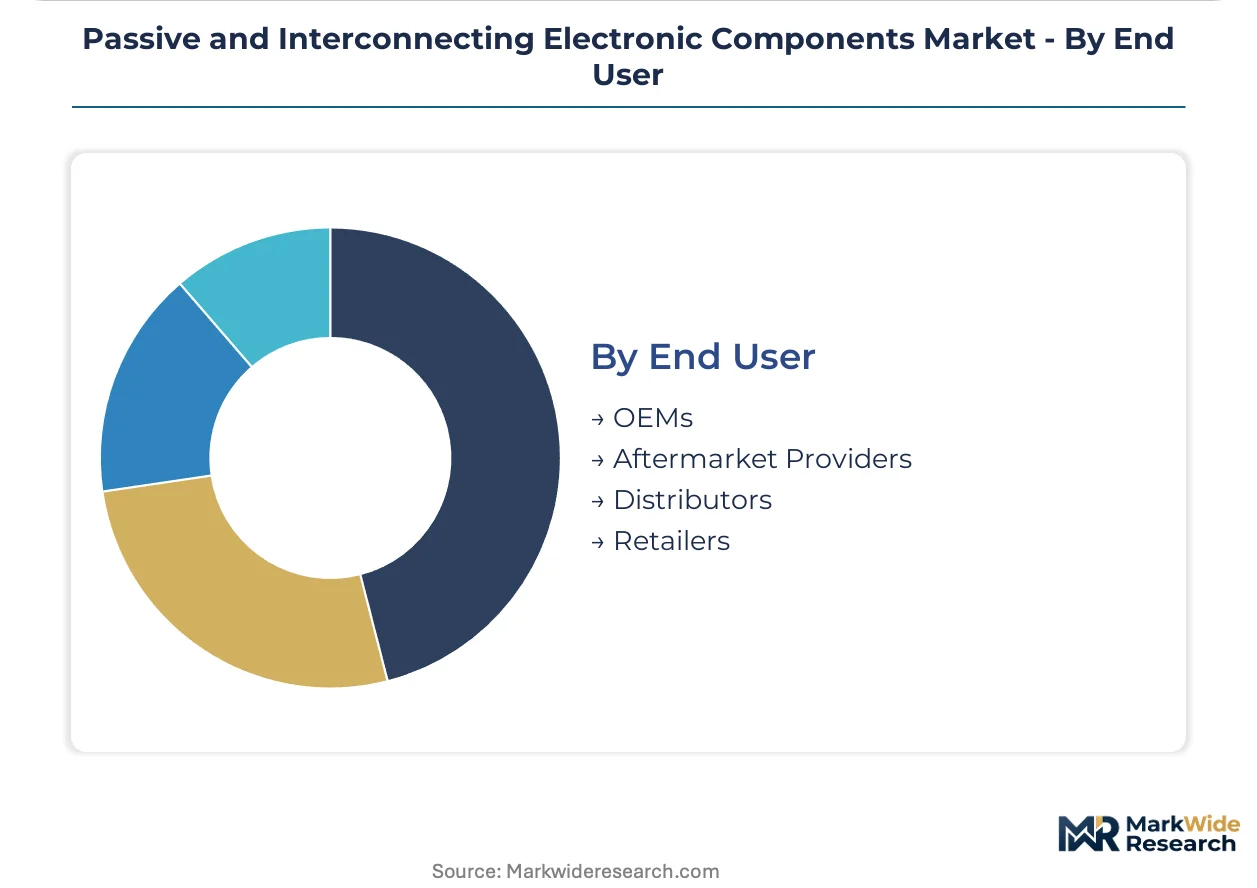
- OEMs:Original Equipment Manufacturers integrate passive and interconnecting components directly into their final products, requiring high-volume supply and often custom specifications. Automotive and telecommunications OEMs demand components that meet stringent performance, reliability, and regulatory compliance standards for their advanced systems and devices.
- Distributors:Distributors act as intermediaries, stocking and supplying components to a broad range of smaller OEMs, contract manufacturers, and repair shops. They manage inventory and logistics. They serve as a critical channel for accessing specialized components and managing supply chain risks, particularly for customers requiring diverse product portfolios or smaller order quantities.
- Aftermarket Providers:These entities supply components for repair, maintenance, and upgrades of existing equipment, focusing on availability and compatibility with legacy systems.
- Retailers:Retailers primarily serve hobbyists, educational institutions, and small-scale prototyping, offering a selection of general-purpose components for individual projects.
The dominant purchasing power lies with OEMs. Growth in accessibility is driven by Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance costs and geopolitical risks are recalibrating manufacturing footprints across the industry. This environment incentivizes production migration to regions offering favorable operating conditions. Strategic investments in material science and supply chain diversification now characterize regional development.
South Korea
South Korean component manufacturers are heavily investing in advanced materials for 5G and automotive applications. The country's Ministry of Trade, Industry and Energy supports R&D initiatives for next-generation semiconductor components. Companies in the Gyeonggi Province, particularly around Seoul, drive innovation in high-frequency MLCCs and specialized connectors.
United States
Demand for high-reliability passive components in the United States stems from defense and automotive electrification programs. Government initiatives like the IRA and CHIPS Act stimulate domestic electronics manufacturing, aiming to secure critical supply chains. Silicon Valley and Austin, Texas, host significant R&D and advanced packaging facilities for specialized components.
Germany
German automotive OEMs drive substantial demand for durable and thermally stable passive components and interconnects. The EU Green Deal encourages the development of energy-efficient power electronics, impacting material selection for capacitors and inductors. The Bavaria region, home to major automotive and industrial players, concentrates expertise in high-voltage power management components.
China
China's rapid 5G infrastructure build-out and electric vehicle production create immense volume demand for miniaturized components. The country's GB standards dictate technical specifications, influencing local and international manufacturers operating within its borders. Shenzhen, a major electronics manufacturing hub, sees extensive production of resistors, capacitors, and connectors for domestic and export markets.
India
India's PLI scheme for electronics manufacturing is fostering localized production of passive components to reduce import dependency. This policy aims to build a robust domestic supply chain for consumer electronics and automotive applications. Bengaluru, known as India's Silicon Valley, is witnessing increased investment in component assembly and testing facilities.
Passive and Interconnecting Electronic Components Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers scale production to meet rising demand from automotive and 5G sectors. The market exhibits a tiered structure, with a few global leaders providing a broad portfolio and numerous specialized players focusing on niche applications. Strategic partnerships for material development and technology licensing are prevalent competitive moves. Companies are also pursuing portfolio diversification to mitigate reliance on single end-markets.
Within the premium-tier segment, Murata Manufacturing Co., Ltd. exemplifies leadership in advanced ceramic components, particularly MLCCs for demanding automotive and 5G applications. TE Connectivity Ltd. occupies a strong position in high-reliability connectors designed for harsh environments, serving critical automotive and industrial needs. Amphenol Corporation represents a diversified interconnect specialist, anchoring a broad product portfolio across multiple end markets including telecommunications and aerospace. These entities leverage extensive R&D and global manufacturing footprints, often engaging in strategic alliances to accelerate material science advancements. Their market presence underscores the industry's focus on specialized performance and reliability.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| TE Connectivity Ltd. |
| AVX Corporation |
| Amphenol Corporation |
| Vishay Intertechnology, Inc. |
| YAGEO Group |
| Samsung Electro-Mechanics |
| TAIYO YUDEN CO., LTD. |
| Others |
Cost & Logistics Intelligence
Low-temperature co-fired ceramic technology adoption is reshaping component manufacturing costs while simultaneously concentrating specialized production capabilities in key Asian hubs.
Pricing Analysis
Direct-to-OEM discount structures dominate pricing for high-volume passive components. Pricing stratifies across premium, standard, and economy tiers based on certification level and customization requirements. Raw material volatility, particularly for ceramic powders, creates ongoing pricing pressure. Automotive OEMs exhibit the lowest price sensitivity for mission-critical parts, while consumer electronics buyers remain highly price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements are increasingly mandated by automotive and telecommunications OEMs for critical components. Geographic supply concentration remains high in Taiwan and South Korea for advanced manufacturing, with China holding significant raw material processing. Key dependencies include specialized ceramic powders and high-purity metal alloys. Geopolitical tensions represent a significant structural supply chain risk, while distribution runs through a hybrid model combining direct sales with extensive distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for passive and interconnecting electronic components presents a geographic-arbitrage play, driven by differing labor costs and environmental regulatory stringencies between East Asia and Europe.
For Market Incumbents: Anticipate continued demand for high-reliability components by expanding capacity in strategic regional hubs. Invest in advanced material science R&D to counter physical miniaturization limits and emerging competitive threats from specialized players. Reinforce channel control by offering pre-validated component libraries to platform-based OEMs. Bolster supply chain resilience through multi-country material sourcing to mitigate geopolitical risks.
For New Entrants and Emerging Players: Capture white space in industrial IoT applications by developing long-lifecycle interconnects. The most penetrable segment lies within specialized power-over-Ethernet components for commercial building infrastructure. Focus on niche solutions for energy efficiency mandates, targeting advanced passive components that minimize energy loss. A direct-to-developer go-to-market angle can bypass established distribution channels.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with strong intellectual property in advanced materials. Long-term viability rests on companies capable of navigating stringent environmental regulations like the EU Green Deal. Target acquisition archetypes include firms with established OEM relationships in automotive electrification. The signal to watch is successful commercialization of next-generation ceramic formulations for high-frequency applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Supports localized electronics manufacturing initiatives under India's PLI scheme. |
| Material Science R&D Investment | Addresses physical miniaturization limits and performance requirements for 5G devices. |
| Supply Chain Traceability System | Ensures compliance with EU Corporate Sustainability Reporting Directive for raw materials. |
| Platform-Based Design Partnership | Aligns with automotive OEM shift towards pre-validated component libraries for EVs. |
| LTCC Technology Integration | Enables compact, multi-layered 3D circuit structures for aerospace and telecommunications RF modules. |
Research Approach
Coverage spans East Asia, North America, and Europe, with primary inputs from each region. This involved interviews with OEM platform engineers, procurement leads, material science directors, and R&D specialists. Secondary validation drew from industry association reports, government electronics manufacturing policies, and company financial disclosures. A bottom-up approach to market sizing was triangulated with top-down validation against macroeconomic indicators.
Market value and volume were modeled at the component type, material, application, and end-user granularity levels. An industry-specific dimension, content per vehicle for electric vehicles, was also integrated. Compound annual growth rates were derived from historical trends and projected technological adoption rates across the analysis window. Key forecast inputs included 5G network deployment schedules and automotive electrification roadmaps.
Geopolitical tensions, raw material price volatility, and evolving environmental regulations are the dominant revision risks to the market outlook. Forecasts reflect assumptions regarding technological advancements and stable trade policies. Deviation in any major geopolitical event or a sustained material supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Elastomeric Connectors Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market