
 Anti-Sulfur Chip Resistors Market | 2026-2036
Anti-Sulfur Chip Resistors Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Sulfur Chip Resistors Market Insights
The premium and commodity tiers in anti-sulfur chip resistors is recalibrating around palladium-silver electrode formulations versus base-metal alternatives. Yageo Corporation leverages vertical integration in ceramic substrate production to sustain margin control across high-reliability tiers. Vishay Intertechnology anchors its position through automotive qualification breadth, while KOA Speer Electronics specializes in precision thin-film architectures for instrumentation.
Anti-sulfur chip resistors are passive electronic components engineered with noble-metal or specially treated electrodes to prevent silver sulfide formation in hydrogen sulfide environments, typically rated for operating temperatures from -55°C to +155°C and tolerance classes down to ±0.1%. Thick film variants dominate volume shipments into consumer electronics and industrial power supplies where cost sensitivity outweighs precision requirements. Thin film architectures command premium positioning in telecommunications infrastructure and automotive ADAS modules where stability under sulfur exposure determines system longevity.
REACH substance restrictions and RoHS hazardous substance limits in Europe shape material selection and electrode metallurgy across the supply base. EPA guidelines in the United States and China's GB standards on electronic component reliability add compliance layers for cross-border component flows. Stakeholders must track evolving automotive AEC-Q200 qualification scopes and sulfur test method harmonization between JEDEC and IEC committees.
Market Dynamics
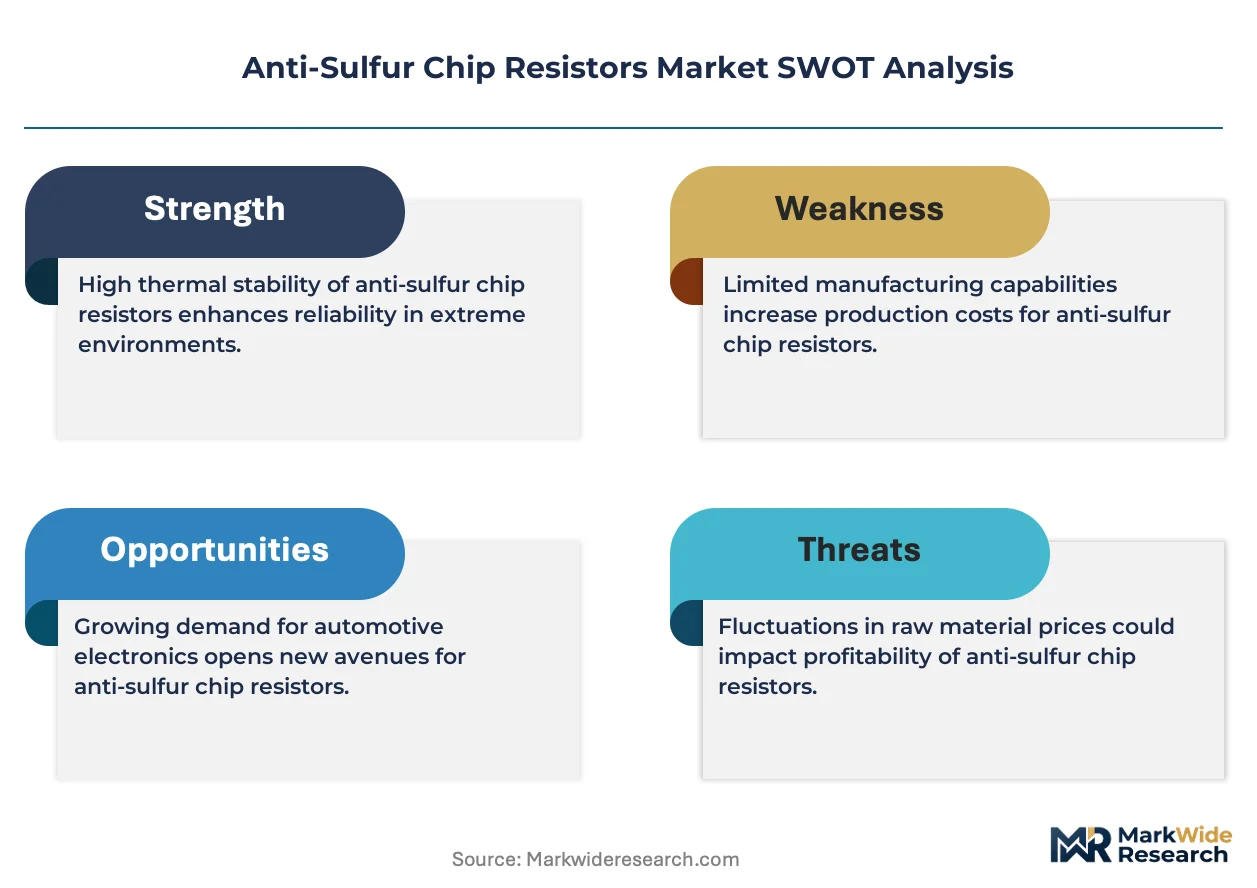
Palladium-silver electrode formulations are recalibrating competitive positioning across premium and commodity tiers, forcing suppliers to qualify base-metal alternatives under tightening automotive reliability standards.
Growth Catalysts
- Automotive electronics qualification:AEC-Q200 sulfur resistance testing is accelerating OEM adoption in ADAS modules and powertrain controllers across German and Japanese manufacturing bases.
- REACH substance restrictions:ECHA enforcement of electrode material purity standards is disqualifying legacy formulations and consolidating supplier lists toward certified noble-metal architectures.
- Semiconductor packaging clusters:Concentrated demand from South Korean and Taiwanese OSAT facilities is pulling thick-film volume through dedicated consignment channels.
Market Restraints
- Palladium price volatility:Noble-metal electrode costs fluctuate with London Bullion Market Association pricing, compressing margin buffers for mid-tier thick-film producers.
- East Asian supply concentration:Ceramic substrate and electrode paste fabrication concentrates in Japanese and South Korean chemical houses, creating single-source vulnerability.
- Base-metal performance ceiling:Copper-nickel electrodes exhibit sulfidation thresholds below 1000 ppm H2S, excluding them from oilfield and wastewater instrumentation.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor packaging are attracting resistor qualification programs from Taiwan-based passive component houses.
- Telecommunications infrastructure:5G base station deployments in sulfur-rich coastal geographies are specifying thin-film precision arrays for RF front-end stability.
- RoHS hazardous substance limits:European exemptions for high-reliability applications are channeling R&D toward lead-free glass encapsulants with equivalent hermeticity.
Industry Challenges
- Metallurgical engineering talent:Noble-metal electrode formulation expertise concentrates in aging Japanese and German technical workforces, constraining new facility ramp rates.
- JEDEC-IEC test method harmonization:Divergent sulfur exposure protocols between standards committees force dual qualification tracks, extending time-to-revenue for new product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Sulfur Chip Resistors Market |
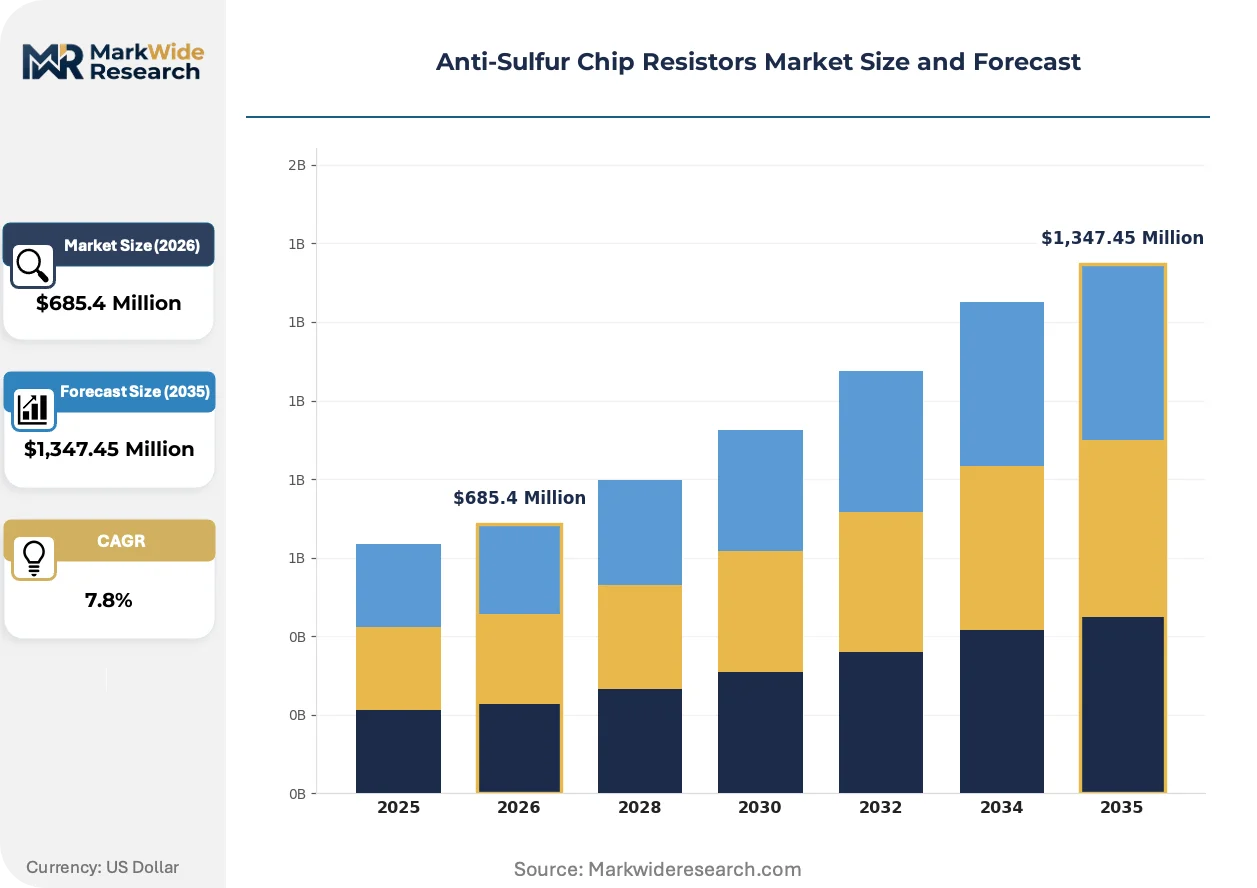
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Thick Film, Metal Film, Carbon Film Application: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Retailers Technology: Surface Mount, Through-Hole, Integrated Circuit, Hybrid |
| Companies Covered | Yageo Corporation, ROHM Semiconductor, Vishay Intertechnology, Panasonic Industry, KOA Speer Electronics, Bourns, Viking Tech, Walsin Technology Corporation, TT Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Sulfur Chip Resistors Market Trends and Innovations
Electrode metallurgy and test protocol standardization are absorbing capital and engineering resources across the supply base, compressing development cycles for sulfur-resistant architectures.
Ruthenium oxide-based thick-film formulations are absorbing qualification attention from automotive tier-1 suppliers seeking palladium reduction without sulfidation penalty. Power module manufacturers in Germany are validating these electrodes under combined temperature-humidity-sulfur stress profiles. The technology is absorbing margin pressure from noble-metal markets while maintaining AEC-Q200 compliance thresholds.
EPA guidelines on electronic waste recovery are mandating electrode material disclosure in US-bound component shipments, forcing reformulation documentation through customs clearance. Passive component distributors are building hazardous substance tracking databases to satisfy downstream automotive OEM audit requirements. The regulation most affects thick-film commodity shipments where material provenance documentation was historically sparse.
Consignment inventory models are displacing traditional spot purchasing in East Asian semiconductor packaging clusters. OSAT facilities in Taiwan and South Korea now specify vendor-managed stock programs with sulfur-resistance certification pre-validated at incoming inspection. The shift is most visible in high-volume consumer electronics where line-down risk from electrode failure exceeds carrying cost premiums.
Anti-Sulfur Chip Resistors Market Segmentation
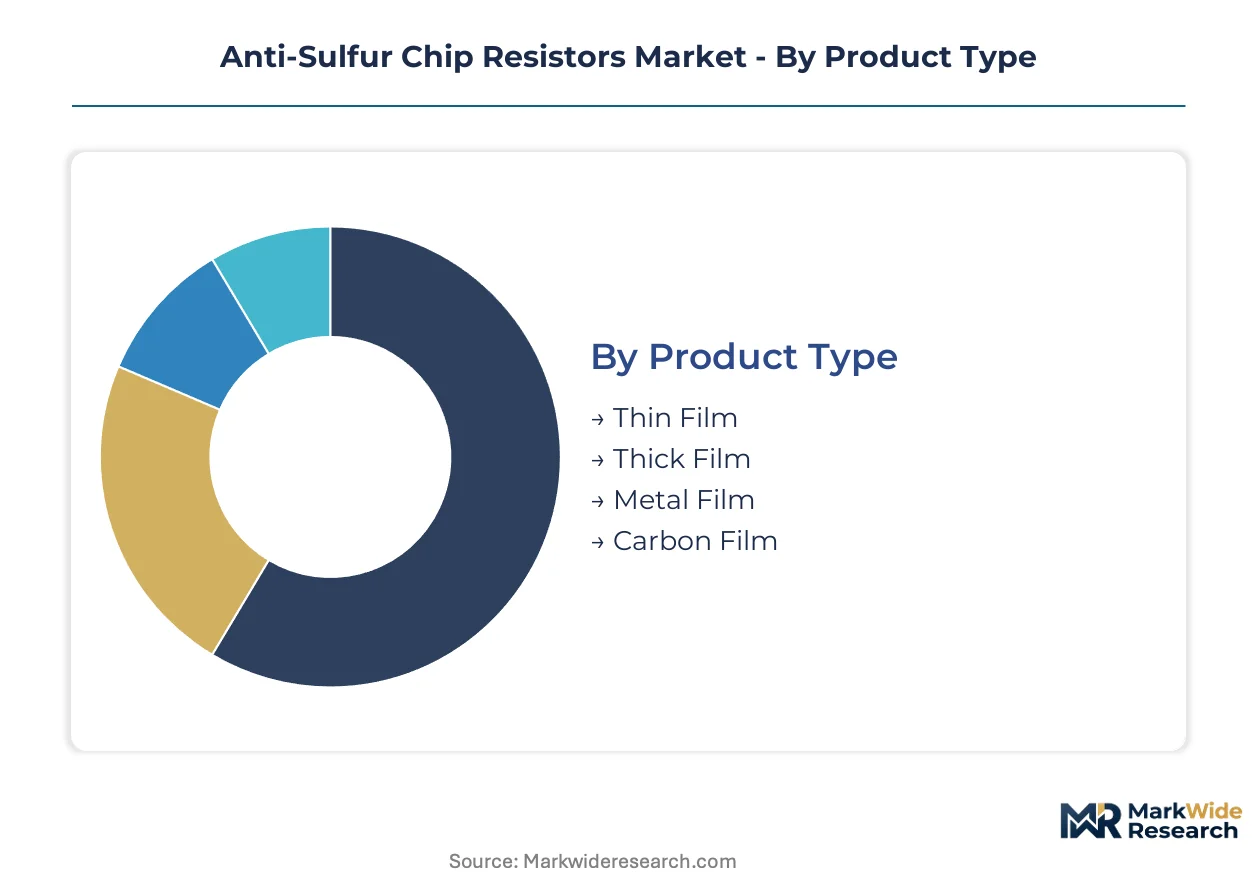
Anti-sulfur chip resistor procurement patterns diverge sharply across electrode architectures and mounting technologies. Component buyers prioritize sulfur-resistance certification tiers differently depending on end-use reliability requirements and geographic regulatory exposure.
Product Type:
Electrode metallurgy and film deposition thickness determine sulfur immunity thresholds and unit economics across resistor architectures.
- Thick Film:Ruthenium oxide or palladium-silver paste fired onto alumina substrates dominates volume shipments into cost-sensitive electronics. South Korean OSAT facilities pull thick-film volume through consignment channels for consumer electronics packaging.
- Thin Film:Sputtered nichrome or tantalum nitride layers on silicon or ceramic achieve ±0.1% tolerance and sub-50 ppm temperature coefficients. German automotive tier-1 suppliers specify thin-film arrays for ADAS modules exposed to hydrogen sulfide in tunnel and urban environments.
- Metal Film:Nickel-chromium alloys with glass passivation occupy mid-range precision applications.
- Carbon Film:Deposited carbon resistive elements serve legacy industrial equipment with modest sulfur exposure limits.
Mature deployment sits with Thick Film. Newer deployment is concentrated in Thin Film.
Application:
End-use sulfur exposure severity and failure cost dictate specification stringency across customer segments.
- Automotive:Powertrain controllers and battery management systems require AEC-Q200 sulfur resistance validation under combined temperature-humidity stress. Japanese OEMs in Toyota City and Nagoya manufacturing corridors specify noble-metal electrodes exclusively for under-hood electronics.
- Telecommunications:5G base station RF front-ends in coastal geographies with geothermal sulfur emissions demand thin-film precision stability. Taiwanese equipment manufacturers specify anti-sulfur resistors for base stations deployed across sulfur-rich volcanic zones in Indonesia and the Philippines.
- Consumer Electronics:Smartphones and wearables prioritize cost-optimized thick-film solutions with baseline sulfur protection.
- Industrial Equipment:Oilfield instrumentation and wastewater treatment sensors face intermittent high-concentration H2S exposure.
Procurement volume concentrates in Automotive. Specification tightening is accelerating fastest in Telecommunications.
End User:
Supply chain position determines qualification burden and inventory model preferences across the procurement base.
- OEMs:German automotive OEMs maintain approved vendor lists with electrode material disclosure requirements under EPA guidelines for US-bound shipments. Direct procurement contracts specify JEDEC and IEC dual-qualified resistor families.
- Tier-1 Suppliers:Continental and Bosch-tier suppliers manage consignment inventory at OSAT facilities in Taiwan and South Korea.
- Aftermarket Providers:Independent distributors serve repair networks with cross-reference qualified alternatives.
- Retailers:Component distributors stock commodity thick-film lines for low-volume industrial maintenance.
Margin capture sits with OEMs. Channel expansion is concentrating in Tier-1 Suppliers.
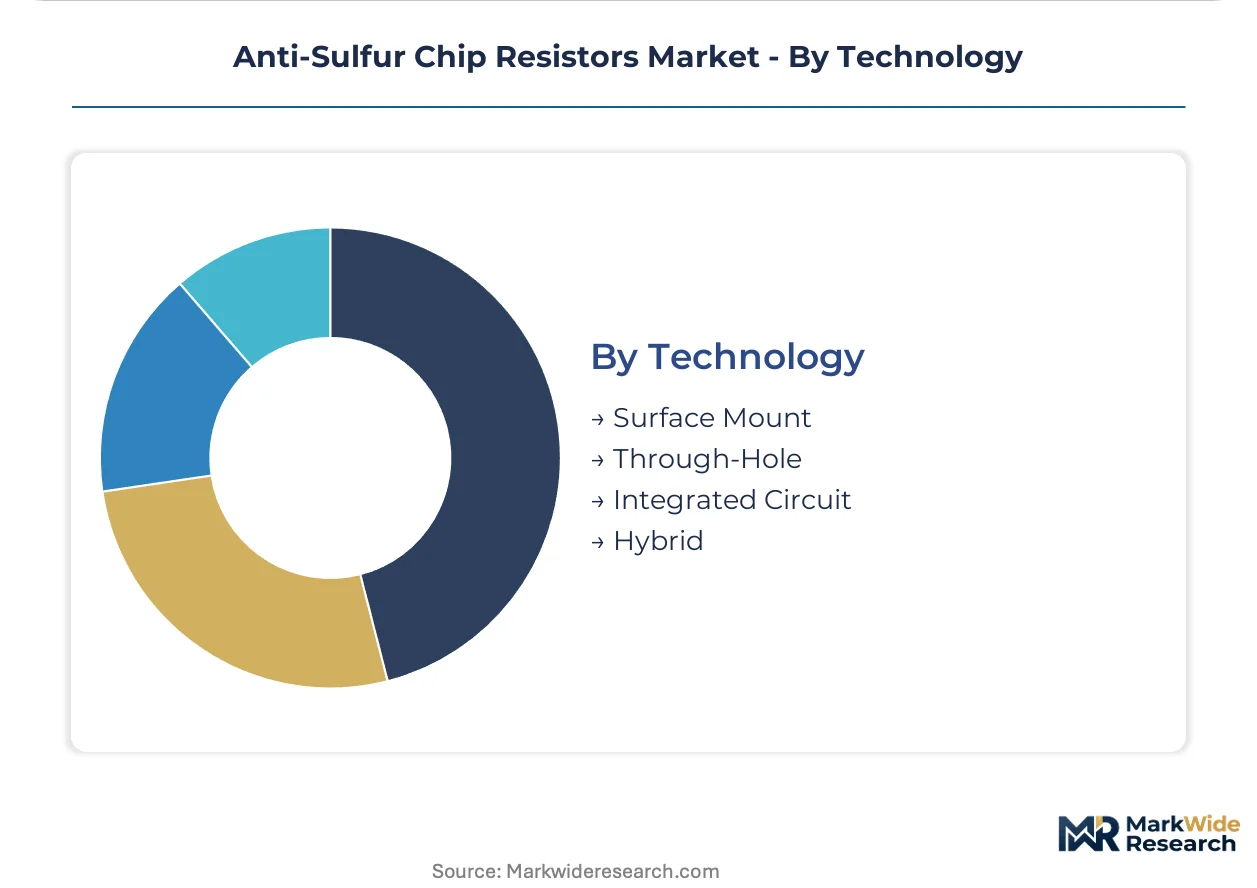
Technology:
Mounting and integration density requirements shape resistor package selection alongside sulfur resistance needs.
- Surface Mount:0402 to 1206 case sizes dominate PCB real estate-constrained designs. Taiwanese semiconductor packaging clusters specify surface-mount anti-sulfur resistors for smartphone motherboard miniaturization.
- Through-Hole:Axial and radial leaded formats persist in high-voltage industrial power supplies requiring mechanical strain relief.
- Integrated Circuit:Embedded resistor networks within multi-chip modules reduce interconnect parasitics.
- Hybrid:Mixed mounting approaches accommodate legacy system retrofits with partial SMT conversion.
Volume production sits with Surface Mount. Hybrid formats are gaining share in industrial retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toyota City and the Nagoya manufacturing corridor anchor procurement of noble-metal electrode resistors for Japanese automotive electronics. German suppliers in Stuttgart and Munich corridors specify AEC-Q200 qualified components for powertrain systems. Taiwanese OSAT clusters in Hsinchu and Tainan drive consignment inventory models for thick-film volume.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich corridors demand AEC-Q200 sulfur resistance validation for battery management systems. REACH substance restrictions enforced by ECHA disqualify legacy electrode formulations lacking material purity documentation. Bosch and Continental procurement teams specify noble-metal architectures exclusively for under-hood electronics.
Japan
Toyota City and Nagoya manufacturing bases require noble-metal electrodes for powertrain controllers exposed to tunnel and urban hydrogen sulfide environments. METI industrial standards on component reliability shape qualification protocols for domestic OEMs. Osaka-based chemical houses concentrate electrode paste fabrication, creating supply concentration for resistor manufacturers.
South Korea
OSAT facilities in Seoul and Suwon pull thick-film anti-sulfur resistors through vendor-managed inventory programs. GB standards on electronic component reliability from China add compliance layers for cross-border component flows. Samsung Electronics and SK Hynix packaging operations specify pre-validated sulfur-resistance certification at incoming inspection.
Taiwan
Hsinchu Science Park semiconductor packaging clusters specify surface-mount anti-sulfur resistors for smartphone motherboard miniaturization. Taiwanese equipment manufacturers require thin-film precision stability for 5G base stations deployed across sulfur-rich volcanic zones in Indonesia and Philippines. TSMC ecosystem suppliers maintain consignment stock with dual JEDEC-IEC qualification.
United States
EPA guidelines on electronic waste recovery mandate electrode material disclosure for US-bound component shipments. Automotive OEMs in Michigan and Ohio maintain approved vendor lists with hazardous substance tracking databases. Detroit-area tier-1 suppliers specify JEDEC and IEC dual-qualified resistor families for domestic powertrain production.
Anti-Sulfur Chip Resistors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the anti-sulfur chip resistor supply base. The market structure concentrates around vertically integrated ceramic substrate manufacturers and specialized thin-film fabricators. Three strategic archetypes dominate: Japanese-German precision specialists, Taiwanese-Korean volume producers, and diversified passive component conglomerates. Capacity expansion in East Asian packaging corridors and strategic partnerships for electrode paste supply constitute the primary competitive moves.
Within the diversified conglomerate tier, Yageo Corporation and Vishay Intertechnology exemplify scale-driven positioning through captive ceramic substrate production and automotive qualification breadth respectively. KOA Speer Electronics represents the precision specialist archetype, occupying a position in thin-film architectures for instrumentation applications. ROHM Semiconductor and Panasonic Industry anchor Japanese-origin supply for domestic automotive OEM requirements.
| Leading Market Players |
|---|
| Yageo Corporation |
| ROHM Semiconductor |
| Vishay Intertechnology |
| Panasonic Industry |
| KOA Speer Electronics |
| Bourns |
| Viking Tech |
| Walsin Technology Corporation |
| TT Electronics |
| Others |
Pricing and Supply Chain Analysis
AEC-Q200 sulfur resistance mandates from German and Japanese automotive OEMs are forcing electrode paste suppliers to document noble-metal purity certifications, compressing margin buffers for thick-film producers unable to absorb qualification costs. This specification tightening concentrates procurement power among vertically integrated ceramic substrate manufacturers while fragmenting spot-market availability for commodity tiers.
Pricing Analysis
Value-based pricing anchored to AEC-Q200 certification tiers separates noble-metal electrode architectures from base-metal alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects tolerance precision, temperature coefficient stability, and sulfur exposure threshold guarantees. Cost compression in thick-film commodity segments is intensifying because South Korean OSAT facilities negotiate vendor-managed inventory contracts with pre-validated incoming inspection protocols. Tier-1 automotive suppliers exhibit lowest price sensitivity due to warranty exposure from field failures, while consumer electronics OEMs prioritize unit economics over certification depth.
Supply Chain Analysis
Reverse-logistics flows for failed resistor arrays in automotive powertrain controllers are minimal due to sealed-module replacement practices, though EPA electronic waste recovery guidelines mandate electrode material disclosure for refurbishment tracking. Ceramic substrate fabrication concentrates in Japan, South Korea, and Taiwan, with electrode paste chemistry anchored in Osaka-based chemical houses. Raw material dependencies include palladium-silver alloys, alumina substrates, and ruthenium oxide formulations. Single-source vulnerability in noble-metal electrode paste supply creates exposure to London Bullion Market Association price swings. Distribution runs through consignment inventory models at Taiwanese and South Korean semiconductor packaging clusters, displacing traditional spot purchasing for high-volume consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH substance restrictions and RoHS hazardous substance limits in Europe construct regulatory moats favoring incumbent suppliers with certified material provenance documentation.
For Market Incumbents: Hedge palladium price exposure through long-term offtake agreements with London Bullion Market Association refiners while accelerating ruthenium oxide electrode qualification to reduce noble-metal dependency. Defensive consolidation should target thin-film precision specialists in Japan and Germany to capture aging metallurgical engineering talent pools. Capacity addition in Indian semiconductor packaging corridors under PLI scheme incentives offers geographic diversification from East Asian concentration risk. For New Entrants and Emerging Players: Ruthenium oxide-based thick-film formulations offer a technology-first wedge into automotive tier-1 supplier qualification programs seeking palladium reduction without AEC-Q200 compliance penalty. The most penetrable white space sits with telecommunications infrastructure OEMs specifying thin-film precision arrays for 5G base stations in sulfur-rich coastal geographies. A go-to-market angle through vendor-managed inventory partnerships with Taiwanese OSAT facilities bypasses incumbent distributor lock-in. For Investors and Strategic Acquirers: The window for entry favors vertically integrated ceramic substrate manufacturers with captive electrode paste supply and existing automotive qualification breadth. Long-term viability over a multi-year horizon rests on sulfur test method harmonization between JEDEC and IEC committees reducing dual-qualification cost burdens. Acquisition target archetype: precision thin-film fabricators with instrumentation customer concentration and METI or ECHA pre-certification. The signal to watch is palladium price volatility spikes triggering accelerated base-metal alternative R&D commitments from tier-1 automotive suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Yageo Corporation's captive alumina supply sustains margin control across high-reliability tiers. |
| Ruthenium Oxide Electrode Qualification | Automotive tier-1 suppliers in Stuttgart validate palladium-reduced formulations under combined stress profiles. |
| Vendor-Managed Inventory Programs | Taiwanese OSAT facilities specify pre-validated sulfur-resistance certification at incoming inspection. |
| Dual JEDEC-IEC Qualification Investment | TSMC ecosystem suppliers reduce time-to-revenue for new resistor families through harmonized testing. |
| Indian PLI Scheme Facility Ramp | Taiwan-based passive component houses qualify resistor programs for semiconductor packaging growth. |
Research Methodology
Independent corroboration across primary interviews with passive component procurement directors, automotive electronics platform engineers, and electrode paste R&D leads, combined with secondary validation through AEC-Q200 test laboratory filings, ECHA REACH substance registration databases, and SEC 10-K disclosures from listed resistor manufacturers, underwrites the qualitative findings. Bottom-up triangulation across thick-film and thin-film shipment volumes from South Korean and Taiwanese customs data converges with top-down semiconductor packaging capacity estimates from OSAT facility announcements.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by electrode metallurgy, mounting technology, and end-use application. The analytical framework models resistor procurement patterns across automotive, telecommunications, consumer electronics, and industrial equipment segments, with additional dimensioning by regional regulatory cluster. CAGRs derive from fitted growth curves anchored to semiconductor packaging capacity expansion schedules and automotive electronics content-per-vehicle trends. Industry-specific forecast inputs include palladium price volatility indices and JEDEC-IEC test method harmonization progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained noble-metal price spikes or accelerated base-metal electrode performance breakthroughs. Practitioners should monitor ECHA enforcement actions on electrode material purity standards and palladium futures market volatility for early signals of margin compression or technology substitution inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market