
 Discrete Assortment Kits Market | 2026-2036
Discrete Assortment Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Discrete Assortment Kits Market Outlook
A shift from single-source to multi-source procurement is repositioning how OEMs secure passive component assortments. Würth Elektronik leverages captive manufacturing to control lead times for standard kit configurations. Digi-Key Electronics anchors North American distribution through its massive same-day shipping infrastructure. TE Connectivity specializes in application-specific assortments for automotive and industrial verticals.
Discrete assortment kits are curated collections of individual electronic components—resistors, capacitors, diodes, and transistors—organized by value, tolerance, or function, typically housed in compartmentalized cases for rapid prototyping and repair operations. These kits eliminate sourcing friction for engineers who otherwise face minimum order quantities and parametric search complexity across thousands of part numbers. Standard kits dominate volume shipments due to their predictable demand from educational institutions and field service operations, while custom kits capture margin pools from OEMs requiring application-matched component selections with lot-traceable documentation. Specialty kits targeting RF, high-voltage, or automotive-grade applications represent the fastest-expanding segment as design cycles compress and component qualification burdens intensify.
ISO 9001 and IECQ QC 080000 standards govern component traceability and hazardous substance controls across kit assembly operations, with FDA oversight applying where assortments enter diagnostic device supply chains. REACH and RoHS compliance in Europe and equivalent GB standards in China constrain material choices for packaging and component plating, effectively filtering which suppliers can serve multinational accounts. Stakeholders must monitor how evolving conflict-mineral disclosure rules and export control classifications for advanced semiconductors reshape kit content availability and sourcing geography requirements.
Market Dynamics
Electronics contract manufacturers are consolidating kit procurement under ISO 9001 traceability mandates, forcing passive component suppliers to restructure fulfillment networks around documented lot control and rapid configuration capabilities.
Growth Catalysts
- Automotive electrification:Tier-1 suppliers require AEC-Q200 qualified assortments for inverter and battery management prototyping, expanding kit volumes for high-reliability passive components.
- REACH substance restrictions:European ECHA enforcement against hexavalent chromium plating is redirecting OEM kit sourcing toward RoHS-certified supply chains with full material disclosure documentation.
- Shenzhen component clustering:Same-day kit configuration from concentrated passive distributors compresses prototype turnaround for consumer electronics OEMs.
Market Restraints
- Palladium price volatility:Electrode plating cost swings for multilayer ceramic capacitors destabilize kit pricing models and margin predictability for distributors.
- Wafer-level substrate concentration:Taiwan and South Korea dominance in passive component substrates creates geographic chokepoint risk for kit assemblers.
- MLCC case size miniaturization limits:Physical handling constraints below 0201 imperial format restrict automated kit assembly throughput and yield rates.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and component assembly are creating greenfield demand for traceable kit provisioning to contract manufacturers in Gujarat and Tamil Nadu.
- Medical device prototyping:FDA 21 CFR Part 820 quality system requirements for design controls are expanding demand for lot-traceable diagnostic-grade component assortments.
- Digital kit configurators:Parametric web tools allowing engineers to specify tolerance grades and temperature coefficients online are displacing traditional phone-fax procurement for custom assortments.
Industry Challenges
- Component obsolescence management:End-of-life notifications for legacy resistor series force kit suppliers to maintain dynamic BOM substitution databases with form-fit-function equivalents.
- IECQ QC 080000 certification timelines:Hazardous substance process management audits extend supplier qualification cycles by four to six months for multinational electronics brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Discrete Assortment Kits Market |
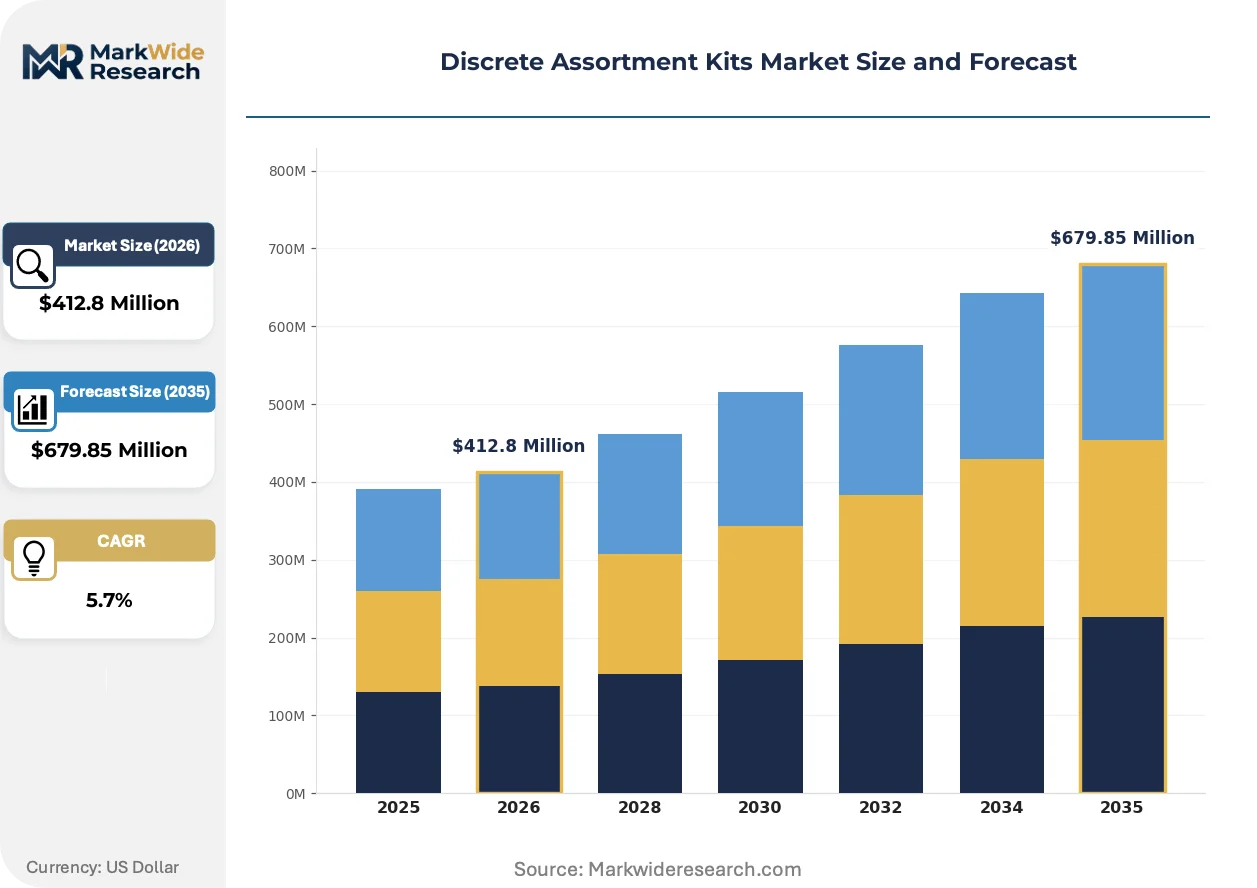
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $679.85 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kits, Custom Kits, Specialty Kits, Bulk Kits End User: Hospitals, Clinics, Laboratories, Educational Institutions Application: Diagnostic Use, Research Use, Educational Use, Industrial Use Packaging Type: Plastic Containers, Cardboard Boxes, Pouches, Blister Packs |
| Companies Covered | RS Components, Arrow Electronics, 3M Company, Würth Elektronik, Avnet, Inc., TE Connectivity, Digi-Key Electronics, Molex LLC, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Discrete Assortment Kits Market Strategic Shifts
Machine-readable packaging and automated kit fulfillment are compressing the interval between design specification and physical component availability, reshaping how engineering teams source passive electronics.
Smart labeling with embedded RFID and QR-coded parametric data is automating inventory reconciliation and counterfeit detection for high-value automotive and aerospace kit shipments. Tier-1 electronics manufacturing services providers in Mexico and Eastern Europe are mandating this capability for incoming passive component receipts. The technology is automating customs documentation and duty classification for cross-border kit movements, reducing clearance delays at ports of entry.
China's GB/T 26572 hazardous substance limits are tightening alignment with EU RoHS substance restrictions, creating regulatory convergence that simplifies kit content compliance for multinational OEMs serving both markets. MIIT enforcement of uniform marking requirements for electronic components is standardizing traceability data formats across Chinese passive manufacturers. Automotive and industrial verticals with dual-continent supply chains are the primary beneficiaries, consolidating kit sourcing onto fewer qualified supplier platforms.
Engineering procurement teams are consolidating vendor relationships onto distributors offering integrated BOM-to-kit fulfillment with parametric search and same-day shipping. Traditional catalog distributors with physical stocking presence are capturing share from manufacturer-direct channels for prototype quantities. This consolidation is most pronounced in North American and German markets where design cycle compression penalties exceed premium freight costs for rapid kit delivery.
Discrete Assortment Kits Market Segmentation
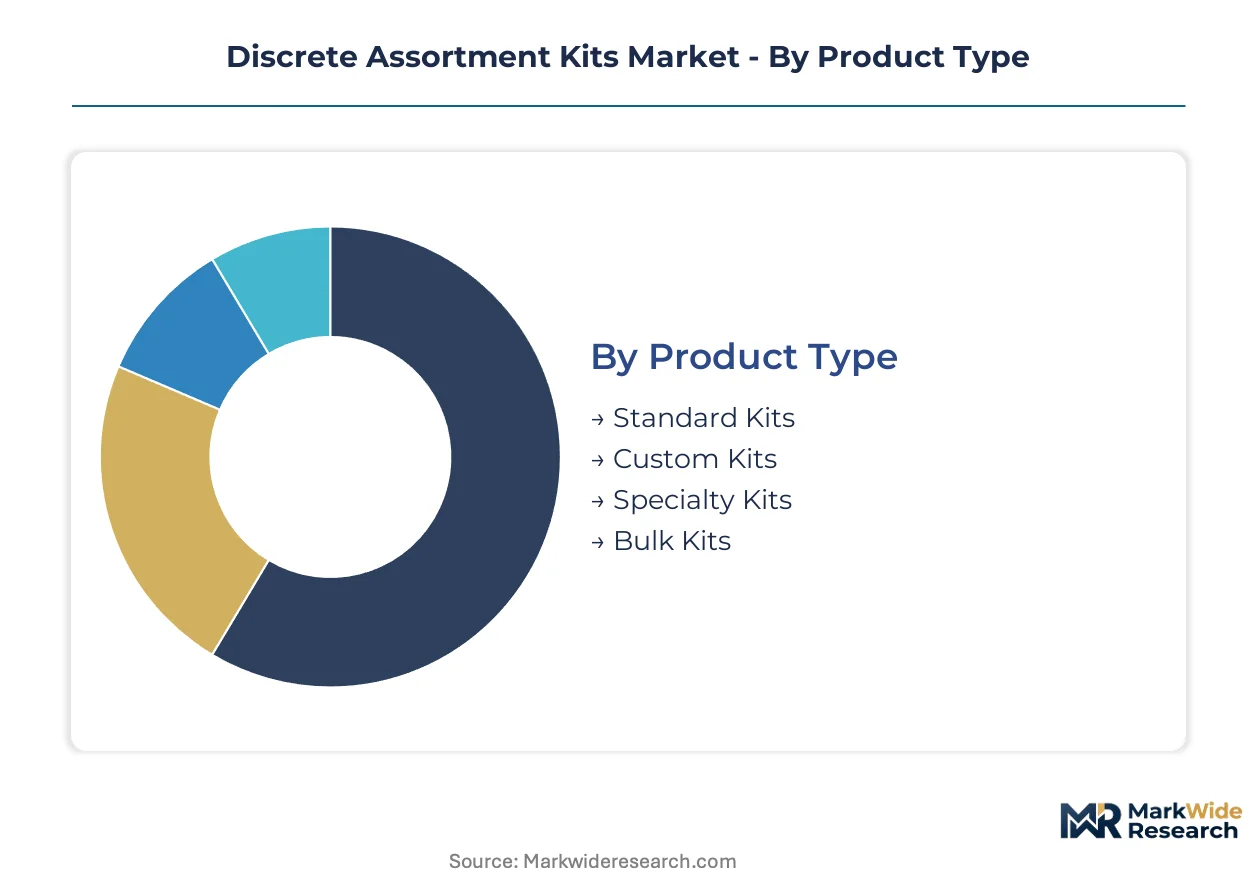
Discrete assortment kits segment across four critical dimensions that determine procurement patterns, margin structures, and regulatory exposure. Each category reflects distinct technical requirements and buyer behaviors that suppliers must navigate to capture value in this fragmented market.
Product Type:
Technical specifications and configuration complexity define competitive positioning across kit formats, with traceability requirements increasingly filtering which suppliers can serve multinational accounts.
- Standard Kits:Pre-configured collections of resistors, capacitors, and diodes organized by common value ranges and tolerances, typically stocked in compartmentalized plastic cases. Educational institutions in Germany and field service operations across the US Midwest generate predictable demand for these configurations, though margin compression from catalog distributors limits supplier profitability.
- Custom Kits:Application-matched component selections assembled to customer BOM specifications with full lot-traceable documentation per ISO 9001 and IECQ QC 080000 standards. Automotive Tier-1 suppliers in Stuttgart and Shenzhen contract manufacturers require these for inverter prototyping and battery management system development, capturing premium pricing through qualification burden reduction.
- Specialty Kits:Curated assortments targeting RF, high-voltage, or automotive-grade applications with AEC-Q200 qualified components.
- Bulk Kits:High-volume unconfigured component pools for internal kitting operations at large contract manufacturers.
Standard kits lead on scale; specialty kits lead on momentum.
End User:
Procurement sophistication and compliance burden vary sharply across buyer categories, with regulatory oversight intensity determining kit documentation requirements.
- Hospitals:Clinical engineering departments source traceable assortments for diagnostic equipment repair and maintenance, with FDA 21 CFR Part 820 quality system requirements governing component documentation. Demand concentrates in US metropolitan health systems and German university hospitals where equipment uptime penalties exceed kit procurement costs.
- Laboratories:Research facilities require lot-traceable components for experimental apparatus construction and calibration standard maintenance. Academic medical centers in Boston and Cambridge UK represent high-value accounts where publication-grade documentation requirements filter supplier eligibility.
- Clinics:Smaller healthcare facilities with limited in-house technical capabilities.
- Educational Institutions:Universities and technical colleges stocking standard kits for undergraduate electronics instruction.
Laboratories lead on margin; hospitals lead on volume stability.
Application:
Use-case specificity determines component grading requirements, with life-critical applications imposing the most stringent qualification protocols.
- Diagnostic Use:FDA-regulated applications in patient-facing medical equipment where component failure carries liability exposure. Kit suppliers must maintain dynamic BOM substitution databases with form-fit-function equivalents to address end-of-life notifications for legacy resistor series.
- Industrial Use:Factory automation and process control applications requiring extended temperature range components and humidity-resistant packaging. German industrial OEMs and Japanese manufacturing equipment builders specify these assortments for field deployment kits.
- Research Use:Non-regulated experimental applications prioritizing parametric breadth over qualification documentation.
- Educational Use:Training and instructional applications with minimal traceability requirements.
Industrial use leads on expansion velocity; diagnostic use leads on pricing power.
Packaging Type:
Physical container specifications interact with automated handling requirements and environmental regulations to shape procurement decisions.
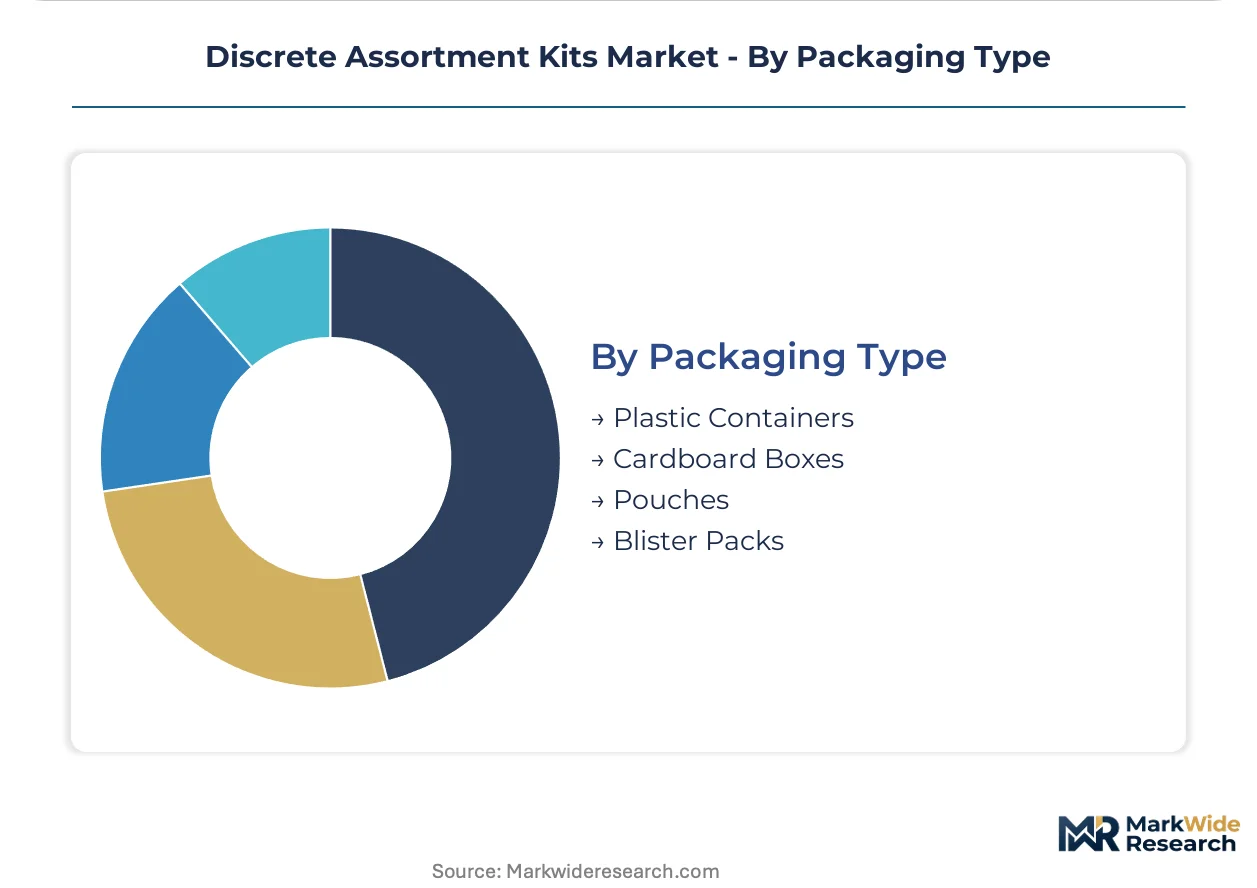
- Plastic Containers:Reusable compartmentalized cases with individual cell labeling for rapid component identification. REACH substance restrictions and ECHA enforcement against hazardous additives in European markets are redirecting sourcing toward RoHS-certified supply chains with full material disclosure documentation.
- Blister Packs:Individual component visibility with tamper-evident sealing for high-value automotive and aerospace shipments. Tier-1 electronics manufacturing services providers in Mexico and Eastern Europe mandate machine-readable packaging with embedded RFID for automated inventory reconciliation.
- Cardboard Boxes:Cost-minimized bulk packaging for internal kitting operations.
- Pouches:Flexible packaging for low-profile component storage and shipping efficiency.
Plastic containers lead on installed base; blister packs lead on technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing discrete assortment kit assembly toward jurisdictions where REACH compliance costs and ISO certification timelines create competitive gaps. Manufacturers migrate configuration operations to exploit these asymmetries while maintaining traceability documentation for multinational OEM accounts.
China
Shenzhen's passive component clustering enables same-day kit configuration for consumer electronics OEMs. MIIT enforcement of GB/T 26572 hazardous substance limits tightens alignment with EU RoHS standards, simplifying dual-market compliance. The Pearl River Delta concentrates contract manufacturers demanding rapid-turn custom assortments with full lot documentation.
Germany
Automotive Tier-1 suppliers in Stuttgart require AEC-Q200 qualified assortments for inverter prototyping, expanding demand for high-reliability passive kits. ECHA enforcement against hexavalent chromium plating redirects sourcing toward RoHS-certified supply chains with full material disclosure. Bavaria's industrial electronics sector drives standard kit consumption for field service operations.
United States
FDA 21 CFR Part 820 quality system requirements expand demand for lot-traceable diagnostic-grade component assortments in medical device prototyping. Clinical engineering departments in metropolitan health systems source traceable kits for diagnostic equipment repair. Greater Boston's academic medical centers represent high-value accounts with publication-grade documentation requirements.
India
PLI scheme incentives for semiconductor and component assembly create greenfield demand for traceable kit provisioning to contract manufacturers in Gujarat and Tamil Nadu. BIS standards alignment with IECQ QC 080000 accelerates supplier qualification for multinational electronics brands. Tamil Nadu's emerging electronics manufacturing clusters absorb bulk kit shipments for internal configuration operations.
Japan
METI industrial policy supports domestic kit assembly for automotive and industrial automation applications requiring extended temperature range components. JIS standards for electronic component marking standardize traceability data formats across passive manufacturers. Nagoya's manufacturing equipment builders specify humidity-resistant kit assortments for field deployment.
Discrete Assortment Kits Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue application-specific specialization and digital procurement interfaces. The vendor base stratifies across three maturity tiers: multinational distributors with captive logistics infrastructure, regional assemblers with ISO-certified configuration facilities, and niche specialists targeting AEC-Q200 or medical-grade qualification requirements. Dominant competitive moves include M&A to acquire traceability certification capabilities and strategic partnerships with contract manufacturers for embedded kit provisioning.
Among Germany-based fabricators, Würth Elektronik exemplifies the captive manufacturing archetype with in-house production control over standard kit configurations. TE Connectivity occupies a position within the application-specific tier, anchoring automotive and industrial vertical specialization. Digi-Key Electronics represents the distribution-centric model with same-day shipping infrastructure anchoring North American prototype demand. These three entities collectively illustrate how geographic origin and organizational structure map to competitive positioning in traceable component fulfillment.
| Leading Market Players |
|---|
| RS Components |
| Arrow Electronics |
| 3M Company |
| Würth Elektronik |
| Avnet, Inc. |
| TE Connectivity |
| Digi-Key Electronics |
| Molex LLC |
| Johnson Matthey |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists across Germany and Japan anchor kit assembly operations with conservative leverage profiles, translating balance-sheet discipline into stable pricing for AEC-Q200 qualified assortments while resisting margin erosion from catalog distributors.
Pricing Analysis
Distributor margin layers separate captive-manufactured standard kits from application-specific premium configurations. Three-tier pricing structure across automotive-grade, industrial-standard, and educational-economy levels reflects certification burden and traceability documentation depth. Cost compression in economy-tier standard kits intensifies as Shenzhen contract manufacturers consolidate procurement onto direct-import channels. Educational institutions exhibit highest price sensitivity, while automotive Tier-1 suppliers absorb premium positioning for lot-traceable custom assortments.
Supply Chain Analysis
Returns and refurbishment flows for blister-packaged automotive kits create reverse-logistics complexity at Tier-1 electronics manufacturing services providers in Mexico and Eastern Europe. Supply concentrates in China, Taiwan, and South Korea for MLCC substrates and passive component wafers, with assembly drawing from Shenzhen clustering and Stuttgart precision manufacturing. Palladium electrode plating and ceramic substrate feedstock expose kit assemblers to commodity price volatility. Distribution runs through authorized distributors with ISO-certified configuration facilities serving multinational OEM accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in traceability-automation investments that reduce IECQ QC 080000 compliance costs while capturing premium-tier shifts toward medical-grade diagnostic assortments.
For Market Incumbents: Deploy machine-readable packaging capabilities to defend against emerging digital-native configurators. Consolidate certification assets by acquiring regional assemblers with existing IECQ QC 080000 audits in India and Mexico. Channel control through embedded kit provisioning contracts with contract manufacturers protects against direct-import displacement from Shenzhen distributors. For New Entrants and Emerging Players: The gap between premium AEC-Q200 qualified kits and unbranded economy assortments offers entry positioning for mid-tier specialists. White-space targets include FDA-registered diagnostic-grade configurations for US metropolitan health systems and PLI-scheme-aligned traceable provisioning for Gujarat contract manufacturers. A go-to-market angle through parametric web configurators displaces traditional phone-fax procurement for custom assortments. For Investors and Strategic Acquirers: Valuations sit cheapest among ISO-certified regional assemblers lacking captive substrate supply but holding established automotive qualification relationships. Long-term viability across the analysis window hinges on traceability automation capex and geographic diversification beyond Taiwan-South Korea substrate dependence. Acquisition target archetype: mid-cap specialists with IECQ certification and underutilized configuration capacity in India or Eastern Europe. Monitor palladium price volatility and MIIT enforcement of GB/T 26572 marking requirements as inflection indicators for margin compression or regulatory consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive MLCC wafer sourcing reduces Taiwan chokepoint exposure for automotive kit assemblers. |
| Digital Kit Configurator Platform Launch | Parametric web tools displace traditional procurement at North American engineering teams. |
| IECQ QC 080000 Certification Investment | Accelerated supplier qualification timelines unlock multinational electronics brand accounts. |
| Strategic Partnership with Contract Manufacturers | Embedded provisioning agreements in Shenzhen and Stuttgart secure volume commitments. |
| RFID-Enabled Smart Labeling Deployment | Automated inventory reconciliation meets Tier-1 EMS mandates in Mexico and Eastern Europe. |
Study Parameters
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each market informing demand calibration and regulatory pathway mapping. The analysis combines structured interviews with kit procurement managers at contract manufacturers, quality assurance leads at automotive Tier-1 suppliers, and clinical engineering directors at US metropolitan health systems, validated against secondary sources including MIIT GB standard filings, ECHA REACH substance restriction updates, FDA 21 CFR Part 820 guidance documents, and SEC disclosures from listed distributors. Bottom-up shipment data from regional assemblers triangulates against top-down OEM procurement spend estimates.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models discrete assortment kit demand across product type, end user, application, and packaging format dimensions, with additional segmentation by regional regulatory cluster. CAGRs derive from fitted growth curves anchored to observable procurement pattern shifts, incorporating AEC-Q200 qualification expansion timelines, PLI scheme incentive disbursement schedules, and digital configurator adoption curves as industry-specific forecast inputs.
Caveats apply where palladium price volatility, Taiwan substrate supply disruptions, or ECHA enforcement intensity against hexavalent chromium plating could materially shift the outlook. Practitioners should monitor BIS alignment timelines with IECQ standards and FDA diagnostic device procurement budget cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market