
 Sputtering Equipment Cathode Market | 2026-2036
Sputtering Equipment Cathode Market Size, Share, and Industry Trends Forecast 2026-2036
Sputtering Equipment Cathode Market Outlook
Project finance for captive thin-film deposition lines is tilting competitive dynamics toward capital-rich equipment lessors and foundry operators. Applied Materials leverages its installed base of Endura platforms to sustain aftermarket cathode pull-through. Kurt J. Lesker anchors its position through specialized target-source integration for research-scale systems. Veeco Instruments competes in compound semiconductor applications where RF cathode precision commands premium positioning.
Sputtering equipment cathodes are consumable electrodes—typically fabricated from high-purity metals or alloys such as copper, titanium, or aluminum—that generate plasma for physical vapor deposition onto substrates. These components operate at power densities exceeding 10 W/cm² and require precise magnetic field confinement to achieve uniform film thicknesses critical for semiconductor interconnects, display panels, and optical coatings. Magnetron sputtering dominates current installations due to its deposition rate advantages in high-volume electronics manufacturing, while pulsed sputtering architectures are gaining traction in precision optical coatings where defect control supersedes throughput. Copper cathodes command the largest material value pool given their ubiquity in back-end-of-line semiconductor metallization, though titanium variants are displacing legacy aluminum in barrier layer applications.
FDA oversight of medical device coatings and EPA hazardous air pollutant standards for metalworking operations shape cathode material specifications and end-of-life handling protocols in the United States. REACH substance restrictions and RoHS compliance requirements in Europe constrain cadmium and hexavalent chromium content in target materials, directly influencing supplier qualification criteria. Stakeholders must monitor how evolving F-Gas Regulation thresholds and emerging PFAS restrictions in multiple jurisdictions will alter process gas selections and cathode surface conditioning chemistries.
Market Dynamics
Captive capacity expansion by Taiwan Semiconductor Manufacturing, Samsung Foundry, and Intel is compressing merchant equipment procurement cycles and forcing cathode suppliers to align with fab tool qualification timelines.
Growth Catalysts
- Advanced Node Logic:Taiwan and South Korea foundries are scaling 3nm and 2nm production lines, each requiring precision magnetron cathodes for copper barrier seed layers. Tool qualification windows are narrowing to 18 months.
- China MEE Emissions Standards:Tightening particulate and energy efficiency mandates are accelerating cathode replacement cycles in legacy display panel fabs across the Yangtze River Delta.
- Compound Semiconductor RF Devices:Gallium nitride power amplifiers for 5G base stations and radar systems are pulling specialized rotary cathode architectures into volume production.
Market Restraints
- High-Purity Copper Concentration:Five Japanese and German suppliers control 90% of 6N+ copper feedstock for semiconductor-grade targets, exposing cathode fabricators to price volatility and allocation risk.
- Magnet Array Technical Limitations:Erosion groove deepening beyond 8mm degrades magnetic field uniformity, capping cathode life at 3,000 kWh for advanced node applications.
- REACH Substance Restrictions:ECHA cadmium and hexavalent chromium limitations are disqualifying legacy alloy formulations from European display panel supply chains.
Strategic Opportunities
- India PLI Scheme:Semiconductor and display manufacturing incentives are attracting cathode-target integrators to establish localized deposition material supply for Vedanta-Foxconn and ISMC Digital fabs.
- Pulsed DC-DC Sputtering Convergence:Arc suppression electronics combined with rotating cylindrical cathodes are opening precision optical coating applications previously served by ion beam deposition.
- Used Cathode Reclamation Channels:Closed-loop precious metal recovery programs are emerging as a margin-protecting service layer for captive fab operators in Singapore and Arizona.
Industry Challenges
- Plasma Physics Talent Scarcity:Magnetron design and erosion simulation expertise resides with a shrinking cohort of specialists at national labs and legacy equipment OEMs.
- Multi-Site Qualification Burden:Cathode suppliers must replicate identical magnetic field profiles across fabs in Taiwan, Arizona, and Germany to maintain process equivalence for logic device yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sputtering Equipment Cathode Market |
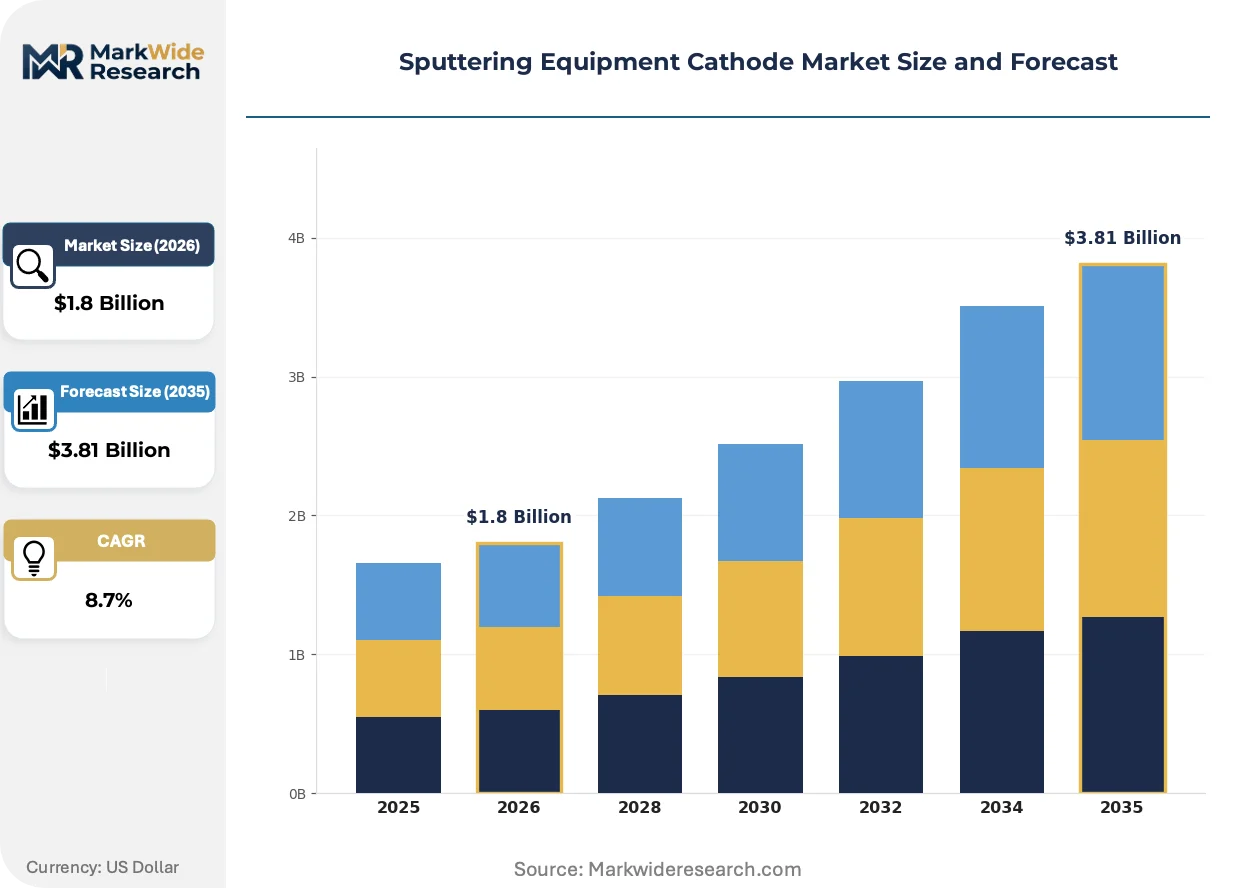
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Sputtering, RF Sputtering, Magnetron Sputtering, Pulsed Sputtering Material: Copper, Aluminum, Titanium, Zinc End User: Electronics, Solar Cells, Automotive, Optical Coatings Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Hybrid Systems, Nanotechnology |
| Companies Covered | Applied Materials, Inc., Kurt J. Lesker Company, Veeco Instruments, Inc., ULVAC, Inc., Canon Anelva Corporation, AJA International, Inc., Semicore Equipment, Inc., Angstrom Engineering Inc., Impact Coatings AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sputtering Equipment Cathode Market Strategic Shifts
Digital twin integration and closed-loop process control are compressing cathode development cycles from 24 months to 14 months. Equipment suppliers are embedding predictive erosion algorithms directly into tool controllers.
Rotatable cylindrical cathodes with in-situ magnetic field tuning are virtualizing the fixed planar magnetron architecture that dominated display panel manufacturing for three decades. Samsung Display and BOE Technology are qualifying these systems for Gen 10.5 OLED deposition lines. The technology is virtualizing capital allocation patterns by extending cathode life 40% while reducing target inventory positions.
EPA hazardous air pollutant standards for metal finishing operations are forcing cathode fabricators to eliminate hexavalent chromium passivation chemistries from surface conditioning protocols. Wet chemical alternatives are extending processing times 15% but qualifying under NESHAP 6X compliance. US-based medical device coating suppliers are absorbing these costs to maintain FDA 510(k) pathway access.
Consolidated procurement by foundry alliances is disintermediating regional equipment distributors. Taiwan Semiconductor Manufacturing and Intel are negotiating direct cathode supply agreements with target-source integrators, bypassing traditional tool OEM aftermarket channels. This pattern is most pronounced in Arizona and Hsinchu Science Park where captive logistics hubs are consolidating inbound material flows.
Sputtering Equipment Cathode Market Segmentation
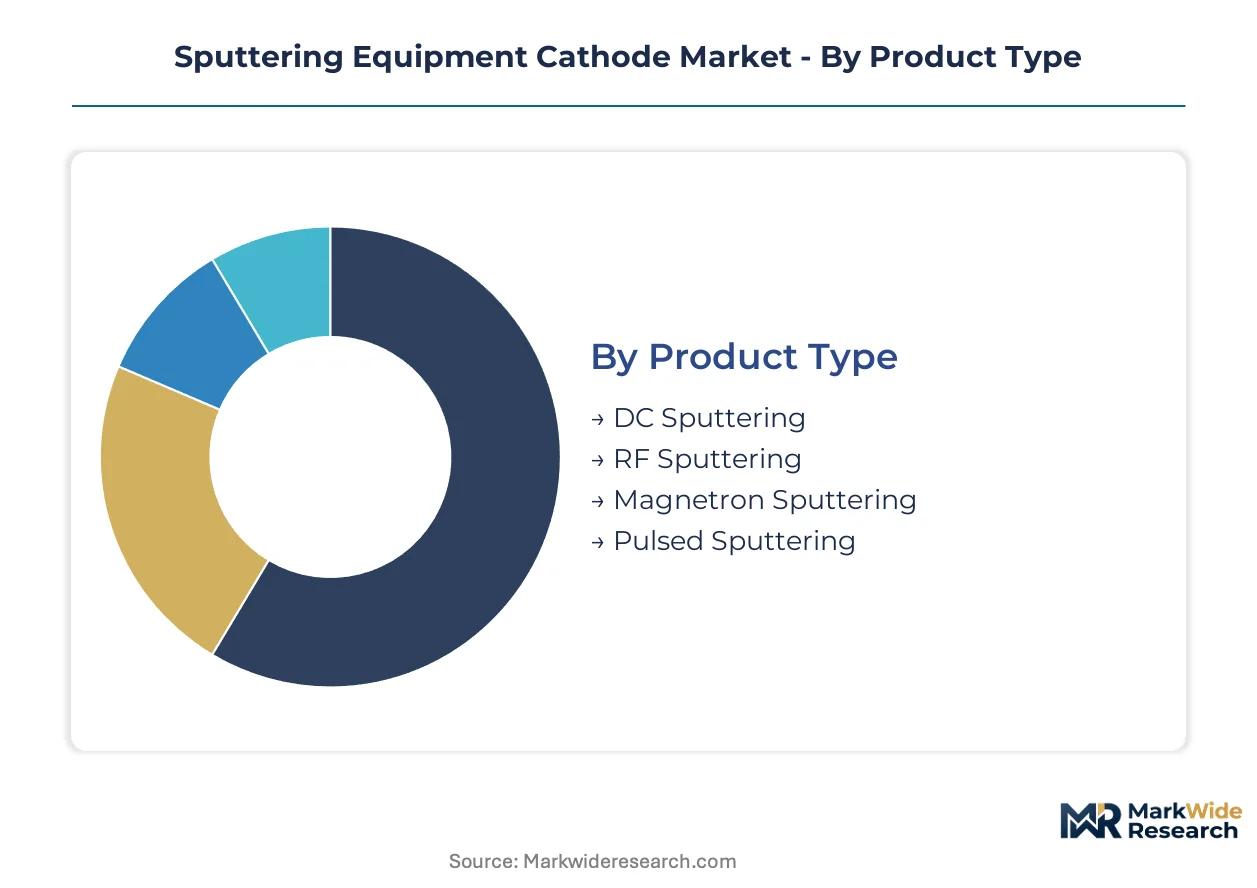
Cathode architecture, target composition, and deposition technology each impose distinct qualification protocols and procurement economics on fab operators. Segmentation reveals where equipment lessors concentrate R&D spend versus where captive operators negotiate direct supply agreements.
Product Type:
Power delivery architecture distinguishes throughput-optimized production systems from precision-oriented research installations.
- Magnetron Sputtering:High-density plasma confinement via magnetic field arrays achieves deposition rates exceeding 10 W/cm² for copper interconnect seed layers. Taiwan Semiconductor Manufacturing and Samsung Foundry deploy these cathodes across 3nm and 2nm logic lines where magnetic erosion groove tolerances tighten to sub-millimeter specifications.
- Pulsed Sputtering:Arc suppression electronics enable defect-controlled deposition for optical coating applications previously requiring ion beam systems. BOE Technology qualifies pulsed DC-DC architectures for Gen 10.5 OLED barrier layers where particulate contamination thresholds fall below 0.1 defects per cm².
- DC Sputtering:Conventional direct-current power supplies dominate legacy display panel installations across China's Yangtze River Delta under MEE emissions compliance retrofit programs.
- RF Sputtering:Radio-frequency excitation serves compound semiconductor applications including gallium nitride power amplifiers for 5G base station RF chains.
Magnetron configurations command the established base. The steepest expansion runs through pulsed sputtering architectures.
Material:
Purity grades and alloy specifications determine qualification pathways for semiconductor-grade versus industrial coating applications.
- Copper:6N+ purity cathodes (99.9999%) constitute the dominant value pool for back-end-of-line metallization in advanced logic fabs. Five Japanese and German suppliers control 90% of semiconductor-grade feedstock, concentrating procurement risk for Taiwan and Arizona fabrication clusters.
- Titanium:Barrier layer displacement of legacy aluminum accelerates across memory and logic devices where conformal coverage requirements tighten at sub-7nm nodes. Titanium nitride formulations face REACH cadmium and hexavalent chromium restrictions in European display supply chains.
- Aluminum:Legacy interconnect material retains cost advantage in photovoltaic cell metallization and commodity electronics packaging.
- Zinc:Transparent conductive oxide precursors serve architectural glass and automotive glazing applications outside semiconductor qualification regimes.
Copper cathodes anchor current fab configurations. Titanium variants are climbing the fastest as barrier layer specifications tighten.
End User:
Application-specific deposition parameters separate high-volume electronics manufacturing from specialized optical and energy systems.
- Electronics:Semiconductor foundries and display panel manufacturers consume precision magnetron cathodes under direct supply agreements that bypass traditional equipment OEM aftermarket channels. Intel and Taiwan Semiconductor Manufacturing negotiate cathode-target integration contracts consolidating inbound logistics at Arizona and Hsinchu hubs.
- Optical Coatings:Precision lens and laser system suppliers demand erosion uniformity beyond standard magnetron capabilities, pulling pulsed sputtering and cylindrical rotating cathode architectures from display manufacturing into optical applications.
- Solar Cells:Photovoltaic manufacturers prioritize deposition rate over defect density, accepting lower-purity aluminum and copper targets under less stringent qualification protocols.
- Automotive:Head-up display and sensor window coatings require automotive-grade reliability certification distinct from semiconductor fab standards.
Electronics applications concentrate the revenue base. Optical coatings are gaining share fastest as precision requirements migrate from ion beam systems.
Technology:
Process methodology selection locks in cathode replacement cycles, target inventory positions, and chamber maintenance protocols.
- Physical Vapor Deposition:Sputtering dominates thin-film electronics manufacturing where plasma-generated metal vapor deposits onto wafers, display glass, and optical substrates without chemical reaction intermediates. Magnetron enhancement extends cathode life through magnetic confinement of secondary electrons.
- Chemical Vapor Deposition:Competing deposition methodology for high-aspect-ratio features where conformal coverage exceeds sputtering capabilities; cathode suppliers face displacement risk in select memory and logic layer applications.
- Hybrid Systems:Combined PVD-CVD architectures emerge for advanced packaging where heterogeneous integration demands multiple deposition modalities within single tool platforms.
- Nanotechnology:Research-scale systems at national laboratories and university fabrication facilities require specialized cathode geometries for materials science exploration outside volume manufacturing economics.
Physical vapor deposition retains the installed base. Hybrid system integration is expanding most quickly as advanced packaging complexity mounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive fab operators and merchant equipment lessors concentrate procurement power in East Asian fabrication clusters, with secondary demand emerging from North American reshoring investments and European regulatory-driven replacement cycles.
United States
Intel's Arizona expansion and TSMC's Phoenix fab drive precision cathode demand for 3nm logic production. EPA NESHAP 6X compliance forces elimination of hexavalent chromium passivation chemistries from surface conditioning protocols. The Phoenix-Tucson corridor hosts concentrated logistics hubs consolidating inbound target material flows for captive operators.
China
Display panel investments across the Yangtze River Delta sustain replacement demand for legacy DC magnetron systems. MEE emissions standards tightening particulate and energy efficiency mandates accelerate cathode replacement cycles in BOE Technology and TCL CSOT fabs. Shanghai and Suzhou fabrication clusters dominate procurement volume for Gen 10.5 OLED deposition lines.
South Korea
Samsung Foundry and SK Hynix scale 2nm logic and advanced memory capacity requiring sub-millimeter erosion groove tolerances. MFDS oversight of medical device coatings shapes material specifications for Seoul-based coating suppliers. The Suwon-Giheung corridor anchors captive sputtering capacity for RF device and memory interconnect applications.
Japan
Tokyo Electron and Canon Anelva supply chains concentrate 6N+ copper feedstock control for semiconductor-grade targets. METI industrial policy supports domestic cathode-target integration for logic and memory device exports. The Nagoya-Osaka manufacturing belt hosts precision magnetron design expertise and erosion simulation specialists.
Taiwan
TSMC's Hsinchu Science Park expansion compresses tool qualification windows to 18 months for copper barrier seed layer applications. Direct supply agreements bypass traditional equipment OEM aftermarket channels for cathode-target integration. The Tainan Science Park secondary cluster absorbs overflow capacity from Hsinchu for 3nm risk production lines.
Sputtering Equipment Cathode Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Equipment OEMs with installed base leverage dominate aftermarket pull-through, while target-source integrators and research-scale specialists occupy differentiated positions. Strategic moves center on direct supply agreement negotiation with captive fab operators and qualification timeline compression to match 18-month tool windows.
Among US-based equipment OEMs, Applied Materials, Inc. anchors the channel-controlling tier through Endura platform aftermarket leverage. Veeco Instruments, Inc. occupies a specialized position in compound semiconductor applications where RF cathode precision commands premium positioning. Kurt J. Lesker Company exemplifies the research-scale specialist archetype, serving national laboratory and university fabrication facilities with integrated target-source systems outside volume manufacturing economics.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Kurt J. Lesker Company |
| Veeco Instruments, Inc. |
| ULVAC, Inc. |
| Canon Anelva Corporation |
| AJA International, Inc. |
| Semicore Equipment, Inc. |
| Angstrom Engineering Inc. |
| Impact Coatings AB |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Japanese and German 6N+ copper feedstock suppliers exposes cathode fabricators to allocation-driven price tier spreads and geographic concentration in East Asian fabrication clusters. This chokepoint determines both premium-mid-economy pricing differentiation and the contract-manufacturing footprint that captive foundry operators negotiate around.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement between target-source integrators and captive fab operators. Price differentiation hinges on purity certification grade and volume scale, with 6N+ semiconductor-grade copper commanding substantial premiums over 4N industrial specifications. Cost compression in standard-grade titanium cathodes is intensifying because Chinese display panel manufacturers are consolidating procurement through direct supply agreements. Merchant equipment lessors exhibit the highest price sensitivity, while Taiwan and South Korea foundries prioritize magnetic field uniformity over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Tokyo Electron, Canon Anelva, and ULVAC for precision magnetron assembly, with secondary fabrication distributed across South Korean and Taiwanese equipment lessors. Raw material supply draws from Japanese and German copper refiners, Chinese rare earth magnet producers, and American specialty alloy foundries. Single-source vulnerability pervades 6N+ copper feedstock where five suppliers control semiconductor-grade volumes. Distribution runs through direct supply agreements between target-source integrators and captive fab operators, bypassing traditional regional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma physics expertise for magnetron design and erosion simulation resides with a shrinking cohort of specialists, constraining supplier scalability and compressing qualification timelines for advanced node production.
For Market Incumbents: Insulate aftermarket pull-through by embedding predictive erosion algorithms directly into Endura platform controllers, locking in replacement part demand. Deepen backward integration into 6N+ copper feedstock through long-term offtake agreements with Japanese refiners to defend against allocation risk from emerging Chinese cathode-target integrators. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-driven semiconductor fabrication cluster by co-locating deposition material supply with Vedanta-Foxconn and ISMC Digital fabs. Target research-scale systems at national laboratories where Kurt J. Lesker's integrated target-source model demonstrates viable entry economics outside volume manufacturing qualification regimes. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated target-source specialists with captive magnetron design capabilities. Long-term viability over the projection horizon hinges on qualification timeline compression to match 18-month tool windows. Monitor cadence of direct supply agreement announcements between TSMC, Intel, and cathode-target integrators as inflection indicator for channel disintermediation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetron Design Talent Acquisition | Secures erosion simulation expertise that TSMC and Samsung Foundry require for sub-7nm qualification. |
| Direct Supply Agreement Negotiation | Bypasses Applied Materials aftermarket channels to capture Intel Arizona and TSMC Phoenix cathode volumes. |
| 6N+ Copper Feedstock Integration | Reduces allocation exposure from Japanese and German suppliers controlling semiconductor-grade volumes. |
| Pulsed DC-DC Sputtering Platform Launch | Opens precision optical coating applications where BOE Technology qualifies arc suppression architectures. |
| India PLI Scheme Localization | Positions deposition material supply alongside Vedanta-Foxconn fab construction in Gujarat. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC equipment OEM filings, Japanese METI industrial production surveys, and Taiwan Semiconductor Industry Association capacity reports. Interviews with magnetron design engineers, fab tool procurement managers at captive foundries, target metallurgy specialists, and aftermarket service directors informed supply chain structure assessment. Bottom-up cathode demand modeling triangulated against top-down fabrication capacity expansion announcements across the analysis window.
Forecast inputs include tool qualification timeline compression, MEE emissions standard implementation schedules, and PLI scheme disbursement cadence in India. Segmentation dimensions span cathode architecture, target composition purity grade, deposition technology modality, and end-use application qualification tier. CAGRs were derived from installed base erosion rates and replacement cycle acceleration patterns. Foundry alliance procurement consolidation and REACH substance restriction evolution served as scenario-weighting variables.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, copper commodity price volatility, or China-Taiwan trade corridor stability would shift the trajectory. Forecasts reflect documented assumptions regarding 3nm and 2nm node ramp schedules, EPA NESHAP 6X compliance timelines, and dual carbon goal enforcement intensity. Quarterly review of tool qualification window announcements, direct supply agreement disclosures, and 6N+ copper spot market indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market