
 Chip Capacitor Market | 2026-2036
Chip Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
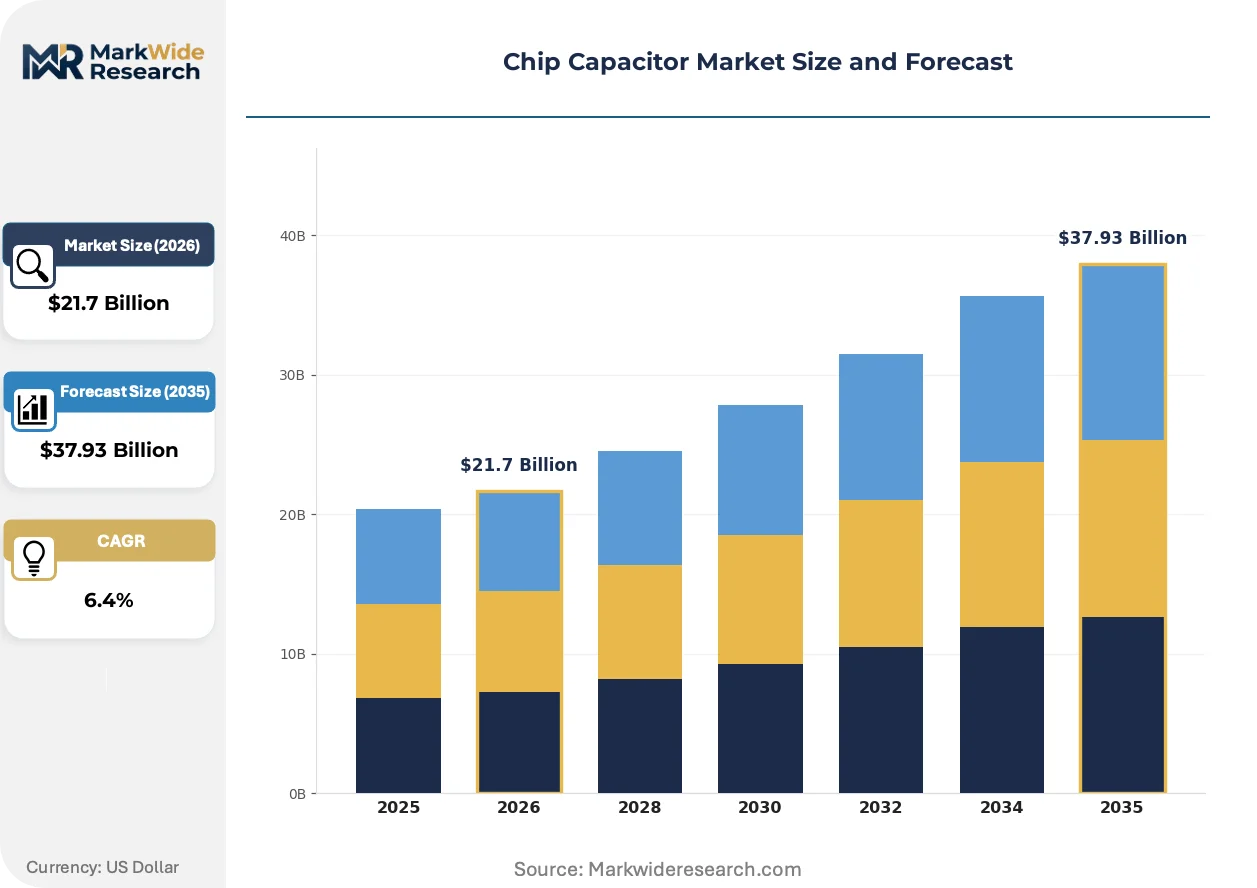
Chip Capacitor Market Outlook
Niobium oxide is expanding its footprint in high-reliability applications as a cost-stabilizing alternative to traditional tantalum powder. Murata Manufacturing Co., Ltd. leverages vertical integration from ceramic powder to finished multilayer devices, sustaining margin control across volatile raw material cycles. Samsung Electro-Mechanics anchors high-volume supply for mobile and automotive tier-one customers, while TDK Corporation differentiates through thin-film expertise in radio-frequency and high-frequency segments.
A chip capacitor is a passive surface-mount or through-hole electronic component that stores and releases electrical energy, typically constructed from alternating layers of ceramic dielectric and metal electrode materials fired at temperatures exceeding 1,200°C to achieve stable capacitance values. Its primary purpose is to filter noise, stabilize voltage, and manage energy transients across printed circuit boards in compact electronic assemblies. Multilayer ceramic capacitors dominate volume and value due to their superior volumetric efficiency and compatibility with automated pick-and-place assembly, while tantalum capacitors retain premium positioning in military-aerospace and implantable medical devices where reliability thresholds exclude ceramic alternatives. Surface mount technology commands the manufacturing standard, though hybrid mounting approaches persist in industrial equipment retrofits and automotive power modules where mechanical stress tolerance varies by subsystem.
REACH restrictions on conflict minerals and RoHS substance limits constrain tantalum sourcing and electrode metallurgy across European supply chains, while China's GB standards and MIIT semiconductor self-sufficiency directives reshape local procurement rules for domestic OEMs. The US EPA and FAA maintain discrete environmental and reliability benchmarks that govern capacitor qualification for aerospace and defense end uses. Stakeholders must monitor how regional decarbonization mandates and export control expansions alter material availability and qualification timelines for next-generation dielectric formulations.
Market Dynamics
Automotive electrification is compressing qualification timelines and forcing dielectric material substitutions as EV powertrains demand higher-density capacitance in thermally stressed environments.
Growth Catalysts
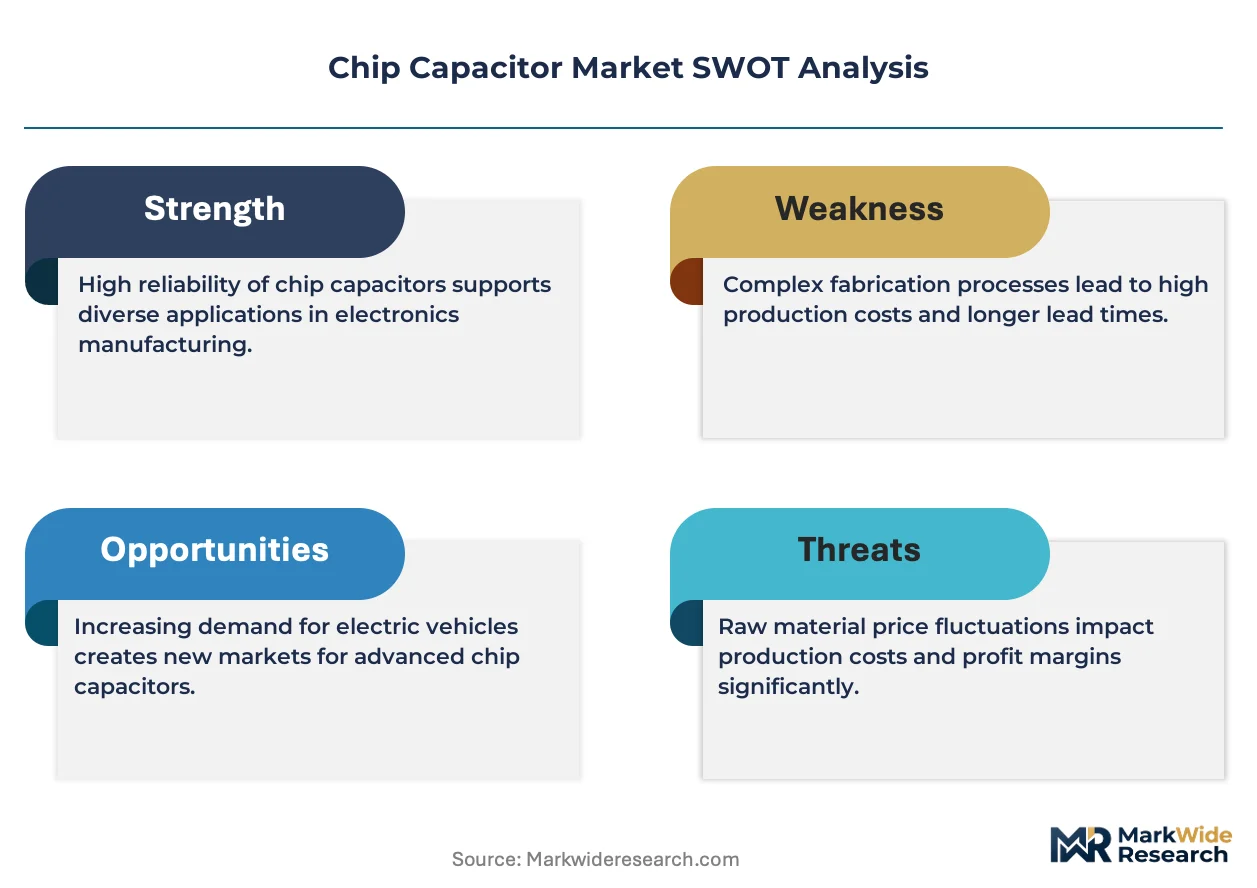
- EV Powertrain Electrification:Battery management systems and inverter modules require multilayer ceramic capacitors with extended temperature ratings, pulling volume from consumer electronics into automotive qualified lines.
- China's Dual Carbon Mandates:MIIT semiconductor directives and GB standards for green manufacturing are redirecting domestic OEM procurement toward locally certified capacitor suppliers.
- Advanced Driver-Assistance Systems:Sensor fusion architectures and LiDAR processing units need high-reliability tantalum and niobium oxide capacitors for noise suppression in safety-critical signal chains.
Market Restraints
- Tantalum Ore Concentration:Conflict mineral sourcing restrictions under REACH and Dodd-Frank Section 1502 constrain electrode material availability from Central African suppliers.
- Palladium Electrode Costs:Base metal electrode transitions remain incomplete in high-voltage grades, exposing margins to precious metal price volatility.
- High-Temperature Ceramic Limitations:X7R and C0G dielectric formulations face capacitance drift thresholds that exclude them from some aerospace engine control applications.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and component assembly are attracting capacitor distributors to establish regional stocking hubs.
- Medical Implant Miniaturization:Pacemaker and neuromodulator OEMs are qualifying niobium oxide capacitors as tantalum alternatives for biocompatible hermetic sealing.
- Thin-Film RF Integration:5G mmWave base station and satellite terminal manufacturers are adopting silicon-integrated thin-film capacitors to reduce discrete component counts.
Industry Challenges
- Automotive Qualification Bottlenecks:AEC-Q200 testing timelines and PPAP documentation requirements stretch 18-24 months, delaying revenue recognition for new dielectric formulations.
- Legacy Equipment Retrofit Integration:Industrial automation customers demand through-hole and hybrid mounting compatibility that conflicts with surface-mount manufacturing scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Capacitor Market |
| Market Size in 2026 | $21.7 Billion |
| Market Size in 2035 | $37.93 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer Ceramic Capacitors, Tantalum Capacitors, Aluminum Electrolytic Capacitors, Film Capacitors End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Capacitance Range: Low Capacitance, Medium Capacitance, High Capacitance, Ultra-High Capacitance Technology: Surface Mount, Through-Hole, Hybrid, Other |
| Companies Covered | Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics, TDK Corporation, Yageo Corporation, Taiyo Yuden Co., Ltd., Kyocera Corporation, Vishay Intertechnology, AVX Corporation, Walsin Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Capacitor Market Strategic Shifts
Dielectric material science and mounting technology are converging to redefine volumetric efficiency benchmarks across automotive, medical, and telecommunications end uses.
High-voltage multilayer ceramic capacitors with base metal electrodes are consolidating market share in EV onboard chargers and DC-DC converters. Tier-one automotive suppliers are qualifying these devices at 500V and above for silicon carbide powertrain architectures. This consolidation is compressing demand for traditional film capacitors in sub-10kW power conversion applications.
REACH substance restrictions and RoHS recast directives are tightening limits on lead content in ceramic formulations and electrode metallurgy. European capacitor manufacturers are reformulating dielectric pastes to maintain X7R performance characteristics under revised ECHA hazard classifications. Medical device OEMs in Germany and France are accelerating qualification of alternative electrode stacks to preempt supply disruptions.
Consolidated procurement through authorized distributors is displacing spot-market purchasing for automotive and aerospace programs. Tier-two EMS providers in Taiwan and South Korea are negotiating long-term fixed-price agreements directly with Murata and Samsung Electro-Mechanics to secure allocation priority. This behavioral shift is most visible in Japan, where keiretsu purchasing relationships are formalizing into binding volume commitments with penalty clauses.
Chip Capacitor Market Segmentation
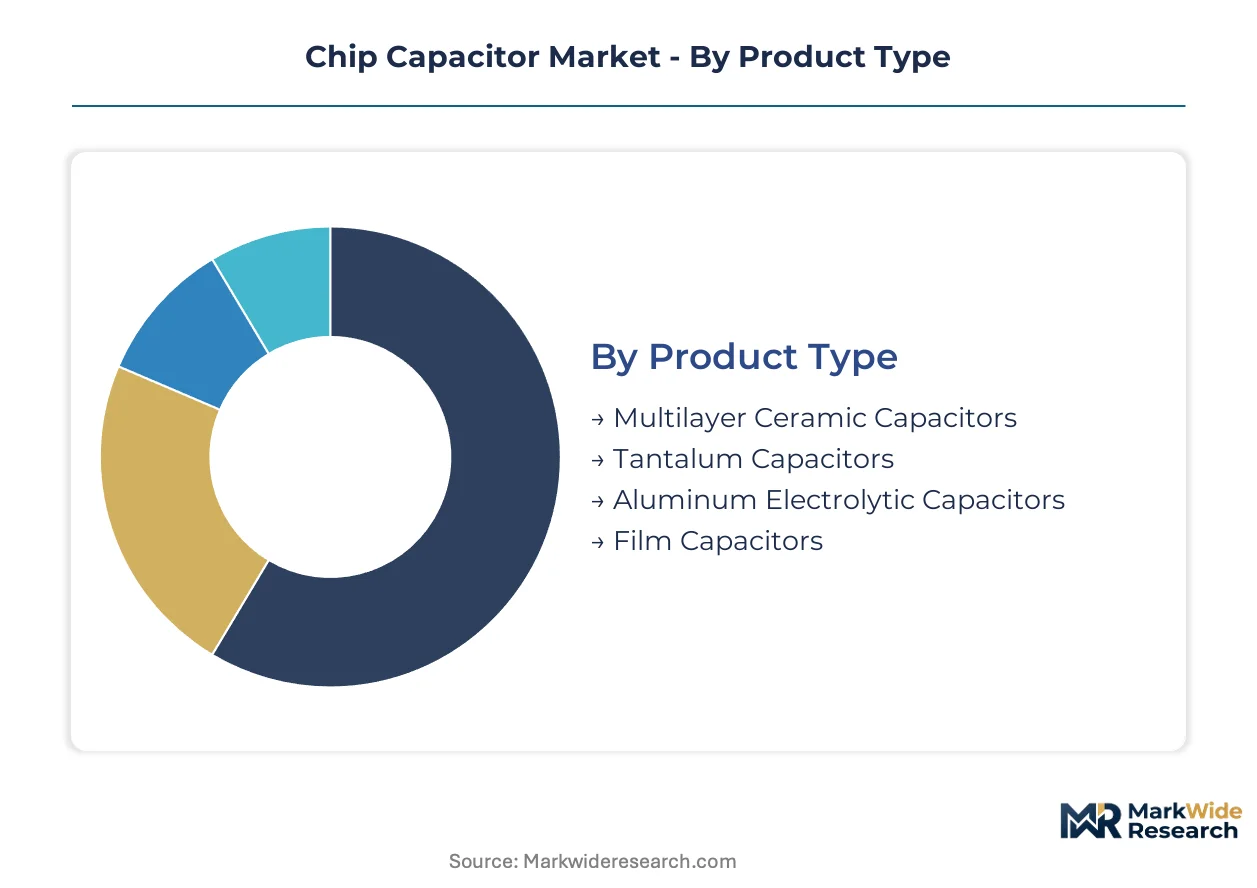
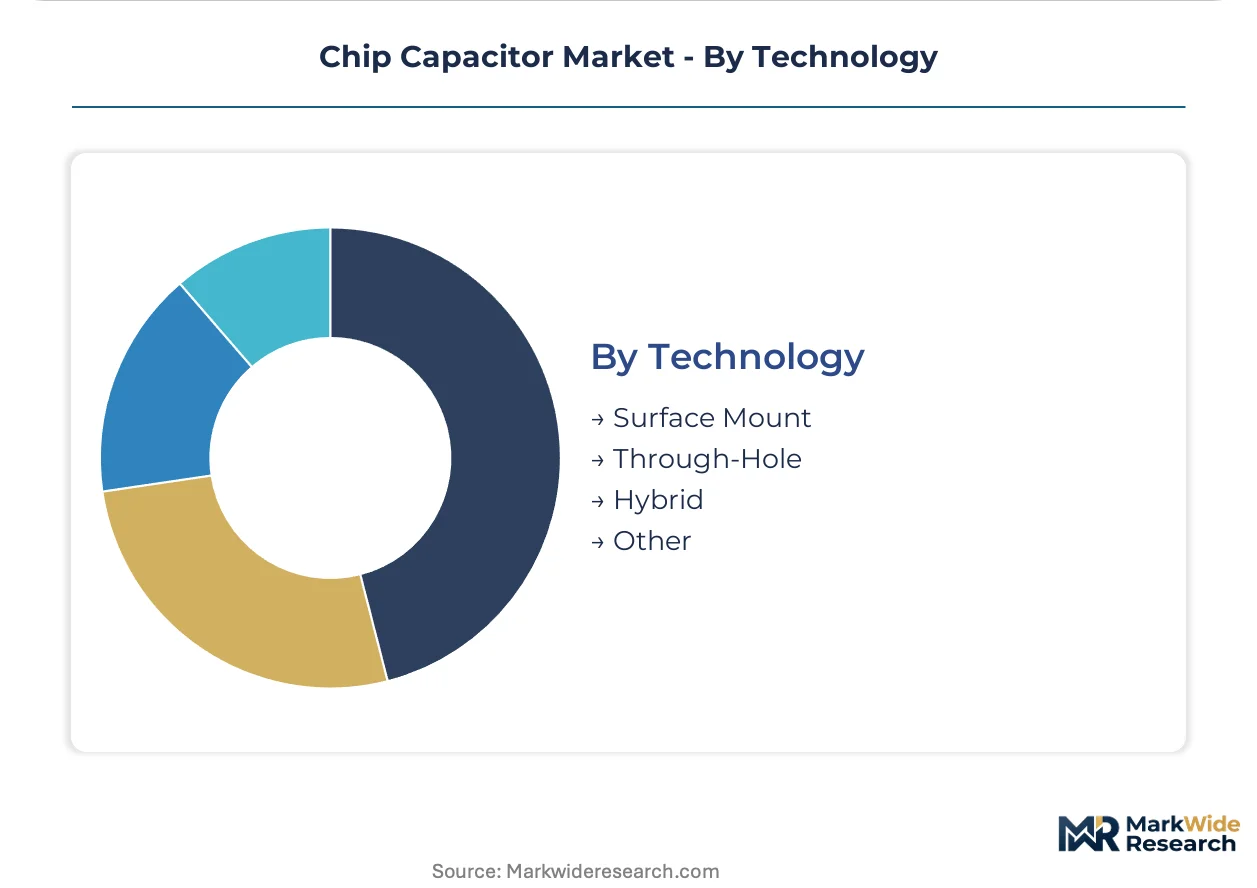
Capacitor segmentation reveals divergent margin structures across dielectric technologies and mounting formats. Automotive qualification requirements and miniaturization pressures are reshaping volume distribution across traditional consumer electronics strongholds.
Product Type:
Volume concentration tilts toward ceramic architectures, while premium positioning clusters around specialty electrolytic and film constructions for mission-critical applications.
- Multilayer Ceramic Capacitors:These devices stack alternating layers of ceramic dielectric and metal electrodes to achieve superior volumetric efficiency. Demand concentrates in East Asian foundry clusters serving smartphone and EV powertrain customers, where Murata and Samsung Electro-Mechanics anchor supply. AEC-Q200 qualification timelines for automotive-grade MLCCs now stretch 18-24 months, constraining rapid volume shifts.
- Tantalum Capacitors:Sintered tantalum powder anodes with manganese dioxide or polymer cathodes deliver stable capacitance in compact footprints. Procurement from German and French medical device OEMs is accelerating for implantable applications, though REACH conflict mineral restrictions constrain Central African ore sourcing.
- Aluminum Electrolytic Capacitors:Rolled aluminum foil with electrolyte-soaked separators dominates bulk energy storage in industrial motor drives.
- Film Capacitors:Polypropylene or polyester dielectric layers wrapped in metalized films retain positioning in high-voltage inverter modules.
Mature deployment sits with multilayer ceramic capacitors. Newer deployment is concentrated in tantalum alternatives for medical and aerospace hermetic sealing.
End User:
Application-driven procurement patterns separate high-volume consumer programs from long-cycle automotive and industrial qualifications.
- Consumer Electronics:Smartphones, tablets, and wearables drive multilayer ceramic consumption in sub-100µF ranges. Assembly lines in Shenzhen and Dongguan pull standard-grade MLCCs through authorized distributors with 12-week rolling forecasts.
- Automotive:Battery management systems and silicon carbide inverters demand extended temperature ratings and AEC-Q200 certification. Tier-one suppliers in Stuttgart and Toyota City are qualifying base metal electrode ceramics at 500V and above.
- Telecommunications:5G base station deployments and satellite terminals require thin-film RF capacitors for mmWave filtering.
- Industrial Equipment:Motor drives and power supplies sustain demand for through-hole and hybrid mounting formats in retrofit installations.
Procurement scale peaks in consumer electronics. Margin expansion is climbing fastest in automotive qualified lines.
Capacitance Range:
Specification tiers align with physical size constraints and energy storage requirements across portable and stationary applications.
- Low Capacitance:Sub-1µF devices in 0402 and 0201 case sizes filter high-frequency noise in mobile processors. Foundry demand from Hsinchu and Seoul anchors volume.
- Medium Capacitance:1µF to 100µF ranges stabilize voltage rails in consumer and automotive subsystems.
- High Capacitance:100µF to 1mF tantalum and aluminum electrolytic constructions buffer power transients in industrial motor controllers.
- Ultra-High Capacitance:Above 1mF, film and electrolytic technologies dominate EV onboard chargers and grid-tied inverters.
Design-in density concentrates in low and medium ranges. System-level power demands are expanding most quickly in ultra-high capacitance segments.
Technology:
Mounting format selection reflects assembly automation levels and mechanical stress tolerance requirements by end-use environment.
- Surface Mount:Pick-and-place compatible 0402 to 1210 case sizes dominate high-volume consumer and automotive PCB assembly. Osaka and Suwon manufacturing lines run 24-hour surface-mount operations.
- Through-Hole:Radial and axial leads retain necessity in high-vibration industrial and legacy equipment retrofits.
- Hybrid:Combined mounting approaches accommodate automotive power modules where mechanical stress varies by subsystem.
- Other:Press-fit and spring-contact variants serve specific telecommunications and military connector standards.
Manufacturing scale clusters in surface mount. Hybrid configurations are gaining share fastest in automotive powertrain integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters anchor component supply chains for chip capacitors, with Japan, South Korea, and Taiwan concentrating foundry and OSAT infrastructure. Automotive electrification and consumer electronics assembly pull demand toward specific national production bases.
China
MIIT semiconductor directives and GB standards for green manufacturing redirect domestic OEM procurement toward locally certified suppliers. NMPA standards reshape material sourcing compliance for medical-grade capacitors. Shenzhen and Dongguan assembly lines pull standard-grade multilayer ceramic devices through authorized distributors with rolling forecasts.
Japan
METI industrial policy supports captive production of ceramic dielectric materials and electrode pastes. JIS standards govern reliability benchmarks for automotive and aerospace applications. Osaka and Kyoto manufacturing lines run continuous surface-mount operations serving tier-one automotive suppliers in Toyota City.
South Korea
MFDS medical device regulations and K-Battery initiative funding accelerate qualification of high-reliability capacitors for implantable electronics. Samsung Electro-Mechanics anchors high-volume supply for mobile and automotive customers. Suwon manufacturing clusters concentrate pick-and-place compatible device production.
Taiwan
Hsinchu Science Park foundry demand anchors volume for sub-1µF noise filtering devices in mobile processors. The island's semiconductor packaging ecosystem integrates capacitor assembly into advanced substrate manufacturing. Taipei-based distributors negotiate long-term allocation agreements with Japanese and Korean suppliers.
Germany
REACH restrictions on conflict minerals and RoHS substance limits constrain tantalum sourcing for European automotive and medical OEMs. KBA automotive certification requirements extend qualification timelines for EV powertrain components. Stuttgart suppliers qualify base metal electrode ceramics at elevated voltage ratings for silicon carbide inverter architectures.
Chip Capacitor Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers add ceramic powder synthesis and firing lines to capture automotive qualification volumes. The vendor base organizes into three tiers: integrated material-to-device producers, specialized high-frequency thin-film fabricators, and regional contract assemblers. Two strategic archetypes define competitive positioning: backward-integrated specialists controlling dielectric formulation and scale-driven volume manufacturers serving consumer electronics. Geographic expansion into India and Vietnam accompanies portfolio diversification toward automotive-grade product lines.
Among Japanese integrated producers, Murata Manufacturing Co., Ltd. and Taiyo Yuden Co., Ltd. exemplify the material-captive archetype with in-house ceramic powder production. Samsung Electro-Mechanics represents the scale-driven Korean model serving high-volume mobile and automotive tier-one programs. These three companies anchor the competitive structure through distinct geographic and operational positioning rather than overlapping strategic approaches.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Samsung Electro-Mechanics |
| TDK Corporation |
| Yageo Corporation |
| Taiyo Yuden Co., Ltd. |
| Kyocera Corporation |
| Vishay Intertechnology |
| AVX Corporation |
| Walsin Technology Corporation |
| Others |
Value Chain & Pricing Dynamics
Palladium price volatility on the London Metal Exchange cascades through electrode metallurgy costs, compressing margins in high-voltage ceramic grades while automotive OEMs lock in 18-24 month fixed-price contracts to buffer against raw material swings.
Pricing Analysis
Volume concentrates in standard-grade multilayer ceramic capacitors where Samsung Electro-Mechanics and Murata compete on scale, while margin expansion sits with AEC-Q200 qualified automotive lines and thin-film RF devices for 5G infrastructure. Price differentiation hinges on certification tier and base metal electrode versus palladium-based construction, with EV powertrain customers showing lowest sensitivity due to qualification lock-in and consumer electronics buyers driving hardest bargain on spot-market volumes. Cost compression in standard-grade MLCCs is intensifying because Chinese domestic suppliers are expanding ceramic powder synthesis capacity under MIIT directives.
Supply Chain Analysis
Dual-sourcing mandates from tier-one automotive suppliers in Stuttgart and Toyota City force qualification of second-source MLCC vendors, stretching PPAP documentation timelines and favoring established Japanese and Korean manufacturers with existing AEC-Q200 portfolios. Geographic supply concentration rests on Japan, South Korea, and Taiwan, where Murata, Samsung Electro-Mechanics, and Taiyo Yuden anchor ceramic dielectric production. Raw material dependencies center on barium titanate ceramic powders, palladium and nickel electrode pastes, and tantalum ore from Central African sources. Single-source vulnerability persists in high-reliability tantalum powder for medical-aerospace applications. Distribution runs through authorized distributors like Arrow and Avnet for automotive programs, while spot-market purchasing persists in Shenzhen consumer electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification is consolidating the chip capacitor landscape as AEC-Q200 qualification barriers and 18-24 month PPAP timelines force sub-scale competitors into contract manufacturing roles or exit.
For Market Incumbents: Deepen backward integration into ceramic powder synthesis to secure margin control against barium titanate price cycles, while expanding firing capacity in Vietnam or India to capture PLI-scheme incentives and hedge against China tariff exposure. Prioritize AEC-Q200 certification investment for 500V+ base metal electrode lines before silicon carbide powertrain architectures lock in supplier selections.
For New Entrants and Emerging Players: Capture medical implant miniaturization demand for niobium oxide capacitors as REACH conflict mineral restrictions disqualify traditional tantalum suppliers from European OEM procurement. Target German and French pacemaker manufacturers with biocompatible hermetic sealing qualifications as the most penetrable entry point, leveraging CDSCO or MFDS regulatory pathways to establish credibility before pursuing FDA PMA submissions.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap ceramic specialists with existing automotive qualification pipelines but constrained working capital in Japan and South Korea, where keiretsu relationship fragmentation creates acquisition windows. Watch for inflection in silicon carbide inverter ramp rates at European OEMs as the signal to accelerate deployment of dry powder into qualified supply chain positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Synthesis | Murata and Taiyo Yuden sustain margin control across volatile barium titanate cycles through captive material production. |
| AEC-Q200 Certification Expansion | Automotive-grade qualification timelines stretching 18-24 months create defensive moats against unqualified competitors. |
| Niobium Oxide Product Line Development | REACH conflict mineral restrictions position niobium oxide as the viable tantalum alternative for European medical device OEMs. |
| Geographic Manufacturing Diversification | India PLI scheme incentives attract capacitor assembly investment to reduce China concentration risk. |
| Long-Term Fixed-Price Agreements | Tier-two EMS providers in Taiwan negotiate binding volume commitments with penalty clauses to secure allocation priority. |
Study Parameters
SEC 10-K filings, ECHA REACH substance registrations, and MIIT semiconductor industry reports formed the secondary backbone, cross-referenced with primary interviews involving capacitor procurement managers at tier-one automotive suppliers, ceramic powder plant managers in Osaka and Suwon, and regulatory affairs leads at medical device OEMs in Germany. Bottom-up and top-down triangulation validated volume estimates across dielectric technology segments.
Bottom-up modeling aggregated unit economics by dielectric formulation, capacitance range, and mounting technology, while top-down analysis tracked end-use demand from EV powertrain electrification, 5G base station deployment, and medical implant miniaturization across the projection horizon. CAGRs derived from regression against historical automotive electronics content per vehicle, smartphone unit forecasts, and foundry capacity expansion in Hsinchu and Seoul.
The model holds under sustained automotive electrification capex and stable tantalum ore supply from Central African sources; deviation in REACH substance restriction expansion or China-Taiwan logistics disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market