
 France Outdoor LED Lighting Market | 2026-2036
France Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
France Outdoor LED Lighting Market Insights
Modular fixture design is hardening as the dominant configuration pattern, allowing municipalities to swap LED engines without replacing entire luminaire housings. Signify France leverages its connected lighting platform to anchor large-scale urban retrofit contracts across Bordeaux and Lyon. Schréder competes through specialized optical systems that reduce uplight pollution for Dark Sky-certified projects. Legrand SA extends its electrical infrastructure portfolio into outdoor LED control systems, integrating street-level power distribution with dimming protocols.
France outdoor LED lighting comprises solid-state luminaires employing gallium nitride chip-on-board arrays, typically operating at color temperatures between 2700K and 4000K with system efficacies exceeding 130 lumens per watt, engineered for roadway illumination, architectural accentuation, and public safety applications. Street lights dominate installed value due to mandatory replacement timelines under French energy transition law, while smart lighting technology captures the fastest expansion as cellular and mesh network connectivity enables remote dimming and predictive maintenance. Solar powered installations occupy a niche but growing position in rural communes where grid extension costs outweigh photovoltaic premium pricing.
The EU Ecodesign Directive and French AGEC anti-waste law shape product compliance requirements, mandating repairability indices and recycled content thresholds that filter out non-compliant imports. ANSM and CNIL oversight extends to cybersecurity standards for connected luminaires collecting pedestrian flow data through embedded sensors. Stakeholders must monitor forthcoming EU battery regulation impacts on solar-integrated fixtures and position procurement strategies around circular economy service contracts rather than transactional equipment sales.
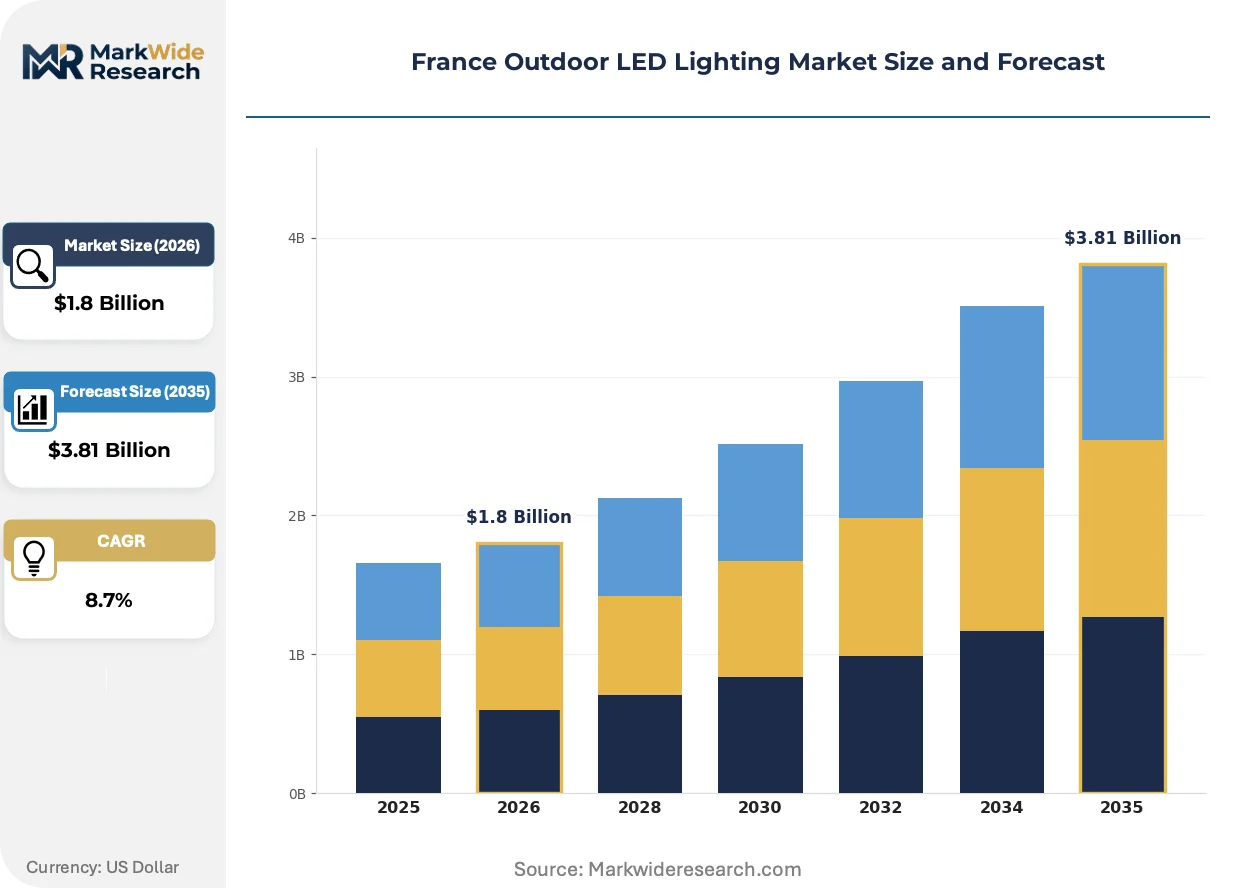
Market Dynamics
The French outdoor LED lighting sector is undergoing structural recalibration as modular fixture architectures replace sealed-unit designs, forcing incumbent manufacturers to reconfigure supply chains around swappable LED engines and standardized control interfaces.
Growth Catalysts
- EU Green Deal energy efficiency mandates:The EU Green Deal's binding efficiency targets are compressing municipal procurement cycles and mandating lumen-per-watt thresholds that only solid-state technology satisfies.
- Île-de-France smart city infrastructure:Parisian urban digitalization programs are generating premium demand for connected luminaires with embedded sensor arrays and cellular mesh connectivity.
- Gallium nitride chip-on-board arrays:Advances in GaN thermal management are pushing system efficacies past 130 lumens per watt, enabling single-fixture replacements for legacy high-pressure sodium installations.
Market Restraints
- Aluminum alloy input volatility:Die-cast housing production faces margin pressure from London Metal Exchange aluminum price swings and European smelter energy surcharges.
- Optical component supply concentration:Precision lens and reflector manufacturing clusters in German and Austrian specialty glass facilities, creating single-source vulnerability for French assemblers.
- French AGEC anti-waste law compliance friction:The AGEC law's repairability index requirements and recycled content thresholds are filtering out lower-cost non-EU imports and extending qualification timelines.
Strategic Opportunities
- Rural solar-integrated installations:Photovoltaic-powered street lighting in grid-remote communes of Occitanie and Provence-Alpes-Côte d'Azur bypasses costly underground cable extension.
- Circular economy service contracts:Luminaire-as-a-service models with French municipalities are shifting revenue from transactional equipment sales to long-term maintenance and upgrade subscriptions.
- Dark Sky certification convergence:Specialized optical systems reducing uplight pollution are capturing premium positioning in Auvergne-Rhône-Alpes regional parks and protected night-sky reserves.
Industry Challenges
- Cybersecurity competency gaps:Connected fixture deployments require embedded systems engineers capable of implementing ANSM and CNIL data protection protocols for pedestrian flow sensors.
- Legacy control system integration:Municipal buyers in Hauts-de-France and Grand Est demand backward compatibility with existing DALI and 0-10V dimming infrastructure, complicating smart-node rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Outdoor LED Lighting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Landscape Lights, Decorative Lights Installation: Wall Mounted, Pole Mounted, Ceiling Mounted, Free Standing End User: Municipalities, Commercial Properties, Parks, Schools Technology: Smart Lighting, Solar Powered, Wired, Wireless |
| Companies Covered | Lucibel SA, Thorn Lighting, Signify France, Osram GmbH, Schréder, Legrand SA, Eclatec, Planlicht France, Schneider Electric SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Outdoor LED Lighting Market Trends and Innovations
Three distinct vectors are compressing product lifecycles and rewiring competitive positioning in French outdoor illumination: thermal management breakthroughs, tightening circular economy compliance, and procurement model fragmentation.
Tunable white LED engines with dynamic correlated color temperature adjustment are rewriting fixture value propositions for French roadway authorities. Bordeaux and Lyon municipal operators are piloting circadian-responsive street lighting that shifts from 4000K to 2700K after midnight. The technology is compressing replacement intervals by allowing spectral output modification without hardware swaps.
The EU Ecodesign Directive's 2024 amendments are mandating modular construction and standardized component interfaces for all publicly procured luminaires. French manufacturers must now certify repairability indices and document recycled aluminum content percentages. The regulation is accelerating obsolescence of sealed-unit designs from Asian competitors lacking European service networks.
Municipal buyers are fragmenting procurement across specialized regional clusters rather than national framework agreements. Grand Est communes now aggregate demand through cross-border purchasing cooperatives with Luxembourg and Belgian counterparts, bypassing traditional distribution channels. The pattern is most visible in border regions where multilingual tender specifications and interoperable technical standards enable volume consolidation across jurisdictions.
France Outdoor LED Lighting Market Segmentation
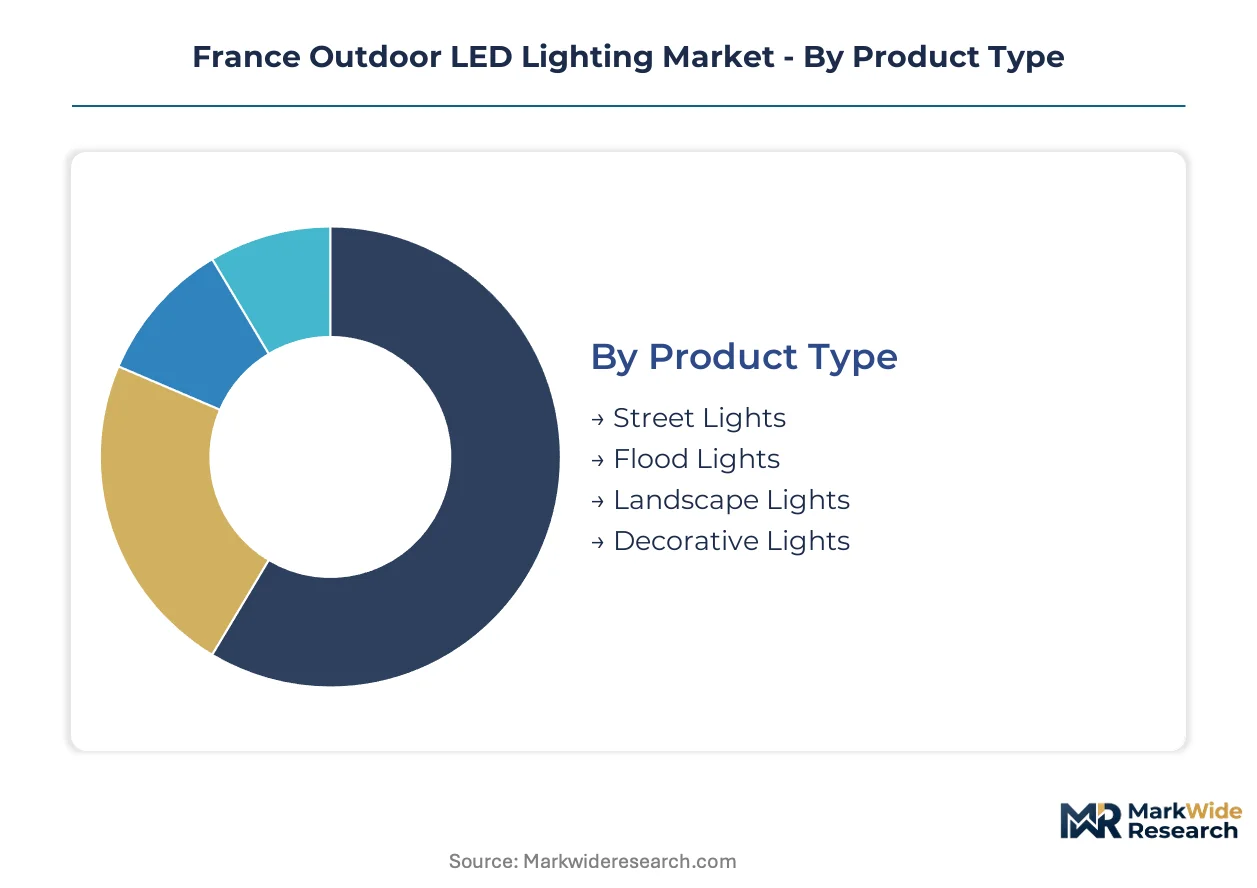
Segmentation in the France outdoor LED lighting market reveals how procurement priorities diverge across infrastructure vintages and regulatory exposure. Municipal retrofit programs favor standardized form factors with modular upgrade paths, while commercial installations prioritize aesthetic differentiation and connectivity integration.
Product Type:
Replacement-cycle economics drive procurement patterns across fixture categories, with legacy high-pressure sodium obsolescence creating differentiated demand windows for each product family.
- Street Lights:Modular pole-top luminaires employing chip-on-board LED arrays dominate installed value through mandatory replacement timelines under French energy transition law. Demand concentrates in Île-de-France and Auvergne-Rhône-Alpes regional authorities managing dense arterial networks.
- Flood Lights:High-output asymmetric beam fixtures serve industrial perimeters and sports complexes. Commercial property managers in Lyon and Marseille industrial zones are specifying these for security compliance upgrades.
- Landscape Lights:Low-wattage bollards and in-grade fixtures for pedestrian pathway illumination. Bordeaux municipal parks departments specify these for riverside promenade renovations.
- Decorative Lights:Ornamental post-top and pendant fixtures for historic district preservation. Parisian arrondissement councils procure these for monument-adjacent streetscapes requiring heritage-compatible aesthetics.
Volume placements concentrate in Street Lights; the faster expansion belongs to Smart Lighting-enabled Street Lights with embedded sensor capacity.
Installation:
Mounting configuration selection tracks infrastructure ownership patterns, with public realm assets favoring pole-mounted solutions and private commercial spaces diversifying across attachment types.
- Pole Mounted:Cantilevered arm and post-top assemblies for roadway and parking field coverage. French departmental road services (DIR) in Grand Est and Hauts-de-France specify these for national route modernization.
- Wall Mounted:Bracketed downlight and uplight fixtures for building facade grazing and security perimeters. Logistics facilities in Île-de-France industrial suburbs are retrofitting these for perimeter illumination compliance.
- Ceiling Mounted:Suspended canopy luminaires for covered walkways, transit shelters, and parking structures. RATP and SNCF station renovation programs generate recurring demand for vandal-resistant variants.
- Free Standing:Bollard and tower-mounted solutions for plaza and parking island illumination. Occitanie rural communes deploy solar-integrated versions where underground cable extension proves cost-prohibitive.
Pole Mounted captures the majority of public procurement volume; Wall Mounted is climbing the fastest as commercial security lighting mandates tighten.
End User:
Customer-type segmentation exposes divergent specification authority, with municipalities controlling standardized bulk purchases and commercial buyers demanding customized performance tiers.
- Municipalities:City and departmental authorities managing street lighting concessions and public space illumination. French communes are aggregating demand through regional purchasing cooperatives to achieve scale pricing on LED retrofits.
- Commercial Properties:Retail, logistics, and industrial facility operators specifying parking lot and perimeter systems. Big-box retailers in peripheral commercial zones near Lille and Nantes are driving demand for high-efficacy flood packages.
- Parks:Regional natural parks and municipal green space managers requiring Dark Sky-compatible optical systems. Auvergne-Rhône-Alpes regional park authorities specify full cut-off fixtures for protected night-sky reserves.
- Schools:Academy and municipal education authorities managing campus security and sports field illumination. The Versailles and Lyon academies have initiated phased playground and parking area conversions.
Municipalities dominate absolute fixture volume; Parks represent the steepest expansion trajectory as biodiversity lighting regulations proliferate across French regions.
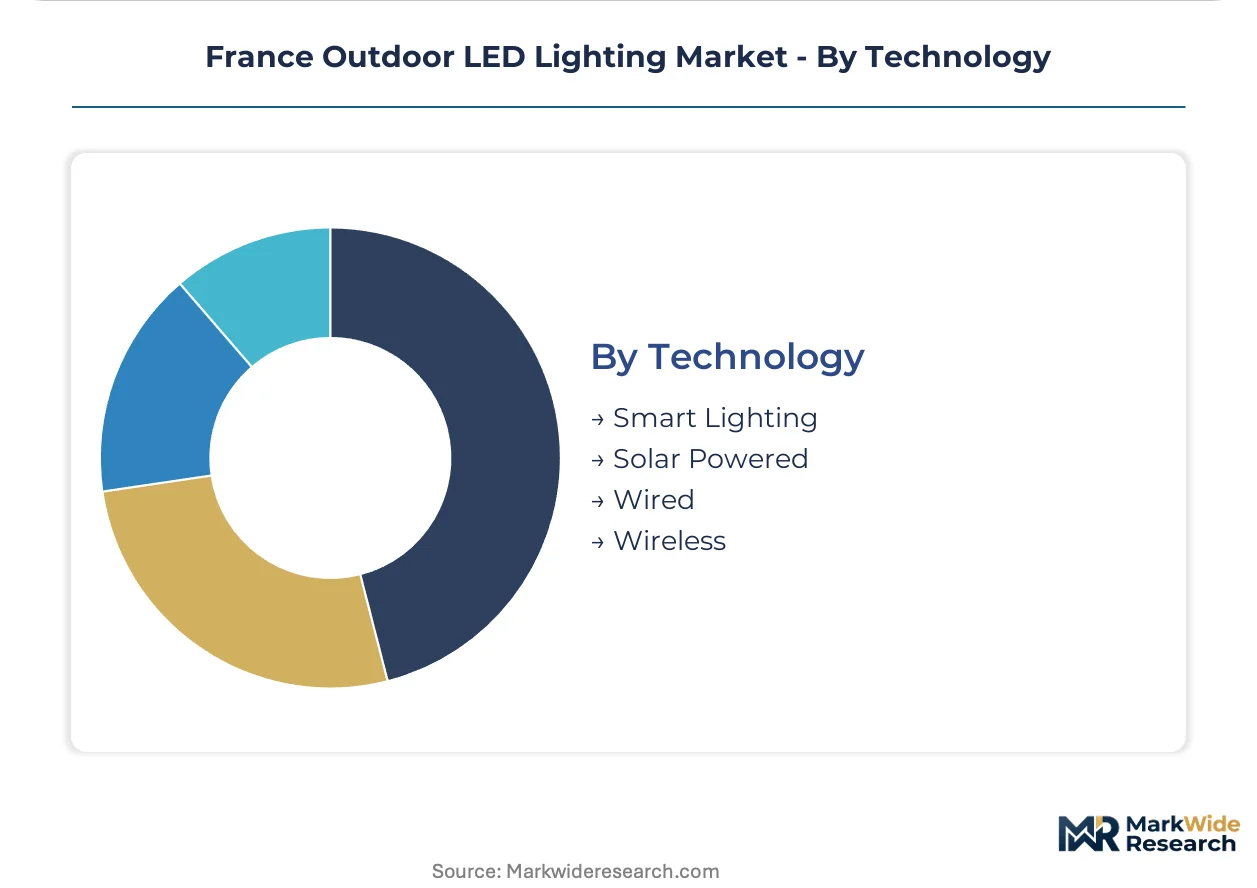
Technology:
Technology-layer segmentation separates connected intelligence from power-source architecture, with procurement patterns increasingly bundling both dimensions into integrated specifications.
- Smart Lighting:Cellular and mesh-networked fixtures enabling remote dimming, predictive maintenance, and sensor data collection. Parisian smart city infrastructure programs are generating premium demand for these systems with embedded environmental monitoring.
- Solar Powered:Photovoltaic-integrated luminaires with battery storage for off-grid operation. Grid-remote communes in Provence-Alpes-Côte d'Azur deploy these to bypass costly underground cable extension.
- Wired:Conventional AC-powered fixtures with DALI or 0-10V control compatibility. Legacy municipal infrastructure in Hauts-de-France and Grand Est demands these for backward compatibility with existing control networks.
- Wireless:Radio-frequency controlled systems avoiding trenching and conductor installation. Temporary installation scenarios and heritage-sensitive contexts where conduit placement is restricted favor this architecture.
Wired technology retains the largest installed base; Smart Lighting is gaining share fastest as ANSM and CNIL cybersecurity frameworks mature for connected luminaire deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes the majority of domestically manufactured LED luminaires, though die-cast housing components and precision optical elements are imported from German and Austrian specialty suppliers. Regional demand patterns track municipal budget cycles and smart city infrastructure maturity.
Île-de-France
Parisian smart city programs generate premium demand for connected luminaires with embedded sensor arrays. ANSM and CNIL cybersecurity frameworks shape procurement specifications for pedestrian flow data collection. The metropolis anchors national volume through RATP station renovations and arrondissement streetscape upgrades.
Auvergne-Rhône-Alpes
Regional park authorities drive specialized demand for Dark Sky-certified optical systems reducing uplight pollution. The EU Green Deal's biodiversity targets accelerate full cut-off fixture mandates in protected night-sky reserves. Lyon municipal operators pilot circadian-responsive street lighting with dynamic color temperature adjustment.
Provence-Alpes-Côte d'Azur
Grid-remote communes deploy solar-integrated luminaires to bypass costly underground cable extension. Photovoltaic-powered installations capture share where rural infrastructure gaps persist. Coastal municipalities balance heritage preservation requirements with energy efficiency mandates in historic district illumination.
Hauts-de-France
Departmental road services specify pole-mounted solutions for national route modernization with backward-compatible DALI control infrastructure. Legacy control system integration demands complicate smart-node rollouts. Cross-border purchasing cooperatives with Belgian counterparts aggregate demand through multilingual tender specifications.
Occitanie
Rural communes favor free-standing solar bollards where trenching costs exceed photovoltaic premium pricing. The AGEC anti-waste law's repairability indices filter procurement toward modular fixture architectures. Toulouse metropolitan expansion generates recurring demand for roadway and parking field coverage systems.
France Outdoor LED Lighting Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. Electrical infrastructure conglomerates leverage distribution breadth to anchor municipal framework agreements. Pure-play lighting specialists capture premium positioning through optical engineering differentiation and Dark Sky certification expertise. Dominant competitive moves include circular economy service contract transitions and modular platform standardization.
Among France-based specialists, Lucibel SA, Schréder, and Eclatec occupy positions within the premium architectural and roadway segments. Signify France and Legrand SA represent diversified electrical conglomerates with integrated control system portfolios. Thorn Lighting and Planlicht France exemplify mid-market positioning through standardized municipal specifications. Osram GmbH and Schneider Electric SE anchor multinational technology supply into French assembly operations.
| Leading Market Players |
|---|
| Lucibel SA |
| Thorn Lighting |
| Signify France |
| Osram GmbH |
| Schréder |
| Legrand SA |
| Eclatec |
| Planlicht France |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in French luminaire assembly anchor pricing discipline through captive die-cast housing production and long-term aluminum offtake agreements with European smelters. Their ownership structure insulates margin targets from quarterly earnings pressure, allowing sustained investment in modular platform standardization that transactional competitors cannot match.
Pricing Analysis
Margin tightening in standard-tier fixtures reflects London Metal Exchange aluminum volatility and German optical component premiums. Three-tier pricing structure across premium connected systems, standard modular units, and economy sealed designs tracks certification grade and after-sales service bundling. Pricing pressure intensifies in the economy tier as AGEC repairability requirements filter out non-compliant imports. Municipal buyers exhibit highest price sensitivity through aggregated cooperative procurement, while Parisian smart city operators accept premium positioning for sensor-embedded systems.
Supply Chain Analysis
Workforce availability constraints in German precision glass manufacturing and Austrian optical coating facilities are extending lead times for French assemblers. Die-cast housing production draws from French and Italian aluminum foundries, while gallium nitride substrates source from German and Japanese semiconductor facilities. Single-source vulnerability in specialty lens manufacturing creates concentration risk for Dark Sky-certified optical systems. Distribution runs through electrical wholesale networks anchored by Legrand SA and Schneider Electric SE infrastructure, with direct municipal contracting gaining share for large-scale retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum alloy input bottlenecks and specialized optical engineering capacity constraints are propping pricing power for incumbents with backward-integrated supply positions. Supply scarcity in certified Dark Sky optical systems creates defendable premium tiers.
For Market Incumbents: Acquire precision optical engineering capabilities in Auvergne-Rhône-Alpes to secure Dark Sky certification capacity before biodiversity lighting mandates proliferate. Consolidate regional die-cast housing production through French aluminum foundry partnerships to defend margin position against LME price swings. Threat substitution from solar-integrated off-grid systems demands accelerated cellular connectivity integration in standard-tier offerings. For New Entrants and Emerging Players: Launch via circular economy service contracts with Occitanie rural communes, bypassing capital-intensive manufacturing through luminaire-as-a-service models. White-space concentrates in solar-integrated free-standing bollards for grid-remote applications and wireless retrofit systems for heritage-sensitive contexts where trenching is restricted. Go-to-market should anchor on AGEC compliance consulting bundled with modular fixture supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor family-owned optical specialists in eastern France with established ANSM cybersecurity certification pathways. Long-term viability hinges on positioning for EU battery regulation compliance in solar-integrated portfolios. Signal to monitor: acceleration of cross-border purchasing cooperatives in Grand Est and Hauts-de-France compressing distributor margins and favoring direct manufacturer relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Enables LED engine swaps without luminaire replacement, aligning with AGEC repairability mandates. |
| Circular Economy Service Contract Transition | Shifts revenue from transactional sales to long-term maintenance subscriptions with French municipalities. |
| Dark Sky Optical System Certification | Captures premium positioning in Auvergne-Rhône-Alpes regional parks and protected night-sky reserves. |
| Cellular Mesh Connectivity Integration | Supports Parisian smart city infrastructure programs requiring remote dimming and predictive maintenance. |
| Backward Integration into Die-Cast Housing | Insulates margin from London Metal Exchange aluminum volatility and European smelter energy surcharges. |
Research Methodology
Document review covered EU Ecodesign Directive amendments, French AGEC anti-waste law implementation guidance, and ANSM cybersecurity framework publications, complemented by interviews with municipal lighting concession managers, electrical distribution procurement directors, and modular fixture engineering leads. Secondary sources included customs trade data for aluminum alloy imports, SEC filings of diversified electrical conglomerates, and French departmental road service retrofit program disclosures. Bottom-up fixture deployment estimates triangulated against top-down municipal budget allocation analysis.
Cross-referencing historical retrofit cycle patterns with expert panel input on smart city infrastructure rollout timelines shaped the projection framework. Segmentation dimensions modeled include product type, installation configuration, end-user category, and technology layer across the analysis window. CAGRs derived from installed base replacement dynamics and premium connected system penetration curves. Industry-specific inputs incorporated gallium nitride thermal management advancement trajectories and EU battery regulation compliance cost assumptions for solar-integrated portfolios.
Aluminum price volatility, optical component supply disruption, and cybersecurity standard revision are the dominant revision risks to forecast assumptions. Material deviation in any trigger warrants strategic pause and re-evaluation of capacity and pricing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Flip Chip Market
LED
LED Lighting Solution Market
LED
LED Encapsulation Market
LED
Mini LED Market
LED
LED Lighting Controllers Market
LED
Saudi Arabia LED Lights Market
LED
Europe Outdoor LED Lighting Market
LED
LED Light Bar Market
LED
France Indoor LED Lighting Market
LED
Africa LED Lighting Market
LED
LED Lamp Market
LED
High Power LED Market
LED
North America Indoor LED Lighting Market
LED
Global Waterproof LED Module Market
LED
India LED Outdoor Lighting Market
LED
Mini LED Display Market