
 Latin America Wearable Sensors Market | 2026-2036
Latin America Wearable Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Wearable Sensors Market Foresight
Subscription-based health analytics is hardening as the core revenue layer in Latin America wearable sensors, shifting vendor economics from hardware margins to recurring software revenue. Apple Inc. leverages its HealthKit ecosystem to anchor premium positioning across Brazilian urban centers. Samsung Electronics competes through Galaxy Watch integrations with local telehealth platforms. Garmin specializes in sports performance segments where GPS-accelerometer fusion commands pricing power among endurance athletes in Argentina and Chile.
Wearable sensors are electromechanical transducers embedded in wrist-worn, body-worn, or textile-integrated form factors, converting physiological or kinematic signals into processable digital outputs through MEMS fabrication, flexible printed circuit lamination, or conductive yarn weaving; their primary purpose is continuous ambulatory monitoring of biopotentials, motion vectors, or environmental exposures for preventive health, athletic optimization, or clinical surveillance. Biosensors within the technology stack capture expanding margin pools as glucose and lactate enzymatic electrodes migrate from clinical settings to consumer wristbands. Health Monitoring among applications leads absolute revenue generation through hypertension and cardiac arrhythmia detection programs sponsored by Mexican public health institutions. Smartwatches within product type categories dominate unit volume, though Health Monitors sustain higher average selling prices through prescription-channel distribution in Colombian and Peruvian markets.
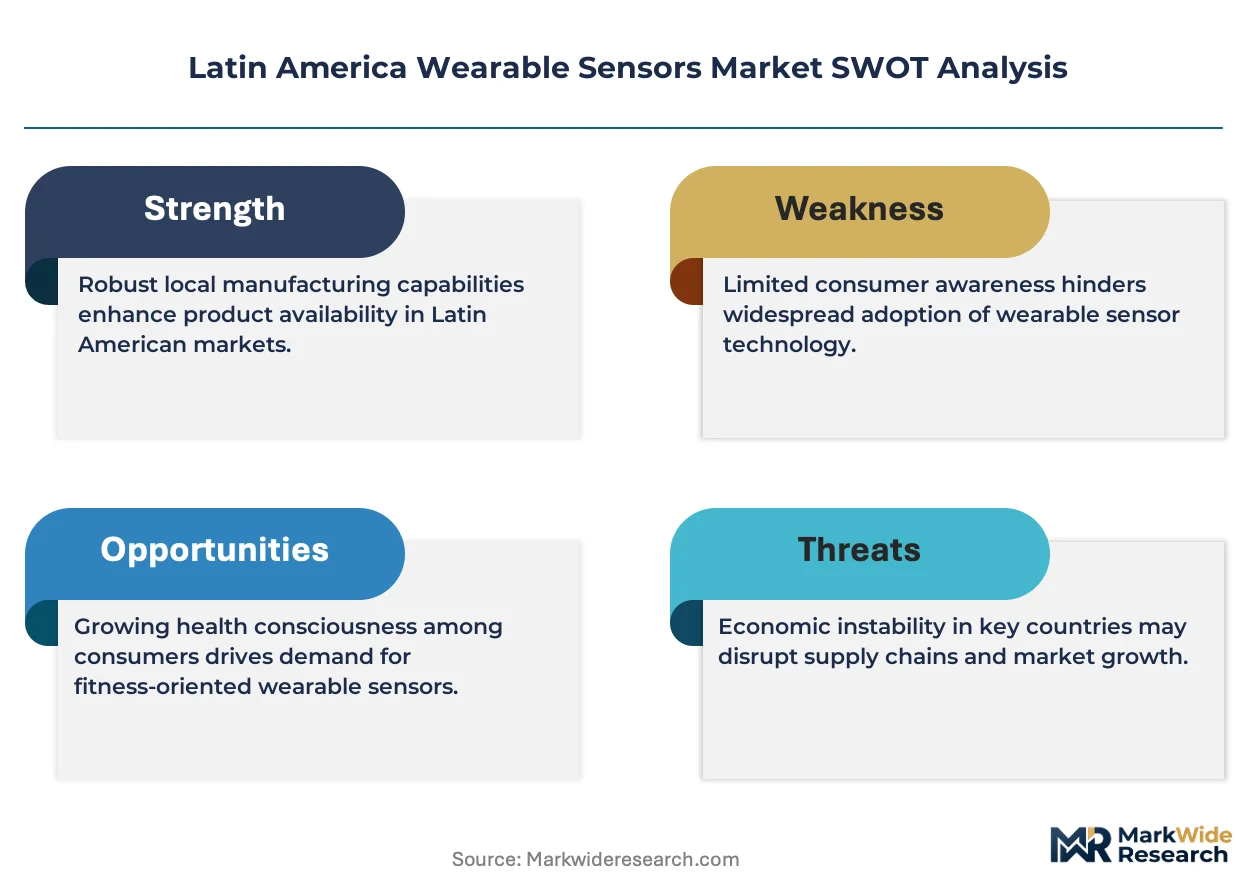
ANVISA in Brazil and COFEPRIS in Mexico enforce medical device classification tiers that determine whether wearable sensors require full registration or qualify for streamlined software-as-medical-device pathways, directly shaping product development roadmaps and go-to-market timelines for vendors. Brazil's LGPD data protection framework and Mexico's LFPDPPP impose cross-border data residency requirements that constrain cloud analytics architectures and elevate local server infrastructure investments. Stakeholders must monitor how pending harmonization between Mercosur and Pacific Alliance technical standards reshapes testing certification burdens for multi-country product rollouts.
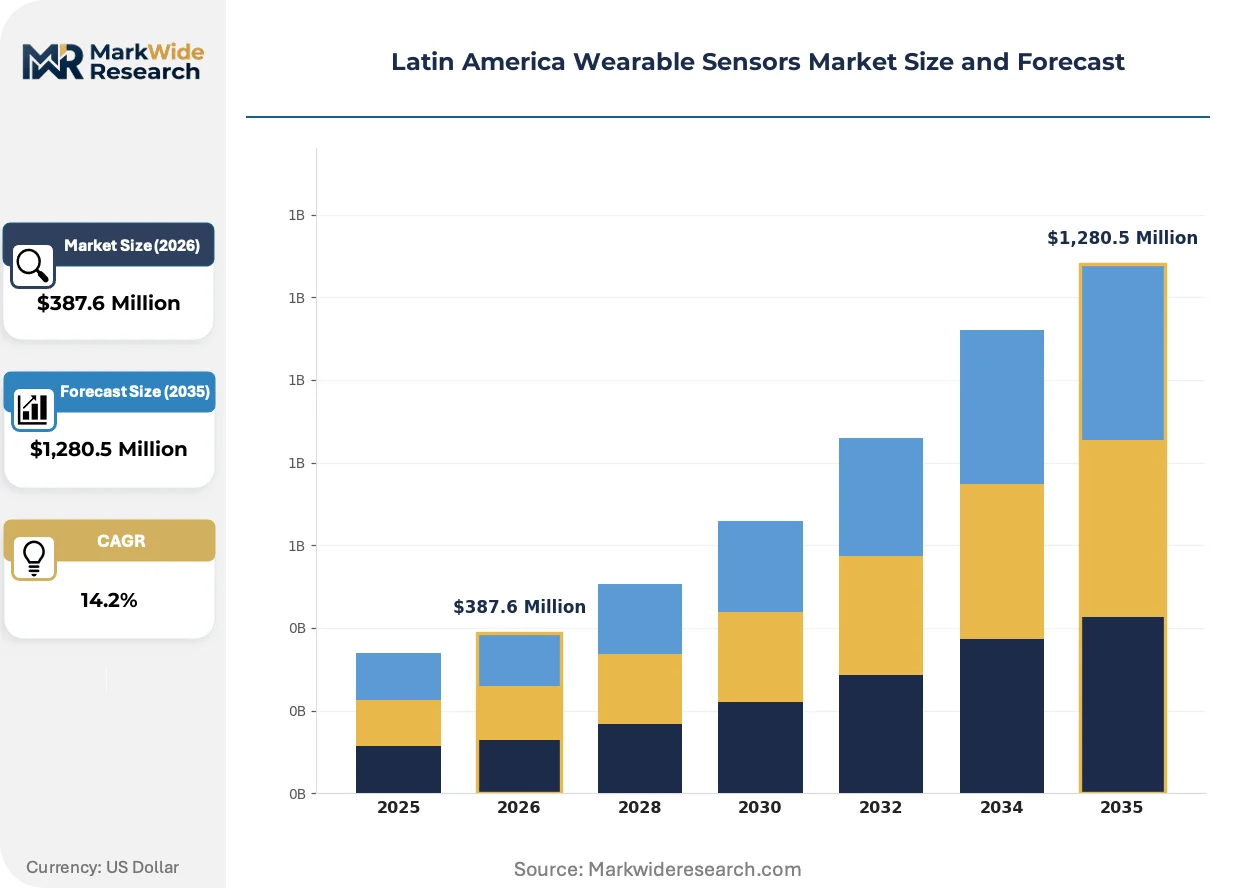
Market Dynamics
Subscription-based health analytics is hardening as the dominant revenue architecture across Latin America wearable sensors, compressing hardware margins and elevating recurring software streams as the primary value capture mechanism for vendors.
Growth Catalysts
- ANVISA software-as-medical-device pathways:Brazil's streamlined registration tiers accelerate market entry for algorithm-driven wearables, reducing time-to-commercialization for glucose monitoring and cardiac surveillance devices.
- Remote patient monitoring expansion:Healthcare providers across São Paulo and Rio de Janeiro deploy continuous ambulatory programs for hypertension management, creating institutional demand for prescription-channel distribution.
- Biosensor electrode miniaturization:Enzymatic glucose and lactate sensors migrate from clinical settings to consumer wristbands, expanding addressable populations beyond diagnosed diabetics to prediabetic wellness segments.
Market Restraints
- MEMS foundry concentration:Sensor fabrication capacity concentrates in East Asian contract manufacturers, exposing Latin American vendors to input cost volatility and extended lead times for accelerometer and gyroscope modules.
- Cross-border data residency mandates:Brazil's LGPD and Mexico's LFPDPPP impose local server infrastructure requirements that elevate cloud analytics costs and complicate multi-country platform architectures.
- Smartphone tethering dependency:Wearable sensor functionality remains contingent on paired mobile devices, limiting adoption among aging populations with lower smartphone penetration in rural Colombian and Peruvian zones.
Strategic Opportunities
- Andean sports performance segments:GPS-accelerometer fusion devices target endurance athletes in Argentina and Chile where altitude training creates premium pricing tolerance for specialized kinematic analytics.
- Mercosur-Pacific Alliance harmonization:Pending technical standard alignment promises to reduce redundant testing certification burdens for vendors pursuing multi-country rollouts across South American markets.
- Textile-integrated form factors:Conductive yarn weaving enables garment-embedded biosensors for occupational safety applications in Brazilian agriculture and mining sectors requiring continuous physiological surveillance.
Industry Challenges
- Embedded firmware talent scarcity:Shortage of engineers with MEMS signal processing and low-power Bluetooth stack expertise constrains product development velocity for regional hardware startups.
- COFEPRIS classification uncertainty:Mexican medical device tier determinations for novel sensor algorithms create unpredictable registration timelines that disrupt commercial planning and inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Wearable Sensors Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smartwatches, Health Monitors, Smart Clothing End User: Fitness Enthusiasts, Healthcare Providers, Elderly Patients, Tech Savvy Consumers Technology: Biosensors, Accelerometers, Bluetooth, NFC Application: Health Monitoring, Sports Performance, Sleep Tracking, Emergency Response |
| Companies Covered | Apple Inc., Samsung Electronics, STMicroelectronics, Infineon Technologies, Texas Instruments, Analog Devices, Fitbit, Garmin, Panasonic Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Wearable Sensors Market Shifts & Advancements
Electromechanical transducer architectures are undergoing functional convergence as physiological and kinematic sensing modalities merge into unified wearable platforms, compressing discrete device categories and reshaping vendor specialization boundaries.
Photoplethysmography with multi-wavelength LED arrays is consolidating as the standard non-invasive modality for continuous blood oxygen, heart rate variability, and blood pressure estimation. Brazilian hospital systems integrate these sensors into post-discharge monitoring protocols for cardiac patients. The technology is consolidating previously separate pulse oximeter and Holter monitor markets into single wrist-worn devices.
ANVISA's 2023 software-as-medical-device classification guidance creates explicit regulatory pathways for algorithm-driven diagnostic features. Vendors now embed arrhythmia detection and sleep apnea screening directly into consumer firmware without full hardware registration. Mexican public health institutions leverage this clarity to sponsor population-scale hypertension detection programs using certified wearable devices.
Employer-sponsored wellness programs are displacing direct-to-consumer channels as the primary volume driver for mid-tier health monitors. Brazilian corporate benefits platforms bundle wearable subscriptions with telehealth access, capturing sustained engagement through payroll deduction models. This shift concentrates procurement decisions into benefits administrators rather than individual buyers, elevating B2B sales complexity for hardware vendors.
Latin America Wearable Sensors Market Segmentation
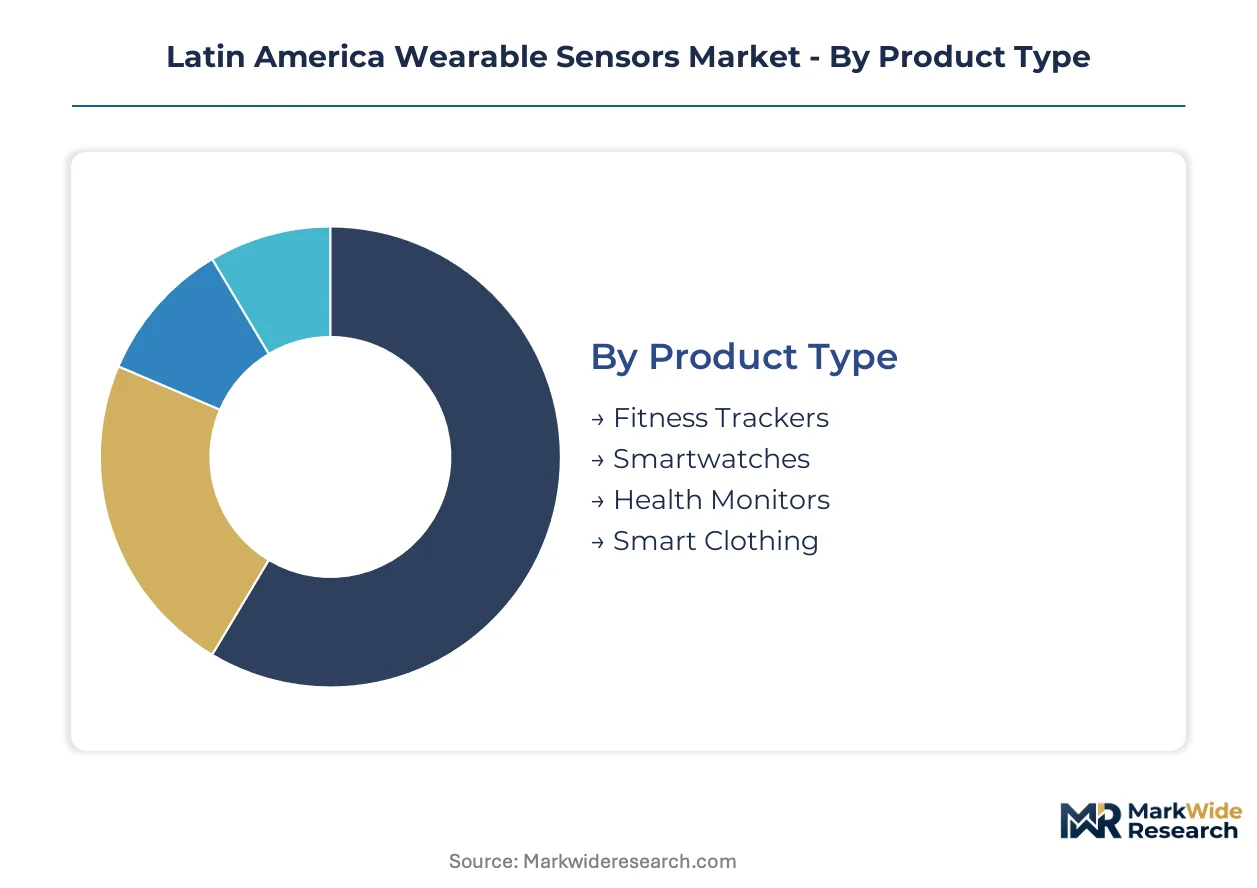
Segmentation in Latin American wearable sensors reveals how hardware form factors, user demographics, and sensing modalities intersect with distinct regulatory pathways and procurement channels across Brazil, Mexico, and Andean markets.
Product Type:
Replacement cycles vary sharply across form factors, with wrist-worn devices compressing to 18-24 month refresh intervals while textile-integrated platforms extend toward 36-month industrial procurement schedules.
- Smartwatches:Photoplethysmography and multi-wavelength LED arrays consolidate pulse oximetry, cardiac monitoring, and sleep staging into unified wrist-worn platforms. São Paulo hospital systems deploy these for post-discharge cardiac surveillance, with ANVISA software-as-medical-device pathways enabling algorithm-driven diagnostic features without full hardware re-registration.
- Health Monitors:Prescription-channel distribution through Colombian and Peruvian clinical networks sustains premium average selling prices for single-purpose devices targeting hypertension and glucose surveillance. COFEPRIS classification tiers in Mexico determine whether novel sensor algorithms require full registration or qualify for streamlined pathways.
- Fitness Trackers:Entry-level accelerometer-based units dominate unit volume in Brazilian retail channels through payroll-deduction corporate wellness programs.
- Smart Clothing:Conductive yarn weaving embeds biosensors into garments for occupational safety in Brazilian agriculture and mining sectors requiring continuous physiological surveillance.
Smartwatches sits at the top of the volume ranking, with Smart Clothing climbing the fastest.
End User:
Procurement authority concentrates in distinct institutional layers, with healthcare providers and corporate benefits administrators displacing individual consumers as decision-makers for premium-tier deployments.
- Healthcare Providers:Brazilian southeastern hospital corridors spanning São Paulo and Rio de Janeiro expand remote patient monitoring programs for hypertension management, creating institutional demand for continuous ambulatory surveillance with prescription-channel reimbursement.
- Fitness Enthusiasts:GPS-accelerometer fusion devices command pricing tolerance among endurance athletes in Argentina and Chile where altitude training creates demand for specialized kinematic analytics.
- Elderly Patients:Smartphone tethering dependency limits adoption in rural Colombian and Peruvian zones where mobile penetration lags among aging populations.
- Tech Savvy Consumers:Direct-to-consumer channel erosion accelerates as employer-sponsored wellness platforms capture sustained engagement through bundled telehealth access.
Healthcare Providers anchor the revenue base, while Fitness Enthusiasts show the steepest expansion trajectory.
Technology:
Margin pools concentrate in sensing layers where enzymatic electrode miniaturization and MEMS fabrication complexity create defensible intellectual property positions.
- Biosensors:Glucose and lactate enzymatic electrodes migrate from clinical settings to consumer wristbands, expanding addressable populations beyond diagnosed diabetics to prediabetic wellness segments in Mexican urban centers.
- Accelerometers:MEMS foundry concentration in East Asian contract manufacturers exposes Latin American vendors to input cost volatility and extended lead times for motion-sensing modules.
- Bluetooth:Low-energy stack expertise scarcity constrains product development velocity for regional hardware startups seeking firmware optimization.
- NFC:Contactless payment and medical record access integration lags in deployment due to fragmented banking infrastructure across Andean markets.
Biosensors command the highest margin tier, with Accelerometers maintaining dominant unit attachment rates.
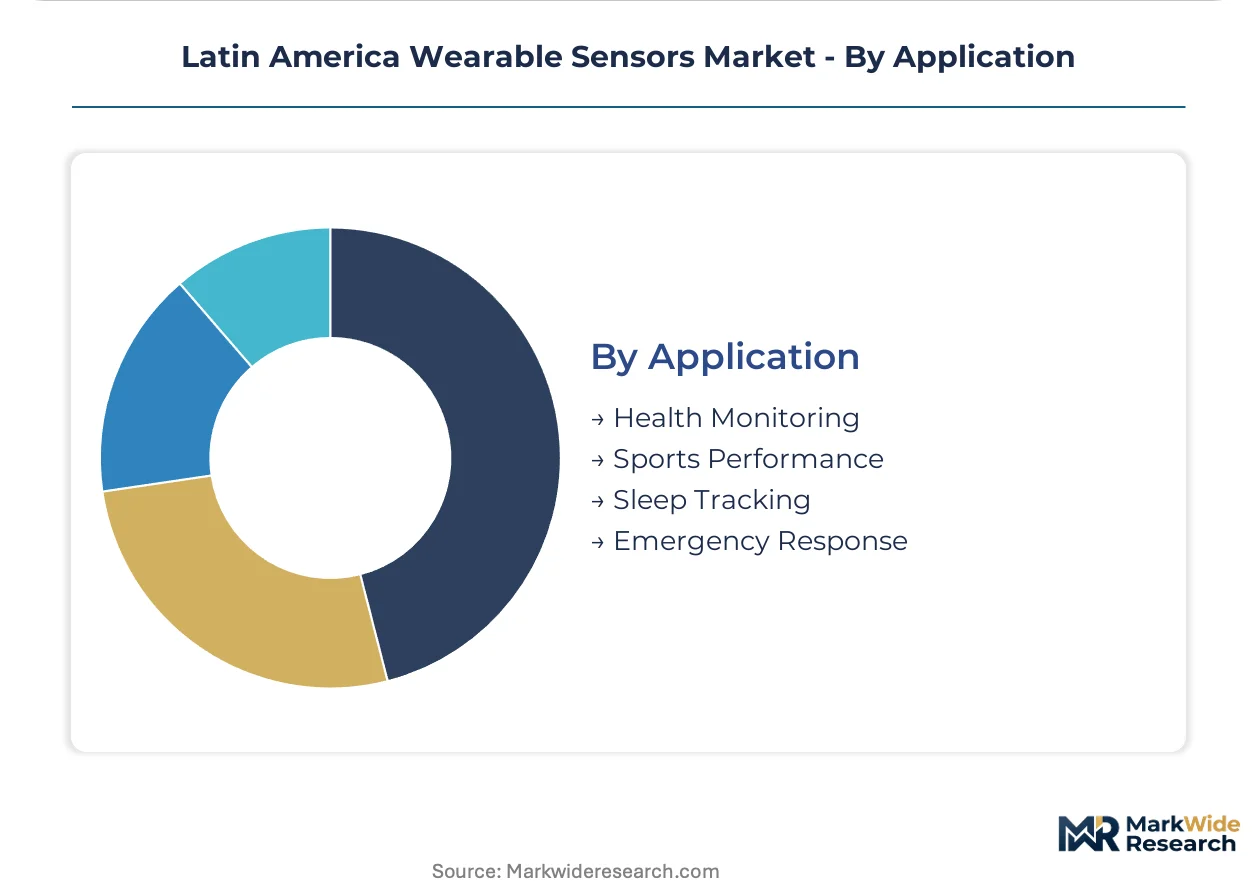
Application:
Use-case maturity determines whether vendors capture value through hardware margins or recurring software subscriptions, with clinical surveillance applications hardening toward SaaS revenue architectures.
- Health Monitoring:Mexican public health institutions sponsor population-scale hypertension detection programs using certified wearable devices, consolidating previously separate pulse oximeter and Holter monitor markets into single platforms.
- Sports Performance:Altitude training regimens in Argentine and Chilean endurance athletics create premium pricing tolerance for GPS-kinematic fusion analytics with real-time lactate threshold estimation.
- Sleep Tracking:Multi-wavelength photoplethysmography enables sleep apnea screening embedded in consumer firmware under ANVISA software-as-medical-device guidance.
- Emergency Response:Fall detection and automated alert systems penetrate slowly among elderly populations due to smartphone tethering requirements and rural connectivity gaps.
Health Monitoring leads absolute revenue generation, with Sports Performance gaining share fastest among premium-tier deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil captures institutional procurement volume while Mexico drives algorithm-driven diagnostic adoption through public health sponsorship programs.
Brazil
ANVISA software-as-medical-device pathways accelerate commercialization timelines for glucose monitoring and cardiac surveillance wearables. The LGPD data protection framework mandates local server infrastructure for cloud analytics platforms. São Paulo and Rio de Janeiro anchor the southeastern hospital corridor where remote patient monitoring programs for hypertension management generate prescription-channel demand.
Mexico
COFEPRIS medical device classification tiers determine registration requirements for novel sensor algorithms. The LFPDPPP imposes cross-border data residency constraints that elevate platform architecture costs. Mexican public health institutions sponsor population-scale hypertension detection programs using certified wearable devices.
Argentina
Endurance athletics in altitude training regimens create premium pricing tolerance for GPS-kinematic fusion analytics. The national pharmaceutical regulator oversees device classification for clinical-grade wearables. Buenos Aires and Mendoza concentrate sports performance segments where real-time lactate threshold estimation commands specialized demand.
Chile
Outdoor recreation and professional athletics sustain demand for ruggedized GPS-accelerometer devices. The central bank's fintech regulations influence contactless payment integration in consumer wearables. Santiago anchors procurement decisions for corporate wellness platforms bundling wearable subscriptions with telehealth access.
Colombia
Prescription-channel distribution through clinical networks sustains premium average selling prices for single-purpose health monitors. The national data protection authority enforces local processing requirements for health analytics platforms. Bogotá and Medellín concentrate healthcare provider procurement for continuous ambulatory surveillance devices.
Latin America Wearable Sensors Market Competitive Landscape
Top-tier vendors anchor premium positioning through ecosystem integration, while mid-tier specialists compete on sports performance segmentation and component supply. The vendor base spans three strategic tiers: consumer electronics platforms with health analytics software, MEMS component fabricators supplying sensor modules, and specialized sports performance device manufacturers. Competitive moves concentrate on strategic partnerships with telehealth platforms and portfolio diversification into textile-integrated form factors.
Within the consumer platform tier, Apple Inc. and Samsung Electronics exemplify ecosystem-driven positioning through health analytics software integration. Garmin occupies a position representing specialized sports performance segmentation. STMicroelectronics, Infineon Technologies, Texas Instruments, and Analog Devices anchor the component supply layer supplying MEMS fabrication and signal processing modules to downstream device manufacturers.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| STMicroelectronics |
| Infineon Technologies |
| Texas Instruments |
| Analog Devices |
| Fitbit |
| Garmin |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Silicon wafer spot indices from East Asian contract manufacturers cascade through Latin American wearable sensor supply chains, compressing margin buffers for accelerometer and gyroscope modules while elevating premium pricing for biosensor-integrated devices with local firmware customization.
Pricing Analysis
Capacity additions in Taiwanese MEMS foundries are reshaping price floors for motion-sensing modules, yet enzymatic electrode miniaturization sustains premium tiers. Subscription-based SaaS revenue models dominate health monitoring applications, separating prescription-channel devices from direct-to-consumer fitness trackers. Certification under ANVISA software-as-medical-device pathways commands price premiums against unregistered wellness devices. Price differentiation hinges on glucose monitoring accuracy grades and local data residency compliance. Cost compression in entry-level fitness trackers intensifies as Brazilian corporate wellness programs consolidate procurement volume.
Supply Chain Analysis
Freight cost volatility from East Asian hubs to São Paulo and Mexico City elevates landed costs for MEMS modules and flexible printed circuit substrates. Sensor fabrication concentrates in Taiwan, South Korea, and China, drawing Latin American vendors into extended lead time exposure for accelerometer components. Raw material dependencies span silicon wafers, lithium-ion cells, and conductive yarn polymers. Single-source vulnerability in Bluetooth low-energy chipset supply creates procurement risk. Distribution runs through Brazilian payroll-deduction benefits platforms and Mexican telehealth channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory clarity, with ANVISA's 2023 software-as-medical-device classification guidance accelerating algorithm-driven diagnostic commercialization across Brazilian hospital systems.
For Market Incumbents: To counter firmware talent scarcity constraining regional product development, anchor ecosystem control through backward integration into MEMS signal processing IP and captive supply of low-power Bluetooth stack expertise. Deepen channel control via exclusive partnerships with São Paulo benefits administrators consolidating corporate wellness procurement.
For New Entrants and Emerging Players: Capture white-space in Andean sports performance segments where altitude training regimens in Argentina and Chile sustain premium pricing tolerance for GPS-kinematic fusion analytics. Target textile-integrated occupational safety applications in Brazilian agriculture and mining sectors requiring continuous physiological surveillance. Prioritize COFEPRIS streamlined registration pathways for novel lactate threshold estimation algorithms.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized sports performance device manufacturers holding altitude-training IP and enzymatic electrode miniaturization patents. Long-term viability rests on recurring SaaS revenue attachment rates rather than hardware refresh cycles. Watch for Mercosur-Pacific Alliance technical standard harmonization as inflection signal for multi-country rollout scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Certification | ANVISA pathway acceleration enables algorithm-driven diagnostics without full hardware re-registration. |
| Telehealth Platform Integration | Galaxy Watch and local platform partnerships capture institutional procurement through bundled subscriptions. |
| Textile-Integrated Form Factor Development | Conductive yarn weaving opens occupational safety demand in Brazilian mining and agriculture sectors. |
| Local Server Infrastructure Deployment | LGPD and LFPDPPP compliance elevates cloud analytics costs but creates competitive moats. |
| Enzymatic Electrode Miniaturization | Glucose and lactate sensor migration to consumer wristbands expands addressable wellness populations. |
Research Methodology
Direct dialogue with biomedical engineers at São Paulo hospital systems, COFEPRIS regulatory affairs specialists, Brazilian corporate benefits administrators, and MEMS component procurement leads grounded qualitative findings. Secondary validation drew from ANVISA medical device registration databases, COFEPRIS classification guidance documents, GPO contracts for remote patient monitoring programs, and SEC filings of sensor component suppliers. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, and technology dimensions.
Bottom-up unit economics for smartwatch, health monitor, and textile-integrated platforms were reconciled with top-down healthcare expenditure flows across the analysis window. Segmentation modeling captured product type, end user archetype, sensing technology, and application use-case variations. CAGRs derived from installed base projections, replacement cycle compression, and subscription revenue attachment rates. Forecast inputs incorporated ANVISA registration velocity, LGPD infrastructure investment requirements, and altitude-training athlete population estimates.
Regulatory reclassification delays, MEMS foundry capacity constraints, and cross-border data residency enforcement shifts are the dominant revision risks. Forecasts reflect documented assumptions on software-as-medical-device adoption curves and corporate wellness program penetration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Predictive Touch Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Taiwan Sensors Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
India Industrial Sensors and Transmitters Market