
 Molded Interconnect Devices (MID) Market | 2026-2036
Molded Interconnect Devices (MID) Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Interconnect Devices (MID) Market Analysis
Skilled laser structuring technicians is unwinding capacity bottlenecks at precision electronics manufacturers across Germany and Japan. LPKF Laser & Electronics leverages its proprietary LDS equipment portfolio to dominate photonic patterning workflows for automotive antenna modules. Molex sustains broad geographic manufacturing coverage across North American and Asian plants, securing preferred-supplier status with tier-one automotive harness makers. TactoTek anchors growth in injection-molded structural electronics through its IMSE technology platform, converting passive plastic parts into active circuit carriers for consumer appliances.
Molded Interconnect Devices integrate conductive circuit traces onto three-dimensional thermoplastic substrates through laser direct structuring, two-shot molding, or film insert techniques, typically achieving trace widths of 150 micrometers and enabling functional density impossible with conventional flat printed circuit boards. The devices primarily serve applications demanding miniaturized electromechanical integration where space constraints prohibit separate PCB assembly. Laser Direct Structuring occupies the premium technology tier due to its design flexibility and elimination of masking steps, while Multi-Shot Molding captures volume automotive applications where durability under thermal cycling proves decisive. Consumer Electronics end-use demand orbits around smartphone antenna modules and wearable sensor housings, though Automotive applications in EV power distribution and ADAS sensor enclosures are expanding fastest.
FDA biocompatibility requirements for implantable and diagnostic device materials constrain substrate polymer selection and plating chemistry choices in medical MID applications. REACH substance restrictions and RoHS hazardous material limits in Europe mandate lead-free plating alternatives and full material disclosure across supply chains. OEMs and molders must monitor evolving ECHA candidate list expansions for novel restricted substances affecting flame-retardant additives in automotive-grade substrates. Stakeholders should prioritize dual-registration strategies that satisfy both FDA device master file requirements and EU MDR technical documentation obligations before committing to high-volume medical or automotive production lines.
Market Dynamics
Automotive electrification and miniaturization imperatives are compressing design cycles for three-dimensional circuit integration, forcing substrate suppliers and laser equipment vendors to synchronize roadmaps with tier-one harness makers.
Growth Catalysts
- ADAS Sensor Enclosure Demand:German and Japanese automakers are specifying MID housings for radar and lidar modules to reduce assembly complexity and electromagnetic interference.
- REACH Substance Restrictions:ECHA candidate list expansions are accelerating lead-free plating chemistry adoption, creating upgrade cycles for existing production lines.
- Laser Direct Structuring:LDS equipment improvements are extending viable substrate materials beyond traditional LCP to lower-cost PBT blends for consumer electronics antenna modules.
Market Restraints
- Palladium Price Volatility:Electroless plating chemistries depend on palladium activators, with spot price swings compressing margins for job-shop platers serving medical device OEMs.
- Equipment Supplier Concentration:Precision laser structuring systems for sub-150-micron trace widths concentrate among German and Japanese capital equipment vendors, creating procurement bottlenecks.
- Two-Shot Molding Substitution:Conventional insert-molded flex circuits retain cost advantages for low-complexity automotive lighting applications below 500,000 annual units.
Strategic Opportunities
- Chinese EV Component Ecosystems:Domestic battery pack manufacturers are evaluating MID busbars and contactors for cell-to-pack architectures, creating entry points for substrate specialists with localized plating capacity.
- Film Insert Molding Convergence:Combination of printed electronics films with thermoformed substrates enables curved touch surfaces for appliance control panels without separate PCB attachment.
- EU Medical Device Regulation Tailwinds:MDR technical documentation requirements favor suppliers with established FDA master files, rewarding early dual-registered polymer compounders.
Industry Challenges
- Laser Structuring Technician Scarcity:Precision parameter tuning for multi-layer substrates requires 18-24 month apprenticeship pipelines that German manufacturers struggle to fill.
- RoHS Compliance Verification:Full material disclosure across plating additive supply chains demands spectroscopic testing protocols that smaller molders lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Interconnect Devices (MID) Market |
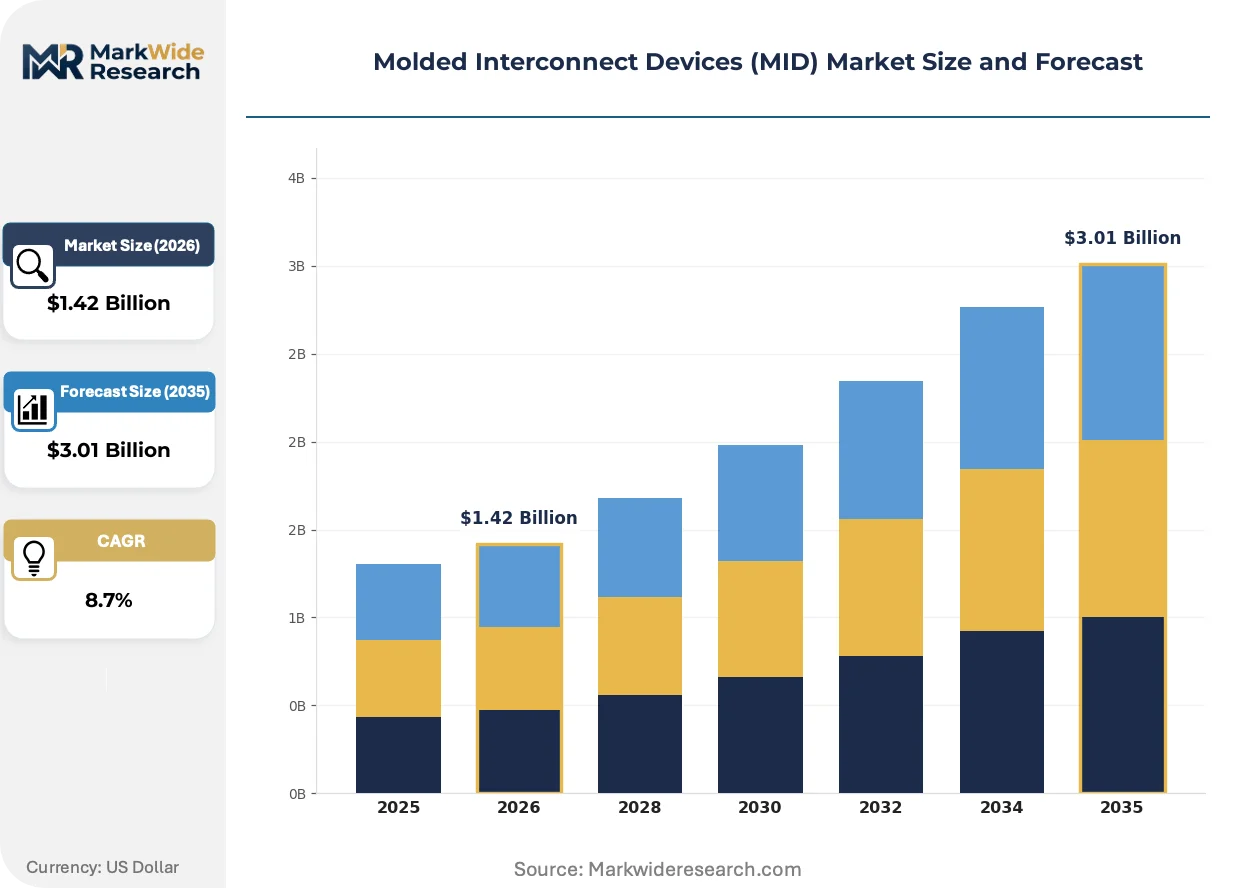
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Molding, Direct Molding, Multi-Shot Molding, Laser Direct Structuring End User: Consumer Electronics, Automotive, Telecommunications, Medical Devices Technology: Injection Molding, Compression Molding, Overmolding, Additive Manufacturing Application: Lighting, Sensors, Power Distribution, Connectivity Solutions |
| Companies Covered | LPKF Laser & Electronics, JOHNAN, Molex, MID Solutions, APC, TE Connectivity, TactoTek, Galtronics, HARTING Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Interconnect Devices (MID) Market Emerging Trajectories
Process-material convergence is collapsing traditional boundaries between mechanical engineering and electronics manufacturing, with substrate suppliers acquiring plating chemistry capabilities and equipment vendors embedding quality verification into laser systems.
Laser Direct Structuring is bifurcating into high-flexibility prototyping workflows using fiber lasers and high-throughput production systems employing ultraviolet sources for fine-pitch antenna applications. South Korean smartphone manufacturers are migrating toward UV-LDS for 5G mmWave antenna modules. The technology is bifurcating equipment vendor strategies between precision-focused specialists and throughput-optimized platform suppliers.
ECHA REACH candidate list expansions are prohibiting specific brominated flame retardants in automotive interior substrates, compelling compounders to reformulate PBT and PA blends with phosphorus-based alternatives. Plating chemistry suppliers must validate new substrate surfaces for adhesion and conductivity. Medical device manufacturers face the tightest compliance timelines as notified bodies prioritize MDR transition reviews.
Consolidated procurement by tier-one automotive harness makers is compressing supplier bases, with Molex and Yazaki specifying approved substrate and plating vendors for MID content in wiring assemblies. Molded interconnect specialists must achieve PPAP approval at multiple tiers simultaneously. South Korean electronics manufacturing services are extending this pattern to smartphone antenna module supply chains.
Molded Interconnect Devices (MID) Market Segmentation
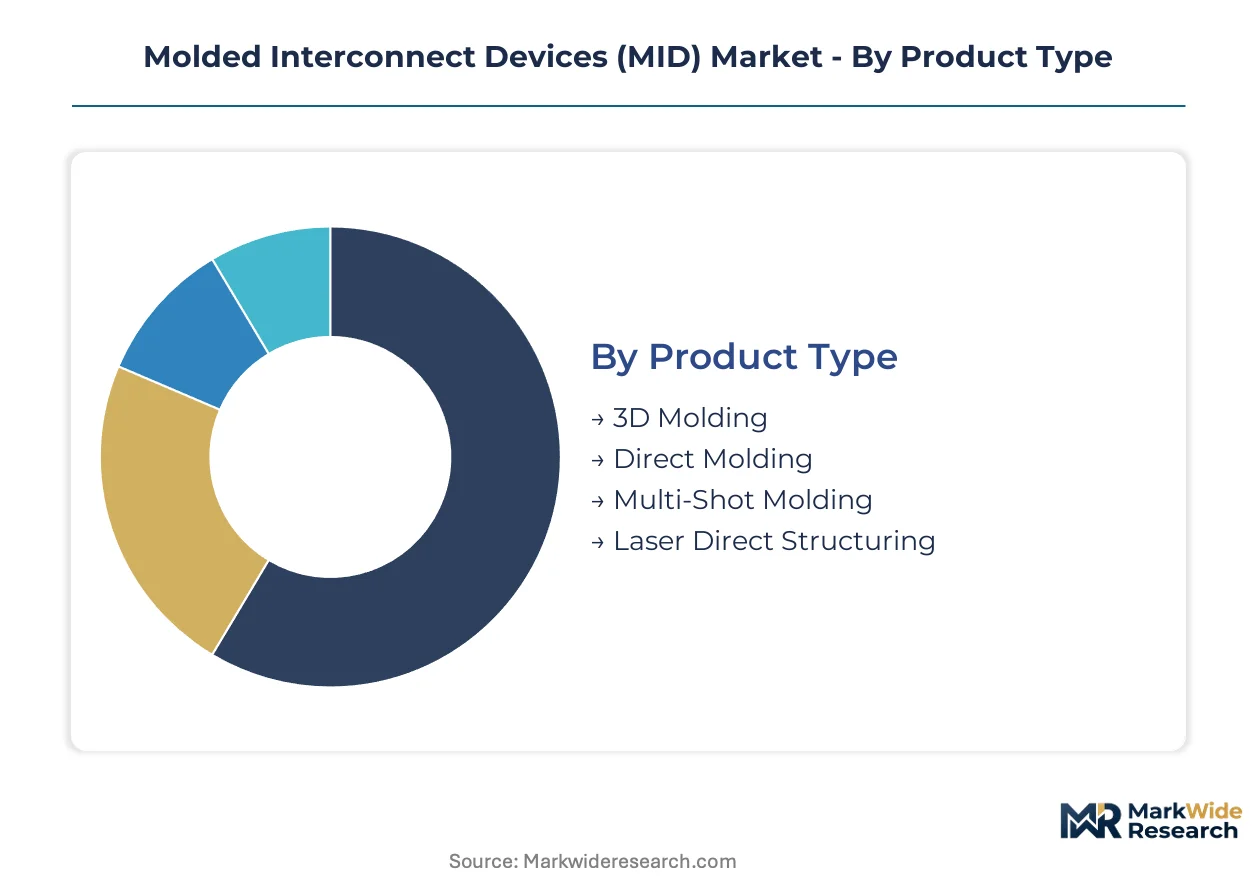
MID segmentation reflects fundamental trade-offs between design flexibility, production scale, and regulatory compliance burden. Each dimension—product type, end user, technology, and application—carries distinct certification requirements and capital intensity profiles that shape supplier specialization.
Product Type:
REACH substance restrictions and FDA biocompatibility rules create divergent material qualification pathways across these four manufacturing approaches.
- Laser Direct Structuring:Fiber and UV laser systems activate thermoplastic substrates with additive metal traces, achieving 150-micrometer feature resolution without masking. German automotive harness makers specify LDS for radar module housings where electromagnetic interference shielding is critical.
- Multi-Shot Molding:Sequential injection of conductive and non-conductive polymers creates integrated circuit paths within a single tool cycle. Japanese tier-one suppliers favor this approach for EV power distribution components subject to thermal cycling stress.
- 3D Molding:Thermoformed substrates with printed conductive layers suit curved appliance control panels requiring moderate circuit density.
- Direct Molding:Single-shot processes with embedded conductive inserts serve cost-sensitive lighting applications with simpler geometries.
Multi-Shot Molding handles the majority of throughput; Laser Direct Structuring is gaining share fastest on automotive antenna demand.
End User:
Customer procurement patterns split between high-volume consumer electronics with compressed design cycles and medical-automotive segments with extended qualification timelines.
- Automotive:ADAS sensor enclosures and EV power distribution modules drive specification activity. ECHA flame-retardant restrictions are forcing PBT compound reformulations for interior applications.
- Consumer Electronics:South Korean smartphone manufacturers dominate antenna module procurement. UV-LDS adoption for 5G mmWave arrays is displacing conventional flex circuit attachments.
- Medical Devices:FDA master file requirements and EU MDR technical documentation constrain substrate and plating chemistry selection. Implantable applications demand biocompatible polymer grades with full material disclosure.
- Telecommunications:Base station antenna arrays and small-cell housings require weather-resistant substrates with stable RF performance across temperature ranges.
Automotive commands the largest committed capacity; Consumer Electronics shows the steepest expansion trajectory on 5G infrastructure deployment.
Technology:
Process selection hinges on substrate material compatibility, feature resolution requirements, and integration with downstream plating operations.
- Injection Molding:Dominant platform for LCP and PBT-based substrates. LPKF equipment vendors optimize laser parameters for specific melt-flow characteristics.
- Overmolding:Encapsulation of pre-formed circuit elements suits medical device applications requiring hermetic sealing.
- Compression Molding:Lower shear stress benefits fiber-reinforced substrates in automotive structural electronics.
- Additive Manufacturing:Fused filament and selective laser sintering approaches enable prototyping workflows without hard tooling investment.
Injection Molding carries the bulk of commercial volume; Additive Manufacturing is climbing fastest on prototyping demand from appliance designers.
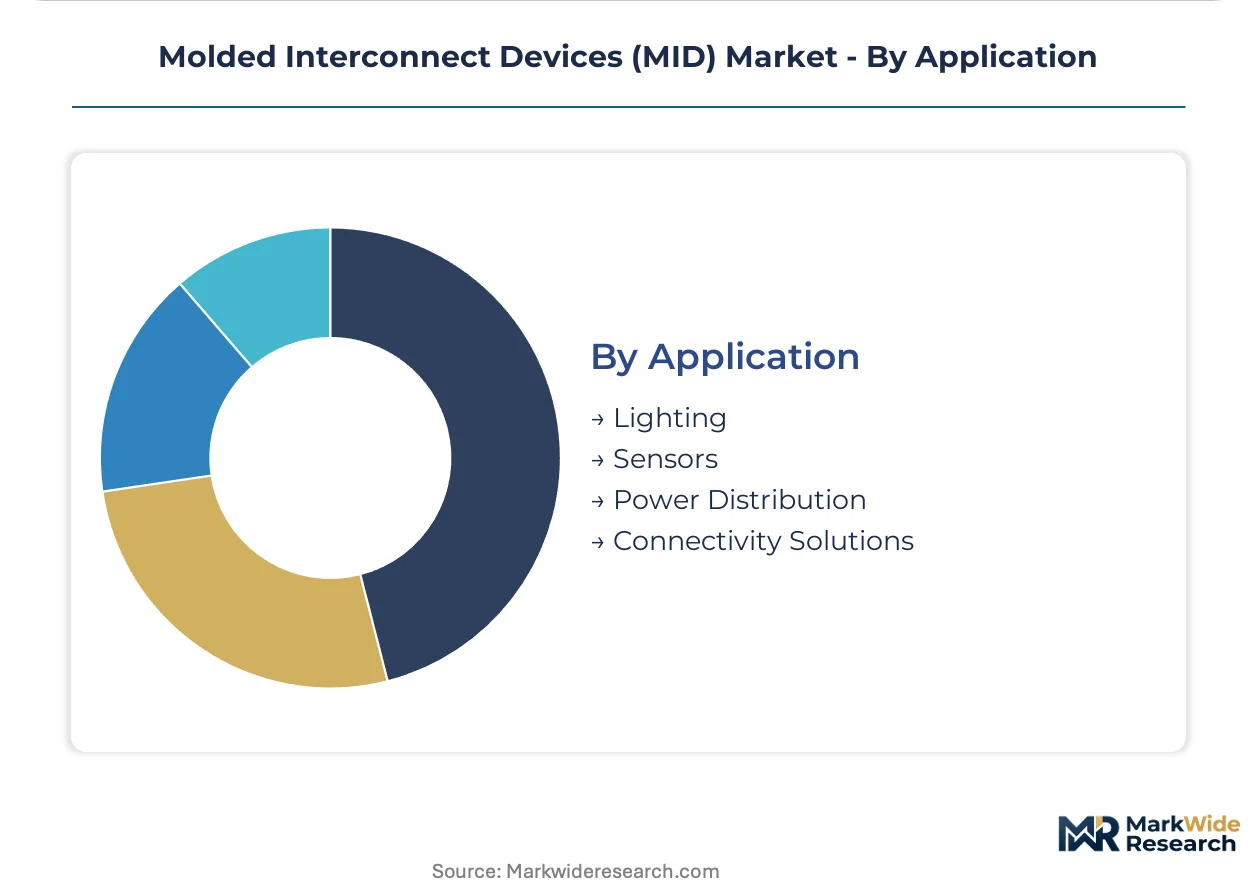
Application:
Functional requirements determine substrate thermal performance, plating thickness specifications, and environmental sealing grades.
- Sensors:Radar and lidar module housings integrate shielding traces and connector interfaces in single-piece geometries. German OEMs specify these for ADAS platforms.
- Connectivity Solutions:Antenna modules and RF connectors demand controlled impedance traces with tight dimensional tolerance.
- Lighting:LED module carriers and headlamp control units prioritize thermal management over circuit density.
- Power Distribution:Busbar replacements and contactor housings in Chinese EV battery packs require current-carrying capacity validation.
Sensors absorb the greatest plating chemistry volume; Power Distribution is expanding most quickly on cell-to-pack architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH substance restrictions are reshaping substrate formulation requirements across the European manufacturing footprint. German automotive harness makers and South Korean smartphone manufacturers anchor committed capacity expansion.
Germany
ADAS sensor enclosure demand from BMW and Mercedes-Benz suppliers is accelerating LDS qualification timelines for radar module housings. KBA vehicle type approval processes now reference ECHA flame-retardant restrictions for interior electronic substrates. Stuttgart and Munich industrial clusters concentrate laser structuring equipment deployment for automotive antenna applications.
China
Domestic EV battery pack manufacturers are evaluating MID busbars for cell-to-pack architectures in BYD and CATL supply chains. MIIT new energy vehicle certification standards now incorporate electromagnetic compatibility testing for integrated electronic housings. Shenzhen and Suzhou electronics manufacturing clusters host plating capacity expansion serving consumer appliance control panel demand.
Japan
Tier-one automotive suppliers favor multi-shot molding for EV power distribution components subject to thermal cycling stress. METI carbon neutrality roadmaps are pressuring substrate compounders to reformulate PBT blends with reduced embodied carbon. Nagoya and Osaka industrial corridors concentrate precision molding capacity for hybrid vehicle electronic modules.
South Korea
Samsung and LG smartphone supply chains are migrating toward UV-LDS for 5G mmWave antenna modules displacing conventional flex circuits. MFDS medical device quality system requirements are tightening material traceability for diagnostic equipment housings. Seoul Capital Area electronics manufacturing services are consolidating approved substrate vendor lists for antenna module procurement.
United States
Automotive tier-one harness makers are specifying MID content for wiring assemblies serving Detroit Three electrification programs. FDA biocompatibility requirements for implantable devices are constraining polymer selection for medical-grade substrate specialists. Michigan and Ohio automotive supplier corridors are adding plating capacity to support domestic EV component qualification.
Molded Interconnect Devices (MID) Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the MID value chain. The vendor base separates into precision equipment specialists, broad-line connector manufacturers, and substrate-focused compounders with captive plating operations. Two strategic archetypes dominate: laser system vendors controlling photonic patterning workflows, and diversified electronics fabricators leveraging geographic manufacturing coverage. Competitive moves concentrate on equipment vendor consolidation and substrate-plating chemistry vertical integration.
Among German capital equipment specialists, LPKF Laser & Electronics and HARTING Technology Group exemplify the precision-focused archetype with concentrated exposure to automotive qualification cycles. Molex occupies a position within the diversified connector fabricator tier, sustaining broad geographic manufacturing coverage across North American and Asian plants. TactoTek represents the structural electronics specialist segment, anchoring growth in injection-molded circuit integration for consumer appliance applications. These three company profiles illustrate how competitive positioning splits between technology depth and manufacturing scale.
| Leading Market Players |
|---|
| LPKF Laser & Electronics |
| JOHNAN |
| Molex |
| MID Solutions |
| APC |
| TE Connectivity |
| TactoTek |
| Galtronics |
| HARTING Technology Group |
| Others |
Supply Flow & Price Mechanics
UV-LDS equipment displacing fiber laser systems for 5G mmWave antenna production is redrawing procurement geography toward South Korean capital equipment vendors while compressing price premiums previously commanded by German precision specialists. This substitution dynamic simultaneously elevates buyer negotiating leverage against legacy suppliers and fragments plating chemistry purchasing across newly qualified substrate compounders in Shenzhen and Suzhou.
Pricing Analysis
Price spreads between German-engineered LDS substrates and Chinese-manufactured PBT blends now exceed thirty percent for comparable antenna module specifications. Three-tier pricing structure across automotive-grade, medical-grade, and consumer-grade certification levels governs transactional arrangements, with FDA master file status commanding substantial premiums. Cost compression in consumer electronics tiers is intensifying because South Korean smartphone OEMs are consolidating approved vendor lists to three substrate suppliers. Medical device manufacturers exhibit lowest price sensitivity due to biocompatibility qualification timelines, while appliance control panel buyers drive hardest bargain terms.
Supply Chain Analysis
Strategic stockpiling of palladium activators and electroless plating chemistry concentrates among Japanese and German job-shop platers serving automotive harness makers, while consumer electronics assemblers favor just-in-time substrate delivery from Shenzhen-based distributors. Supply geography centers on Germany, Japan, and China for precision laser systems, with plating capacity expanding fastest in South Korea and coastal Chinese provinces. Raw material dependencies span LCP and PBT polymer resins, copper and nickel plating salts, and palladium catalysts. Single-source vulnerability in sub-150-micron laser structuring equipment creates procurement bottlenecks when Stuttgart or Nagoya facilities face capacity constraints. Distribution runs through tier-one automotive harness makers and consolidated electronics manufacturing services rather than open merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including plating chemistry replenishment contracts and laser parameter tuning subscriptions are expanding faster than hardware sales for capital equipment vendors, transforming customer lifetime value calculations across the MID value chain.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance software into LDS equipment platforms before South Korean competitors replicate fiber-to-UV upgrade pathways. Prioritize backward integration into captive plating chemistry production to offset palladium price volatility squeezing job-shop margins. Defend against emerging substrate compounders in Shenzhen by accelerating dual FDA-EU MDR registration timelines that new entrants cannot match. For New Entrants and Emerging Players: Anchor in Chinese EV battery pack busbar applications where cell-to-pack architecture adoption outpaces established supplier qualification cycles. Target appliance control panel film insert molding segments where design cycle compression favors agile prototyping capabilities over incumbent scale advantages. Pursue equipment-leasing models with embedded consumables contracts to bypass capital expenditure barriers facing domestic Chinese manufacturers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision laser equipment specialists seeking exit liquidity amid technology bifurcation between fiber and UV platforms. Five-to-ten year viability hinges on successful navigation from automotive radar module saturation toward medical implantable device qualification pipelines. Signal to monitor involves ECHA candidate list expansion pace affecting flame-retardant substrate reformulation costs and compounder consolidation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Equipment Technology Bifurcation | UV-LDS adoption by Samsung and LG displaces fiber systems for 5G mmWave antenna modules. |
| Plating Chemistry Backward Integration | German equipment vendors acquire electroless plating suppliers to secure palladium activator supply chains. |
| Dual Regulatory Registration Investment | Substrate compounders pursue simultaneous FDA master file and EU MDR technical documentation approval. |
| Chinese EV Component Localization | Domestic plating capacity expansion serves BYD and CATL battery pack busbar qualification programs. |
| Film Insert Molding Convergence | Printed electronics integration with thermoformed substrates enables curved appliance control panels. |
Methodological Framework
A spread of perspectives from laser equipment engineers, plating chemistry formulators, tier-one automotive harness procurement managers, and medical device regulatory affairs specialists converged on the working assumptions governing substrate qualification timelines and technology adoption curves. Primary fieldwork combined structured interviews across German automotive supplier corridors, South Korean electronics manufacturing clusters, and Chinese EV battery pack production zones with secondary validation against ECHA regulatory filings, FDA device master file databases, MIIT new energy vehicle certification records, and customs trade data for LCP and PBT polymer imports. Bottom-up demand modeling from individual application segments triangulated against top-down equipment vendor shipment data.
Segmentation dimensions modeled span product type, end user industry, manufacturing technology, and application function across the projection horizon. Analytical framework incorporated laser direct structuring equipment deployment rates, multi-shot molding capacity utilization, and plating chemistry consumption intensity to derive expansion trajectories. Industry-specific forecast inputs included ADAS sensor enclosure specification activity from BMW and Mercedes-Benz supply chains and UV-LDS qualification progress at Seoul-based smartphone manufacturing services.
Decision-makers should treat outputs as directional under assumptions of sustained automotive electrification investment and stable ECHA regulatory enforcement timelines; material deviation in palladium commodity pricing or REACH substance list expansion velocity would warrant model refresh. Revision becomes warranted when Chinese domestic EV component qualification rates cross thresholds indicating accelerated substitution of imported substrate supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market