
 Motor Driver IC Market | 2026-2036
Motor Driver IC Market Size, Share, and Industry Trends Forecast 2026-2036
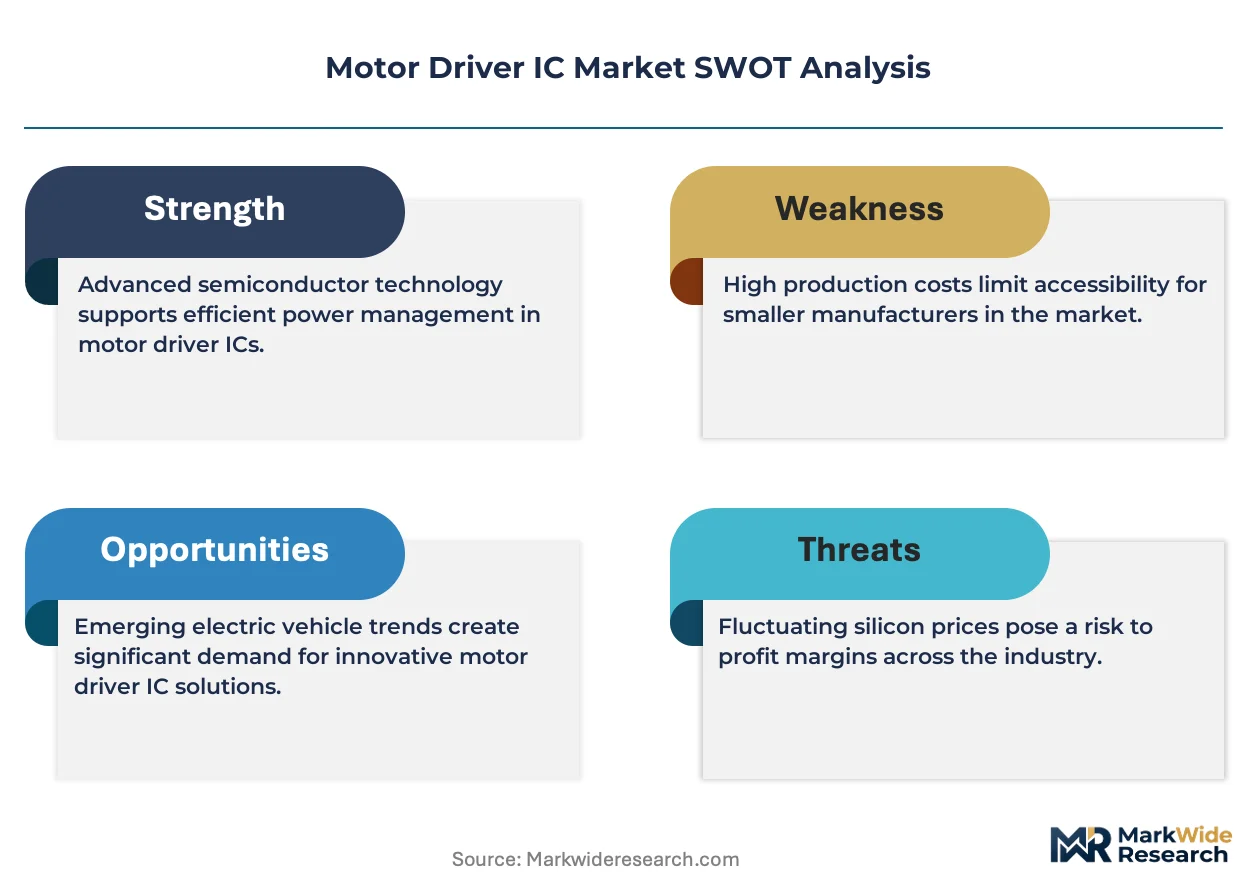
Motor Driver IC Market Analysis
Automotive OEMs is collapsing the historical dominance of consumer electronics as the primary volume buyer for motor driver ICs. Infineon Technologies anchors its position through captive SiC and IGBT co-packaging capabilities for EV traction inverters. Texas Instruments competes with a broad catalog spanning brushed DC to precision stepper drivers, sustaining design-win momentum across industrial and medical accounts. NXP Semiconductors dominates automotive-qualified gate drivers with ASIL-D functional safety integration, occupying a defensible tier in electrified powertrain architectures.
A motor driver IC is a power semiconductor device that converts low-voltage control signals into higher-current outputs to govern motor speed, torque, and direction, typically integrating MOSFET or IGBT power stages with protection logic and thermal management in packages ranging from QFN to thermally enhanced TSSOP. Its primary purpose is to enable precise, efficient electromechanical actuation across battery-operated and mains-connected systems. H-Bridge configurations lead unit shipments due to ubiquity in bidirectional DC motor control, while stepper motor driver ICs command premium pricing in precision positioning for robotics and medical devices. Smart driver technology is displacing analog-only architectures as embedded diagnostics and SPI-configurable fault thresholds become baseline requirements for automotive and industrial safety standards.
FCC emissions rules in the United States, EU RoHS and REACH substance restrictions, and China's GB standards for motor energy efficiency collectively shape product qualification roadmaps and material selection for motor driver IC suppliers. EMA and NHTSA safety frameworks for electrified vehicles in Europe and North America are accelerating demand for ISO 26262-compliant motor control solutions with predictive fault detection. Stakeholders must monitor how regional carbon mandates and efficiency tier upgrades redefine the boundary between commodity motor drivers and premium smart-driver platforms.
Market Dynamics
Automotive electrification is compressing design cycles for motor driver ICs as EV traction inverters demand ASIL-D functional safety and embedded diagnostics that legacy analog architectures cannot deliver. Tier-1 suppliers now prioritize gate drivers with predictive fault detection over commodity H-Bridge solutions.
Growth Catalysts
- China's dual carbon goals:GB standards for motor energy efficiency are forcing industrial equipment retrofits, expanding demand for high-efficiency variable frequency drives and smart motor control platforms.
- EV traction inverter proliferation:Battery electric vehicle powertrains require dedicated gate driver ICs with isolation and desaturation protection, pulling volume from consumer electronics applications.
- SiC MOSFET co-packaging:Wide-bandgap semiconductor integration is enabling higher switching frequencies and thermal performance in compact modules for aerospace and defense actuation systems.
Market Restraints
- 300mm silicon wafer supply concentration:Taiwan and South Korea dominate substrate production, exposing motor driver IC fabs to geopolitical disruption and allocation constraints.
- Copper and rare earth magnet cost volatility:Permanent magnet synchronous motor dependencies create input cost instability for integrated driver-motor modules.
- ISO 26262 certification timelines:Functional safety documentation and fault analysis requirements extend automotive qualification cycles by 18-24 months versus industrial grades.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for electric vehicle component manufacturing are attracting motor driver IC packaging investments in Gujarat and Tamil Nadu.
- Medical robotics precision actuation:Surgical robot OEMs require sub-micron stepper positioning with SPI-configurable current control, commanding 3-4x pricing premiums over industrial equivalents.
- EU F-Gas Regulation phase-down:Compressor motor efficiency mandates in HVAC-R equipment are accelerating replacement of relay-based controls with variable speed driver ICs.
Industry Challenges
- Power electronics talent scarcity:Mixed-signal IC designers with magnetics and thermal co-design expertise remain concentrated at established semiconductor firms, constraining startup scaling.
- Legacy industrial motor park interoperability:Retrofitting 20-30 year old brushed DC and induction motor installations with smart drivers requires custom firmware adaptation and field calibration protocols.
- IP fragmentation in integrated gate driver topologies:Patent thickets around desaturation detection and active miller clamping circuits complicate clean-sheet design for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Driver IC Market |
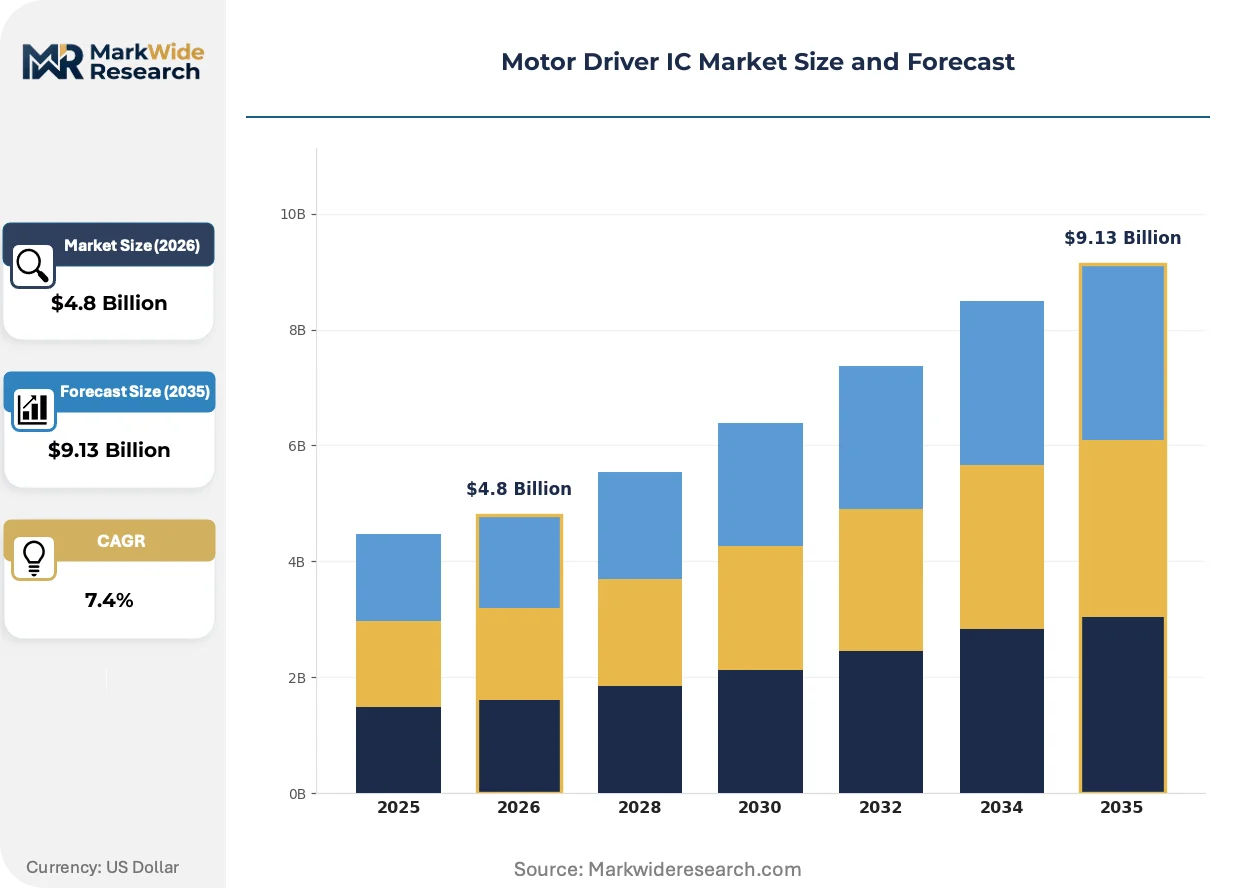
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.13 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: H-Bridge, PWM Controller, Dual Motor Driver, Stepper Motor Driver Technology: Analog, Digital, Mixed-Signal, Smart Driver End User: Consumer Electronics, Automotive, Industrial Automation, Robotics Application: Home Appliances, Electric Vehicles, Telecom Equipment, Medical Devices |
| Companies Covered | NXP Semiconductors, Analog Devices, Infineon Technologies, Microchip Technology, Renesas Electronics, STMicroelectronics, ON Semiconductor, Toshiba Corporation, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Driver IC Market Emerging Trajectories
Smart driver architectures with embedded microcontrollers and real-time diagnostics are displacing analog-only motor control solutions across safety-critical applications. This convergence of power electronics and digital signal processing is redefining supplier qualification requirements.
GaN-based half-bridge driver ICs are displacing silicon MOSFET solutions in sub-500W applications. Drone propulsion and cordless power tool OEMs in Shenzhen and Dongguan have adopted GaN drivers for 30% reduction in switching losses. The technology is compressing thermal management system costs and enabling higher power density in battery-operated equipment.
REACH substance restrictions and RoHS recast directives in Europe are eliminating lead-frame plating chemistries and certain mold compound flame retardants from motor driver IC bill-of-materials. Component suppliers must requalify packages with alternative surface finishes and halogen-free substrates. Automotive-qualified products face the steepest compliance timelines due to extended reliability testing requirements.
Volume consolidation among Chinese EV manufacturers is compressing supplier negotiation cycles and favoring motor driver IC vendors with localized application engineering. BYD and CATL battery ecosystem suppliers now demand 48-hour technical response times and co-located firmware tuning support. This behavioral shift privileges semiconductor firms with established design centers in Shanghai and Shenzhen over distant competitors.
Motor Driver IC Market Segmentation
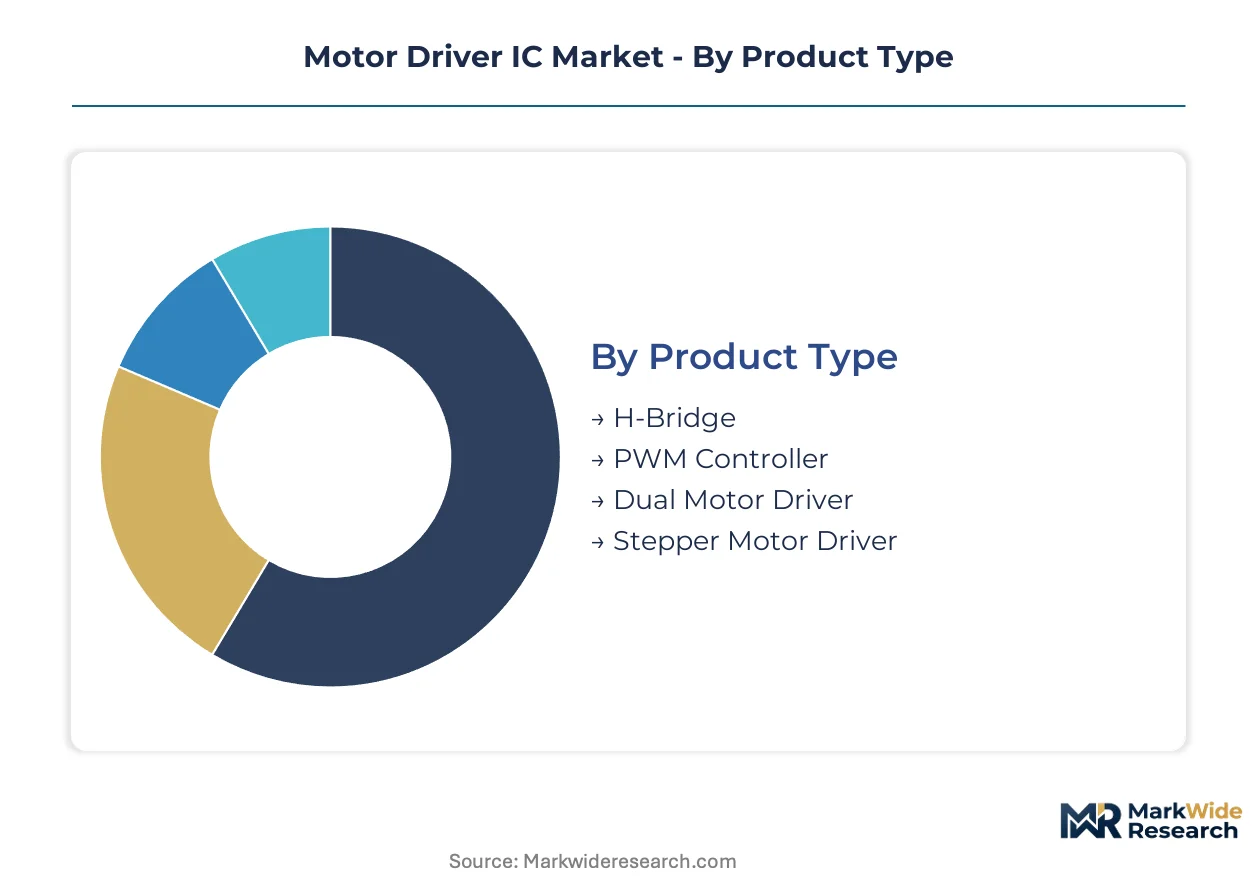
Motor driver IC segmentation reveals how technology substitution pressures and application-specific certification requirements reshape procurement patterns across power electronics. Distinct performance tiers, safety qualification levels, and integration densities create non-overlapping supply relationships between commodity and premium segments.
Product Type:
H-Bridge architectures face mounting displacement risk from integrated smart drivers in battery-operated equipment, while stepper motor drivers defend their position through precision requirements that integrated alternatives cannot match.
- H-Bridge:Bidirectional DC motor control topology integrating four switching elements in bridge configuration with shoot-through protection and thermal shutdown. Demand concentrates in cordless power tools from Dongguan manufacturing clusters, where cost sensitivity favors discrete implementations over integrated alternatives. China's GB motor efficiency standards are accelerating replacement of relay-based H-Bridge designs with MOSFET-based solutions in industrial retrofit programs.
- Stepper Motor Driver:Precision positioning IC with microstepping capability and integrated current regulation for open-loop or closed-loop control. Surgical robot OEMs in Germany and Japan specify these devices for sub-micron positioning accuracy, commanding substantial pricing premiums over industrial equivalents due to ASIL-D and ISO 13485 qualification requirements.
- PWM Controller:Variable speed motor control through pulse-width modulation with external power stage integration.
- Dual Motor Driver:Integrated dual-channel architecture for synchronous control of two independent motors in space-constrained designs.
H-Bridge solutions anchor the volume base while stepper motor drivers gain share at the steepest rate.
Technology:
Analog-only architectures carry the heaviest substitution burden as embedded diagnostics and SPI configurability become baseline requirements across automotive and medical safety standards.
- Smart Driver:Power stage integration with embedded microcontroller, real-time fault diagnostics, and predictive maintenance algorithms. Automotive traction inverter programs from Stuttgart to Shanghai now mandate these capabilities for ASIL-D compliance, displacing analog gate drivers in electrified powertrain architectures.
- Mixed-Signal:Hybrid architecture combining analog power stages with digital control interfaces and programmable protection thresholds. Industrial automation OEMs in South Korea and Japan favor this technology for variable frequency drives requiring field-adjustable parameters without full microcontroller integration.
- Analog:Discrete component-based motor control with fixed protection thresholds and external timing networks.
- Digital:Software-defined control with DSP-based commutation and sensorless operation algorithms.
Analog platforms retain cost-sensitive volume while smart driver architectures expand most quickly into safety-critical applications.
End User:
Automotive electrification is compressing procurement cycles and reshaping volume allocation away from consumer electronics toward traction and auxiliary motor control systems.
- Automotive:Electrified powertrain applications including traction inverters, electric power steering, and thermal management pumps. BYD and CATL ecosystem suppliers in Shenzhen demand 48-hour technical response times and co-located firmware tuning support, privileging semiconductor firms with established China design centers.
- Industrial Automation:Variable frequency drives, servo systems, and conveyor motor controls for manufacturing equipment. China's dual carbon goals and GB efficiency standards are forcing retrofit demand across 20-30 year old motor installations, requiring custom firmware adaptation for legacy interoperability.
- Consumer Electronics:Battery-operated devices including smartphones, laptops, and personal care appliances.
- Robotics:Precision actuation for collaborative robots, surgical systems, and autonomous mobile platforms.
Consumer electronics provides the installed base volume while automotive applications climb the fastest on electrification investment cycles.
Application:
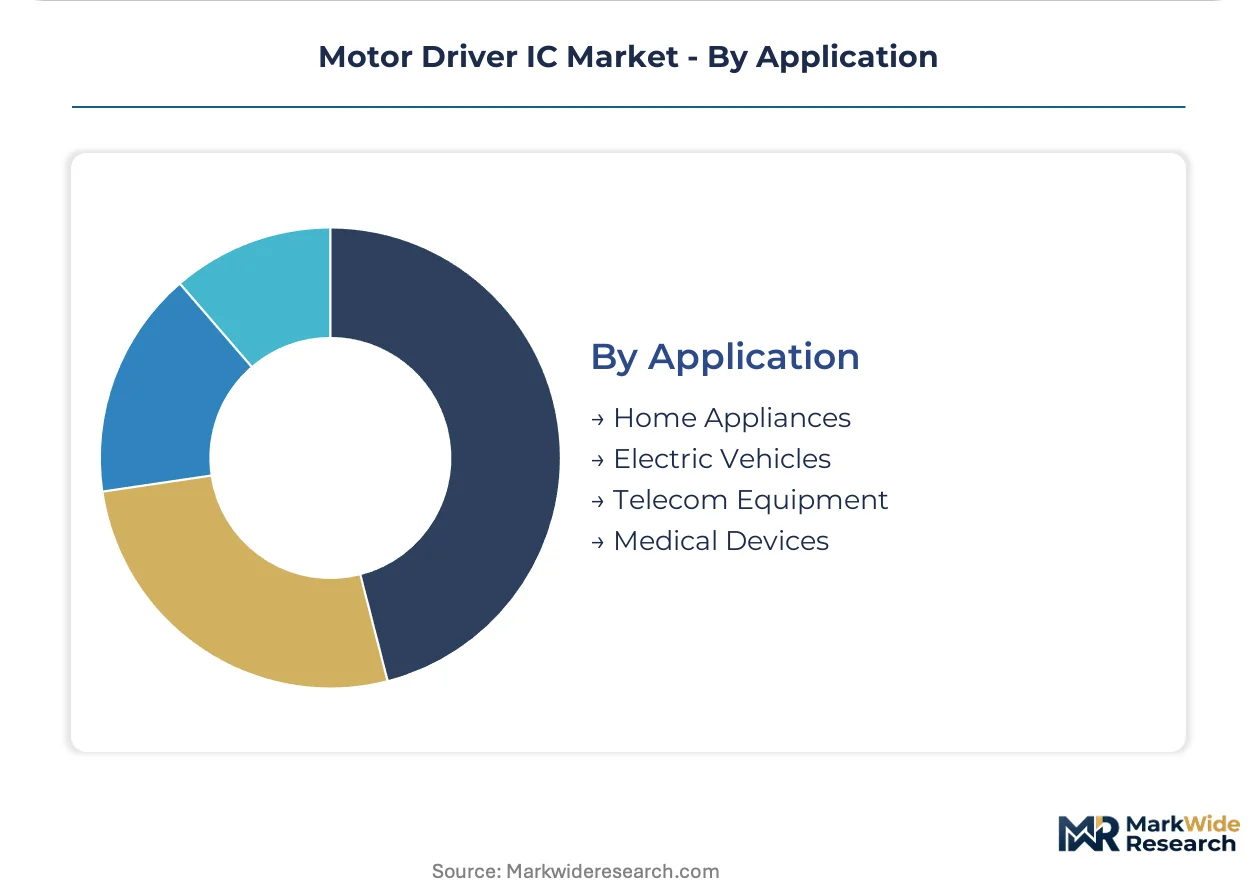
Electric vehicle powertrains concentrate the most demanding specification requirements, pulling technology development investment away from home appliance commoditization.
- Electric Vehicles:Traction inverter gate drivers with isolation, desaturation protection, and active miller clamping for battery electric powertrains. EMA and NHTSA safety frameworks across Europe and North America mandate ISO 26262-compliant solutions with predictive fault detection, extending qualification timelines substantially versus industrial grades.
- Medical Devices:Surgical robots, infusion pumps, and diagnostic equipment requiring sub-micron positioning and fail-safe operation. EU MDR and FDA device regulations impose documentation burdens that favor established suppliers with dedicated medical product lines over industrial crossover vendors.
- Home Appliances:Compressor and fan motor control for HVAC-R and white goods equipment.
- Telecom Equipment:Cooling fans and antenna positioning actuators for base station infrastructure.
Home appliances sustain shipment volumes while electric vehicle applications show the steepest expansion trajectory on powertrain electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese foundries export silicon substrates to fabrication facilities across Germany, Japan, and the United States, creating a trade-flow dependency that shapes regional motor driver IC availability and pricing power.
China
BYD and CATL ecosystem suppliers in Shenzhen drive procurement of ASIL-D qualified gate drivers for EV traction inverters. GB standards for motor energy efficiency under the dual carbon goals mandate industrial retrofit programs. Dongguan manufacturing clusters specialize in H-Bridge solutions for cordless power tools, where cost sensitivity favors discrete implementations over integrated alternatives.
Germany
Surgical robot OEMs in Stuttgart and Munich specify stepper motor drivers with sub-micron positioning accuracy for medical applications. EU F-Gas Regulation phase-down mandates compressor motor efficiency upgrades in HVAC-R equipment. Bavaria's industrial automation corridor concentrates variable frequency drive demand from automotive component suppliers.
United States
NHTSA safety frameworks for electrified vehicles accelerate ISO 26262-compliant motor control procurement from Detroit-area automotive OEMs. FCC emissions rules constrain electromagnetic compatibility design for industrial motor drivers. Texas instrumentation clusters sustain demand for precision stepper drivers across medical and aerospace accounts.
Japan
METI efficiency standards for industrial equipment force replacement of legacy relay-based motor controls with MOSFET-based solutions. Renesas Electronics anchors domestic supply of automotive-qualified gate drivers. Nagoya's automotive manufacturing belt concentrates demand for electrified powertrain motor control systems from Toyota and Honda suppliers.
South Korea
Samsung SDI and LG Energy Solution battery ecosystems pull high-efficiency motor driver ICs for EV auxiliary systems. MFDS medical device regulations impose documentation burdens that favor established suppliers with dedicated healthcare product lines. Seoul Capital Area semiconductor design houses specialize in mixed-signal architectures for industrial automation OEMs.
Motor Driver IC Market Vendor Landscape
Player mix skews toward diversified semiconductor conglomerates with captive power device fabrication. The vendor base concentrates around three tiers: integrated device manufacturers with SiC and IGBT co-packaging capabilities, fabless specialists licensing gate driver IP, and industrial-grade commodity suppliers competing on unit cost. Strategic moves center on automotive qualification acceleration and China design center expansion to meet 48-hour technical response demands from EV ecosystem suppliers.
Within the integrated device manufacturer tier, Infineon Technologies and STMicroelectronics exemplify European-based conglomerates with vertical control over wide-bandgap semiconductor production. Texas Instruments occupies a position bridging industrial precision applications and automotive safety-critical systems. These three anchors represent distinct competitive vectors: captive substrate supply, medical-grade certification depth, and catalog breadth spanning brushed DC to precision stepper architectures.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Analog Devices |
| Infineon Technologies |
| Microchip Technology |
| Renesas Electronics |
| STMicroelectronics |
| ON Semiconductor |
| Toshiba Corporation |
| Texas Instruments |
| Others |
Supply Flow & Price Mechanics
300mm wafer fab utilization rates above 90 percent in Taiwan and South Korea compress marginal cost curves for MOSFET gate drivers while simultaneously concentrating pricing power among substrate suppliers. This scale asymmetry creates divergent price floors between automotive-qualified smart drivers and commodity H-Bridge solutions.
Pricing Analysis
Silicon-based smart drivers command 40-60 percent premiums over legacy analog architectures, while GaN-based half-bridge solutions occupy an emerging premium tier above both. Pricing stratifies across automotive ASIL-D certification, industrial mixed-signal grades, and consumer analog tiers. Cost compression in cordless power tool H-Bridge segments intensifies as Dongguan manufacturers consolidate procurement volumes. Consumer electronics OEMs exhibit highest price sensitivity, while surgical robot OEMs in Germany and Japan accept substantial premiums for sub-micron stepper positioning accuracy.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for motor driver IC substrates, with back-end packaging concentrated in Malaysia and Vietnam. Silicon carbide wafers draw from US and Japanese substrate suppliers, while copper lead frames and epoxy mold compounds feed from Chinese chemical processors. Single-source vulnerability in 300mm silicon wafer supply exposes motor driver IC fabs to geopolitical disruption and allocation constraints. Distribution runs through authorized distributors serving Tier 1 automotive suppliers and direct OEM relationships for high-volume consumer accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification fragments procurement patterns across ASIL-D traction inverters, auxiliary pump controls, and legacy industrial retrofits, creating specialization niches that reward focused capabilities over broad catalog breadth.
For Market Incumbents: Fortify captive SiC and IGBT co-packaging capabilities to defend automotive traction inverter share against fabless gate driver specialists. Accelerate ISO 26262 certification pipelines to compress 18-24 month qualification timelines. Expand Shenzhen and Shanghai design centers to meet 48-hour technical response demands from BYD and CATL ecosystem suppliers. For New Entrants and Emerging Players: Anchor in India's PLI scheme for automotive component manufacturing, where Gujarat and Tamil Nadu packaging investments attract EV auxiliary system suppliers. Target medical robotics precision actuation segments commanding 3-4x industrial pricing premiums. Pursue licensing arrangements for desaturation detection and active miller clamping IP to circumvent patent thickets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart driver suppliers with firmware-locked automotive platforms and long-term service agreements. Five-to-ten year viability favors vendors with backward integration into wide-bandgap semiconductor production. Monitor China's GB standards enforcement velocity as inflection indicator for industrial retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Acceleration | Compresses ISO 26262 timelines to capture EV traction inverter design wins from Stuttgart to Shanghai. |
| Wide-Bandgap Semiconductor Integration | Enables SiC MOSFET co-packaging for higher switching frequencies in aerospace and defense actuation systems. |
| China Design Center Expansion | Delivers 48-hour technical response capability required by BYD and CATL battery ecosystem suppliers. |
| Medical Robotics Precision Development | Captures 3-4x pricing premiums through sub-micron stepper positioning for surgical robot OEMs. |
| Industrial Retrofit Firmware Adaptation | Unlocks China's GB standards-mandated equipment replacement across 20-30 year old motor installations. |
Methodological Framework
A spread of perspectives from power semiconductor design engineers, Tier 1 automotive procurement managers, industrial automation OEM technical directors, and medical device regulatory affairs leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs and trade flow databases, IHS Markit vehicle production data, and EMA safety framework documentation. Bottom-up unit shipment estimates triangulated against top-down semiconductor industry revenue allocations.
Segmentation dimensions modeled include motor driver IC product type, technology architecture, end-use industry, and application category across the analysis window. CAGRs derived from regression analysis of historical shipment trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated China's dual carbon policy enforcement schedules, EV powertrain penetration curves, and REACH substance restriction compliance timelines.
Material uncertainties — geopolitical disruption to 300mm wafer supply, copper and rare earth magnet cost volatility, ISO 26262 certification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement velocity and technology substitution rates. Recalibration cycles align with material shifts in GB standards adoption, wide-bandgap semiconductor yield improvements, and automotive platform consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Japan Analog IC Market