
 Programmable ASIC Market | 2026-2036
Programmable ASIC Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable ASIC Market Analytics
Taiwan is rewriting the geographic logic of programmable ASIC supply by expanding advanced packaging capacity at multiple foundry complexes. Intel Corporation leverages its IDM strategy to sustain captive wafer supply for structured ASIC lines. Broadcom Inc. anchors North American demand through custom silicon programs for hyperscale data center clients.
A programmable ASIC is an application-specific integrated circuit whose logic functions can be configured or reconfigured after manufacturing, typically through field-programmable gate arrays, antifuse-based one-time programming, or embedded FPGA fabric integrated within SoC architectures, enabling post-fabrication customization for specific computational workloads. FPGA-based programmable ASICs occupy the largest revenue pool due to their reprogrammability advantage in prototyping and low-to-medium volume production, while structured ASIC variants capture margin concentration from clients seeking lower unit costs after design freeze. AI acceleration applications within the application dimension are expanding fastest as neural network inference demands reshape silicon architecture priorities across cloud and edge deployments.
China's MIIT sets domestic semiconductor self-sufficiency targets that redirect local programmable ASIC procurement toward indigenous suppliers, while the EU Chips Act and CE marking requirements under the EU AI Act shape European product standards and market access conditions for AI-integrated programmable silicon. Stakeholders must monitor how export control classifications from multiple jurisdictions reshape foundry access and design tool licensing before committing to multi-year tape-out schedules.
Market Dynamics
AI inference workloads are compressing design cycles and forcing programmable ASIC architectures toward heterogeneous compute fabrics that merge embedded FPGA with dedicated tensor cores. This structural pressure is redrawing foundry partnerships and tool chain investments across the value chain.
Growth Catalysts
- EU Chips Act capital allocation:European subsidies for domestic semiconductor fabrication are expanding foundry capacity for structured ASIC production, reducing reliance on external wafer supply.
- Hyperscale data center buildouts:Cloud operators in the United States are commissioning custom silicon programs that prioritize programmable logic for workload flexibility.
- China's eastern coastal manufacturing corridor:Foundry partnerships between domestic fabs and fabless designers are multiplying procurement volumes for indigenous programmable ASIC supply.
Market Restraints
- Advanced packaging substrate shortage:CoWoS and similar 2.5D/3D packaging technologies face capacity constraints at Taiwan-based facilities, throttling output of high-performance programmable ASICs.
- EUV lithography equipment access restrictions:Export control classifications from multiple jurisdictions are limiting foundry access to sub-7nm process nodes for certain design houses.
- Structured ASIC NRE cost barriers:Non-recurring engineering expenses for mask sets and physical design remain prohibitive for sub-million-unit production volumes.
Strategic Opportunities
- Edge AI deployment in industrial automation:Factory automation systems in Germany and Japan are adopting embedded FPGA fabric for real-time inference with deterministic latency requirements.
- CE marking under EU AI Act:Conformity assessment requirements for AI-integrated silicon are creating preference for programmable architectures that enable post-certification algorithm updates.
- Chiplet-based modular design:Interconnect standards enabling die-to-die integration are allowing programmable logic tiles to be combined with custom accelerators in heterogeneous packages.
Industry Challenges
- Physical design engineering scarcity:Talent pools capable of advanced node place-and-route for complex programmable fabrics remain concentrated at a handful of design services firms.
- Multi-jurisdiction export compliance:Navigating simultaneous BIS, DGFT, and customs classification requirements is extending tape-out timelines by quarters for cross-border design teams.
- Legacy FPGA migration friction:Porting existing bitstreams to new programmable ASIC architectures requires substantial verification effort that delays product transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable ASIC Market |
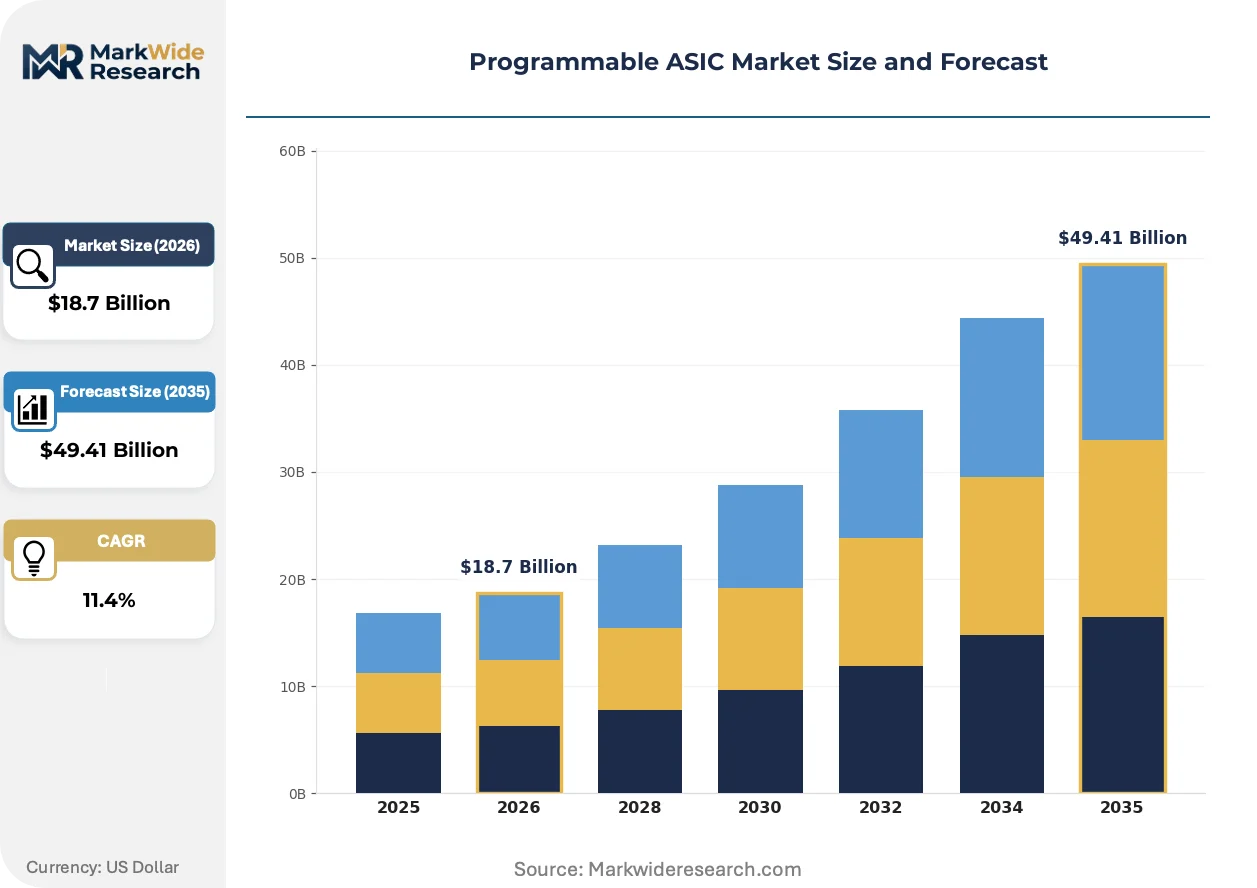
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPGA, SoC, Structured ASIC, Custom ASIC Technology: Low Power, High Performance, Mixed Signal, RF End User: Telecommunications, Automotive, Consumer Electronics, Data Centers Application: Network Processing, Image Processing, Cryptography, AI Acceleration |
| Companies Covered | Intel Corporation, Texas Instruments, Broadcom Inc., STMicroelectronics, Infineon Technologies, Analog Devices, NXP Semiconductors, Renesas Electronics Corporation, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable ASIC Market Evolving Landscape
Heterogeneous integration is collapsing the traditional boundary between fixed-function and reconfigurable logic, enabling silicon architectures that adapt to workload evolution without full retape-out. This convergence is accelerating across cloud, edge, and embedded deployments.
Embedded FPGA fabric integrated within SoC architectures is rendering obsolete the discrete FPGA modules that previously dominated prototyping and low-volume production. Hyperscale data center operators are now mandating embedded reconfigurability in custom silicon programs to enable in-field algorithm updates without board redesign. The structural consequence is compressing margins for standalone FPGA vendors while expanding addressable market for programmable ASIC designers.
China's MIIT semiconductor self-sufficiency targets are redirecting domestic procurement toward indigenous programmable ASIC suppliers, with GB standards compliance becoming a gate for foundry access. This policy friction is fragmenting previously global design tool licensing arrangements. European and Japanese equipment vendors are responding by establishing localized support infrastructure for China-qualified process technologies.
Hyperscale buyers are consolidating vendor relationships around full-stack programmable silicon programs that bundle design services, wafer supply, and firmware support under multi-year contracts. Traditional distribution through broadline semiconductor channels is losing share to direct foundry-design house engagement in the United States and Taiwan. This concentration is most visible in AI training and inference clusters where single customers represent substantial annual wafer demand.
Programmable ASIC Market Segmentation
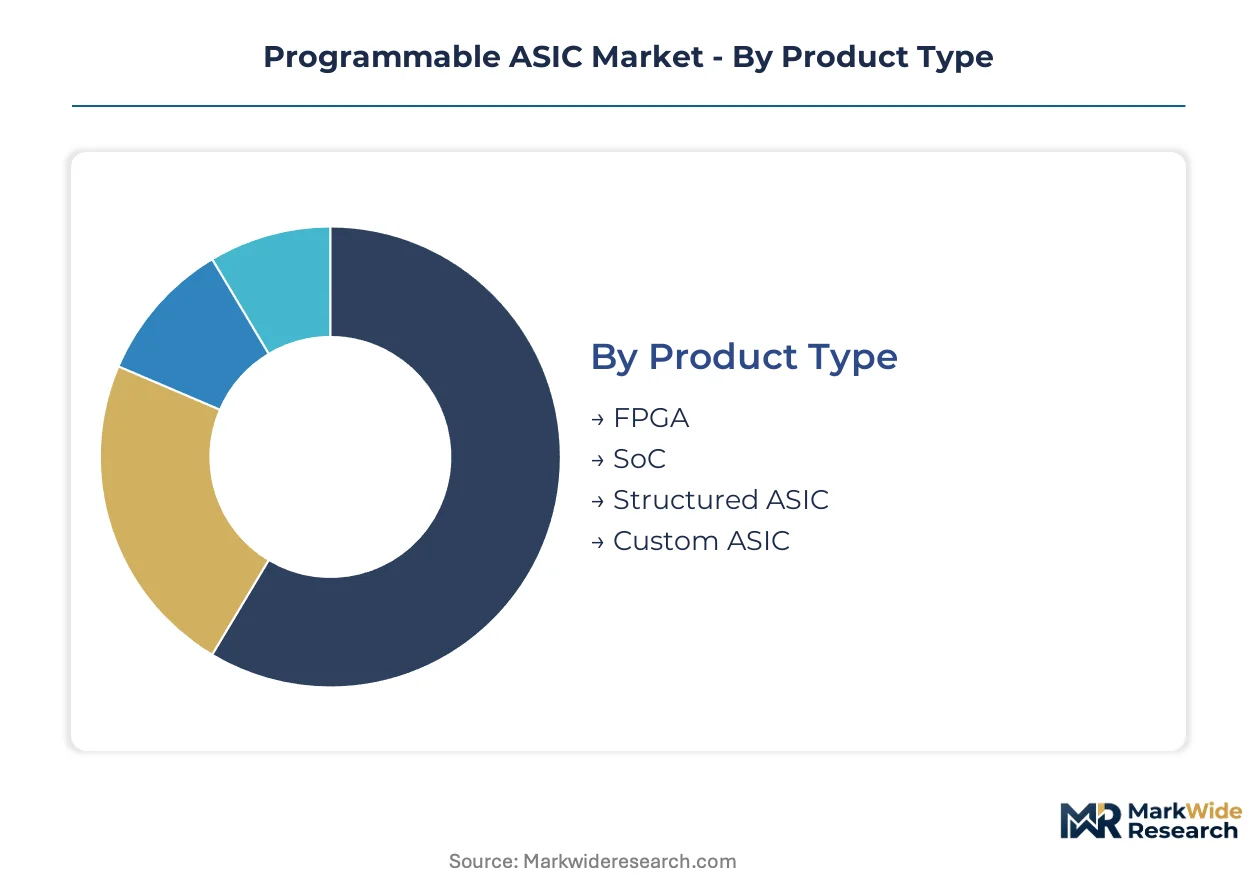
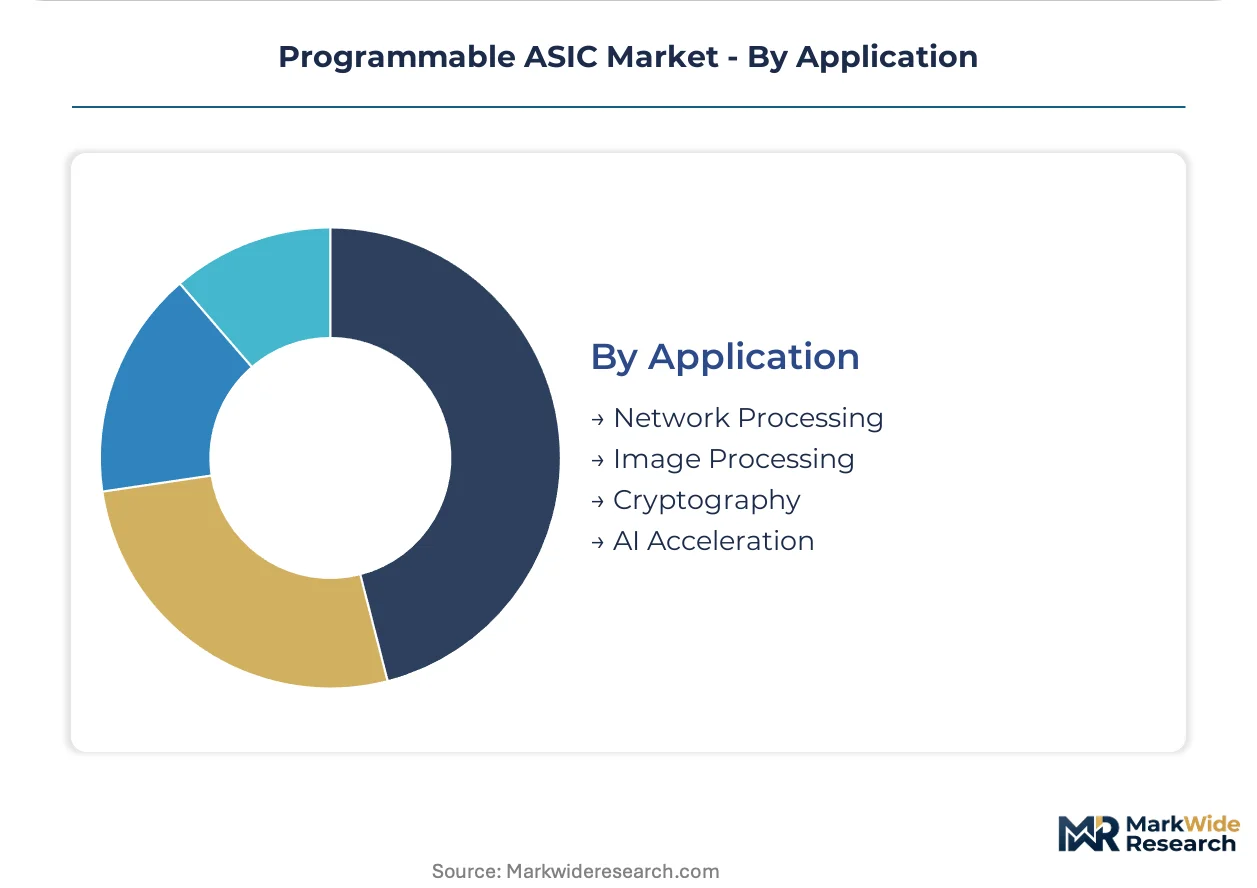
Programmable ASIC segmentation reveals how architectural trade-offs between flexibility and efficiency map onto distinct procurement patterns. Each dimension—product type, technology, end user, and application—carries different after-sales service intensity, from continuous bitstream updates in FPGA deployments to one-time mask-set validation for structured ASICs.
Product Type:
After-sales service intensity varies sharply across product types, with reprogrammable architectures demanding ongoing technical support while fixed-configuration variants require minimal post-deployment engagement.
- FPGA:Field-programmable gate arrays enable unlimited post-manufacturing reconfiguration through SRAM-based or flash-based programming cells. Data center operators in the United States commission FPGA-based acceleration cards for AI inference workloads where algorithm iteration demands hardware adaptability without board replacement.
- SoC:System-on-chip architectures integrate embedded FPGA fabric alongside CPU, GPU, and dedicated accelerators on monolithic silicon. China's eastern coastal manufacturing corridor shows concentrated procurement for SoC-based programmable solutions combining reconfigurable logic with indigenous RISC-V cores.
- Structured ASIC:Pre-diffused base layers with customizable metal routing reduce unit costs versus FPGAs for frozen designs. European automotive suppliers leverage structured ASICs for sensor fusion modules after design validation.
- Custom ASIC:Full-mask customization delivers maximum performance-per-watt for million-unit-plus production commitments. Hyperscale cloud operators in North America drive custom ASIC programs for workload-specific acceleration.
FPGA holds the largest share; momentum sits with SoC.
Technology:
Cost tier stratification separates premium high-performance nodes from mainstream low-power offerings, with pricing scaling nonlinearly against process complexity and packaging sophistication.
- Low Power:Sub-1V operating voltages and aggressive clock gating extend battery life in portable and edge-deployed systems. Japan's factory automation sector sources low-power programmable ASICs for wireless sensor networks requiring multi-year battery operation.
- High Performance:Advanced FinFET nodes and 2.5D/3D packaging enable terabit-scale interconnect bandwidth. Taiwan-based foundries dominate high-performance programmable ASIC production through CoWoS capacity expansion.
- Mixed Signal:Integration of analog front-ends with digital programmable fabric reduces component count in signal acquisition systems. Germany's industrial equipment manufacturers specify mixed-signal programmable ASICs for precision motor control.
- RF:Millimeter-wave capable programmable transceivers support 5G and satellite communication infrastructure. South Korean telecommunications equipment vendors drive RF programmable ASIC procurement for baseband processing.
High Performance commands premium pricing; Mixed Signal is climbing the fastest.
End User:
Application-specific volume patterns concentrate procurement, with data center and telecommunications buyers representing wafer-scale annual commitments while automotive and consumer segments fragment across numerous smaller programs.
- Telecommunications:Baseband processing, switching fabric, and optical transport demand programmable logic for protocol evolution. India's 5G infrastructure rollout accelerates programmable ASIC procurement for macro and small-cell deployments.
- Automotive:Functional safety requirements and long production lifecycles favor structured ASICs over FPGAs for ADAS and infotainment. EU AI Act CE marking requirements reshape automotive silicon validation procedures.
- Consumer Electronics:Cost-sensitive, high-volume production drives preference for structured ASICs post-design-freeze. China's MIIT domestic procurement policies redirect consumer electronics programmable ASIC supply toward indigenous sources.
- Data Centers:Hyperscale operators commission custom silicon programs with embedded reconfigurability for workload-specific acceleration. United States-based cloud providers represent the largest single-country demand concentration.
Data Centers hold the largest share; Automotive is gaining share fastest.
Application:
Supply concentration for advanced packaging and design services clusters around AI acceleration, with foundry capacity allocation prioritizing neural network inference workloads over legacy networking applications.
- Network Processing:Programmable packet parsing, classification, and forwarding enable software-defined networking infrastructure. Israel's cybersecurity-focused networking vendors drive specialized network processing ASIC development.
- Image Processing:Real-time video encoding, computer vision preprocessing, and display pipeline acceleration leverage programmable parallelism. Japan's broadcast equipment manufacturers specify image processing programmable ASICs for 8K production workflows.
- Cryptography:Post-quantum algorithm agility and hardware security module integration favor reconfigurable implementations. NIST standardization timelines for quantum-resistant algorithms accelerate cryptography-focused programmable ASIC design starts.
- AI Acceleration:Tensor operation offloading, sparse computation, and dynamic precision scaling reshape silicon architecture priorities. China's eastern coastal corridor shows fastest procurement expansion for AI acceleration programmable ASICs.
Network Processing holds the largest installed base; AI Acceleration shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT semiconductor self-sufficiency targets are redirecting Chinese programmable ASIC procurement toward domestic suppliers while EU Chips Act subsidies expand European foundry capacity for structured ASIC production.
United States
Hyperscale data center operators in the United States commission custom silicon programs with embedded FPGA fabric for AI inference workloads. FCC equipment authorization requirements shape import and deployment timelines for programmable logic devices. The Pacific Northwest and Greater Boston clusters concentrate design house activity for cloud-optimized programmable architectures.
China
China's eastern coastal manufacturing corridor multiplies foundry partnerships between domestic fabs and fabless designers for indigenous programmable ASIC supply. MIIT domestic procurement policies and GB standards compliance requirements gate market access for foreign suppliers. The Yangtze River Delta anchors advanced packaging capacity expansion for high-performance programmable silicon.
Germany
German industrial equipment manufacturers specify mixed-signal programmable ASICs for precision motor control and factory automation systems. EU AI Act CE marking requirements reshape validation procedures for AI-integrated automotive silicon. Bavaria and Baden-Württemberg concentrate automotive supplier design centers for structured ASIC development.
Japan
Japan's factory automation sector sources low-power programmable ASICs for wireless sensor networks requiring multi-year battery operation. METI technology roadmaps prioritize domestic semiconductor manufacturing equipment and materials capabilities. The Chubu region around Nagoya hosts precision machinery vendors integrating embedded FPGA fabric for real-time control.
South Korea
South Korean telecommunications equipment vendors drive RF programmable ASIC procurement for 5G baseband processing infrastructure. MFDS regulatory frameworks for medical devices influence mixed-signal programmable silicon design requirements. The Seoul Capital Area anchors system house activity for communications-optimized programmable architectures.
Programmable ASIC Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. IDM-integrated players with captive wafer supply compete against fabless design houses dependent on foundry partnerships. Three archetypes dominate: diversified semiconductor conglomerates with programmable logic divisions, pure-play programmable silicon specialists, and custom silicon service providers for hyperscale clients. Competitive moves center on advanced packaging capacity expansion and multi-year supply contracts with cloud operators.
Among diversified semiconductor conglomerates, Intel Corporation and Broadcom Inc. exemplify scale-driven positions, while STMicroelectronics represents European IDM-integrated capability. Texas Instruments anchors analog-mixed signal programmable silicon expertise. These entities occupy positions across FPGA, structured ASIC, and custom silicon segments without exclusive specialization.
| Leading Market Players |
|---|
| Intel Corporation |
| Texas Instruments |
| Broadcom Inc. |
| STMicroelectronics |
| Infineon Technologies |
| Analog Devices |
| NXP Semiconductors |
| Renesas Electronics Corporation |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor carries silicon wafers and advanced packaging substrates between Taiwan-based foundries and Chinese fabless design houses, with logistics cost volatility amplifying price spreads between high-performance and mainstream programmable ASIC tiers while EU Chips Act subsidies compress European structured ASIC pricing against Asian imports.
Pricing Analysis
Geographic price spreads between Taiwan-produced high-performance programmable ASICs and China-sourced mainstream alternatives have widened as CoWoS packaging capacity constraints concentrate premium supply. Three-tier pricing structure across premium, standard, and economy levels reflects process node differentiation, with 5nm and below commanding substantial premiums over mature-node offerings. Cost compression in the standard tier is intensifying because foundry customers are consolidating orders to secure allocation priority. Hyperscale data center operators show the lowest price sensitivity due to workload-specific performance requirements, while industrial automation buyers in Germany and Japan face acute budget constraints for low-volume deployments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for programmable ASIC vendors navigating BIS export control classifications and DGFT licensing requirements. Wafer fabrication concentrates in Taiwan, South Korea, and China, with advanced packaging capacity anchored in Taiwan and expanding in China's eastern coastal corridor. Raw material dependencies include silicon wafers, EUV photoresists, and organic substrate materials for 2.5D integration. Single-source vulnerability at Taiwan-based CoWoS facilities threatens output of AI acceleration chips. Distribution runs through direct foundry-design house engagement for hyperscale clients, with broadline semiconductor channels serving smaller industrial and automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmable ASIC incumbents face substitution pressure from GPU-based AI acceleration and custom fixed-function silicon, requiring defensive positioning around embedded reconfigurability and multi-year supply contracts that GPU vendors cannot match.
For Market Incumbents: Entrench customer relationships through captive advanced packaging capacity additions in Taiwan and Arizona, securing allocation priority for hyperscale cloud operators. Deepen backward integration into substrate supply to mitigate CoWoS bottleneck exposure. Defend against GPU substitution by mandating embedded FPGA fabric in custom silicon programs, creating switching costs through firmware-level integration that pure-play AI accelerators cannot replicate.
For New Entrants and Emerging Players: Establish a beachhead in edge AI deployment for German factory automation systems, where deterministic latency requirements and modest volume scales deter incumbent resource allocation. Target Japan's wireless sensor network segment with ultra-low-power programmable ASIC designs optimized for multi-year battery operation. Pursue design services partnerships with European automotive suppliers navigating EU AI Act CE marking requirements, offering post-certification algorithm update capabilities as a compliance-enabling value proposition.
For Investors and Strategic Acquirers: Fabless design houses with proven 2.5D integration capabilities and existing hyperscale customer relationships represent the most defensible acquisition archetype in a five-to-ten-year viability window. Foundry access guarantees through multi-year wafer supply agreements function as scarce strategic assets amid capacity constraints. Monitor BIS export control classification expansions as the critical inflection signal, with additional restrictions on sub-7nm process access potentially collapsing valuations for China-exposed design houses overnight.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | CoWoS and 2.5D integration investments at Taiwan and Arizona facilities secure allocation priority for AI acceleration workloads. |
| EU Chips Act Compliance Positioning | Structured ASIC production qualification at European foundries enables access to subsidy-backed domestic procurement programs. |
| Embedded FPGA Fabric Integration | SoC architectures combining reconfigurable logic with fixed-function accelerators defend against GPU substitution in data center inference. |
| China-Qualified Process Technology Localization | GB standards compliance and MIIT certification enable continued access to indigenous fabless design house procurement. |
| Multi-Year Hyperscale Supply Contracts | Direct foundry-design house engagements with United States cloud operators lock in wafer-scale demand commitments. |
Research Methodology
A standing panel of foundry operations executives, fabless design house technical leads, hyperscale data center procurement officers, and industrial automation system architects provided ongoing calibration against operating reality. Primary interview intelligence combined with secondary validation from SEC filings, foundry capex disclosures, BIS and DGFT regulatory notices, and customs trade data. Bottom-up triangulation across product type, technology node, end user segment, and application dimensions anchored volume estimates, while top-down cross-checks against foundry revenue disclosures and equipment vendor order books validated value projections.
Scenario-bracketing around EU Chips Act subsidy disbursement timelines, BIS export control expansion trajectories, and CoWoS capacity ramp schedules bounded the projection horizon. Segmentation modeling incorporated product type, technology tier, end user industry, and application workload dimensions alongside regional regulatory cluster effects. CAGRs derived from fitted growth curves against historical foundry utilization rates and equipment spending patterns. Forecast inputs included hyperscaler custom silicon program announcements, MIIT domestic procurement policy enforcement intensity, and NIST post-quantum cryptography standardization timelines.
Sensitivities concentrate around BIS classification expansions, Taiwan Strait logistics disruptions, and EU AI Act CE marking implementation delays that could compress or extend adoption curves. Forecasts reflect assumptions about continued foundry access for China-qualified design houses and stable advanced packaging substrate supply. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market